
 Veterinary Ultrasound Devices Market | 2026-2036
Veterinary Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Ultrasound Devices Market Analysis
High-resolution imaging standards is reorganizing competitive dynamics across the veterinary ultrasound landscape. GE Healthcare leverages its deep imaging heritage to sustain technology leadership in cart-based cardiology systems. Siemens Healthineers anchors its position through manufacturing scale and channel control across European veterinary hospitals. FUJIFILM Sonosite Inc. specializes in portable point-of-care designs that dominate mobile veterinary services and field deployments.
Veterinary ultrasound devices employ piezoelectric transducers operating at 2-15 MHz to generate real-time anatomical images for non-invasive diagnosis in animals. These systems process acoustic echoes through digital beamforming algorithms to visualize soft tissue structures, cardiac function, and fetal development across species. Portable devices command expanding share as clinics prioritize flexibility and reduced footprint, while cart-based systems retain margin concentration in academic and referral hospitals. Color Doppler technology leads technology adoption for hemodynamic assessment, whereas 3D imaging remains nascent with growth tied to reproductive specialty practices.
The FDA Center for Veterinary Medicine oversees device safety and performance claims for equipment marketed in the United States, while EU MDR requirements extend conformity assessment obligations for manufacturers serving European clinics. ISO 13485 quality management certification shapes supplier qualification processes for procurement teams at large hospital networks. Stakeholders must monitor evolving harmonization between human medical device standards and veterinary-specific pathways, as regulatory convergence will determine which manufacturers can sustain cross-market platform strategies without duplicative compliance investment.
Market Dynamics
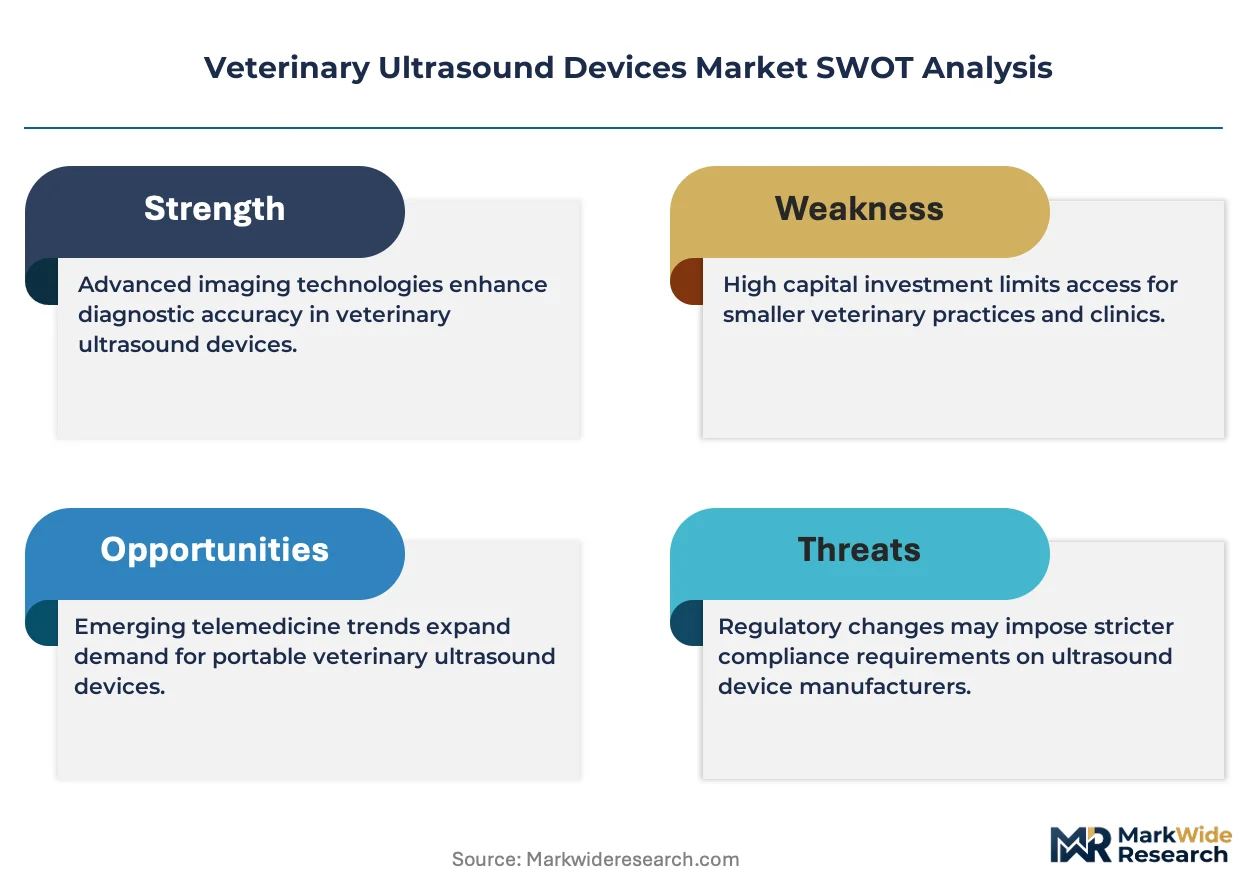
Point-of-care imaging capabilities are compressing diagnostic timelines across companion animal practices, forcing equipment vendors to reconcile portability demands with the performance thresholds demanded by cardiology and reproductive specialists.
Growth Catalysts
- EU MDR conformity pathways:Harmonized quality benchmarks accelerate cross-border equipment approvals, reducing time-to-market for manufacturers serving multiple European veterinary hospital networks.
- Mobile veterinary services:Field-deployable ultrasound platforms enable on-farm livestock assessments and home-visit companion animal diagnostics, expanding addressable service territory per practice.
- Pet insurance penetration:Reimbursement structures in the United States, Germany, and Japan lower out-of-pocket cost barriers for advanced imaging procedures, driving referral hospital capital expenditure.
Market Restraints
- Piezoelectric crystal supply concentration:Specialized transducer materials depend on concentrated rare earth processing capabilities, exposing manufacturers to input cost volatility and geographic supply disruption.
- FDA Center for Veterinary Medicine review timelines:Device safety and performance claim substantiation extends product launch schedules, compressing revenue recognition windows for new platform introductions.
- Computed tomography substitution:CT modalities capture orthopedic and oncological diagnostic volume in academic referral centers, constraining ultrasound addressable market expansion at the premium tier.
Strategic Opportunities
- Artificial intelligence convergence:Machine learning algorithms paired with real-time imaging enable automated cardiac measurement and lesion detection, reducing operator skill variance in general practice settings.
- Subscription-based equipment access:Hardware-as-a-service models lower upfront capital requirements for independent clinics, shifting revenue recognition toward recurring service and consumable streams.
- Reproductive specialty practices:3D imaging adoption concentrates in equine and bovine breeding operations, creating premium pricing power for manufacturers with dedicated transducer portfolios.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation for veterinary-specific production lines extends supplier qualification periods, delaying procurement approvals from large hospital networks.
- Sonographer training pipeline gaps:Veterinary-specific imaging education programs produce insufficient certified operators, constraining equipment utilization rates and customer satisfaction metrics.
- Legacy system integration complexity:PACS connectivity and electronic medical record interoperability requirements fragment IT procurement decisions, lengthening sales cycles for replacement equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Ultrasound Devices Market |
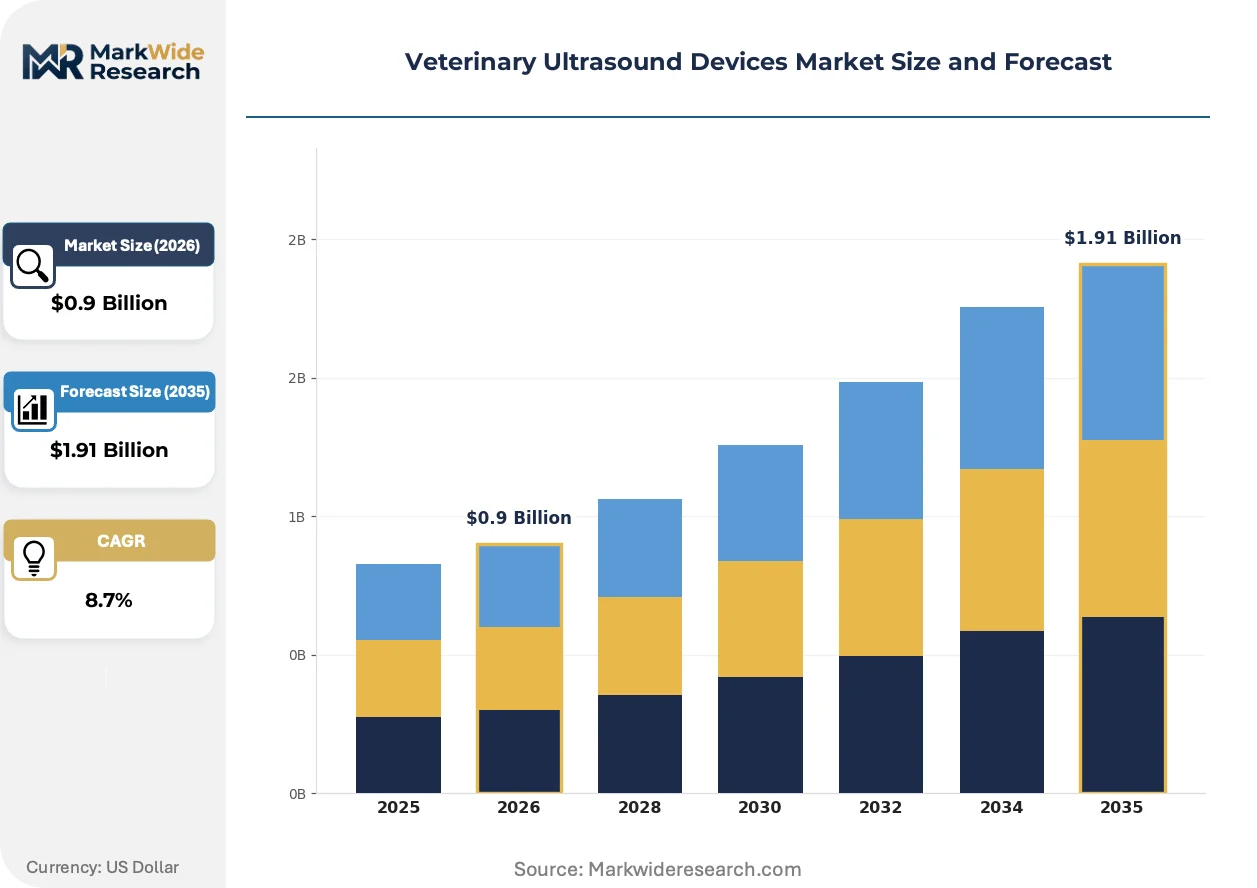
| Market Size in 2026 | $0.9 Billion |
| Market Size in 2035 | $1.91 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Standalone Systems, Cart-Based Systems, Software Solutions End User: Veterinary Clinics, Animal Hospitals, Research Institutions, Mobile Veterinary Services Technology: Pulsed Wave Doppler, Color Doppler, 2D Imaging, 3D Imaging Application: Cardiology, Obstetrics, Abdominal Imaging, Musculoskeletal Imaging |
| Companies Covered | Canon, FUJIFILM Sonosite Inc., GE Healthcare, Chison Medical Technologies Co., Ltd., IMV Imaging, Esaote SpA, Siemens Healthineers, SonoScape Medical Corp., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Ultrasound Devices Market Emerging Trajectories
Wireless transducer technology and cloud-native image archiving are dissolving the hardware boundaries between portable and cart-based system categories, forcing manufacturers to reconceptualize platform differentiation around software-enabled workflow rather than physical form factor alone.
Capacitive micromachined ultrasonic transducer (CMUT) arrays are fragmenting traditional piezoelectric transducer dominance in portable veterinary applications. Small animal emergency practices and mobile large-animal services adopt CMUT-enabled probes for their reduced power consumption and broader frequency tunability. The technology is fragmenting vendor competitive positions by enabling new entrants to bypass established transducer supply relationships and compete on semiconductor fabrication economics rather than crystal sourcing scale.
EU MDR technical documentation requirements for class IIa and IIb veterinary diagnostic equipment tighten post-market surveillance obligations, extending conformity assessment timelines for manufacturers without established notified body relationships. European veterinary hospital procurement teams now prioritize suppliers with existing MDR certificates, compressing competitive access for late-certifying vendors. German and French referral networks accelerate supplier consolidation around MDR-compliant portfolios, reducing vendor fragmentation in premium equipment segments.
After-sales service unbundling disrupts traditional capital equipment purchasing patterns across United States companion animal clinic chains. Large corporate practice groups negotiate direct maintenance contracts with third-party service providers, displacing manufacturer-captive service revenue streams. This pattern concentrates in multi-site veterinary platforms in California and Texas, where equipment fleet standardization enables independent service economies of scale.
Veterinary Ultrasound Devices Market Segmentation
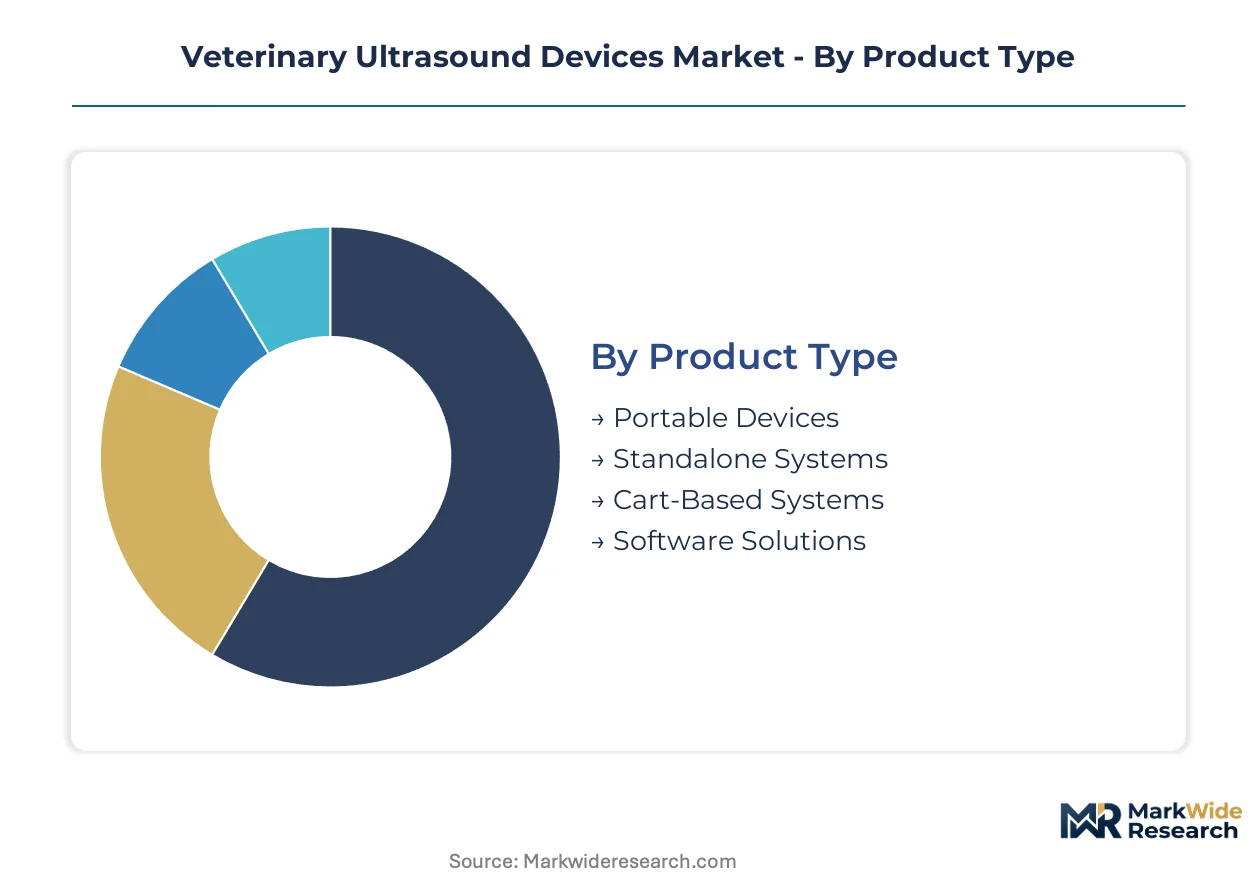
Veterinary ultrasound segmentation reflects the tension between portability demands and specialist-grade performance requirements. Equipment categories diverge sharply in pricing power, replacement cycles, and vulnerability to competing imaging modalities.
Product Type:
Portable devices face the strongest substitution pressure from handheld smartphone-connected probes, while cart-based platforms defend against CT and MRI encroachment through real-time functional assessment.
- Portable Devices:Battery-powered units with CMUT or piezoelectric transducers operate at 5-12 MHz for field diagnostics. Demand concentrates in mobile large-animal services across Texas and Australian cattle regions, where farm-gate assessment eliminates transport mortality risks.
- Cart-Based Systems:Full-platform configurations integrate color Doppler, elastography, and advanced measurement packages for cardiology and reproductive specialists. Academic veterinary hospitals in the United States, Germany, and Japan anchor procurement volume, driven by residency training requirements and research publication demands.
- Standalone Systems:Mid-tier console designs serve mixed-animal practices requiring cardiac and abdominal versatility without research-grade pricing.
- Software Solutions:AI-enabled measurement automation and cloud PACS integration address sonographer skill gaps in general practice settings.
Cart-based systems anchor the volume base while portable devices gain share at the steepest rate.
End User:
Customer concentration varies by capital intensity, with corporate clinic chains driving standardization and independent practices prioritizing financing flexibility.
- Animal Hospitals:Multi-specialty referral centers in California, Texas, and Florida deploy premium platforms for cardiology, oncology staging, and interventional guidance. Pet insurance reimbursement structures in these states support advanced imaging procedure volumes.
- Veterinary Clinics:General companion animal practices across the United States and Western Europe favor portable or compact systems for pregnancy confirmation and emergency triage. Equipment financing constraints limit penetration of Doppler-capable platforms.
- Mobile Veterinary Services:Equine reproductive specialists and livestock practitioners require weather-resistant, battery-independent operation for on-farm deployment.
- Research Institutions:Veterinary schools and pharmaceutical toxicology facilities drive demand for high-frequency micro-imaging and longitudinal study archiving capabilities.
Veterinary clinics dominate unit shipments while animal hospitals capture the majority of revenue concentration.
Technology:
Technology tiers separate by hemodynamic assessment capability, with Doppler modalities commanding premium pricing against basic grayscale imaging.
- Color Doppler:Velocity-encoded flow mapping enables cardiac valve assessment and vascular patency evaluation. Demand clusters in cardiology referral practices across the United States and Japan, where pet insurance covers echocardiographic screening protocols.
- 3D Imaging:Volume-rendered reconstruction supports equine fetal sexing and bovine twin diagnosis. Reproductive specialty practices in Kentucky, Ireland, and New Zealand generate concentrated procurement.
- Pulsed Wave Doppler:Spectral analysis quantifies flow velocities for pressure gradient calculations in congenital heart disease.
- 2D Imaging:Grayscale anatomical visualization serves pregnancy detection, effusion assessment, and mass characterization in cost-sensitive general practice.
Color Doppler anchors installed base value while 3D imaging expands most quickly in reproductive segments.
Application:
Clinical application segmentation tracks specialty board certification density and procedure reimbursement levels across regional veterinary markets.
- Cardiology:Echocardiographic assessment of congenital and acquired heart disease requires Doppler-capable platforms with measurement software. United States and Japanese markets lead penetration due to veterinary cardiologist density and pet insurance structures.
- Abdominal Imaging:Hepatic, splenic, and urinary tract evaluation represents the highest-frequency ultrasound application across general practice. Standardization of FAST protocols in emergency medicine drives portable device adoption.
- Obstetrics:Fetal viability assessment and dystocia planning concentrate in equine and small animal breeding operations.
- Musculoskeletal Imaging:Tendon and ligament evaluation serves equine sports medicine and canine orthopedic referral practices.
Abdominal imaging anchors procedure volume while cardiology commands the highest equipment pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in veterinary ultrasound equipment tilt toward deficit positions in markets with dense companion animal clinic networks, while manufacturing concentration in East Asia and Western Europe shapes cross-border equipment sourcing patterns.
United States
Corporate veterinary chains in California and Texas drive standardized fleet procurement across multi-site operations. FDA Center for Veterinary Medicine oversight of device safety claims extends product registration timelines for foreign manufacturers. The Research Triangle in North Carolina anchors veterinary school research demand for high-frequency imaging platforms.
Germany
Referral hospital networks in Bavaria and North Rhine-Westphalia sustain premium cart-based system procurement for cardiology specialization. EU MDR conformity assessment obligations filter supplier access to institutional procurement channels. The Munich-Stuttgart corridor concentrates distributor headquarters serving Central European veterinary markets.
Japan
Pet insurance reimbursement structures in Tokyo and Osaka metropolitan areas lower cost barriers for advanced echocardiography procedures. METI industrial standards for medical equipment create parallel certification pathways for veterinary device variants. The Kansai region hosts specialized transducer refurbishment facilities serving domestic manufacturers.
China
Domestic livestock operations in Shandong and Sichuan provinces generate field-deployable ultrasound demand for bovine reproductive services. NMPA medical device registration requirements extend to veterinary equipment marketed for food animal applications. Shenzhen's electronics manufacturing base supplies CMUT transducer components to regional equipment assemblers.
United Kingdom
Independent companion animal practices across Greater London and the Southeast favor portable systems for pregnancy confirmation services. The Veterinary Medicines Directorate aligns device safety reporting with EU MDR surveillance frameworks post-Brexit. Cambridge-Oxford research corridors drive demand for micro-imaging platforms in pharmaceutical toxicology studies.
Veterinary Ultrasound Devices Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and distribution reach dimensions. The vendor base separates into three tiers: diversified imaging conglomerates with veterinary divisions, dedicated veterinary equipment specialists, and emerging Asian manufacturers competing on semiconductor economics. Consolidation pressure concentrates in European markets where MDR compliance costs favor scaled players, while technology licensing agreements accelerate CMUT transducer adoption among mid-tier competitors.
Within the diversified imaging tier, GE Healthcare and Siemens Healthineers exemplify platform leverage strategies that span human and veterinary applications. FUJIFILM Sonosite Inc. occupies a distinct position among portable-focused specialists with point-of-care heritage. Chinese manufacturers including Shenzhen Mindray Bio-Medical Electronics Co., Ltd. and SonoScape Medical Corp. represent the scale-driven archetype competing on fabrication economics and regional distribution density.
| Leading Market Players |
|---|
| Canon |
| FUJIFILM Sonosite Inc. |
| GE Healthcare |
| Chison Medical Technologies Co., Ltd. |
| IMV Imaging |
| Esaote SpA |
| Siemens Healthineers |
| SonoScape Medical Corp. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for piezoelectric crystal procurement concentrate pricing power among transducer manufacturers with captive supply agreements in Japan and Germany, while CMUT semiconductor economics from Shenzhen fabs compress margins in portable device tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in veterinary ultrasound equipment. Premium cart-based systems command differentiation through FDA 510(k) clearance tier and ISO 13485 certification grade, while portable segments face cost compression from CMUT-enabled new entrants. Price erosion runs through mid-tier console designs as corporate clinic chains in Texas and California negotiate fleet-scale service unbundling. Independent companion animal practices in the United Kingdom exhibit highest price sensitivity due to equipment financing constraints, whereas Japanese referral hospitals with pet insurance reimbursement show lowest sensitivity to Doppler-capable platform premiums.
Supply Chain Analysis
Inventory buffers for specialized transducer materials rarely exceed sixty days across veterinary ultrasound manufacturers, exposing procurement to rare earth processing concentration in China and precision ceramic fabrication in Japan. Piezoelectric crystals, CMUT semiconductor wafers, and lithium-ion battery cells constitute critical input dependencies. Single-source vulnerability in lead zirconate titanate sourcing from Hunan province creates tariff exposure risk for European and North American assemblers. Distribution runs through authorized distributor networks anchored in the Munich-Stuttgart corridor for Central European veterinary hospitals, with direct manufacturer relationships dominating corporate chain procurement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary ultrasound equipment sits at an inflection where CMUT semiconductor fabrication and EU MDR regulatory harmonization simultaneously disrupt incumbent transducer economics and consolidate procurement access.
For Market Incumbents: Compound defensive positioning through backward integration into CMUT wafer supply and accelerated MDR certification timelines to lock European hospital procurement channels against emerging Asian competitors. Channel control in German referral networks and captive service contracts with California corporate chains represent critical margin defense levers as portable device pricing compresses. For New Entrants and Emerging Players: Lead with AI-enabled measurement automation targeting general companion animal practices in the United Kingdom and independent clinics in Texas where sonographer skill gaps constrain equipment utilization. SaaS-tiered pricing models lower capital barriers for these price-sensitive segments, creating white-space penetration before incumbents adapt software revenue architectures. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates with underperforming veterinary divisions facing MDR compliance cost pressures. Long-term viability hinges on software-enabled workflow differentiation rather than hardware scale. The signal to watch is AI algorithm FDA clearance velocity as an indicator of which platforms can reduce operator skill variance and capture general practice volume.| Strategic Initiative | Industry Significance |
|---|---|
| CMUT Transducer Platform Development | Semiconductor fabrication economics from Shenzhen fabs bypass traditional piezoelectric supply relationships. |
| EU MDR Certification Acceleration | Notified body relationships filter competitive access to German and French institutional procurement channels. |
| AI Measurement Software FDA Submission | Automated cardiac analysis reduces operator skill variance in general companion animal practices. |
| Hardware-as-a-Service Model Launch | Subscription revenue shifts capital burden from independent clinics toward recurring service streams. |
| Third-Party Service Network Partnership | Independent maintenance contracts align with corporate chain fleet standardization in California and Texas. |
Methodological Framework
The analysis maps portable devices, cart-based systems, and AI-enabled software solutions, each validated through biomedical engineers at academic veterinary hospitals, procurement managers at corporate clinic chains, distributor principals in Central Europe, and regulatory affairs specialists navigating FDA Center for Veterinary Medicine pathways. Secondary sources include FDA 510(k) device filings, EU MDR technical documentation databases, hospital procurement contract registries, and GPO equipment purchasing records. Bottom-up unit shipment estimates triangulate against top-down revenue benchmarks across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs throughout the forecast period. The analytical framework models equipment type, technology tier, end-user category, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from procedure volume elasticity to pet insurance penetration and replacement cycle compression from CMUT technology adoption. Forecast inputs incorporate veterinary cardiologist density by metropolitan area and corporate practice consolidation rates in the United States.
The analysis sits within stated boundaries; outcomes outside sustained pet insurance reimbursement expansion or severe rare earth supply disruption would require recalibration. Forecasts reflect documented assumptions about technology substitution timelines and regulatory harmonization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Vascular Screening Devices Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Non-Invasive Ventilators Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Gastric Bands Market
Medical Devices
Photopheresis Products Market