
 EEG Electrodes Market | 2026-2036
EEG Electrodes Market Size, Share, and Industry Trends Forecast 2026-2036
EEG Electrodes Market Analysis
Specialized neuroelectrode engineering talent is rotating toward dry-electrode and flexible substrate development, tightening labor pools for legacy wet-electrode manufacturing. Medtronic leverages its vertically integrated neuromodulation pipeline to sustain electrode supply security for implantable and surface applications. Ambu A/S dominates disposable EEG electrode production in Europe, while Nihon Kohden Corporation anchors Asia-Pacific distribution through its diagnostic equipment service networks. Natus Medical competes in the North American hospital channel with bundled neurodiagnostic system offerings.
EEG electrodes are conductive sensors that interface with the scalp to detect and transmit electrical activity generated by cortical neurons, typically employing silver-silver chloride compositions or sintered materials to achieve impedance values below five kilo-ohms for signal fidelity. Their primary purpose is to enable non-invasive brain monitoring for clinical diagnosis of seizure disorders, sleep dysfunction, and cognitive impairment. Disposable electrodes command the largest revenue share in the product type dimension due to infection control protocols in hospitals, while dry electrodes represent the fastest-expanding technology segment as researchers pursue rapid-deployment protocols for mobile brain-computer interface studies. The application landscape tilts toward clinical diagnostics, where reimbursement codes for extended EEG monitoring protect margin pools, whereas neuroscience research applications absorb volume through academic grant cycles.
The FDA enforces biocompatibility standards under ISO 10993 for skin-contact neural devices, while the EU Medical Device Regulation requires notified body certification for EEG electrodes marketed in Europe, elevating compliance costs for cross-border suppliers. The EPA regulates silver chloride waste streams from electrode manufacturing facilities in the United States, pushing producers toward closed-loop chemical recovery systems. Stakeholders must monitor how evolving FDA guidance on brain-computer interface accessories reshapes classification pathways for next-generation dry electrode arrays.
Market Dynamics
The EEG electrodes market is experiencing a fundamental restructuring as dry-electrode architectures displace traditional wet-electrode protocols across clinical and research environments. This technology pivot is compressing manufacturing margins for legacy suppliers while opening new competitive terrain for materials-science entrants.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter notified body certification requirements for neural interface devices are consolidating procurement toward ISO 13485-certified suppliers with established quality management systems.
- Epilepsy monitoring units:Tertiary hospitals in the United States are expanding long-term video-EEG capacity, driving recurring electrode consumption through standardized seizure monitoring protocols.
- Flexible polymer substrates:Advances in stretchable conductive inks are enabling conformal electrode arrays that maintain signal fidelity during patient movement, accelerating adoption in ambulatory diagnostics.
Market Restraints
- Silver chloride cost volatility:Fluctuating precious metal prices directly impact input costs for Ag/AgCl electrode production, squeezing margins for commodity-grade disposable manufacturers.
- European supply concentration:Notified body capacity bottlenecks in Germany and the Netherlands are extending MDR certification timelines, delaying market entry for new electrode designs.
- Signal impedance limitations:Dry electrodes without conductive gel struggle to achieve consistent impedance values below ten kilo-ohms across diverse scalp conditions, restricting clinical acceptance.
Strategic Opportunities
- Saudi Arabia healthcare infrastructure:The kingdom's neurotechnology investment initiatives under Vision 2030 are creating demand for diagnostic electrode systems in new specialty hospitals.
- Brain-computer interface accessories:FDA draft guidance on BCI device classification is clarifying regulatory pathways for dry electrode arrays intended for consumer neurotechnology applications.
- Closed-loop chemical recovery:EPA enforcement of silver waste regulations is incentivizing electrode manufacturers to develop in-house precious metal reclamation capabilities that reduce environmental liability.
Industry Challenges
- Biocompatibility testing expertise:ISO 10993-5 cytotoxicity assessment capabilities are scarce among contract research organizations serving neural device developers, extending validation timelines.
- Legacy system integration:Dry electrode arrays require modified amplifier interfaces and software calibration protocols, complicating deployment in hospital networks with entrenched diagnostic equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EEG Electrodes Market |
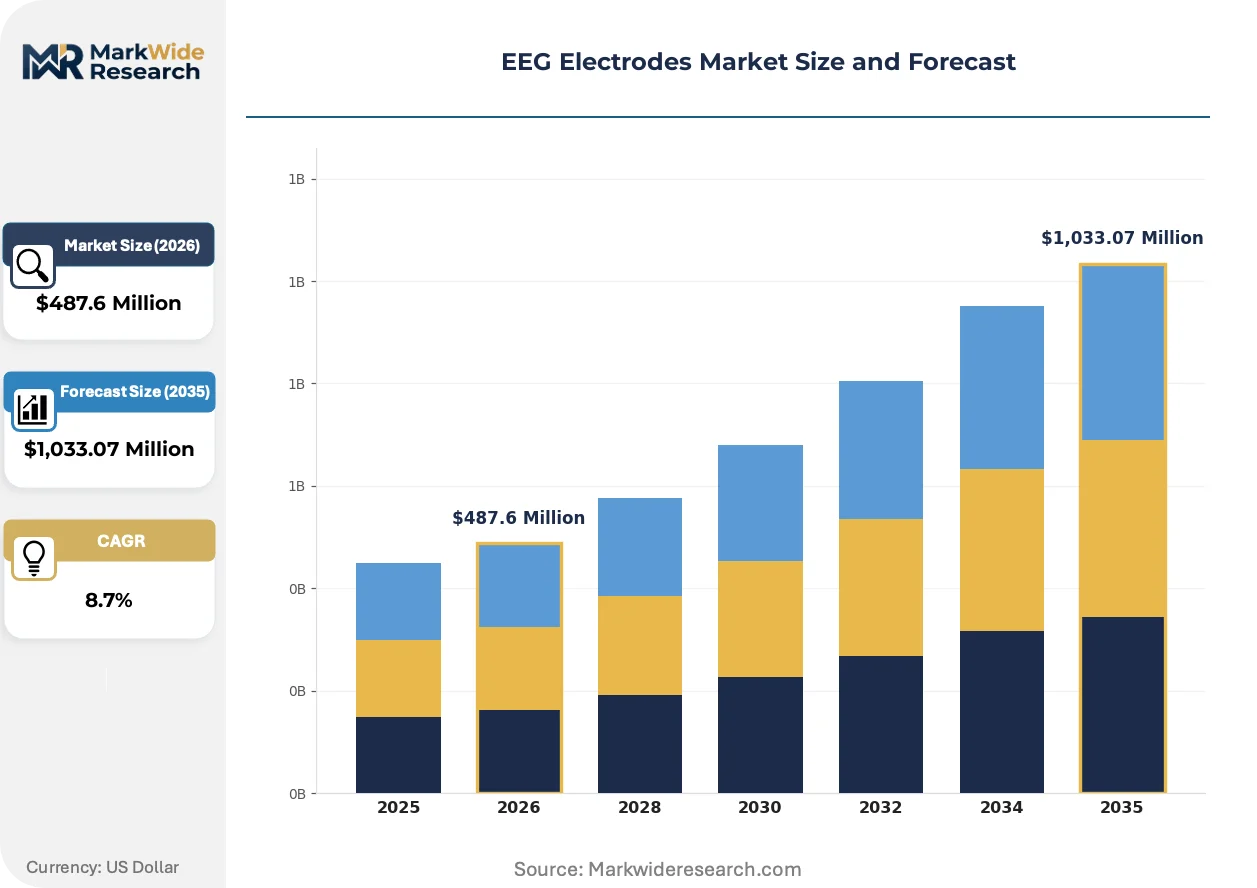
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Soft, Rigid Technology: Wet, Dry, Gel-Based, Fiber Optic Application: Clinical Diagnostics, Research Studies, Neuroscience, Cognitive Assessment End User: Hospitals, Research Institutions, Rehabilitation Centers, Academic Labs |
| Companies Covered | Medtronic, Ambu A/S, Natus Medical, Nihon Kohden Corporation, 3M, Koninklijke Philips, CONMED Corporation, Rhythmlink International, BIOPAC Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EEG Electrodes Market Emerging Trajectories
Materials innovation and regulatory clarification are converging to reshape competitive positioning across electrode architectures. Three developments are particularly consequential for supplier strategy and buyer procurement patterns.
Micro-needle electrode arrays fabricated from biocompatible polymers are fragmenting the traditional surface-electrode paradigm by penetrating the stratum corneum to achieve gel-free impedance matching. Academic medical centers in the United States are piloting these devices for rapid-deployment seizure monitoring, compressing the addressable market for conventional wet electrodes in emergency departments.
FDA's evolving guidance on brain-computer interface accessories is creating compliance clarity that accelerates product development cycles for dry electrode manufacturers. The agency's 2024 draft recommendations on non-invasive neural signal acquisition devices are prompting electrode designers to pre-submission pathways that reduce regulatory uncertainty. Consumer neurotechnology developers are responding by advancing dry-electrode form factors intended for wellness applications outside traditional clinical reimbursement channels.
Hospital procurement departments are consolidating electrode purchasing through bundled neurodiagnostic system contracts rather than standalone consumable agreements. This channel compression favors suppliers with integrated amplifier and software offerings, squeezing pure-play electrode manufacturers in the North American hospital channel. Academic research institutions remain the exception, maintaining direct electrode sourcing flexibility to support experimental protocols.
EEG Electrodes Market Segmentation
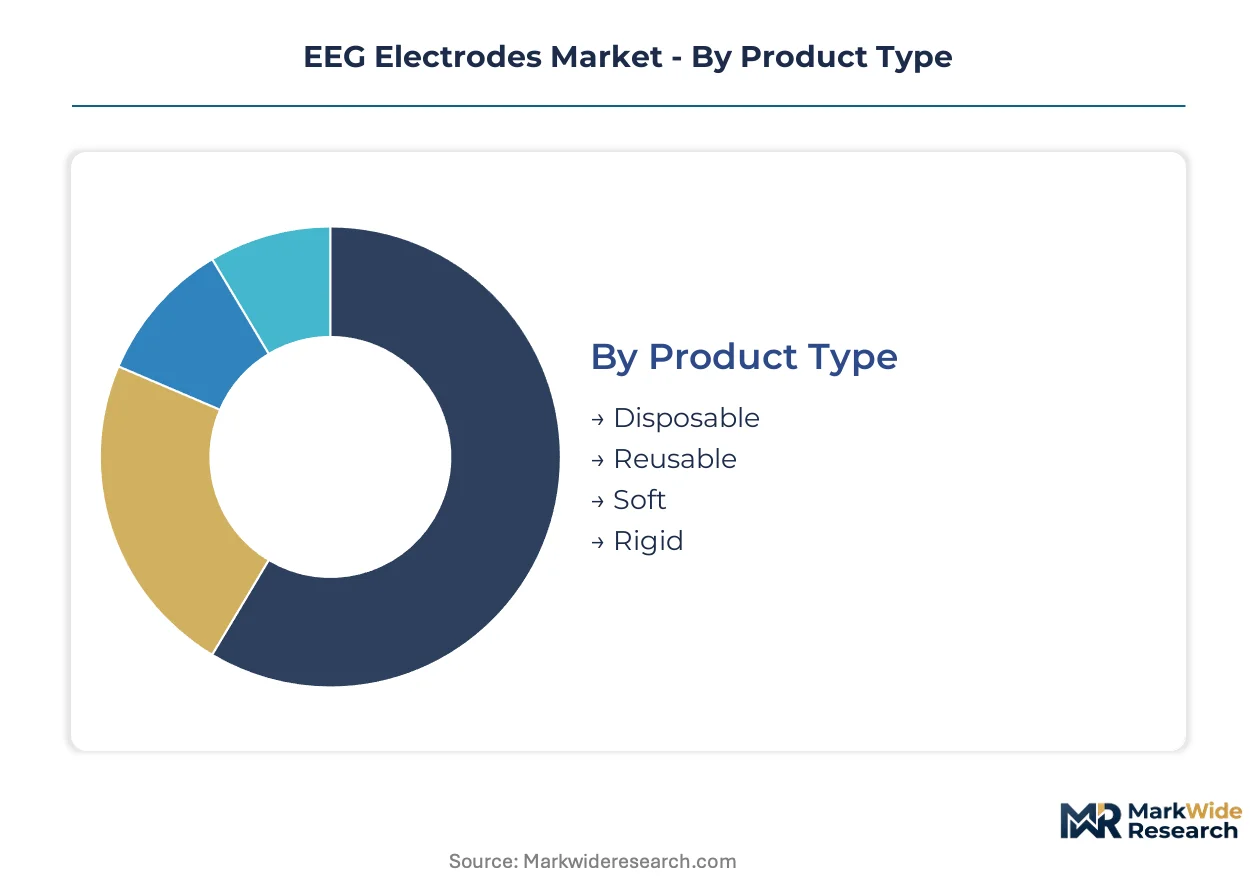
EEG electrode procurement patterns diverge sharply across product architectures and use environments. Hospital infection control protocols, research grant cycles, and regulatory compliance requirements each reshape demand concentration within segment boundaries.
Product Type:
Regulatory frameworks differentiate electrode categories through biocompatibility testing intensity and sterilization validation requirements.
- Disposable:Single-use Ag/AgCl electrodes eliminate cross-contamination risk in tertiary hospital epilepsy monitoring units. United States academic medical centers drive volume through standardized long-term video-EEG protocols that mandate fresh electrodes per patient encounter.
- Reusable:Sintered silver-silver chloride electrodes withstand repeated autoclave cycles for operating room intraoperative monitoring. Cost pressures in European hospital systems sustain demand despite higher upfront capital outlay and reprocessing labor.
- Soft:Polymer substrate electrodes conform to pediatric and neonatal scalp geometries.
- Rigid:Metal disk electrodes serve legacy amplifier systems in research laboratories.
Established volume favors Disposable; emerging adoption favors Soft.
Technology:
Signal fidelity requirements and deployment speed tradeoffs segment technology selection across clinical and research environments.
- Wet:Conductive gel electrodes achieve impedance below five kilo-ohms for diagnostic-grade signal quality. Sleep disorder clinics in Germany and the Netherlands specify wet-electrode protocols for polysomnography reimbursement compliance.
- Dry:Capacitive and active dry electrodes enable rapid-deployment brain-computer interface studies. Mobile neurotechnology developers in California and Massachusetts prioritize dry architectures for consumer wellness applications outside clinical reimbursement channels.
- Gel-Based:Semi-dry conductive pastes bridge impedance performance and application speed for ambulatory monitoring.
- Fiber Optic:Optically isolated electrodes eliminate electromagnetic interference in MRI-compatible neural recording.
Clinical reimbursement protects Wet-electrode margin pools; research grant funding accelerates Dry-electrode expansion.
Application:
End-use reimbursement structures and publication incentives reshape electrode specification and procurement volume.
- Clinical Diagnostics:Extended EEG monitoring for seizure disorders commands the largest revenue concentration. United States CPT reimbursement codes for long-term video-EEG protect consumable electrode margins in hospital neurophysiology departments.
- Neuroscience:High-density array studies for brain-computer interface development absorb volume through NIH and NSF grant cycles. Massachusetts Institute of Technology and Stanford University research facilities specify custom electrode configurations for invasive and non-invasive neural recording protocols.
- Research Studies:Academic grant-funded protocols prioritize cost efficiency and experimental flexibility.
- Cognitive Assessment:Pharmaceutical clinical trials and sports concussion monitoring drive standardized electrode procurement.
Revenue concentration clusters in Clinical Diagnostics; steepest expansion trajectory appears in Neuroscience.
End User:
Procurement authority and technical specification control vary sharply across institutional buyer types.
- Hospitals:Centralized purchasing departments consolidate electrode procurement through bundled neurodiagnostic system contracts. Natus Medical and Nihon Kohden equipment service agreements in United States health systems specify captive electrode supply arrangements.
- Research Institutions:Principal investigators retain direct sourcing authority for experimental electrode configurations. Howard Hughes Medical Institute and Allen Institute facilities maintain flexible procurement for prototype dry-electrode and micro-needle array evaluation.
- Rehabilitation Centers:Outpatient neurofeedback and stroke recovery programs prioritize patient comfort and rapid application.
- Academic Labs:Graduate student and postdoctoral researchers source electrodes through university procurement systems with limited technical specification input.
Contract consolidation favors Hospitals; experimental flexibility favors Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biocompatibility enforcement under ISO 10993 anchors United States procurement patterns, while EU MDR certification bottlenecks reshape European supplier consolidation. Academic medical centers and tertiary hospital networks across five major economies are driving electrode specification divergence.
United States
Epilepsy monitoring units at Cleveland Clinic and Mayo Clinic are expanding long-term video-EEG capacity, driving recurring disposable electrode consumption. FDA draft guidance on brain-computer interface accessories is clarifying regulatory pathways for dry-electrode developers. Boston and San Francisco Bay Area neurotechnology clusters are piloting flexible polymer substrate arrays for ambulatory diagnostics.
Germany
Sleep disorder clinics in Berlin and Munich specify wet-electrode protocols for polysomnography reimbursement compliance under statutory health insurance. ECHA REACH regulations govern silver chloride chemical handling in electrode manufacturing facilities. The Baden-Württemberg medical technology corridor hosts precision fabrication operations serving European diagnostic equipment OEMs.
Japan
PMDA quality management requirements for neural interface devices sustain demand for high-reliability reusable electrodes in university hospital networks. METI funding for neurotechnology R&D is accelerating dry-electrode prototyping at Osaka and Tokyo research institutes. The Kansai region maintains concentrated electrode supply relationships with domestic diagnostic equipment manufacturers.
China
NMPA Class II medical device registration is tightening for imported EEG electrodes, favoring domestic manufacturers with established quality management systems. The Yangtze River Delta neurotechnology cluster in Shanghai and Suzhou is scaling flexible substrate electrode production for research applications. SAMR standardization initiatives are converging with international ISO 10993 biocompatibility frameworks.
Saudi Arabia
Vision 2030 healthcare infrastructure investments are creating demand for diagnostic electrode systems in new King Faisal Specialist Hospital neurotechnology facilities. SFDA medical device registration requirements are aligning with international quality standards for neural interface products. Riyadh and Jeddah academic medical centers are building dedicated neurophysiology departments with extended EEG monitoring capabilities.
EEG Electrodes Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the EEG electrodes market, with hospital procurement consolidation favoring suppliers with bundled neurodiagnostic system offerings. The competitive terrain fragments across disposable commodity manufacturing, reusable precision fabrication, and emerging dry-electrode materials science. Three archetypes dominate: vertically integrated neuromodulation conglomerates, European disposable specialists with ISO 13485-certified quality systems, and Asia-Pacific diagnostic equipment OEMs with captive electrode supply arrangements. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and backward integration into conductive material supply chains.
Among vertically integrated neuromodulation leaders, Medtronic exemplifies the conglomerate archetype with supply security spanning implantable and surface applications. Ambu A/S represents the European disposable specialist tier with notified body-certified production serving hospital infection control protocols. Nihon Kohden Corporation anchors the Asia-Pacific diagnostic equipment OEM category through service network integration.
| Leading Market Players |
|---|
| Medtronic |
| Ambu A/S |
| Natus Medical |
| Nihon Kohden Corporation |
| 3M |
| Koninklijke Philips |
| CONMED Corporation |
| Rhythmlink International |
| BIOPAC Systems |
| Others |
Supply Flow & Price Mechanics
Dry-electrode substitution for traditional wet-electrode architectures is simultaneously shifting supply geography toward polymer substrate fabrication clusters in Massachusetts and California while compressing pricing economics for legacy silver-silver chloride electrode manufacturers. This materials pivot fragments established procurement patterns as buyers renegotiate contracts around signal fidelity guarantees rather than precious metal content.
Pricing Analysis
Price spreads between German-engineered reusable electrodes and Asian-manufactured disposable alternatives run three to four times at equivalent channel tiers, reflecting ISO 13485 certification premiums and autoclave durability guarantees. Three-tier pricing structure across premium certified, standard clinical-grade, and economy unbranded levels dominates hospital procurement, with FDA 510(k) clearance status and biocompatibility test documentation serving as the primary differentiation drivers. Pricing pressure stems from silver chloride commodity volatility squeezing Ag/AgCl disposable margins, while research institutions exhibit the sharpest price sensitivity due to grant-funded budget constraints.
Supply Chain Analysis
Silver mining concentration in Peru and Mexico creates raw material chokepoints that propagate through electrode manufacturing supply chains, with smelter capacity limitations periodically constraining Ag/AgCl precursor availability. Production draws from precision fabrication facilities in Germany, high-volume molding operations in China, and polymer substrate printing clusters in the United States. Single-source vulnerability around sintered silver-silver chloride disk suppliers exposes reusable electrode manufacturers to disruption. Distribution runs through diagnostic equipment OEM service networks, GPO contracts, and direct academic sourcing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EEG electrodes market functions as a service-attach opportunity where electrode consumable contracts, calibration maintenance subscriptions, and neurodiagnostic software licensing expand faster than standalone hardware revenue. Recurring revenue layers now command strategic priority in supplier valuations.
For Market Incumbents: Fortify captive supply arrangements with tertiary hospital networks through bundled amplifier-electrode-service contracts that lock out pure-play electrode competitors. Deepen backward integration into conductive polymer formulation to offset silver chloride cost volatility and secure dry-electrode substrate supply. The FDA's evolving BCI accessory guidance threatens to reclassify next-generation electrode arrays, demanding proactive regulatory affairs investment. For New Entrants and Emerging Players: Lead with micro-needle electrode arrays for emergency department rapid-deployment seizure monitoring, where clinical validation gaps and wet-electrode application delays create immediate white-space. Target Saudi Arabia's Vision 2030 neurotechnology infrastructure buildout before established suppliers consolidate King Faisal Specialist Hospital procurement relationships. Pursue direct research institution partnerships that bypass GPO contract consolidation. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors materials-science specialists with dry-electrode intellectual property over legacy wet-electrode manufacturers facing margin compression. Long-term viability across the projection horizon hinges on regulatory pathway clarity for BCI-adjacent applications. Watch FDA draft guidance finalization as the critical inflection signal for consumer neurotechnology market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-5 Cytotoxicity Certification Investment | Biocompatibility testing capabilities are scarce among contract research organizations serving neural device developers. |
| Closed-Loop Silver Recovery System Deployment | EPA enforcement of precious metal waste regulations incentivizes in-house reclamation to reduce environmental liability exposure. |
| Flexible Polymer Substrate R&D Partnership | Stretchable conductive ink advances enable conformal arrays maintaining signal fidelity during patient movement. |
| Hospital System Bundled Contract Negotiation | Procurement consolidation through neurodiagnostic system agreements squeezes pure-play electrode manufacturers. |
| Saudi Arabia Distribution Infrastructure Buildout | Vision 2030 specialty hospital investments create first-mover advantage for diagnostic electrode system suppliers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neurophysiology department heads, hospital purchasing committee members, biomedical equipment service managers, and conductive materials procurement leads. Secondary validation drew from FDA 510(k) device filings, EPA enforcement action records, EU MDR notified body certification databases, and hospital GPO contract repositories. Bottom-up electrode volume estimates triangulated against top-down diagnostic equipment installed base calculations.
Across the analysis window, the forecast framework modeled product type segmentation, technology architecture migration curves, application reimbursement code protection levels, and end-user procurement authority structures. CAGRs were derived from elasticity-adjusted demand projections and replacement cycle analysis. Dry-electrode adoption velocity in brain-computer interface research and silver chloride commodity price trajectories served as key sensitivity inputs.
Forecasts assume regulatory continuity in FDA biocompatibility enforcement and EU MDR certification requirements; material policy shifts would require re-modeling. Specific risk factors include notified body capacity bottlenecks extending European market entry timelines and PMDA quality management requirement evolution affecting Japanese hospital procurement. Practitioners should keep alternative scenarios live as BCI accessory classification guidance and precious metal supply conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ovulation Microscope Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Tubeless Insulin Pump Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Transcranial Doppler Devices Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Pulmonology Devices Market