
 ECG Sensor Patch Market | 2026-2036
ECG Sensor Patch Market Size, Share, and Industry Trends Forecast 2026-2036
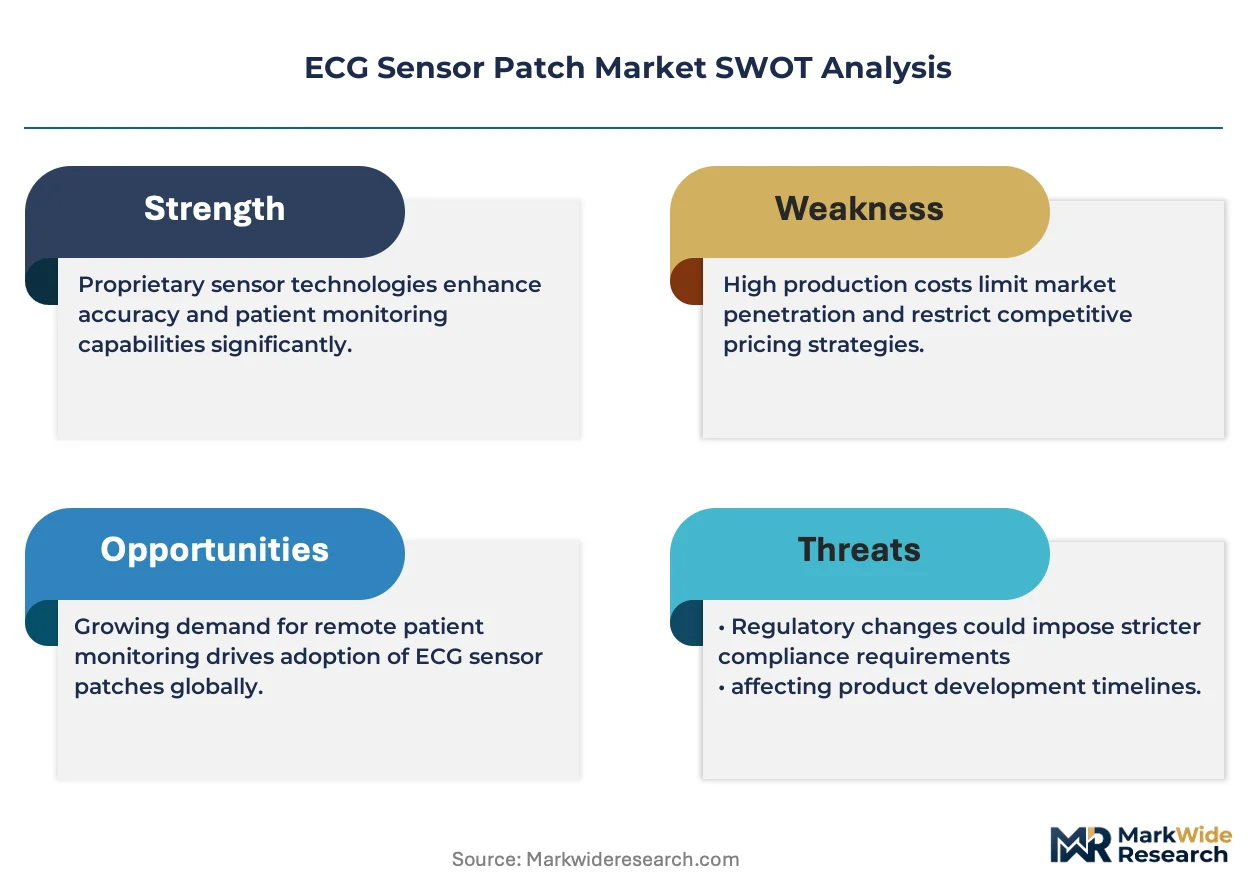
ECG Sensor Patch Market Analysis
Flexible printed circuit miniaturization is tilting ECG sensor patch architecture toward ultra-thin conformable substrates that integrate directly with skin topology. Medtronic leverages its cardiac rhythm management infrastructure to anchor institutional procurement contracts across North American health systems. iRhythm Technologies specializes in algorithm-driven diagnostic workflows that differentiate its patch-to-report pipeline from conventional Holter services. AliveCor competes through direct-to-consumer channel control, extending its mobile ECG brand into prescription-grade patch monitoring.
An ECG sensor patch is a disposable or limited-use electrophysiological recording device comprising biocompatible electrodes, signal amplification circuitry, and wireless transmission modules, typically measuring 50-100 micrometers in thickness and sampling cardiac electrical activity at 250-1000 Hz for ambulatory or remote diagnostic purposes. The wireless patch category dominates hospital procurement due to elimination of tethered leads that restrict patient mobility during multi-day monitoring protocols. Electrical sensing technology occupies the largest installed base, though hybrid sensing architectures combining capacitive and optical modalities are gaining traction in fitness tracking segments where motion artifact rejection determines user retention.
FDA 510(k) clearance timelines and EU MDR technical documentation requirements shape product development roadmaps, with Class IIa designation mandating clinical performance studies that extend regulatory validation cycles by twelve to eighteen months. The Federal Communications Commission governs radiofrequency transmission protocols for patches operating in unlicensed spectrum bands, creating compliance complexity for manufacturers pursuing simultaneous US and European market entry. Stakeholders must monitor evolving reimbursement codes for remote cardiac monitoring, as CMS national coverage determinations and parallel German G-BA benefit assessments will dictate whether patch-based diagnostics achieve sustainable procedure economics outside cash-pay wellness applications.
Market Dynamics
Wireless telemetry integration is collapsing the distinction between acute hospital monitoring and ambulatory diagnostic workflows, forcing infrastructure consolidation across cardiac care delivery networks.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways compress validation timelines for novel arrhythmia detection algorithms, attracting venture funding toward patch-based electrophysiology platforms.
- Ambulatory Surgical Center Expansion:Cardiology departments in outpatient surgical facilities are deploying patch-based monitoring to reduce same-day surgery cancellation rates linked to undetected cardiac anomalies.
- Cloud-Integrated Telemetry:Hospital procurement consortia in Germany's Rhine-Ruhr corridor mandate wireless patch platforms with real-time data streaming, standardizing interoperability requirements across integrated delivery networks.
Market Restraints
- Silver Nanowire Electrode Costs:Conductive ink formulations for skin-conformable electrodes face price volatility tied to precious metal commodity markets, compressing gross margins on disposable patch units.
- EU MDR Class IIa Certification Burden:Clinical performance study mandates extend regulatory validation cycles by twelve to eighteen months, freezing working capital in pre-market documentation.
- Conventional Holter Monitor Substitution:Established cardiac diagnostic service providers leverage existing reimbursement codes and physician familiarity to delay patch technology conversion.
Strategic Opportunities
- Post-Acute Care Transition Monitoring:Skilled nursing facilities in the United States represent an underpenetrated channel where patch-based telemetry can reduce thirty-day heart failure readmission penalties.
- Hybrid Sensing Convergence:Integration of capacitive electrical sensing with photoplethysmography creates artifact-resistant architectures for fitness-tracking applications outside clinical settings.
- Remote Patient Monitoring Reimbursement:CMS national coverage determinations expanding CPT code eligibility for patch-based diagnostics unlocks sustainable procedure economics beyond cash-pay wellness segments.
Industry Challenges
- Biomedical Signal Processing Talent Scarcity:Algorithm development for motion artifact rejection requires specialized expertise in adaptive filtering and machine learning, constraining R&D velocity at mid-tier manufacturers.
- Legacy EHR Integration Complexity:Patch platforms must achieve seamless data exchange with entrenched electronic health record systems from Epic and Cerner, extending implementation timelines and technical support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ECG Sensor Patch Market |
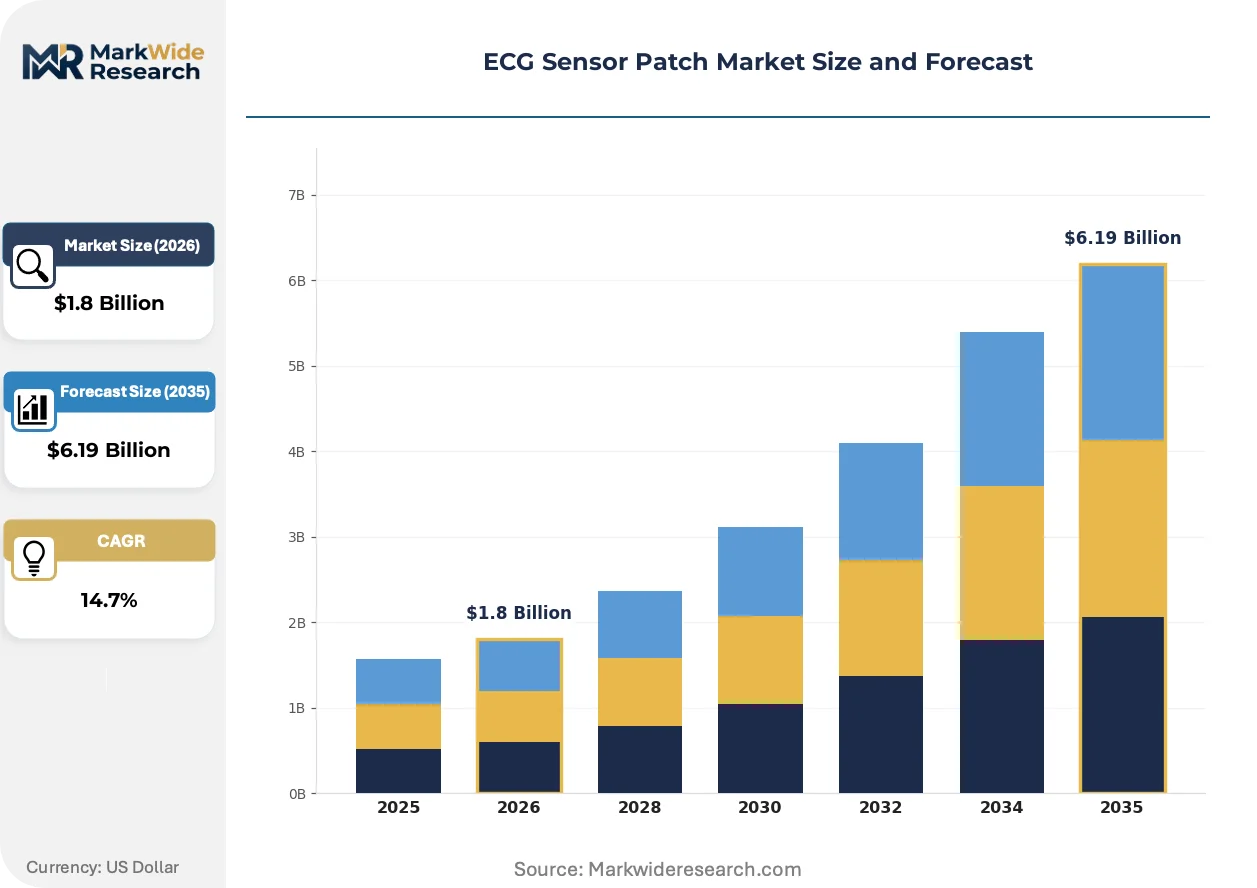
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.19 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Patch, Adhesive Patch, Implantable Patch, Wearable Patch Technology: Optical Sensing, Electrical Sensing, Capacitive Sensing, Hybrid Sensing Application: Remote Monitoring, Diagnosis, Fitness Tracking, Holter Monitoring End User: Patients, Healthcare Providers, Research Institutions, Home Care |
| Companies Covered | AliveCor, Cardiac Insight, Medtronic, LifeSignals, VitalConnect, Hill-Rom Holdings, Vivalk, Bardy Diagnostics, iRhythm Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ECG Sensor Patch Market Emerging Trajectories
Flexible electronics manufacturing is dissolving the hardware boundaries between diagnostic-grade medical devices and consumer wellness wearables, creating overlapping competency requirements across previously siloed supply chains.
Ultra-thin conformable substrates measuring 50-100 micrometers are collapsing the form-factor gap between adhesive skin patches and integrated circuit assemblies. Medtronic and iRhythm Technologies are transitioning production toward roll-to-roll printed electronics processes that eliminate wire-bonding steps. This manufacturing shift is collapsing capital requirements for entering prescription-grade cardiac monitoring, enabling mid-tier contract manufacturers to compete on electrode precision and signal fidelity.
EU MDR technical documentation requirements are mandating clinical performance studies that reshape competitive positioning around evidence generation capabilities. Class IIa designation forces manufacturers to maintain post-market surveillance systems capturing real-world safety data. Cardiac rhythm management divisions with established electrophysiology research infrastructure capture disproportionate certification velocity, while newcomers face eighteen-month documentation freezes.
Hospital procurement consortia are consolidating vendor relationships around platforms offering cloud-integrated telemetry with direct EHR connectivity. Integrated delivery networks in Germany's hospital procurement clusters now require wireless patch systems with API-standardized data exchange, displacing standalone Holter services that rely on manual report transmission. This specification tightening favors manufacturers with institutional IT integration expertise over pure hardware specialists.
ECG Sensor Patch Market Segmentation
ECG sensor patch segmentation reveals divergent replacement cycles across product architectures, with disposable adhesive formats turning over in days while implantable platforms sustain multi-year service intervals. Technology choices determine signal fidelity thresholds that separate prescription-grade diagnostics from consumer wellness applications. End-user concentration in institutional procurement channels versus direct-to-patient distribution creates fundamentally different margin structures and regulatory compliance burdens.
Product Type:
Replacement velocity spans three orders of magnitude across this category, from single-use disposables to multi-year implantables, dictating working capital intensity and service revenue mix.
- Wireless Patch:Eliminates tethered leads through integrated Bluetooth or proprietary RF transmission modules sampling at 250-1000 Hz. Hospital procurement consortia in Germany's Rhine-Ruhr corridor mandate this architecture for cloud-integrated telemetry, though FCC unlicensed spectrum compliance adds regulatory complexity for simultaneous US market entry.
- Adhesive Patch:Single-use disposable format employing biocompatible hydrogel electrodes on flexible substrates measuring 50-100 micrometers thick. Ambulatory surgical centers favor this segment for same-day surgery cardiac screening programs where device turnover matches procedure volume.
- Implantable Patch:Subcutaneous placement with extended battery life for continuous multi-year monitoring. Requires FDA Class III PMA pathway or EU MDR Class III certification with mandatory clinical trials.
- Wearable Patch:Reusable format with detachable electronics and replaceable adhesive layers. Targets fitness tracking segments where consumer price sensitivity constrains bill-of-materials costs.
Wireless patch dominates installed base. Adhesive patch is where expansion concentrates.
Technology:
Cost tier stratification separates high-fidelity electrical modalities from emerging hybrid architectures that trade absolute precision for motion artifact resilience.
- Electrical Sensing:Direct skin-contact electrodes measuring microvolt-level cardiac depolarization signals with established clinical validation. Occupies the largest installed base due to physician familiarity and existing reimbursement code alignment.
- Hybrid Sensing:Combines capacitive electrical detection with photoplethysmography optical modules for artifact-resistant signal reconstruction. Fitness tracking applications outside clinical settings favor this architecture where user retention depends on motion-tolerant performance.
- Optical Sensing:Photoplethysmography-based detection using LED-photodiode pairs without direct electrical skin contact. Enables waterproof designs but sacrifices diagnostic-grade ST-segment resolution.
- Capacitive Sensing:Non-contact electrodes measuring displacement currents through insulating layers. Emerging in ultra-thin conformable substrates where direct skin adhesion compromises comfort.
Electrical sensing commands premium pricing. Hybrid sensing is climbing the fastest.
Application:
Volume concentration in diagnostic workflows contrasts with fitness tracking's mass-market scale, creating divergent customer acquisition economics.
- Remote Monitoring:Continuous cardiac telemetry outside acute care settings with real-time clinician alerts. CMS national coverage determinations and German G-BA benefit assessments dictate sustainable procedure economics.
- Diagnosis:Extended ambulatory recording for arrhythmia detection, typically 7-14 day wear periods. FDA breakthrough device designation accelerates algorithm validation for novel detection capabilities.
- Fitness Tracking:Consumer wellness applications with heart rate variability and recovery metrics. Competes with smartwatch optical sensors on convenience and price.
- Holter Monitoring:Legacy 24-48 hour recording format facing substitution pressure from extended-wear patch platforms. Established cardiac diagnostic service providers defend through existing physician relationships and reimbursement codes.
Remote monitoring drives revenue concentration. Fitness tracking represents the steepest expansion trajectory.
End User:
Customer type determines regulatory pathway, pricing power, and technical support infrastructure requirements across the value chain.
- Healthcare Providers:Hospitals, cardiology clinics, and ambulatory surgical centers with institutional procurement processes. Epic and Cerner EHR integration mandates extend implementation timelines and technical support costs.
- Home Care:Skilled nursing facilities and post-acute transition programs where patch-based telemetry reduces heart failure readmission penalties. Underpenetrated channel with concentrated US geographic opportunity.
- Patients:Direct-to-consumer or prescription-fulfillment channels requiring simplified onboarding and patient education infrastructure.
- Research Institutions:Academic electrophysiology studies and clinical trial sponsors with specialized data format and protocol customization requirements.
Healthcare providers dominate procurement volume. Home care is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia concentrate purchasing power in Germany's Rhine-Ruhr corridor, while ambulatory surgical centers in the United States drive volume through patch-based cardiac screening programs. Regulatory velocity varies sharply across jurisdictions, with FDA breakthrough pathways compressing validation timelines against EU MDR documentation burdens.
United States
Ambulatory surgical centers deploy patch-based monitoring to reduce same-day surgery cancellations from undetected cardiac anomalies. FDA breakthrough device designation accelerates algorithm validation for novel arrhythmia detection platforms. The Federal Communications Commission governs unlicensed spectrum transmission protocols, creating compliance complexity for manufacturers pursuing simultaneous European market entry.
Germany
Hospital procurement consortia in the Rhine-Ruhr medtech corridor mandate wireless patch platforms with cloud-integrated telemetry and API-standardized data exchange. EU MDR Class IIa certification requirements extend regulatory validation cycles by twelve to eighteen months, freezing working capital in pre-market documentation. Integrated delivery networks in North Rhine-Westphalia displace standalone Holter services through vendor consolidation.
United Kingdom
NHS long-term plan targets for cardiovascular disease prevention drive demand for extended-wear ambulatory monitoring outside acute hospital settings. MHRA post-Brexit regulatory divergence from EU MDR creates parallel certification pathways that fragment market access timelines. London and Cambridge medtech clusters attract venture funding toward algorithm-driven diagnostic workflows.
Japan
Aging demographics and rural physician shortages expand remote cardiac telemetry reimbursement under Ministry of Health, Labour and Welfare guidelines. PMDA streamlined review pathways for software-as-medical-device products accelerate patch-to-report pipeline commercialization. Tokyo and Osaka metropolitan hospitals lead adoption of ultra-thin conformable substrates for patient comfort during multi-day monitoring.
India
Private hospital chains in Maharashtra and Karnataka import wireless patch platforms for premium cardiac diagnostic services targeting medical tourism segments. CDSCO medical device rules mandate local clinical trials for Class C and D products, extending market entry timelines for foreign manufacturers. Hyderabad's medical technology corridor hosts contract manufacturers developing low-cost adhesive patch formats for price-sensitive domestic markets.
ECG Sensor Patch Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. The vendor base organizes around three strategic archetypes: cardiac rhythm management divisions leveraging institutional procurement infrastructure, algorithm-native diagnostics companies differentiating through software-to-service workflows, and direct-to-consumer platforms capturing prescription fulfillment through mobile-first brand equity. Dominant competitive moves include backward integration into flexible printed circuit manufacturing and strategic partnerships with electronic health record platforms for seamless data exchange.
Within the cardiac rhythm management tier, Medtronic anchors institutional procurement contracts across North American health systems. iRhythm Technologies exemplifies the algorithm-native archetype through its patch-to-report diagnostic pipeline. AliveCor occupies a position bridging direct-to-consumer channel control with prescription-grade monitoring extension from its mobile ECG brand. These three companies represent divergent competitive vectors: hardware-integrated service bundling, software-driven workflow automation, and consumer-brand prescription conversion.
| Leading Market Players |
|---|
| AliveCor |
| Cardiac Insight |
| Medtronic |
| LifeSignals |
| VitalConnect |
| Hill-Rom Holdings |
| Vivalk |
| Bardy Diagnostics |
| iRhythm Technologies |
| Others |
Supply Flow & Price Mechanics
Rhine-Ruhr corridor freight networks impose cost premiums on silver nanowire electrode shipments from East Asian refineries, compressing gross margins for disposable patch manufacturers while enabling German hospital procurement consortia to extract volume-based price concessions from cloud-integrated telemetry platforms.
Pricing Analysis
Cost-plus contracts with London Metal Exchange silver indexation dominate raw material procurement for skin-conformable electrodes. Three-tier pricing structure across premium diagnostic-grade, standard clinical, and economy wellness tiers separates FDA 510(k) cleared platforms from CE-marked equivalents and unregulated consumer formats. Pricing pressure stems from precious metal commodity volatility, with adhesive patch margins tightening fastest among single-use disposables. Ambulatory surgical centers exhibit highest price sensitivity due to procedure-volume procurement, while integrated delivery networks prioritize interoperability premiums over unit economics.
Supply Chain Analysis
Export control restrictions on semiconductor lithography equipment constrain flexible printed circuit manufacturing capacity expansion in China, limiting substrate supply growth. Production concentrates in Taiwan, South Korea, and Germany for microelectromechanical components, with biocompatible hydrogel electrodes sourcing from Japanese chemical specialists. Silver nanowire conductive inks and Bluetooth Low Energy modules constitute critical dependencies. Single-source vulnerability pervades roll-to-roll printed electronics equipment. Distribution runs through hospital procurement consortia and GPO contracts in institutional channels, with direct-to-consumer platforms bypassing traditional medical device distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as Epic and Cerner EHR interoperability becomes the primary procurement filter, collapsing vendor selection around data exchange capabilities rather than hardware specifications alone.
For Market Incumbents: Entrench institutional procurement relationships through captive supply of flexible printed circuit substrates and accelerated FDA breakthrough device designation pursuit. Defend against algorithm-native diagnostics competitors by embedding patch-to-report workflows directly into hospital IT infrastructure. Prioritize backward integration into roll-to-roll manufacturing to neutralize contract manufacturer cost advantages. For New Entrants and Emerging Players: Establish a beachhead in skilled nursing facility post-acute transition monitoring, where CMS readmission penalty economics create urgent demand without entrenched vendor relationships. Target hybrid sensing architectures for fitness tracking applications outside clinical reimbursement complexity. Pursue direct-to-consumer channel control through mobile-first onboarding infrastructure. For Investors and Strategic Acquirers: Algorithm-native diagnostics companies with FDA-cleared arrhythmia detection pipelines represent the most defensible acquisition archetype against cardiac rhythm management division consolidation. Long-term viability hinges on sustainable remote patient monitoring reimbursement expansion beyond cash-pay wellness segments. Watch CMS national coverage determinations for CPT code eligibility as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates algorithm validation timelines for novel arrhythmia detection capabilities. |
| Cloud-Integrated Telemetry Platform | Meets German hospital procurement consortia mandates for API-standardized data exchange. |
| Flexible Printed Circuit Backward Integration | Captures electrode precision margins and eliminates wire-bonding capital requirements. |
| Post-Acute Care Channel Partnership | Unlocks skilled nursing facility demand for heart failure readmission penalty reduction. |
| Hybrid Sensing Architecture Development | Enables motion artifact-resistant fitness tracking outside clinical reimbursement constraints. |
Methodological Framework
The analysis maps wireless patch, adhesive patch, implantable patch, and wearable patch sub-sectors, each validated through electrophysiologists, hospital purchasing committee directors, biomedical signal processing engineers, and GPO contracts managers. Primary interview intelligence combines with secondary validation from FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS national coverage determination records, and hospital procurement consortium RFP documents. Bottom-up unit economics triangulate against top-down cardiac rhythm management division revenue segmentation.
Assumptions held fixed include current FDA and EU MDR regulatory pathway timelines, existing CMS reimbursement code structures, and prevailing silver commodity price bands, with variable sensitivity on cloud-telemetry adoption velocity and EHR interoperability standardization. Segmentation dimensions span product architecture, sensing technology, clinical application, and end-user procurement channel. CAGRs derive from installed base replacement cycles and ambulatory surgical center expansion trajectories. Forecast inputs incorporate FCC unlicensed spectrum compliance costs and EU MDR Class IIa clinical performance study durations.
Sensitivities concentrate around FDA breakthrough designation velocity, CMS remote monitoring reimbursement expansion, and silver nanowire electrode commodity volatility. Forecasts reflect documented assumptions on regulatory pathway stability and hospital procurement consolidation trajectories. Material shifts in FDA algorithm validation requirements or EU MDR post-market surveillance mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Aesthetic Devices Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
EMEA Surgical Microscopes Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Light Therapy Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Digital Body Thermometer Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Embolization Coils Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Intubation Tubes Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
North America Insulin Delivery Devices Market