
 MLCC Silicone Release Film Market | 2026-2036
MLCC Silicone Release Film Market Size, Share, and Industry Trends Forecast 2026-2036
MLCC Silicone Release Film Market Insights
EU REACH is recalibrating the cost-of-entry calculus for silicone release film suppliers targeting European electronics OEMs. Toyobo leverages its polymer science heritage to sustain premium positioning in high-temperature film grades. Mitsui Chemicals anchors its competitive stance through backward integration into silicone resin production. LINTEC differentiates via proprietary coating technologies that navigate increasingly stringent volatile organic compound limits.
MLCC silicone release film denotes a polymeric substrate, typically polyethylene terephthalate or polyethylene naphthalate, coated with a crosslinked polydimethylsiloxane layer that enables clean delamination of green-sheet ceramic tapes during capacitor lamination. The silicone coating thickness, generally between 0.5 and 2.0 micrometers, determines release force consistency critical to preventing dielectric layer distortion. High-temperature film commands disproportionate margin pools as automotive-grade MLCCs shift to lead-free reflow profiles exceeding 260 degrees Celsius. Electronics applications dominate volume consumption while anti-static variants represent the fastest-growing product category driven by electrostatic discharge sensitivity in sub-micron dielectric formulations.
Japan's METI enforces chemical substance reporting under its Industrial Safety and Health Act that shapes silicone monomer sourcing protocols for Toray Industries and Mitsubishi Chemical Corporation. China's SAMR administers GB standards governing plastic film food-contact migration limits that indirectly constrain substrate selection even for industrial electronics grades. Stakeholders must monitor regulatory divergence between Asian and European chemical control frameworks when qualifying second-source film suppliers.
Market Dynamics
Lead-free reflow temperatures above 260 degrees Celsius are forcing MLCC manufacturers to abandon conventional release films for silicone-coated grades that withstand thermal stress without delamination defects.
Growth Catalysts
- Automotive electronics qualification:Electric vehicle inverters and onboard chargers require Class AEC-Q200 capacitors that demand high-temperature release films for defect-free lamination.
- REACH Substances of Very High Concern:European ECHA restrictions on legacy release agents are redirecting procurement toward compliant silicone-coated substrates.
- Jiangsu-Zhejiang foundry cluster expansion:Concentrated MLCC capacity in these provinces generates localized demand pull for adjacent film converting operations.
Market Restraints
- Dimethylsiloxane monomer supply concentration:Precursor availability hinges on a narrow base of silicone resin specialists, creating input cost volatility.
- Substrate thickness tolerances:PET and PEN film gauge consistency below 12 micrometers remains technically constrained, limiting yield rates.
- Dual carbon compliance in China:MEE enforcement of carbon intensity benchmarks raises energy costs for film coating operations.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and passive component production create virgin demand territory outside established East Asian supply chains.
- Anti-static film variants:Sub-micron dielectric formulations in 5G base stations require electrostatic discharge protection during tape processing.
- Closed-loop PET recycling:Circular substrate sourcing aligns with EU Green Deal procurement mandates for sustainable electronics materials.
Industry Challenges
- Silicone coating uniformity expertise:Crosslinking chemistry control for sub-1.0 micrometer layers requires specialized process engineers in short supply.
- GB standard migration testing:SAMR food-contact compliance documentation for industrial electronics grades extends qualification timelines by 8-14 months.
- Legacy lamination equipment retrofit:Green-sheet tape handling systems require recalibration for modified release force profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MLCC Silicone Release Film Market |
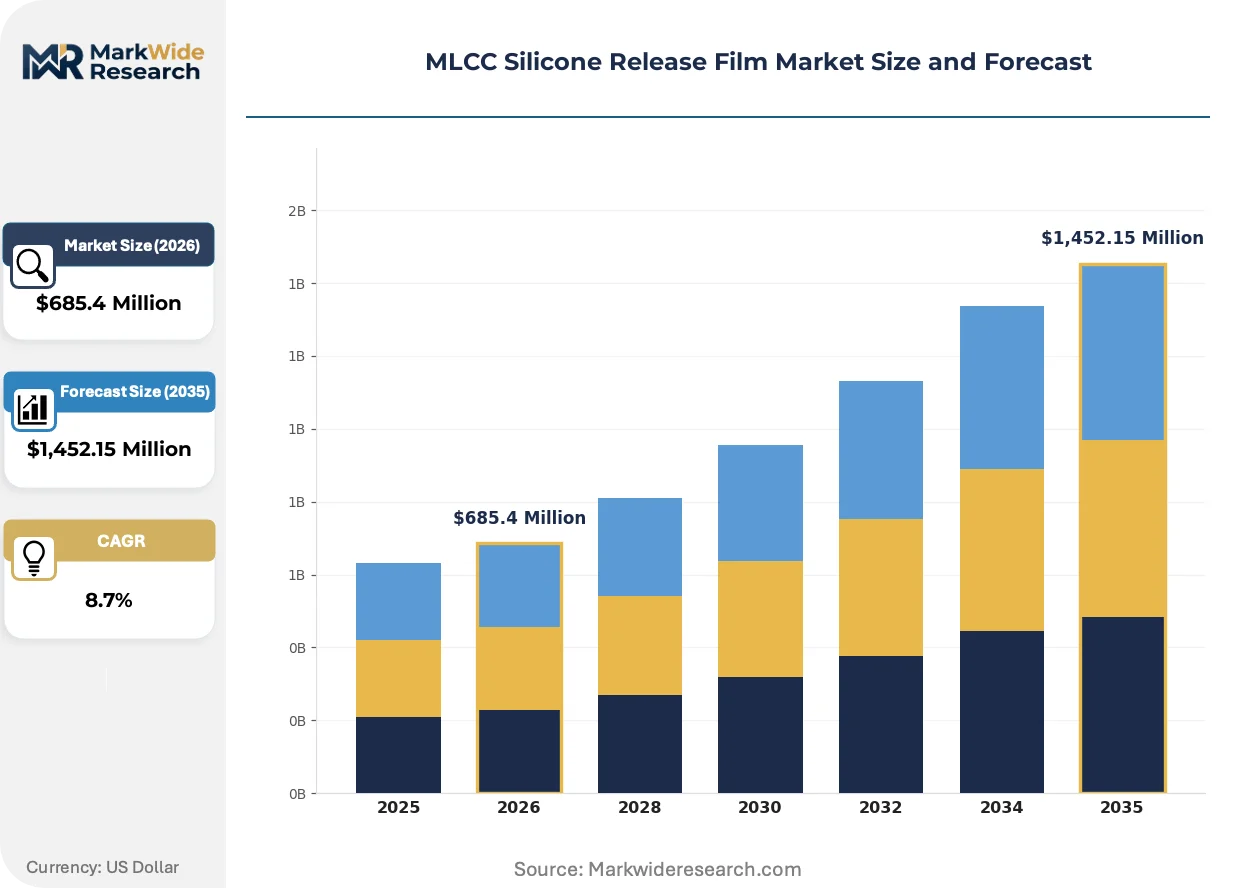
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Film, High-Temperature Film, Anti-Static Film, Double-Sided Film Application: Electronics, Automotive Components, Medical Devices, Packaging Solutions End User: Manufacturers, Distributors, Research Institutions, Healthcare Providers Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Toyobo, Mitsui Chemicals, LINTEC, SKC, Toray Industries, Mitsubishi Chemical Corporation, Nan Ya Plastics Corp., Zhejiang Jiemei Electronic Technology, Jiangsu Shuangxing Color Plastic New Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MLCC Silicone Release Film Market Trends and Innovations
Silicone release film technology is bifurcating between commodity substrates for consumer electronics and precision-engineered grades for automotive and telecommunications applications requiring thermal resilience.
Polyethylene naphthalate substrates with enhanced dimensional stability are electrifying the high-reliability segment. Automotive MLCC manufacturers in Germany and Japan are adopting PEN-based films for lead-free reflow compatibility. This material transition is compressing PET film margins in premium thermal grades while opening specialty resin supply contracts.
China's evolving GB standards for plastic film migration limits are reshaping substrate qualification protocols. SAMR testing requirements now extend to industrial electronics grades previously exempt from food-contact scrutiny. Korean and Taiwanese film converters are establishing dedicated testing laboratories in Shanghai to accelerate compliance documentation.
Consolidated procurement by vertically integrated MLCC foundries is displacing fragmented distributor channels. Samsung Electro-Mechanics and Murata Manufacturing now specify direct film supply agreements with coating specialists. This channel compression is most visible in Japan and South Korea where captive supply relationships dominate capacitor supply chains.
MLCC Silicone Release Film Market Segmentation
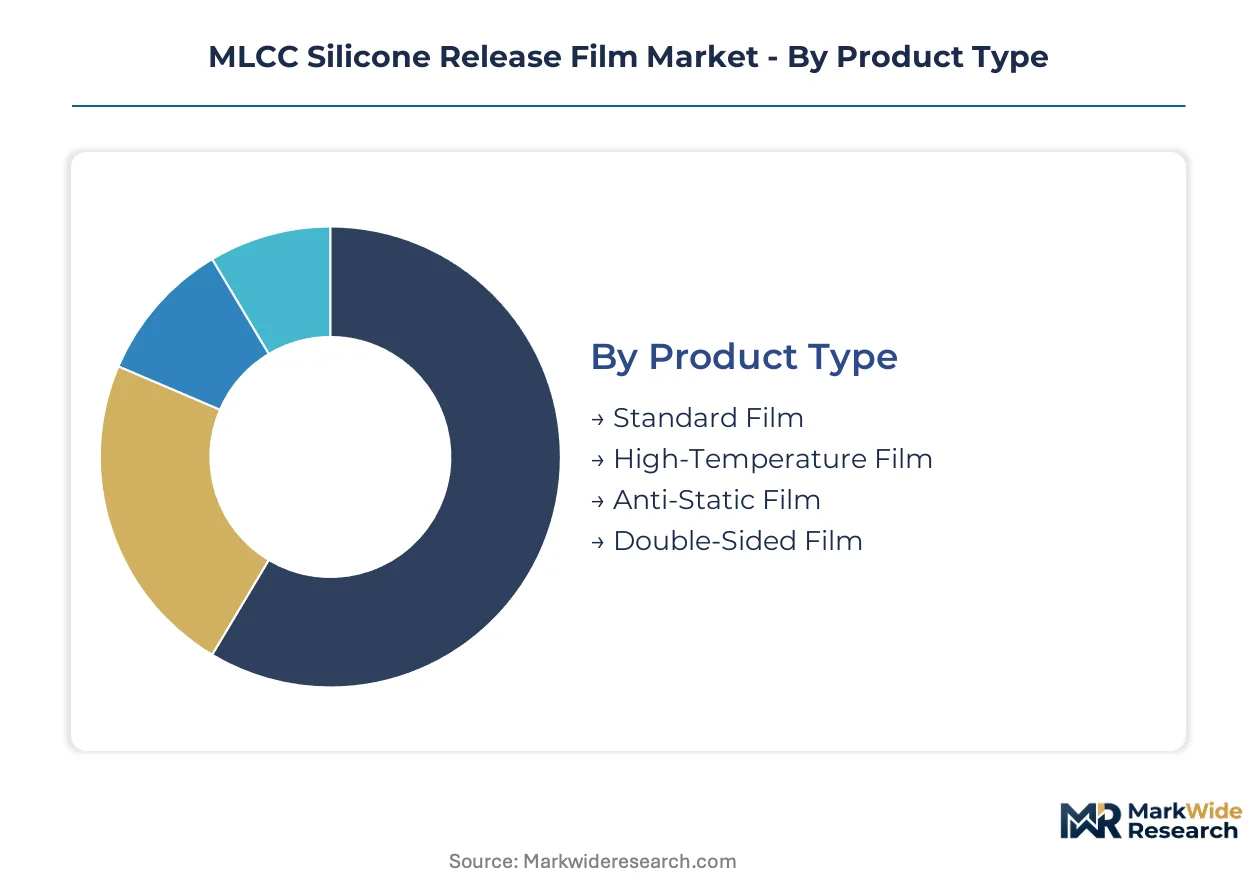
MLCC silicone release film segmentation reveals how thermal performance requirements and electrostatic sensitivity reshape procurement patterns across capacitor manufacturing tiers. Product type differentiation determines which films operate as standalone consumables versus integrated process materials within lamination workflows.
Product Type:
Standard films function as discrete consumables in conventional MLCC production, while high-temperature and anti-static variants embed into specialized manufacturing systems requiring thermal resilience or ESD protection.
- Standard Film:Polyethylene terephthalate substrates carry 0.5-1.0 micrometer silicone coatings for consumer electronics MLCCs with reflow temperatures below 240 degrees Celsius. Jiangsu province manufacturers in China consume the majority of this grade for mid-range capacitor output.
- High-Temperature Film:Polyethylene naphthalate substrates withstand lead-free reflow profiles exceeding 260 degrees Celsius through enhanced dimensional stability. German and Japanese automotive electronics suppliers specify this grade for AEC-Q200 qualified capacitors in electric vehicle inverters.
- Anti-Static Film:Conductive particle-loaded coatings dissipate electrostatic charge during sub-micron dielectric tape processing in 5G base station component manufacturing.
- Double-Sided Film:Dual silicone-coated substrates enable simultaneous green-sheet release from both surfaces in high-throughput lamination presses.
Volume placements concentrate in Standard Film; the faster expansion belongs to Anti-Static Film.
Application:
Application segmentation tracks how thermal qualification requirements stratify film procurement across end-use sectors with divergent reliability standards.
- Electronics:Smartphones, laptops, and consumer devices drive baseline consumption of standard-grade release films with moderate thermal demands.
- Automotive Components:Onboard chargers and DC-DC converters require high-temperature films certified to AEC-Q200 standards. Japanese and German Tier-1 suppliers enforce direct film supply agreements with coating specialists to ensure traceability.
- Medical Devices:Implantable and diagnostic equipment MLCCs demand ultra-clean film substrates with documented extractables testing. ISO 13485 compliance extends qualification timelines.
- Packaging Solutions:Specialized tape applications for sensitive component shipping utilize release films as process aids rather than manufacturing inputs.
Electronics commands the largest volume position; Automotive Components exhibits the steepest expansion trajectory.
End User:
End user categories reflect divergent procurement sophistication, from captive film specifications by integrated manufacturers to spot purchasing by research entities.
- Manufacturers:Samsung Electro-Mechanics, Murata Manufacturing, and TDK specify direct supply agreements with coating specialists, compressing distributor channels. These vertically integrated capacitor foundries dominate premium film consumption.
- Distributors:Regional converters in Taiwan and South Korea maintain inventory positions for mid-tier MLCC producers lacking captive supply relationships.
- Research Institutions:Universities and national laboratories purchase small-batch specialty films for next-generation dielectric formulation trials.
- Healthcare Providers:Medical device OEMs source through qualified suppliers with FDA or PMDA device master file documentation.
Procurement volume clusters with Manufacturers; Research Institutions are gaining share fastest for experimental high-temperature formulations.
Distribution Channel:
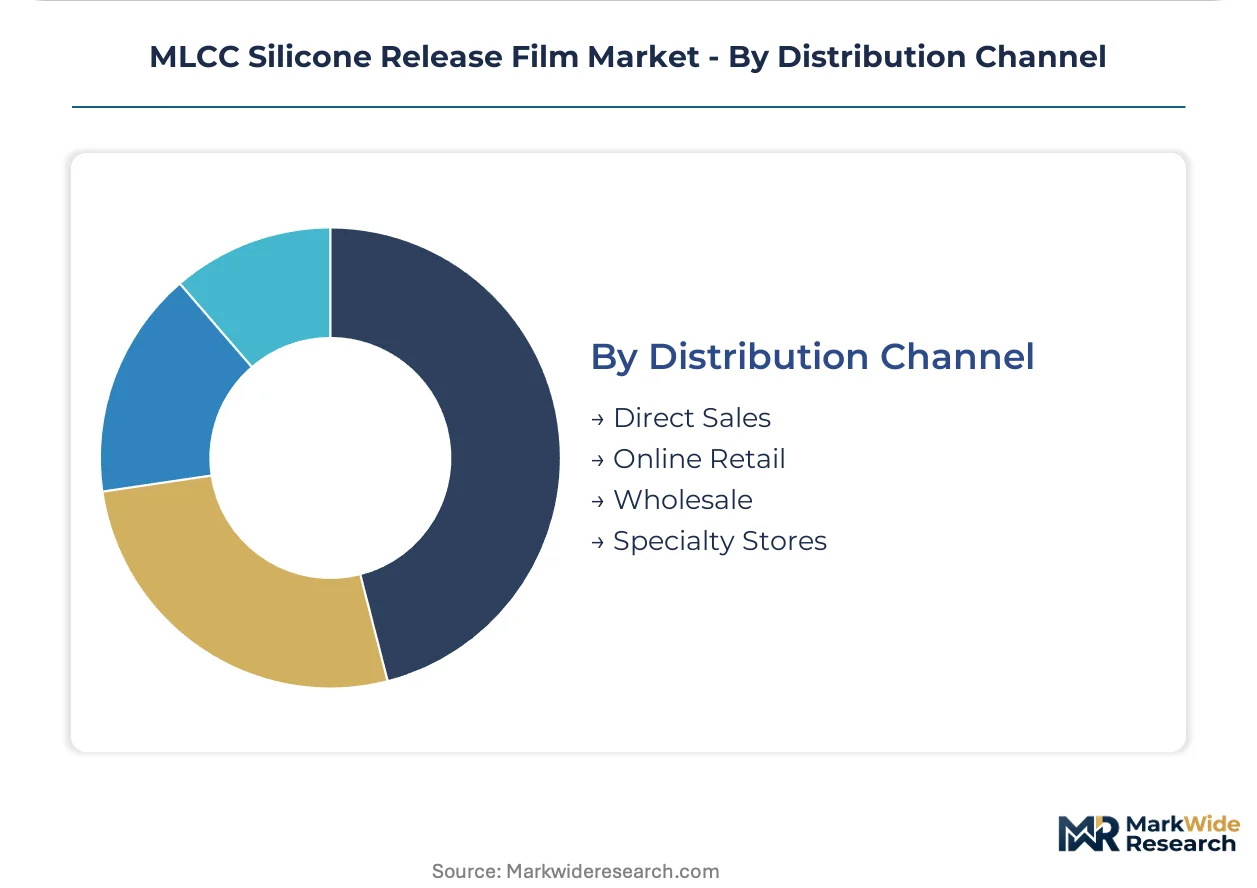
Channel structure reveals how consolidated capacitor foundry procurement is displacing fragmented supply routes across East Asian production clusters.
- Direct Sales:Coating specialists like LINTEC and Toyobo negotiate multi-year supply contracts with MLCC manufacturers. This channel captures premium-grade film transactions.
- Online Retail:E-commerce platforms serve prototype quantities and research laboratory procurement with limited technical support.
- Wholesale:Regional distributors in Shenzhen and Seoul aggregate standard film volumes for second-tier capacitor producers.
- Specialty Stores:Technical film distributors in Osaka and Taipei stock anti-static and high-temperature grades for just-in-time delivery to precision electronics manufacturers.
Transaction volume concentrates in Direct Sales; Online Retail is climbing the fastest for small-batch and experimental procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Jiangsu and Zhejiang provinces anchor the densest concentration of MLCC foundry capacity, with special economic zones offering preferential tax treatment for electronics materials suppliers locating near capacitor production clusters.
China
Jiangsu and Zhejiang provinces host Samsung Electro-Mechanics and domestic capacitor foundries consuming the majority of standard-grade silicone release films. SAMR administers GB standards governing plastic film migration limits that constrain substrate selection even for industrial electronics grades. Suzhou and Ningbo clusters are expanding high-temperature film converting operations to serve automotive MLCC qualification programs.
Japan
Murata Manufacturing and TDK drive premium film consumption through direct supply agreements with coating specialists. METI enforces chemical substance reporting under the Industrial Safety and Health Act that shapes silicone monomer sourcing protocols for domestic resin producers. Kansai and Chubu industrial corridors concentrate backward-integrated film manufacturing with captive silicone resin production.
South Korea
Samsung Electro-Mechanics and smaller capacitor producers generate concentrated demand for anti-static and high-temperature film variants. MFDS pharmaceutical and medical device regulations indirectly influence cleanroom-grade film specifications for healthcare electronics applications. Seoul Capital Area and Busan-Ulsan corridors house vertically integrated supply relationships dominating premium film procurement.
Germany
Bosch and Continental Tier-1 suppliers enforce AEC-Q200 qualified film specifications for electric vehicle inverter capacitors. ECHA REACH Substances of Very High Concern restrictions redirect procurement toward compliant silicone-coated substrates away from legacy release agents. Bavaria and Baden-Württemberg automotive electronics clusters are qualifying PEN-based films for lead-free reflow compatibility above 260 degrees Celsius.
United States
Onshore MLCC reshoring initiatives under the CHIPS and Science Act are stimulating virgin demand for high-reliability release films in defense and automotive applications. EPA volatile organic compound regulations constrain coating operation siting decisions for film converters. Texas and Arizona emerging semiconductor corridors are attracting film supplier qualification programs for captive capacitor production.
MLCC Silicone Release Film Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers in the MLCC silicone release film market. Japanese and Korean chemical groups leverage backward integration into silicone resin production to defend input cost positions. Three archetypes dominate: integrated petrochemical conglomerates with captive film operations, specialized coating technology houses, and regional substrate converters. Capacity expansion and direct supply agreement negotiation constitute the dominant competitive moves as distributor channels compress.
Within the integrated conglomerate tier, Mitsui Chemicals and Mitsubishi Chemical Corporation exemplify upstream control over dimethylsiloxane monomer supply. Toray Industries occupies a position bridging resin production and precision film manufacturing. Among coating specialists, LINTEC and Toyobo represent proprietary technology differentiation in sub-micrometer silicone layer deposition. SKC and Nan Ya Plastics Corp. anchor the substrate supply vector with polyethylene terephthalate and polyethylene naphthalate film production capabilities.
| Leading Market Players |
|---|
| Toyobo |
| Mitsui Chemicals |
| LINTEC |
| SKC |
| Toray Industries |
| Mitsubishi Chemical Corporation |
| Nan Ya Plastics Corp. |
| Zhejiang Jiemei Electronic Technology |
| Jiangsu Shuangxing Color Plastic New Materials |
| Others |
Pricing and Supply Chain Analysis
Dimethylsiloxane monomer spot pricing volatility cascades through MLCC silicone release film supply chains, compressing margins for substrate converters lacking backward integration into silicone resin production while amplifying pricing power for integrated Japanese and Korean chemical groups.
Pricing Analysis
Short lead-time premiums command substantial markups as automotive MLCC manufacturers rush-qualify PEN-based films for AEC-Q200 programs. Three-tier pricing structure across premium, standard, and economy levels separates certified automotive grades from consumer electronics specifications. Cost compression in standard PET film tiers is intensifying because Chinese converters are expanding coating capacity in Jiangsu province. Spot buyers in research institutions exhibit highest price sensitivity; captive procurement teams at Samsung Electro-Mechanics and Murata Manufacturing show least elasticity due to traceability requirements.
Supply Chain Analysis
Dual-sourcing mandates from Tier-1 automotive electronics suppliers force MLCC foundries to qualify second-source film converters, fragmenting procurement concentration despite geographic clustering. Supply concentrates in Japan, South Korea, and China, with Japanese resin producers anchoring high-temperature film output. Raw material dependencies center on dimethylsiloxane monomers, PET and PEN substrates, and conductive particle additives. Single-source vulnerability in silicone resin specialists creates input disruption risk. Distribution runs through direct sales agreements with vertically integrated capacitor manufacturers, compressing wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH Substances of Very High Concern screening creates a barrier-to-entry moat for coating specialists with documented chemical substance reporting protocols.
For Market Incumbents: Hedge against margin erosion in standard film tiers by deepening upstream control over silicone resin production and accelerating high-temperature film certification for automotive qualification programs. Threat substitution from ceramic tape direct-coating technologies demands defensive R&D investment in sub-micrometer coating uniformity expertise. Capacity addition in Suzhou and Ningbo clusters captures Jiangsu-Zhejiang demand concentration. For New Entrants and Emerging Players: Capture virgin demand territory in India's PLI-supported electronics manufacturing corridors before established East Asian supply relationships solidify. Most penetrable segment lies in anti-static film variants for 5G base station component production, where electrostatic discharge sensitivity outpaces incumbent coating capacity. Go-to-market angle: partner with Korean and Taiwanese film converters establishing Shanghai testing laboratories for SAMR GB standard compliance acceleration. For Investors and Strategic Acquirers: The window for entry favors coating technology specialists with proprietary sub-micrometer silicone layer deposition capabilities and established automotive electronics qualification records. Long-term viability hinges on regulatory compliance infrastructure rather than commodity substrate scale. Acquisition target archetype: regional substrate converters with latent coating capacity and SAMR testing laboratory access. Signal to watch: SAMR enforcement timeline for industrial electronics grade migration testing documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Resin | Mitsui Chemicals and Mitsubishi Chemical Corporation defend input cost positions against dimethylsiloxane monomer volatility. |
| High-Temperature Film Certification | PEN-based film qualification for AEC-Q200 standards captures automotive electronics premium pricing tiers. |
| Shanghai Testing Laboratory Establishment | Korean and Taiwanese converters accelerate SAMR GB standard compliance documentation for industrial electronics grades. |
| Direct Supply Agreement Negotiation | LINTEC and Toyobo compress distributor channels through multi-year contracts with Samsung Electro-Mechanics and Murata Manufacturing. |
| Closed-Loop PET Recycling Program | Circular substrate sourcing aligns with EU Green Deal procurement mandates for sustainable electronics materials. |
Research Methodology
Independent corroboration across silicone resin procurement managers, MLCC foundry process engineers, and automotive electronics Tier-1 supplier quality directors underwrites the qualitative findings in this analysis. Primary interviews with coating technology specialists and substrate converter operations heads combined with secondary validation from customs trade data, chemical industry association reports, and SAMR regulatory filings. Bottom-up demand modeling from capacitor production capacity announcements triangulates against top-down chemical feedstock consumption estimates.
Comparable-period anchoring to historical silicone release film consumption patterns across consumer electronics, automotive, and telecommunications application cycles shapes the projection horizon. Segmentation dimensions modeled include product type tier, thermal performance specification, end-use industry reliability standard, and regional production cluster regulatory framework. CAGRs derive from elasticity-adjusted demand curves incorporating lead-free reflow temperature adoption curves and electrostatic discharge sensitivity requirements in sub-micron dielectric formulations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR GB standard enforcement timelines and ECHA REACH substance restriction expansions. Forecasts reflect documented assumptions on dimethylsiloxane monomer supply concentration and Jiangsu-Zhejiang foundry cluster expansion rates. Deviation in automotive electronics lead-free reflow qualification pace or silicone resin capacity addition timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Barium Borate Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Mesoporous Silica Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Conductive Fluted Sheets Market