
 Global Cell Separation Technology Market | 2026-2036
Global Cell Separation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Separation Technology Market Foresight
Direct-to-laboratory distribution channels is reshaping how cell separation consumables reach end users, bypassing traditional distributor markups and shortening replenishment cycles. Thermo Fisher Scientific leverages its global logistics network to sustain same-day delivery commitments in North American research corridors. Danaher Corporation anchors its position through deep integration of cell separation hardware with cloud-connected analytics platforms. Miltenyi Biotec differentiates by dominating the magnetic activated cell sorting segment with proprietary column-based workflows that command premium placement in European academic institutions.
Cell separation technology encompasses methods for isolating specific cell populations from heterogeneous biological samples based on physical, biological, or immunological properties, typically achieving purity thresholds exceeding 95% for downstream genomic or proteomic analysis. These systems serve fundamental roles in stem cell research, immunotherapy development, and clinical diagnostics where contaminating cell types compromise experimental validity or therapeutic safety. Magnetic activated cell sorting commands the largest installed base due to its antibody specificity and gentle handling of viable cells, while microfluidics represents the fastest-expanding technology dimension as labs miniaturize workflows and reduce reagent volumes. The product type landscape tilts toward automated cell separators where margin pools deepen through recurring consumable attachments and software subscription layers.
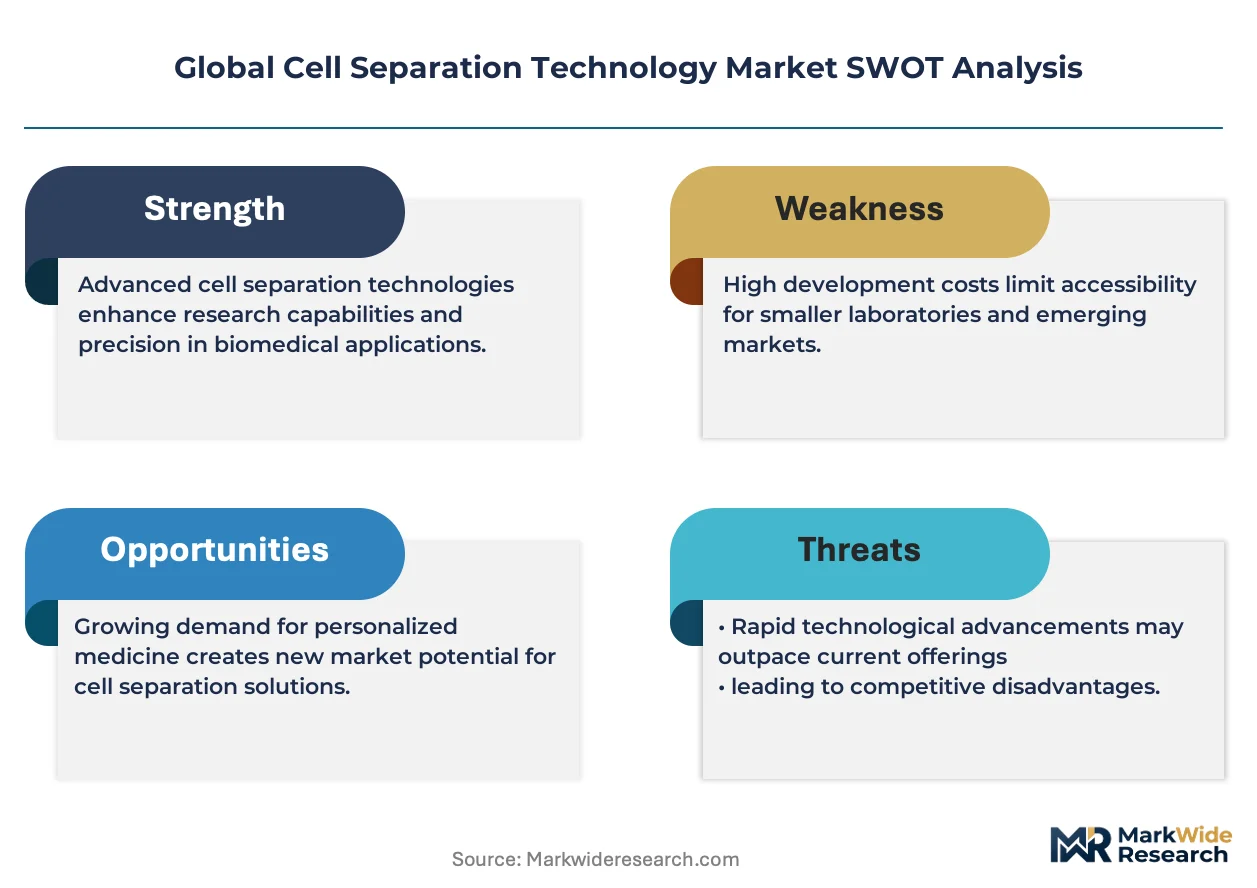
The FDA enforces current Good Manufacturing Practice standards for cell separation devices used in therapeutic manufacturing, compelling vendors to validate traceability and sterility protocols. EMA's Medical Device Regulation and Japan's PMDA quality management requirements create parallel compliance burdens for multinational suppliers seeking market access across three major jurisdictions. Stakeholders must monitor how evolving ISO 13485 interpretations for automated systems reshape qualification timelines and competitive entry barriers.
Market Dynamics
Microfluidics is compressing reagent volumes and instrument footprints while FDA validation requirements for cell-based therapies intensify scrutiny of separation workflow traceability. This dual pressure rewards vendors with integrated hardware-software platforms and punishes point-solution suppliers.
Growth Catalysts
- Immunotherapy manufacturing scale-up:CAR-T production facilities in the United States and China require high-throughput magnetic separation platforms. FDA's evolving guidance on cell-based therapies mandates validated separation workflows.
- EMA Medical Device Regulation:The MDR's stricter clinical evidence requirements for automated cell separators is accelerating replacement of legacy equipment in European diagnostic centers.
- Stem cell banking expansion:Cord blood processing facilities in India and Brazil are adopting fluorescence-activated cell sorting for CD34+ enrichment. National stem cell registry mandates in these countries drive standardization.
Market Restraints
- Neodymium supply concentration:Magnetic activated cell sorting depends on rare-earth magnets where Chinese processing facilities control refining capacity. Price volatility in this input compresses hardware margins.
- Antibody cost structure:Proprietary conjugated antibodies for cell surface markers carry royalty burdens from diagnostic patent estates. This raises per-run consumable costs above microfluidic alternatives.
- Technical throughput ceilings:Column-based magnetic separation faces physical limits on parallel processing that microfluidic chips circumvent. Academic labs with budget constraints remain locked into lower-throughput workflows.
Strategic Opportunities
- Point-of-care decentralization:Miniaturized separation cartridges for bedside immunotherapy processing in German and Japanese hospitals bypass centralized lab bottlenecks. PMDA's streamlined review pathway for designated breakthrough devices accelerates entry.
- Cloud-connected analytics integration:Vendors bundling separation hardware with AI-driven cell population analysis capture recurring software revenue. This convergence targets contract research organizations running high-content screening.
- India's PLI scheme for medical devices:Domestic manufacturing incentives for precision equipment reduce import duty exposure for magnetic separator assembly. Local production lowers landed cost for South Asian research institutes.
Industry Challenges
- ISO 13485 interpretation variance:Notified bodies apply divergent standards for automated system validation across EU member states. This fragments qualification timelines and raises compliance engineering headcount.
- Legacy LIS integration complexity:Hospital laboratory information systems use incompatible data formats that complicate bidirectional connectivity for cell separation instruments. Middleware development consumes R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Separation Technology Market |
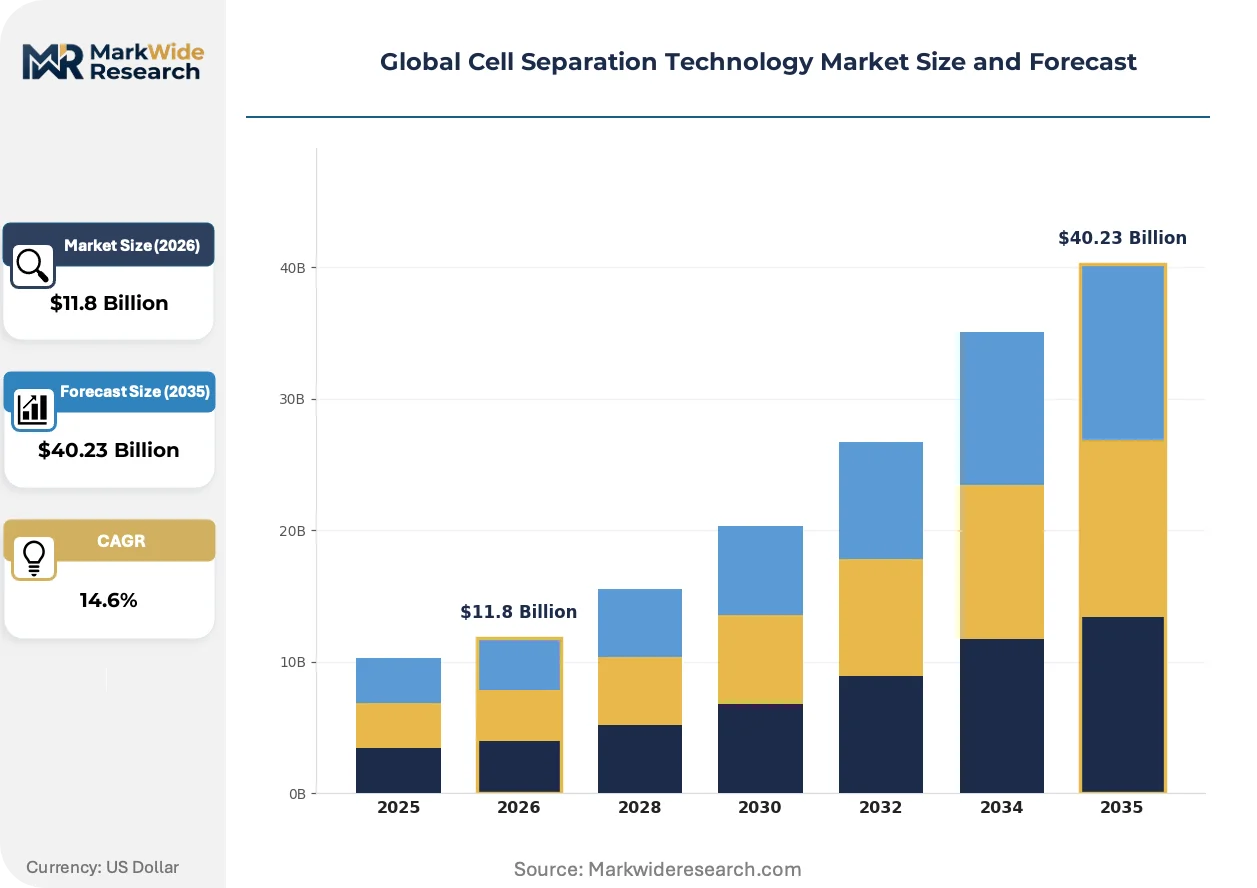
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Magnetic Activated Cell Sorting, Fluorescence Activated Cell Sorting, Density Gradient Centrifugation, Microfluidics, Acoustic Separation Application: Stem Cell Research, Immunology Studies, Oncology Screening, Infectious Disease Diagnosis, Regenerative Medicine End User: Research Laboratories, Biotechnology Firms, Diagnostic Centers, Academic Institutions, Contract Research Organizations Product Type: Automated Cell Separators, Manual Cell Separators, Microfluidic Devices, Centrifuges, Separation Kits |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Becton, Dickinson and Company, Merck KGaA, Miltenyi Biotec, STEMCELL Technologies, Corning, Bio-Rad Laboratories, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Separation Technology Market Shifts & Advancements
Digital twin architectures and AI-assisted gating algorithms are redefining how separation protocols get optimized and validated. The competitive frontier now sits at the intersection of hardware miniaturization and predictive software layers.
Acoustic separation technology is virtualizing traditional centrifugation and magnetic bead workflows by using ultrasonic standing waves to isolate cells based on size and density. Contract development and manufacturing organizations in the United States are piloting these systems for exosome isolation. This virtualization eliminates consumable antibody costs and reduces cross-contamination risks in multi-product facilities.
REACH regulation amendments on per- and polyfluoroalkyl substances are forcing reevaluation of hydrophobic surface coatings used in microfluidic channels. Manufacturers must reformulate chip materials or face market withdrawal in EU member states. Diagnostic instrument suppliers with European manufacturing footprints are accelerating fluorine-free coating qualification programs.
Research consortia in Germany and Switzerland are consolidating purchasing through framework agreements that bundle cell separation hardware with multi-year service and reagent commitments. This displaces transactional spot-buying through distributors. University hospital networks in these countries now negotiate enterprise pricing that locks in vendor relationships across five-year horizons.
Global Cell Separation Technology Market Segmentation
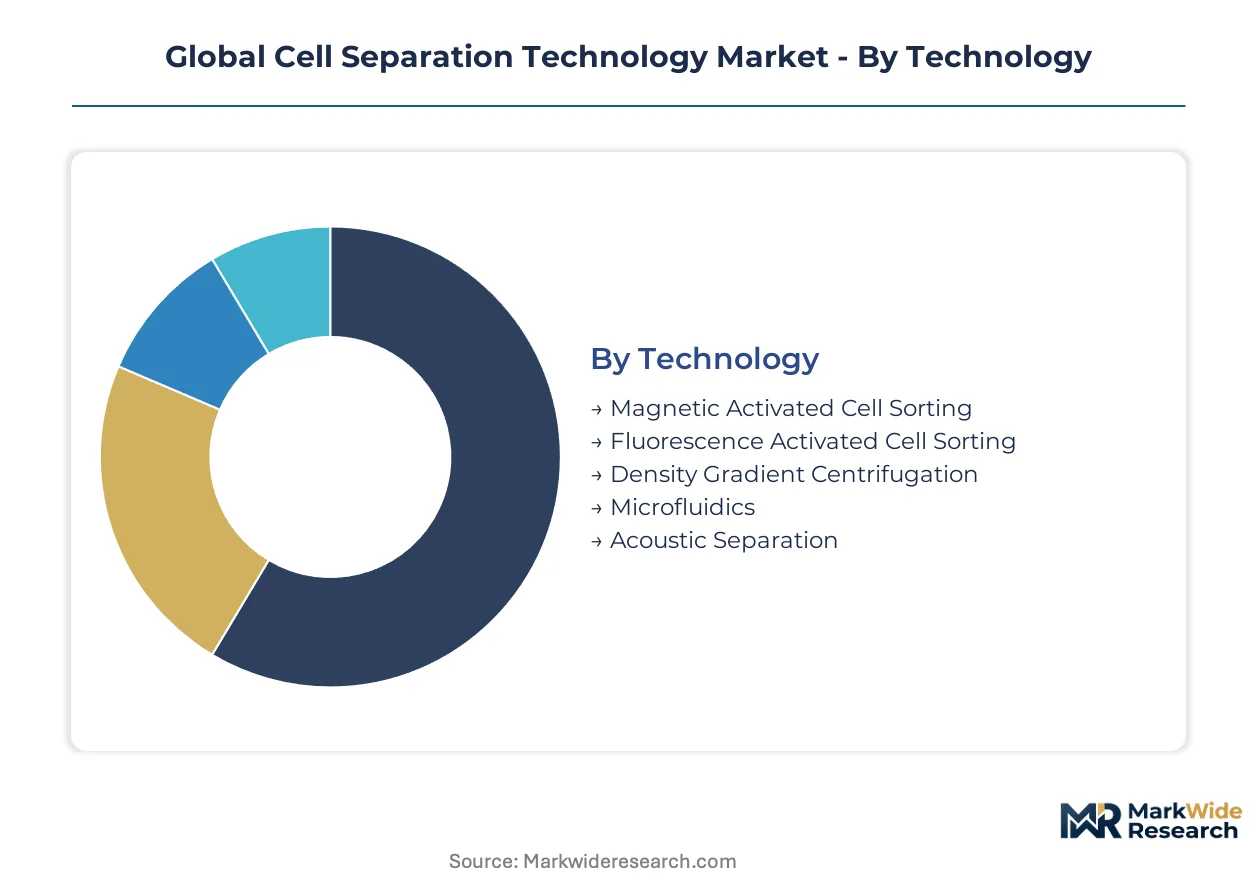
Technology choice dictates capital intensity, consumable economics, and regulatory burden across cell separation workflows. Application focus determines whether installations serve research flexibility or manufacturing compliance. End-user category shapes purchasing authority and service contract structures.
Technology:
Application requirements and throughput demands fragment the technology landscape across five distinct methodological approaches.
- Magnetic Activated Cell Sorting:Antibody-conjugated paramagnetic beads isolate target populations through column-based or tube-based workflows. CAR-T manufacturing facilities in the United States and China anchor demand for high-throughput platforms that preserve cell viability.
- Microfluidics:Lab-on-chip architectures manipulate cells through precisely engineered channels using dielectrophoresis or hydrodynamic focusing. Academic laboratories in Germany and Switzerland adopt these systems to compress reagent volumes and enable parallel processing arrays.
- Fluorescence Activated Cell Sorting:Laser excitation and multi-parameter detection enable complex population discrimination. Diagnostic centers deploy these platforms for leukemia immunophenotyping where multiparameter gating is essential.
- Density Gradient Centrifugation:Differential sedimentation separates cells by buoyant density using Ficoll or Percoll media. Cord blood processing facilities in India leverage this cost-effective approach for initial mononuclear cell enrichment.
- Acoustic Separation:Ultrasonic standing waves create pressure nodes that trap cells by size and compressibility. Contract development organizations pilot these antibody-free systems for exosome isolation in multi-product biomanufacturing suites.
Magnetic Activated Cell Sorting commands the established base. The steepest expansion runs through Microfluidics.
Application:
Clinical translation timelines and reimbursement pathways differentiate demand patterns across therapeutic and diagnostic use cases.
- Oncology Screening:Circulating tumor cell isolation and minimal residual disease monitoring drive fluorescence-activated platform placements. Diagnostic centers in the United States expand screening programs under FDA-validated workflow requirements.
- Regenerative Medicine:Mesenchymal stem cell purification and induced pluripotent stem cell banking require GMP-compliant separation documentation. Manufacturing facilities in Japan pursue PMDA quality management certification for therapeutic-grade outputs.
- Stem Cell Research:CD34+ hematopoietic progenitor enrichment supports basic biology and transplantation protocols. Academic consortia in Switzerland negotiate framework agreements bundling hardware with multi-year reagent commitments.
- Immunology Studies:T-cell subset isolation and dendritic cell purification enable mechanistic investigation. Research laboratories prioritize flexibility over throughput in protocol development phases.
- Infectious Disease Diagnosis:Pathogen-specific cell isolation supports host-pathogen interaction studies. Public health laboratories in Brazil integrate separation workflows into emerging disease surveillance infrastructure.
Oncology Screening generates the highest instrument placement velocity. Regenerative Medicine carries the most demanding compliance overhead.
End User:
Purchasing sophistication and service expectations vary sharply across institutional categories with divergent funding mechanisms.
- Biotechnology Firms:Integrated hardware-software platforms with AI-driven analytics attract recurring subscription revenue. These customers demand cloud-connected validation documentation for IND submissions.
- Contract Research Organizations:High-content screening throughput requirements favor automated separators with 24-hour operational capacity. German CROs consolidate purchasing through enterprise pricing agreements spanning five-year horizons.
- Research Laboratories:Protocol flexibility and open architecture drive preference for modular magnetic separation systems. Budget constraints perpetuate manual workflow adoption despite throughput limitations.
- Diagnostic Centers:Regulatory compliance and bidirectional LIS connectivity dominate procurement criteria. EMA Medical Device Regulation accelerates legacy equipment replacement across European installations.
- Academic Institutions:Shared core facility models distribute capital costs across multiple principal investigators. European university hospitals negotiate service-inclusive framework agreements that displace transactional distributor relationships.
Biotechnology Firms capture vendor R&D investment focus. Contract Research Organizations expand fastest as outsourced therapeutic development concentrates.
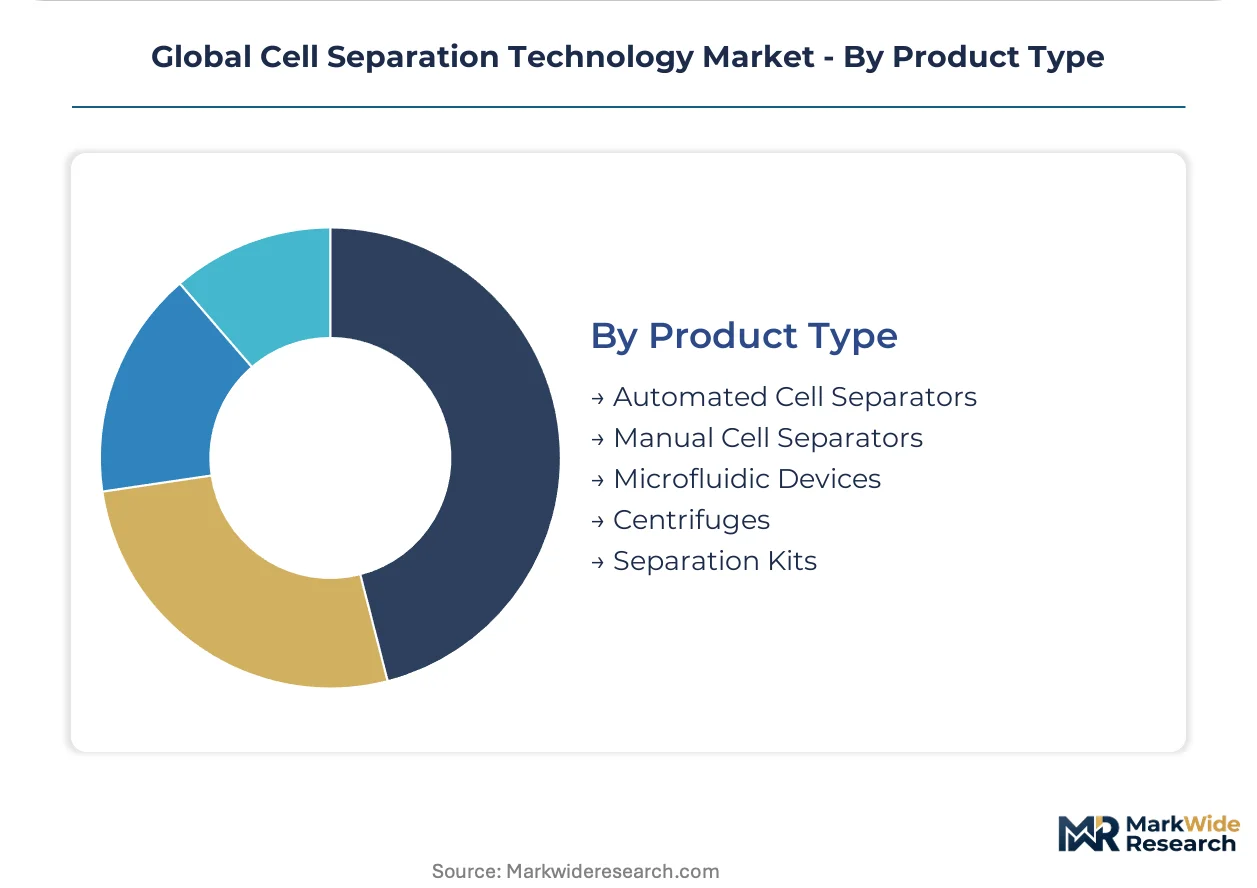
Product Type:
Margin architecture and customer lifetime value differentiate hardware categories with varying attachment rates for consumables and software.
- Automated Cell Separators:Closed-system designs with embedded software control reduce operator variation in GMP environments. These installations generate recurring revenue through proprietary column and reagent attachments.
- Microfluidic Devices:Disposable cartridge formats eliminate cross-contamination risks between patient samples. REACH regulation amendments on perfluoroalkyl substances force material reformulation for EU market access.
- Separation Kits:Pre-validated antibody panels and buffer systems reduce protocol development burden. Royalty structures from diagnostic patent estates elevate per-run consumable costs.
- Manual Cell Separators:Basic magnetic stands and column formats serve budget-constrained academic settings. Physical throughput limits constrain adoption in manufacturing-scale applications.
- Centrifuges:Density gradient and differential centrifugation systems persist in high-volume blood processing. Neodymium magnet supply concentration in Chinese refining facilities pressures hardware margins for magnetic alternatives.
Automated Cell Separators dominate revenue concentration. Microfluidic Devices climb fastest as miniaturization priorities reshape laboratory infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed regenerative medicine initiatives and cell therapy manufacturing incentives are redirecting capital flows toward specific national clusters. FDA guidance evolution in the United States, EMA Medical Device Regulation enforcement in Europe, and China's dual carbon goals are reshaping where separation technology investments concentrate.
United States
CAR-T manufacturing scale-up in Massachusetts and North Carolina biotech corridors drives demand for high-throughput magnetic separation platforms. FDA's evolving guidance on cell-based therapies mandates validated separation workflows with full traceability documentation. The Greater Boston cluster hosts contract development organizations piloting acoustic separation systems for exosome isolation.
Germany
University hospital networks in Bavaria and Baden-Württemberg negotiate five-year framework agreements bundling hardware with reagent commitments. EMA's Medical Device Regulation accelerates replacement of legacy automated separators in diagnostic centers. The Munich-Stuttgart corridor concentrates magnetic activated cell sorting placements in academic core facilities.
China
Domestic cell therapy trial pipelines in Shanghai and Suzhou expand demand for GMP-compliant separation infrastructure. NMPA quality management requirements for therapeutic manufacturing compel validation protocol upgrades. The Yangtze River Delta biotech zone attracts magnetic separator assembly under domestic production incentives.
Japan
PMDA's streamlined review pathway for designated breakthrough devices accelerates point-of-care separation cartridge approvals. METI funding for regenerative medicine manufacturing supports miniaturized system adoption in Osaka and Tokyo hospital networks. The Kansai region concentrates pilot installations for bedside immunotherapy processing.
India
Cord blood banking mandates in Maharashtra and Karnataka standardize CD34+ enrichment workflows using fluorescence-activated platforms. The PLI scheme for medical devices reduces import duty exposure for magnetic separator assembly. Hyderabad and Bengaluru research institutes benefit from localized production lowering landed equipment costs.
Global Cell Separation Technology Market Competitive Landscape
On the supply side, the industry is consolidating around integrated hardware-software platforms that capture recurring consumable revenue. Three strategic archetypes dominate: diversified life science conglomerates with global logistics networks, magnetic separation specialists with proprietary column workflows, and microfluidics innovators miniaturizing reagent volumes. Competitive positioning hardens through cloud-connected analytics bundling and multi-year service contract lock-in.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify scale-driven platform strategies. German-based Merck KGaA and Miltenyi Biotec occupy positions in the magnetic activated cell sorting specialization vector. These named entities represent how geographic origin and corporate structure align with distinct competitive archetypes rather than indicating specific strategic actions or market positions.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Merck KGaA |
| Miltenyi Biotec |
| STEMCELL Technologies |
| Corning |
| Bio-Rad Laboratories |
| Agilent Technologies |
| Others |
Supply & Pricing Matrix
Neodymium supply concentration in Chinese refining facilities determines both the spread between GMP-certified and research-grade magnetic separation platforms and the geographic shape of hardware assembly networks. This rare-earth chokepoint compresses margins on high-throughput systems while pushing vendors toward software subscription models to offset hardware pricing pressure.
Pricing Analysis
Certification level creates the primary spread between FDA-validated manufacturing platforms and research-grade magnetic separators. Three-tier pricing structure across premium GMP-compliant, standard CE-marked diagnostic, and economy research-grade levels reflects validation documentation burden and traceability protocol depth. Cost compression in the economy tier is intensifying because antibody royalty burdens from diagnostic patent estates inflate per-run consumable costs. Academic laboratories exhibit the highest price sensitivity, while CAR-T manufacturing facilities absorb premium pricing for validated workflow assurance.
Supply Chain Analysis
Export-control restrictions on semiconductor manufacturing equipment and rare-earth processing technology limit flows of precision components into Chinese assembly facilities. Hardware production concentrates in China, Germany, and the United States, with magnetic bead consumables drawing from Japanese antibody conjugation specialists and German precision engineering suppliers. Single-source vulnerability sits with neodymium magnet refining capacity controlled by Chinese state-backed processors. Distribution runs through direct-to-laboratory channels that bypass traditional distributor markups in North American research corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates formidable switching costs. FDA validation documentation and EMA Medical Device Regulation compliance erect barriers that protect incumbent positions.
For Market Incumbents: Pre-empt microfluidic displacement by bundling magnetic separation hardware with AI-driven analytics subscriptions. Accelerate cloud-connected platform deployment to lock in CRO purchasing through multi-year service commitments. Backward integration into antibody production reduces royalty exposure from diagnostic patent estates. For New Entrants and Emerging Players: Establish a beachhead in acoustic separation systems for exosome isolation where antibody-free workflows circumvent incumbent patent thickets. Target contract development organizations in the United States running multi-product biomanufacturing suites. Lead with miniaturized cartridge formats that eliminate cross-contamination risks in GMP environments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated hardware-software platforms with recurring revenue attachment. Long-term viability hinges on cloud analytics bundling and consumable lock-in rather than transactional hardware sales. Target acquisition archetypes include microfluidics specialists with REACH-compliant fluorine-free coating qualification. Watch PMDA breakthrough device designations as signal for point-of-care decentralization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Analytics Integration | Bundling separation hardware with AI-driven cell population analysis captures recurring software revenue from CROs. |
| REACH-Compliant Material Reformulation | Fluorine-free coating qualification programs secure EU market access for microfluidic chip manufacturers. |
| Direct-to-Laboratory Channel Expansion | Bypassing distributor markups shortens replenishment cycles for consumables in North American research corridors. |
| Acoustic Separation Platform Development | Antibody-free exosome isolation eliminates consumable costs and reduces cross-contamination in multi-product facilities. |
| Five-Year Framework Agreement Negotiation | Enterprise pricing with German university hospital networks locks in vendor relationships across hardware and reagent commitments. |
Research Methodology
A standing panel of CAR-T manufacturing executives, diagnostic center laboratory directors, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA Medical Device Regulation guidance documents, ClinicalTrials.gov cell therapy protocol registrations, and hospital procurement database extracts. Bottom-up instrument placement counts triangulated against top-down market sizing from trade customs data and SEC 10-K segment disclosures.
Scenario-bracketing around immunotherapy manufacturing scale-up intensity and microfluidics adoption velocity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include technology methodology, application use case, end-user institutional category, and regional regulatory cluster. CAGRs derived from instrument replacement cycle analysis and consumable attachment rate trajectories. Industry-specific forecast inputs incorporated neodymium price volatility indices and antibody royalty rate structures from diagnostic patent estates.
Macroeconomic conditions sit as an overlay; deviation in biotech venture funding availability and cell therapy clinical trial success rates would shift the trajectory. Forecasts reflect assumptions on regulatory pathway stability and rare-earth supply continuity. Material shifts in FDA guidance stringency for cell-based therapies or Chinese export restrictions on refined neodymium would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Laboratory Andrology Equipment Market