
 Cell Harvesting Systems Market | 2026-2036
Cell Harvesting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Harvesting Systems Market Analysis
The capital-intensity divergence between automated platform specialists and manual equipment suppliers is redrawing competitive boundaries in cell harvesting. Sartorius AG leverages its bioprocess automation portfolio to anchor premium positioning in closed-system harvesting. Thermo Fisher Scientific Inc. sustains scale advantages through integrated consumables and instrumentation workflows. STEMCELL Technologies specializes in research-grade density gradient and magnetic bead protocols that dominate academic and early-stage development settings.
Cell harvesting systems comprise integrated instrumentation and consumables designed to isolate, concentrate, and recover viable cells from culture media or biological matrices, typically operating within temperature-controlled, aseptic environments with throughput parameters scaled from milliliter research volumes to thousand-liter bioreactor harvests. Their primary commercial purpose centers on securing cell product yield and viability for downstream therapeutic, diagnostic, or research applications. Automated systems command the dominant revenue position due to labor cost arbitrage and contamination risk reduction in GMP environments, while microfluidics represents the fastest-expanding technology segment as miniaturization enables precision handling of limited patient-derived cell populations. Centrifuges retain the largest installed base across biopharmaceutical manufacturing, though magnetic bead separation is displacing density gradient methods in cell therapy workflows where speed-to-patient dictates process economics.
FDA's guidance on chemistry, manufacturing, and controls for cell and gene therapy products shapes equipment validation protocols, while the EU MDR and ISO 13485 frameworks enforce design documentation and traceability standards for systems deployed in clinical settings. REACH and ECHA substance restrictions additionally govern materials of construction in European-deployed equipment, particularly for single-use consumables. Stakeholders must monitor how evolving FDA and EMA guidance on closed-system processing and point-of-care manufacturing redefines equipment qualification requirements and service revenue models.
Market Dynamics
The cell harvesting systems market is experiencing a fundamental restructuring as automated closed-system platforms displace manual protocols in GMP manufacturing environments, driven by FDA and EMA contamination risk mandates and labor cost arbitrage pressures in cell therapy production.
Growth Catalysts
- FDA Guidance on Cell and Gene Therapy CMC:The agency's chemistry, manufacturing, and controls framework mandates closed-system processing for commercial-scale cell therapies, forcing biopharmaceutical manufacturers to upgrade harvesting infrastructure.
- Magnetic bead separation protocols:These technologies are accelerating cell therapy workflows by reducing processing time versus density gradient methods, enabling same-day patient administration in CAR-T manufacturing.
- United States clinical trial density:The concentration of active CAR-T and stem cell therapy trials in American research hospitals creates sustained demand for high-throughput harvesting platforms.
Market Restraints
- Single-use consumables cost structure:Proprietary bags, tubing sets, and sterile connectors from qualified suppliers command premium pricing that compresses margins for contract manufacturing organizations.
- Stainless steel equipment supplier concentration:German and Swiss precision engineering firms dominate high-capacity centrifuge manufacturing, creating supply vulnerability for North American biopharmaceutical builders.
- ISO 13485 certification timelines:The eighteen-to-twenty-four month qualification period for clinical-grade harvesting systems delays product launches and extends development runway requirements.
Strategic Opportunities
- Point-of-care manufacturing regulatory pathways:FDA draft guidance on decentralized cell therapy production creates openings for compact, validated harvesting systems deployable in hospital settings rather than centralized facilities.
- Microfluidics-precision cell handling convergence:Integration of microfluidic sorting with automated perfusion bioreactors enables gentle recovery of limited patient-derived cell populations for rare disease therapies.
- Japan's regenerative medicine commercialization framework:PMDA's accelerated approval pathways for cell therapies are driving demand for GMP-compliant harvesting systems among Japanese biotech ventures and contract manufacturers.
Industry Challenges
- Aseptic processing specialist scarcity:The shallow talent pool for operators qualified in closed-system cell harvesting under GMP conditions constrains manufacturing scale-up for emerging biotech sponsors.
- Legacy equipment integration complexity:Biopharmaceutical facilities with existing stainless steel infrastructure face substantial reconfiguration costs and validation burdens when adopting single-use automated platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Harvesting Systems Market |
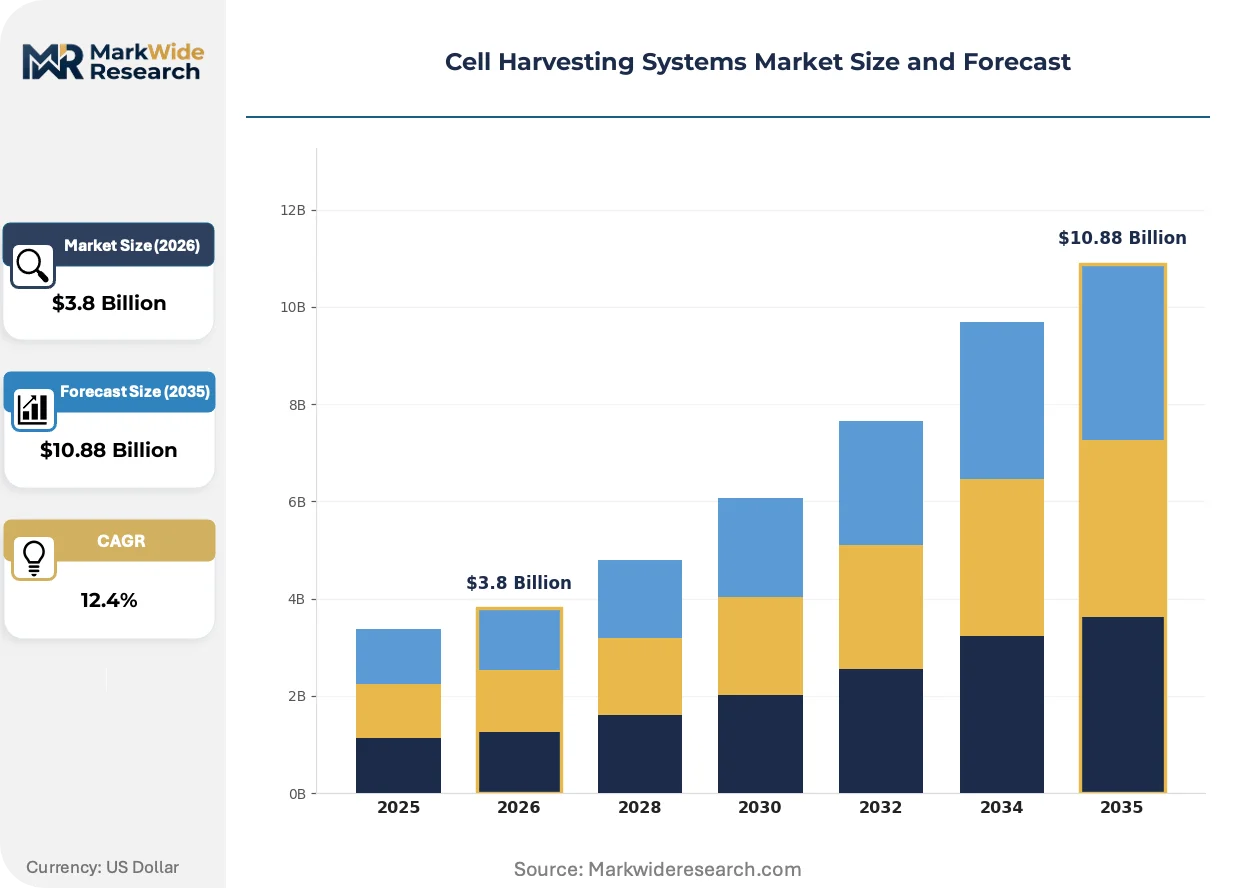
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.88 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filtration Systems, Centrifuges, Magnetic Bead Separation, Density Gradient Separation Technology: Automated Systems, Manual Processing, Microfluidics, Acoustic Separation End User: Biopharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Hospitals Application: Cell Therapy, Regenerative Medicine, Vaccines Production, Tissue Engineering |
| Companies Covered | Sartorius AG, Arthrex Inc., Thermo Fisher Scientific Inc., STEMCELL Technologies, Tomtec, Terumo Corporation, Argos Technologies Inc., Cytiva, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Harvesting Systems Market Emerging Trajectories
Microfluidic cell separation technologies are reshaping competitive positioning in cell harvesting by enabling precision handling of limited therapeutic cell populations. Three interconnected developments are redefining equipment specifications and procurement criteria across biopharmaceutical manufacturing.
Microfluidic sorting platforms are bifurcating the market between high-volume bioprocess applications and precision cell therapy workflows. Academic medical centers and emerging cell therapy developers are adopting these systems for gentle isolation of patient-derived cells. This technology is compressing the viable cell yield gap between research-scale and commercial-scale harvesting operations.
EMA's Medical Device Regulation framework is tightening design documentation and traceability requirements for cell harvesting systems deployed in European clinical settings. Manufacturers must now maintain technical files and post-market surveillance systems comparable to implantable device standards. Cell therapy contract manufacturers in Germany and the Netherlands are responding by demanding extended validation support and service revenue models from equipment suppliers.
Biopharmaceutical procurement teams are unbundling after-sales service contracts from capital equipment purchases, creating standalone revenue streams for technical support and preventive maintenance. This shift pressures traditional bundled pricing models and favors vendors with established field service networks. The United States exhibits the most advanced unbundling, with large CAR-T manufacturers negotiating separate multi-year service agreements.
Cell Harvesting Systems Market Segmentation
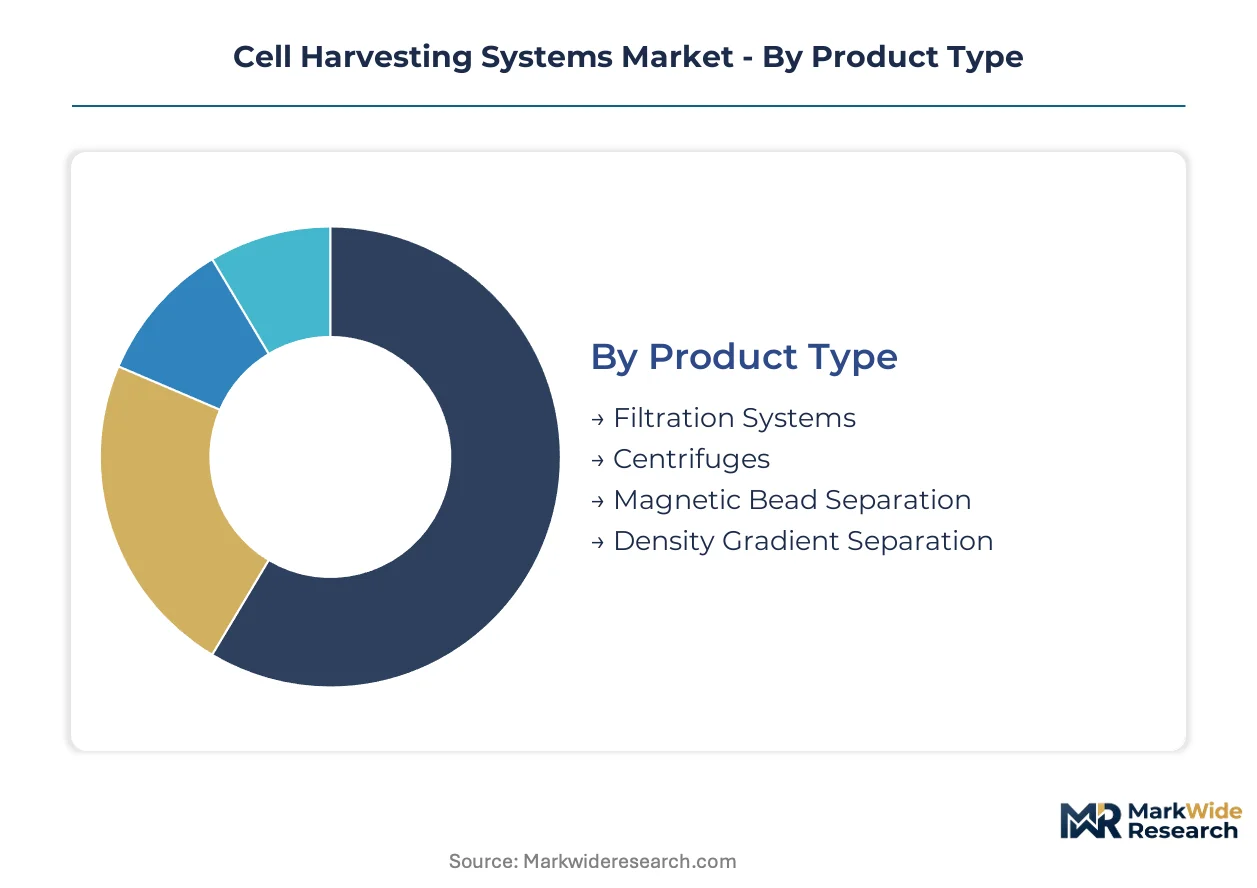
Cell harvesting systems fragment across four functional dimensions that determine procurement priorities and vendor selection criteria. Equipment specifications diverge sharply between GMP manufacturing and research environments, while technology choices reflect trade-offs between throughput, cell viability, and contamination risk.
Product Type:
Centrifuges and magnetic bead systems capture the dominant margin pools, driven by biopharmaceutical demand for closed-system processing and rapid turnaround in cell therapy workflows.
- Centrifuges:These systems employ controlled centrifugal force to separate cells from culture media based on density differentials, with continuous-flow designs dominating commercial-scale operations. Demand concentrates in United States CAR-T manufacturing facilities where FDA mandates for closed-system processing favor sealed rotor technologies. Stainless steel equipment from German and Swiss suppliers commands premium positioning in high-capacity installations.
- Magnetic Bead Separation:Antibody-coated paramagnetic particles enable selective cell isolation without density gradient centrifugation, reducing processing time from hours to minutes. Academic medical centers and contract manufacturers in Boston and San Diego are scaling adoption for same-day patient administration protocols in autologous cell therapies. Proprietary bead chemistries from qualified suppliers create consumables-driven revenue models.
- Filtration Systems:Tangential-flow and depth filtration platforms recover cells through membrane-based size exclusion, finding traction in perfusion bioreactor integration.
- Density Gradient Separation:Ficoll and Percoll media protocols retain dominance in research-grade applications where cost sensitivity outweighs speed requirements.
Centrifuges hold installed capacity across biopharmaceutical manufacturing. Magnetic bead separation is rotating up the share rankings in cell therapy applications.
Technology:
Procurement patterns split between automated platforms commanding GMP facility budgets and manual systems sustaining academic research operations.
- Automated Systems:Programmable platforms integrate cell concentration, washing, and formulation steps within temperature-controlled, aseptic enclosures. Biopharmaceutical companies in the United States are mandating these systems for commercial cell therapy production to satisfy FDA contamination risk requirements and reduce labor-dependent variability. Closed-system automation commands the highest capital expenditure per installation.
- Microfluidics:Lab-on-chip architectures manipulate cells through precisely engineered microchannels, enabling gentle handling of limited patient-derived populations. Research hospitals in Germany and the Netherlands are piloting these systems for rare disease therapies where cell scarcity demands maximum recovery efficiency. Miniaturization trends are compressing the yield gap between research and commercial scales.
- Manual Processing:Operator-dependent protocols using standard centrifuges and pipetting stations persist in early-stage development and resource-constrained settings.
- Acoustic Separation:Ultrasonic standing wave technologies separate cells without physical contact or biochemical labels, attracting interest for fragile cell types in regenerative medicine applications.
Automated systems anchor current revenue. Microfluidics is climbing the fastest as precision cell therapy workflows expand.
End User:
Customer concentration varies dramatically across the value chain, with biopharmaceutical manufacturers driving premium equipment specifications and contract manufacturers optimizing for throughput flexibility.
- Biopharmaceutical Companies:Integrated drug developers specify validated, closed-system platforms for internal manufacturing of commercial cell therapies. These organizations in the United States maintain the densest procurement activity, with CAR-T specialists in California and Massachusetts requiring 24-hour processing capabilities. Regulatory filing timelines dictate equipment qualification standards.
- Contract Manufacturing Organizations:Multi-client service providers demand modular, rapid-changeover systems to accommodate diverse cell therapy programs. European CMOs in Germany and Switzerland are investing in flexible automated platforms to capture spillover demand from biotech sponsors lacking internal GMP infrastructure. Equipment utilization rates drive return-on-investment calculations.
- Research Institutions:Academic medical centers and university laboratories prioritize cost-effective manual systems and open-architecture automation for protocol development.
- Hospitals:Point-of-care manufacturing initiatives are creating nascent demand for compact, validated systems deployable within clinical settings rather than centralized facilities.
Biopharmaceutical companies dominate capital deployment. Contract manufacturing organizations are gaining procurement velocity as outsourcing accelerates.
Application:
Commercial urgency varies across therapeutic categories, with cell therapy manufacturing imposing the most stringent processing speed and sterility requirements.
- Cell Therapy:CAR-T, TCR, and stem cell products require viable cell recovery within narrow time windows to preserve therapeutic potency. Manufacturing facilities in the United States are optimizing harvesting workflows for same-day patient administration, with magnetic bead and automated centrifugation systems displacing legacy protocols. FDA chemistry, manufacturing, and controls guidance shapes equipment validation requirements.
- Vaccines Production:Viral vector and cell-based vaccine manufacturing employs high-throughput harvesting to support pandemic response and seasonal production cycles. Contract manufacturers in India and South Korea are scaling capacity for mRNA and viral vaccine platforms, driving demand for continuous-flow centrifugation systems. Process economics favor equipment with rapid batch turnaround capabilities.
- Regenerative Medicine:Tissue-engineered products and organoid cultures utilize gentle harvesting protocols to preserve three-dimensional cellular architectures.
- Tissue Engineering:Scaffold-based constructs and bioprinting applications require specialized recovery methods that maintain extracellular matrix integrity.
Vaccines production holds historical installed base. Cell therapy is expanding most quickly as commercial approvals accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical buyers in Germany and Switzerland demonstrate the lowest price elasticity, prioritizing validation documentation and service networks over capital cost. Contract manufacturers in India and South Korea exhibit acute sensitivity to consumables pricing and equipment utilization rates. The United States occupies the middle ground, where regulatory compliance timelines outweigh pure cost minimization.
United States
The FDA's chemistry, manufacturing, and controls framework for cell and gene therapies mandates closed-system harvesting infrastructure, driving replacement cycles in commercial CAR-T facilities. The 21st Century Cures Act and subsequent FDA guidance on regenerative medicine advanced therapy accelerate qualification timelines for novel equipment. Massachusetts and California biotech clusters in Cambridge and South San Francisco concentrate the densest procurement activity for automated platforms.
Germany
EMA's Medical Device Regulation enforces design documentation and post-market surveillance standards that extend equipment qualification periods and elevate service contract values. The country's national pharmaceutical regulator, BfArM, coordinates with notified bodies on clinical-grade system certifications. Heidelberg and Munich medical centers anchor demand for precision microfluidic systems in rare disease cell therapy workflows.
Switzerland
Swissmedic's alignment with EU MDR requirements creates dual-validation pathways for equipment suppliers targeting European and Swiss markets simultaneously. The Federal Act on Medicinal Products and Medical Devices mandates traceability standards comparable to implantable device classifications. Basel's pharmaceutical manufacturing corridor sustains premium positioning for high-capacity centrifugation systems in biologics production.
Japan
PMDA's regenerative medicine accelerated approval pathways compress development timelines, forcing biotech ventures to secure GMP-compliant harvesting infrastructure earlier in product lifecycles. The Act on the Safety of Regenerative Medicine and the Pharmaceuticals and Medical Devices Act establish equipment qualification benchmarks for commercial cell therapies. Tokyo and Osaka metropolitan areas concentrate contract manufacturing investment in automated closed-system platforms.
India
CDSCO's evolving framework for cell therapy manufacturing creates compliance uncertainty that delays capital commitment from domestic biopharmaceutical developers. The Production-Linked Incentive scheme for pharmaceuticals incentivizes capacity expansion in advanced therapy manufacturing. Hyderabad and Bangalore biotech corridors attract contract manufacturing investment targeting export markets with stringent validation requirements.
Cell Harvesting Systems Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with German and Swiss precision engineering firms commanding premium positioning in high-capacity stainless steel equipment while consumables-driven specialists capture recurring revenue streams. The market structure bifurcates between integrated bioprocess automation portfolios and focused harvesting technology specialists. Three archetypes dominate: full-stack bioprocess platform providers, magnetic bead chemistry specialists, and precision centrifugation engineering houses. Competitive moves concentrate on strategic partnerships for closed-system validation and geographic expansion into Asian contract manufacturing markets.
Among integrated bioprocess platform providers, Sartorius AG and Thermo Fisher Scientific Inc. exemplify scale-driven archetypes with automation portfolios spanning upstream through downstream processing. STEMCELL Technologies occupies a specialist position, representing the research-grade protocol development segment where density gradient and magnetic bead workflows dominate academic settings. These three companies illustrate the competitive spectrum from enterprise-scale GMP infrastructure to early-stage development tooling.
| Leading Market Players |
|---|
| Sartorius AG |
| Arthrex Inc. |
| Thermo Fisher Scientific Inc. |
| STEMCELL Technologies |
| Tomtec |
| Terumo Corporation |
| Argos Technologies Inc. |
| Cytiva |
| PerkinElmer Inc. |
| Others |
Supply Flow & Price Mechanics
Single-use consumables displacing stainless steel reusable components are simultaneously relocating manufacturing gravity toward polymer processing hubs in Germany and the United States while compressing lifetime equipment economics toward recurring revenue streams. This substitution dynamic concentrates pricing power among qualified bag and tubing suppliers while fragmenting capital equipment margins across centrifuge and automation specialists.
Pricing Analysis
After-sales service contracts and preventive maintenance subscriptions now capture the dominant lifetime value share in automated harvesting platforms. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated closed-system installations from research-grade manual configurations. Pricing pressure stems from contract manufacturing organizations demanding unbundled service agreements and transparent consumables costing. Academic medical centers exhibit the highest price sensitivity, while commercial CAR-T manufacturers prioritize validation documentation over capital cost minimization.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port complexes have elevated landed costs for precision-engineered centrifuge components originating from Swiss and German manufacturing corridors. Supply concentration centers on Germany for high-capacity stainless steel equipment, Switzerland for precision rotor assemblies, and the United States for single-use polymer consumables. Critical dependencies include medical-grade silicone tubing, gamma-sterilizable polymer films, and rare-earth magnetic bead formulations. Single-source vulnerability in qualified sterile connector supply creates structural risk. Distribution runs through authorized dealer networks for capital equipment and direct procurement channels for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell harvesting systems demand is recovering from cyclical biotech funding compression as CAR-T commercial approvals and FDA manufacturing guidance create replacement cycle urgency. Capital deployment timing favors incumbents with validated platforms and emerging entrants with microfluidic precision capabilities.
For Market Incumbents: Fortify installed base retention through backward integration into single-use consumables manufacturing, capturing recurring revenue streams that offset capital equipment margin compression. Prioritize ISO 13485 certification maintenance and field service network density in United States biotech clusters to defend against modular platform challengers entering with rapid-changeover value propositions.
For New Entrants and Emerging Players: FDA's draft guidance on point-of-care manufacturing creates a certification fast-track for compact, hospital-deployable harvesting systems with abbreviated validation pathways. Target academic medical centers in Germany and the Netherlands developing rare disease cell therapies where microfluidic precision commands premium positioning. Pursue strategic equipment placement programs that convert research-scale adoption into commercial procurement relationships.
For Investors and Strategic Acquirers: EMA's Medical Device Regulation enforcement reshapes the acquisition landscape by elevating technical file maintenance and post-market surveillance capabilities to strategic assets. Five-to-ten-year viability favors targets with established notified body relationships and multi-regional regulatory dossiers. Monitor PMDA accelerated approval pathway utilization rates as the inflection signal for Japanese market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Validation Partnership | Equipment suppliers collaborating with CAR-T developers secure FDA chemistry, manufacturing, and controls compliance precedence. |
| Microfluidic Platform Launch | Precision cell handling capabilities address rare disease therapy workflows with limited patient-derived cell populations. |
| Consumables Manufacturing Scale-Up | Backward integration into gamma-sterilizable polymer production captures recurring revenue and margin expansion. |
| Point-of-Care Regulatory Pathway | Compact system development for hospital-deployable manufacturing aligns with FDA decentralized production guidance. |
| Asian Contract Manufacturing Expansion | Equipment qualification support for Indian and South Korean CMOs addresses outsourcing acceleration in cell therapy production. |
Methodological Framework
A standing panel of bioprocess engineering directors, regulatory affairs leads at cell therapy developers, hospital procurement managers, and GPO contracts specialists provided ongoing calibration against market developments. Primary interviews with equipment manufacturers and contract manufacturing organizations were cross-referenced with FDA guidance documents, EMA Medical Device Regulation technical files, ClinicalTrials.gov pipeline data, and ISO 13485 certification databases. Bottom-up segment sizing and top-down market triangulation ensured consistency across automated platform, manual system, and consumables revenue pools.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology segmentation by automation level, product type by separation mechanism, end-user concentration by manufacturing scale, and application urgency by therapeutic category. CAGRs were derived from installed base evolution, replacement cycle timing, and penetration rate assumptions for emerging microfluidic platforms. Industry-specific inputs included FDA chemistry, manufacturing, and controls guidance implementation timelines and EMA notified body capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained biotech funding availability, regulatory guidance stability, and sterile materials supply continuity would require recalibration. Forecasts reflect documented assumptions regarding commercial cell therapy approval velocity and contract manufacturing outsourcing penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Lab Automation in Bioanalysis Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market