
 Biochemistry Analyzers Market | 2026-2036
Biochemistry Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Biochemistry Analyzers Market Intelligence
Modular microfluidics is reconfiguring how biochemistry analyzers process multiplexed assays at point-of-care scale. Danaher leverages integrated reagent-cartridge architectures to sustain installed-base loyalty across high-throughput hospital labs. Roche Diagnostics anchors European demand through automated pre-analytical modules that reduce manual handling errors. Siemens Healthineers competes on AI-augmented result interpretation that flags abnormal patterns before clinician review.
Biochemistry analyzers are precision instruments that quantify metabolic markers, enzymes, electrolytes, and proteins in biological samples through photometric, electrochemical, or turbidimetric detection methods, typically operating through reaction cuvettes maintained at 37°C with sample volumes below 20 microliters. These systems serve core diagnostic functions in disease screening, therapeutic drug monitoring, and organ function assessment across clinical and research settings. Fully automated product types dominate installed capacity in developed health systems where labor costs and throughput requirements favor walkaway processing, while compact and semi-automated configurations capture expansion opportunities in resource-limited settings and decentralized veterinary clinics. Clinical testing applications command the largest revenue pool given chronic disease monitoring volumes, though pharmaceutical research applications are gaining share as contract research organizations scale bioanalytical services for biologic drug development.
FDA 510(k) clearance pathways and EUs In Vitro Diagnostic Regulation (IVDR) reclassification shape product development timelines and clinical evidence requirements for analyzer manufacturers seeking market access. ISO 15189 accreditation standards for medical laboratories directly influence instrument specification demands, particularly around traceability and quality control protocols. Stakeholders must monitor how evolving IVDR companion diagnostic rules and FDA software-as-medical-device guidance reshape analyzer-integrated algorithm validation requirements.
Market Dynamics
IVDR reclassification deadlines are forcing European diagnostic laboratories to accelerate analyzer replacements ahead of 2026 compliance windows, compressing procurement cycles and favoring vendors with validated quality management systems already in place.
Growth Catalysts
- Chronic disease surveillance mandates:Government screening programs for diabetes and cardiovascular conditions in India are expanding installed-base requirements in tier-two cities where BIS standards now mandate analyzer replacements.
- Modular microfluidics integration:Point-of-care configurations are capturing ambulatory settings previously served by central lab send-outs, enabling same-day therapeutic drug monitoring in oncology clinics.
- EU IVDR companion diagnostic rules:The expanded definition of in vitro diagnostic devices is creating pull-through demand for integrated analyzer-software platforms that can validate algorithm outputs as part of the device.
Market Restraints
- Reagent lock-in economics:Closed-system architectures tie operating costs to proprietary consumable pricing, limiting buyer leverage in contract negotiations with incumbent vendors.
- Optical component supply concentration:Photodetector and interference filter manufacturing clusters in East Asia create vulnerability to trade-route disruptions and export control friction.
- IVDR clinical evidence requirements:The expanded performance evaluation obligations for Class C and D devices are extending product development timelines and inflating regulatory submission costs.
Strategic Opportunities
- Veterinary diagnostic decentralization:Companion animal practice consolidation in the United States is creating demand for compact analyzers with species-specific reference ranges pre-loaded.
- AI-augmented result interpretation:Machine learning flagging of abnormal pattern clusters is enabling laboratory staffing models with reduced pathologist oversight during night shifts.
- Pharmaceutical bioanalytical services:Contract research organizations scaling biologic drug development are purchasing high-throughput systems for pharmacokinetic study support.
Industry Challenges
- ISO 15189 accreditation complexity:Medical laboratories pursuing international quality standards face multi-year implementation timelines for traceability and internal quality control protocol documentation.
- Legacy LIS integration:Hospital information system interoperability requirements are delaying analyzer deployments where middleware customization exceeds internal IT capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biochemistry Analyzers Market |
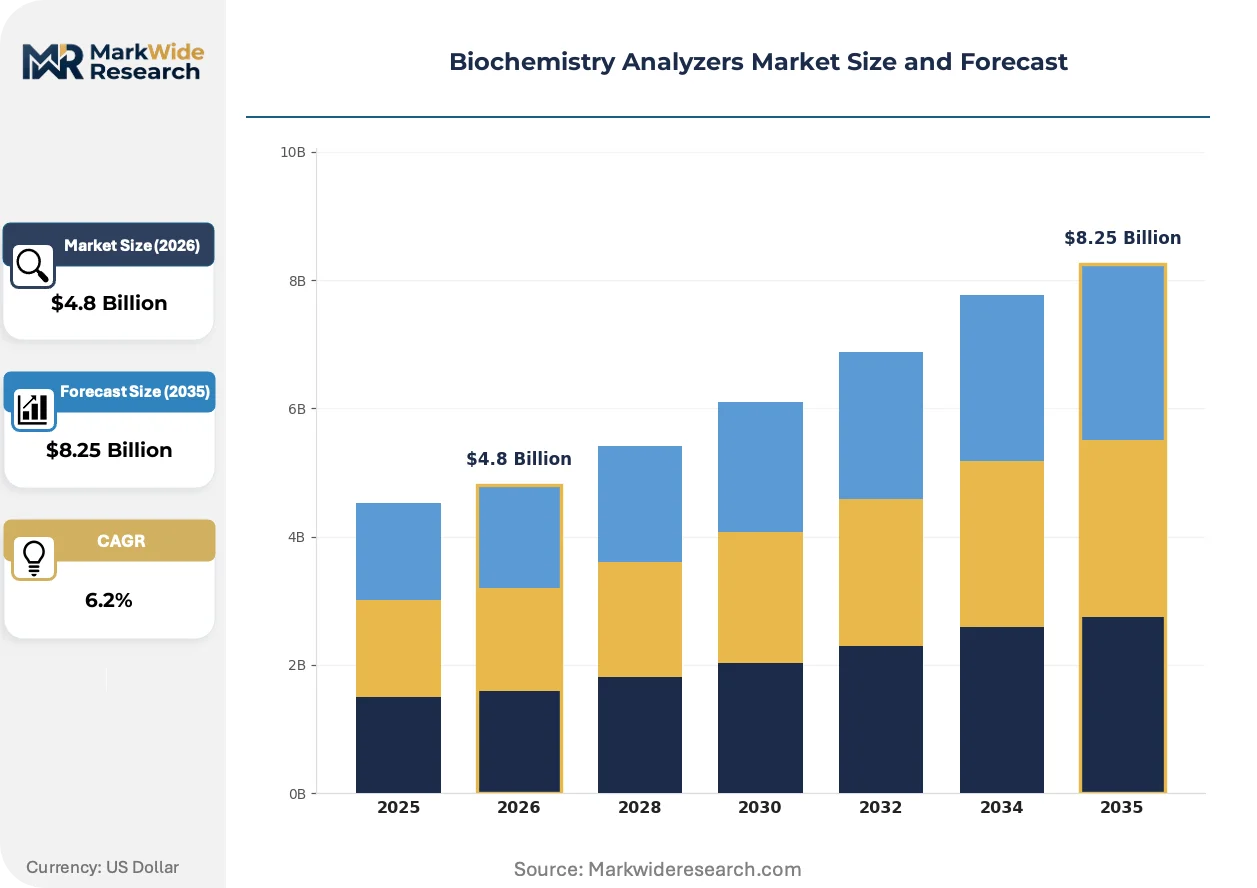
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automated, Fully Automated, Compact, Dry Chemistry, Clinical Chemistry Technology: Photometric, Electrochemical, Turbidimetric, Colorimetric, Immunoturbidimetric Application: Clinical Testing, Pharmaceutical Research, Veterinary Diagnostics, Food Safety, Environmental Testing End User: Diagnostic Laboratories, Research Institutions, Veterinary Clinics, Food Testing Labs, Environmental Agencies |
| Companies Covered | Danaher, Mindray, Roche Diagnostics, Hitachi High-Tech, Thermo Fisher Scientific, Siemens Healthineers, Beckman Coulter, Ortho Clinical Diagnostics, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biochemistry Analyzers Market Strategic Shifts & Innovations
Analyzer architectures are fragmenting across throughput tiers as vendor strategies diverge between defending high-volume hospital installations and capturing decentralized point-of-care expansion.
Microfluidic cartridge systems are collapsing the physical separation between sample preparation and reaction detection into single-use consumables. Community health centers in Brazil are adopting these platforms for hepatitis C screening campaigns. The consolidation of pre-analytical and analytical phases into disposable units is collapsing capital equipment requirements for resource-limited settings.
EU IVDR General Safety and Performance Requirements are mandating enhanced post-market surveillance and periodic safety update reporting for all analyzer classes. Manufacturers must now maintain clinical evidence portfolios throughout product lifecycles rather than at launch only. German notified bodies are experiencing backlog delays that are compressing market access timelines for mid-tier vendors.
Service contract unbundling is separating preventive maintenance, reagent supply, and software updates into independently negotiable components. Independent service organizations are capturing maintenance revenue previously held by original equipment manufacturers. This pattern is most visible in the United States where hospital procurement teams face pressure to reduce annual operating expenditure commitments.
Biochemistry Analyzers Market Segmentation
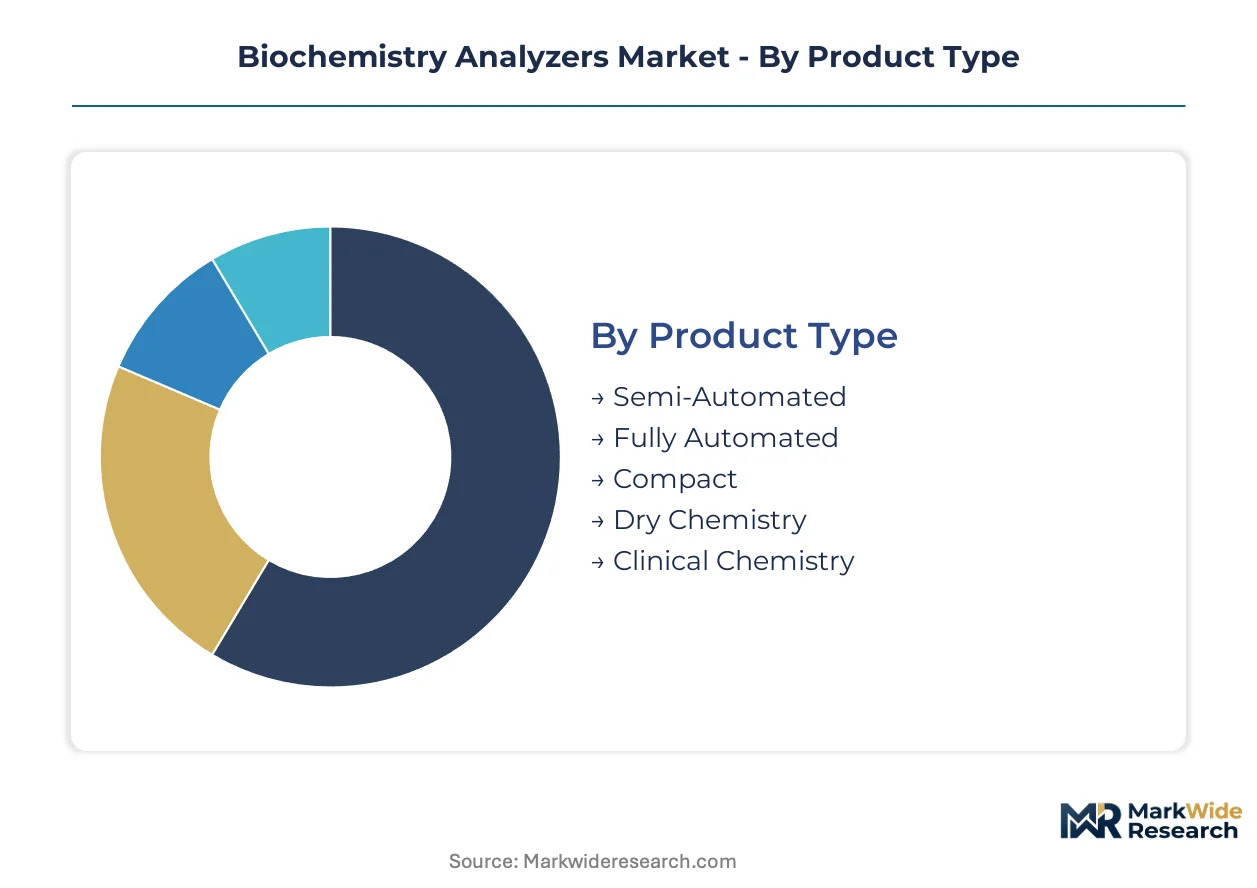
Segmentation in biochemistry analyzers reveals divergent equipment lifecycles and procurement patterns across healthcare infrastructure tiers. Understanding these divisions enables vendors to align product roadmaps with replacement velocities and compliance-driven upgrade windows.
Product Type:
Replacement cycles vary dramatically across automation tiers, with compact systems turning over fastest due to point-of-care obsolescence pressures while fully automated platforms persist through decade-long amortization schedules.
- Fully Automated:These systems integrate sample handling, reagent dispensing, and result reporting into walkaway workflows with throughput exceeding 800 tests per hour. German diagnostic laboratories are accelerating procurement ahead of EU IVDR deadlines, compressing typical seven-year replacement cycles into four-year windows for quality management system compliance.
- Compact:Portable units processing 50-200 tests per hour through cartridge-based microfluidics dominate decentralized deployment. Tier-two Indian cities are replacing legacy equipment under BIS standards mandates, driving fastest-in-category refresh rates as municipal health programs expand screening access.
- Semi-Automated:Operator-intermediate systems requiring manual sample and reagent loading serve budget-constrained settings with moderate throughput demands.
- Dry Chemistry:Reagent-free platforms using dry slide technology reduce cold-chain logistics burdens for field deployment and resource-limited environments.
- Clinical Chemistry:Dedicated analyzers for routine metabolic panels maintain installed bases through reagent contract lock-in economics.
Fully automated platforms anchor the volume base while compact configurations gain share at the steepest rate.
Technology:
Detection modality selection correlates directly with assay menu breadth and capital intensity, separating high-parameter hospital systems from single-analyte screening tools.
- Photometric:Spectrophotometric detection at 340-700 nm wavelengths quantifies enzyme kinetics and metabolite concentrations through absorbance measurement. This modality commands the largest installed base across clinical chemistry departments in developed health systems where multi-test panels justify equipment investment.
- Immunoturbidimetric:Light-scattering quantification of antigen-antibody complexes enables specific protein and therapeutic drug monitoring with minimal sample volume. Oncology clinics in the United States are adopting these systems for same-day pharmacokinetic feedback, displacing central lab send-out workflows.
- Electrochemical:Ion-selective electrode technology measures electrolyte concentrations through potentiometric response, dominating STAT testing applications.
- Turbidimetric:Nephelometric detection of particle aggregation supports coagulation and lipoprotein assays in medium-throughput laboratories.
- Colorimetric:Endpoint absorbance measurement for single-parameter tests persists in veterinary and food safety applications with limited assay menus.
Photometric systems retain the broadest installed footprint while immunoturbidimetric platforms are climbing the fastest amid precision medicine expansion.
Application:
End-use differentiation separates high-frequency chronic disease monitoring from episodic regulatory compliance testing, with divergent sensitivity to reimbursement and capital budget cycles.
- Clinical Testing:Routine diagnostic panels for diabetes, cardiovascular risk, and organ function assessment generate recurring revenue through high test volumes. India's government screening mandates are expanding analyzer deployments in district hospitals and municipal health centers previously reliant on reference laboratory outsourcing.
- Pharmaceutical Research:Bioanalytical method development and pharmacokinetic studies for biologic drug candidates require specialized high-sensitivity detection. Contract research organizations scaling biologic development pipelines are purchasing dedicated systems to capture sponsor study volume.
- Veterinary Diagnostics:Companion animal and livestock health monitoring drives demand for species-specific reference ranges and compact footprints.
- Food Safety:Contaminant and nutritional label verification testing supports regulatory compliance in commercial laboratory networks.
- Environmental Testing:Water quality and soil contaminant analysis applications serve agency and industrial monitoring programs with seasonal demand patterns.
Clinical testing anchors procurement volume while pharmaceutical research applications are expanding most quickly through CRO infrastructure investment.
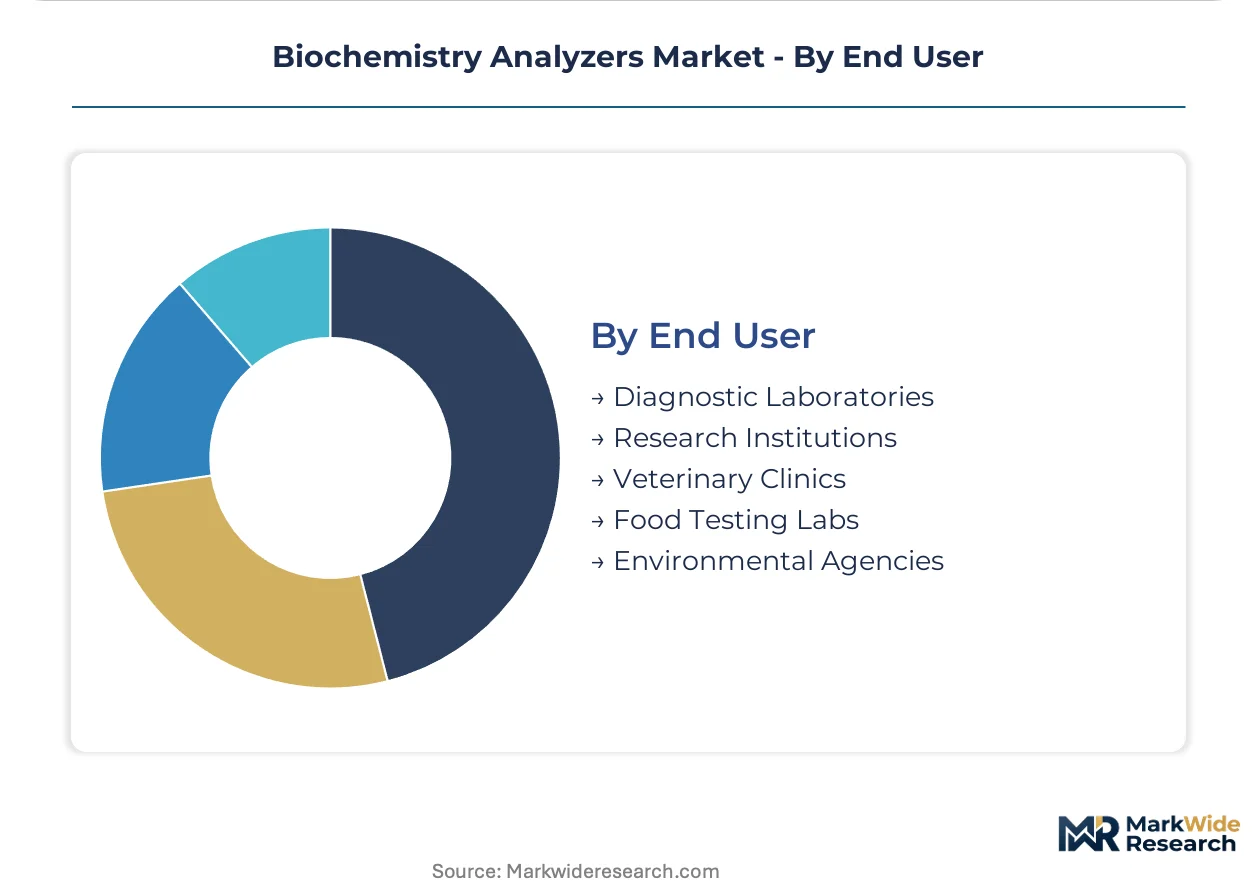
End User:
Customer type determines purchasing authority structure, with centralized laboratory networks negotiating enterprise contracts while decentralized clinics prioritize single-source simplicity over price optimization.
- Diagnostic Laboratories:High-throughput facilities processing thousands of samples daily drive demand for integrated pre-analytical modules and automated quality control. EU IVDR compliance deadlines are forcing accelerated procurement timelines as notified body backlogs compress market access windows for non-validated equipment.
- Veterinary Clinics:Consolidated companion animal practice chains in the United States are standardizing on compact analyzers with pre-loaded species-specific reference ranges to reduce specialist consultation delays.
- Research Institutions:Academic and government laboratories prioritize open-system architectures enabling custom assay development.
- Food Testing Labs:Commercial analytical services supporting manufacturer compliance require multi-parameter flexibility for diverse regulatory jurisdictions.
- Environmental Agencies:Government monitoring programs deploy field-portable systems for remote sampling locations with intermittent power availability.
Diagnostic laboratories dominate capital deployment while veterinary clinics are gaining share fastest through practice consolidation and in-house testing migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories and hospital systems concentrate procurement authority in Germany, India, and the United States, where regulatory deadlines and chronic disease screening programs are compressing replacement cycles. Tier-two cities and decentralized clinics in emerging health systems are capturing fastest deployment velocity.
Germany
Diagnostic laboratories in Bavaria and North Rhine-Westphalia are accelerating fully automated system procurement ahead of EU IVDR compliance deadlines. Notified body backlogs are compressing market access timelines, favoring vendors with pre-validated quality management systems. The Munich-Stuttgart corridor hosts concentrated vendor service infrastructure supporting rapid installation turnaround.
India
Government diabetes and cardiovascular screening mandates are expanding analyzer deployments in district hospitals across Maharashtra and Karnataka. BIS standards and CDSCO quality mandates are accelerating equipment replacements in tier-two cities previously reliant on reference laboratory outsourcing. The Hyderabad-Chennai corridor is capturing fastest refresh rates as municipal health programs scale access.
United States
Consolidated companion animal practice chains are standardizing compact analyzers with species-specific reference ranges to reduce specialist consultation delays. FDA 510(k) clearance pathways shape product development timelines for algorithm-integrated platforms. The Boston-San Diego biotech corridor drives pharmaceutical research demand through contract research organization infrastructure expansion.
China
Domestic manufacturers are capturing share in decentralized clinical testing as NMPA regulatory pathways mature for Class II diagnostic devices. Yangtze River Delta hospital networks are prioritizing open-system architectures enabling custom assay development. The Shanghai-Suzhou cluster concentrates photodetector component manufacturing critical to analyzer supply chains.
Brazil
Community health centers in São Paulo and Minas Gerais are adopting microfluidic cartridge platforms for hepatitis C screening campaigns. ANVISA regulatory harmonization with Mercosur standards is streamlining import pathways for compact systems. The São Paulo-Campinas corridor anchors Latin American distribution infrastructure for regional service coverage.
Biochemistry Analyzers Market Key Industry Players
Channel-controlling players compete with product-specialist players across automation tiers, creating a tiered structure where scale advantages concentrate in high-throughput hospital installations while point-of-care niches fragment across regional specialists. The market exhibits three strategic archetypes: integrated diagnostics conglomerates defending installed-base loyalty through reagent lock-in, mid-tier automation specialists capturing IVDR-driven replacement cycles, and emerging microfluidics innovators collapsing capital requirements for decentralized settings. Dominant competitive moves include M&A activity targeting complementary assay menus and strategic partnerships with contract research organizations for pharmaceutical bioanalytical service expansion.
Among integrated diagnostics conglomerates, Danaher and Roche Diagnostics exemplify channel-control strategies through reagent-cartridge architectures and automated pre-analytical modules respectively. Siemens Healthineers occupies a position on the AI-augmented interpretation vector, representing the algorithm-integrated platform archetype. These three companies anchor the premium-tier competitive set where installed-base loyalty and regulatory validation depth determine procurement outcomes in European and North American hospital networks.
| Leading Market Players |
|---|
| Danaher |
| Mindray |
| Roche Diagnostics |
| Hitachi High-Tech |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Beckman Coulter |
| Ortho Clinical Diagnostics |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Single-source photodetector dependency from East Asian manufacturing clusters determines both the premium-to-economy pricing spread and the geographic shape of analyzer supply chains, compressing margins when export controls disrupt optical component flows while inflating tier spreads for vendors with validated alternative sourcing.
Pricing Analysis
Cost-plus contracts with reagent indexation dominate analyzer procurement, locking hospital laboratories into multi-year commitments where proprietary consumable pricing escalates at predetermined intervals. Pricing stratifies across fully automated, compact, and semi-automated tiers based on throughput certification and IVDR validation status, with German diagnostic laboratories showing lowest price sensitivity due to compliance-driven urgency while tier-two Indian cities negotiate aggressively on capital equipment. Cost compression in compact analyzer segments is intensifying as domestic Chinese manufacturers enter decentralized clinical testing markets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for analyzer manufacturers dependent on Yangtze River Delta photodetector and interference filter production. Component sourcing draws from China, Japan, and Germany for optical subsystems, precision pumps, and reaction cuvettes, with single-source vulnerability concentrated in photodetector manufacturing. Distribution runs through authorized dealer networks serving hospital systems and direct procurement channels for diagnostic laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analyzer incumbents face substitution pressure from microfluidic point-of-care platforms collapsing capital requirements for decentralized settings, requiring defensive repositioning around reagent lock-in and regulatory validation depth.
For Market Incumbents: Harden installed-base loyalty through backward integration into reagent-cartridge manufacturing, capturing consumable revenue streams that resist price negotiation. Prioritize IVDR pre-validation investments to compress procurement cycles for European diagnostic laboratories facing notified body backlogs. Defend against microfluidic substitution by embedding AI-augmented interpretation modules that require centralized algorithm validation.
For New Entrants and Emerging Players: Pursue veterinary diagnostic decentralization in consolidated companion animal practice chains, where species-specific reference range pre-loading commands premium positioning. Target tier-two Indian cities under BIS replacement mandates for compact analyzer deployment through municipal health program partnerships. Lead with disposable cartridge economics that eliminate cold-chain logistics burdens for field deployment.
For Investors and Strategic Acquirers: Mid-tier automation specialists with validated EU quality management systems represent the most defensible acquisition profile, capturing IVDR-driven replacement cycles without conglomerate complexity. Long-term viability hinges on algorithm-integrated platform differentiation rather than hardware commoditization. Watch for FDA software-as-medical-device guidance enforcement as inflection indicator for valuation multiples on AI-augmented interpretation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Pre-Validation Investment | Compresses market access timelines for German diagnostic laboratories facing notified body capacity constraints. |
| Reagent-Cartridge Backward Integration | Captures consumable revenue streams that resist hospital procurement team price pressure. |
| AI-Augmented Interpretation Development | Flags abnormal pattern clusters before clinician review, reducing laboratory staffing costs. |
| Veterinary Reference Range Pre-Loading | Reduces specialist consultation delays in consolidated companion animal practice chains. |
| Microfluidic Cartridge Platform Launch | Collapses capital equipment requirements for hepatitis C screening campaigns in Brazilian community health centers. |
Research Approach
A standing panel of hospital laboratory directors, diagnostic procurement managers, biomedical engineers, and GPO contracts specialists provided ongoing calibration against operating reality throughout the study period. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EU IVDR notified body documentation, BIS certification records, and hospital procurement database analysis. Bottom-up equipment deployment tracking triangulated against top-down vendor revenue segmentation.
Scenario-bracketing around IVDR implementation delays and microfluidic adoption curves shaped the analytical framework across the analysis window. Segmentation modeling incorporated automation tier, detection modality, application type, and end-user purchasing authority structure. CAGRs derived from replacement cycle compression in compliance-driven markets and expansion velocity in decentralized settings, with inputs from chronic disease screening program budgets and CRO bioanalytical service expansion.
Sensitivities concentrate around notified body backlog resolution timelines, export control friction on optical components, and FDA software-as-medical-device guidance enforcement. Forecasts reflect documented assumptions on replacement velocity and regulatory compliance deadlines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market