
 Asia-Pacific Regenerative Medicine Market | 2026-2036
Asia-Pacific Regenerative Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Regenerative Medicine Market Outlook
Project finance for cell therapy manufacturing facilities is narrowing the competitive field to well-capitalized operators. Takeda Pharmaceutical Company Limited leverages its Osaka-based biomanufacturing footprint to anchor regional supply. Mesoblast Ltd. competes through proprietary allogeneic cell platforms. Astellas Pharma Inc. specializes in induced pluripotent stem cell pipelines.
Regenerative medicine encompasses therapeutic approaches that repair, replace, or regenerate human cells, tissues, or organs through biologically active scaffolds, genetically modified cells, or stem cell-derived products manufactured under GMP conditions with defined purity thresholds. Cell therapy leads current revenue contribution due to established reimbursement in oncology and musculoskeletal conditions. Gene therapy represents the fastest-expanding segment as CRISPR-based protocols advance through clinical validation. Tissue engineering commands premium pricing where scaffold technology integrates with autologous cell harvesting.
Japan's PMDA operates the world's first conditional accelerated approval framework for regenerative products, compressing commercialization timelines. Australia's TGA aligns with ISO 14155 for clinical investigations while India's CDSCO enforces BIS standards for imported biologics. South Korea's MFDS maintains separate review tracks for cell and gene therapies. Stakeholders must monitor how reimbursement negotiations in Australia and Japan reshape accessible patient volumes versus premium pricing sustainability.
Market Dynamics
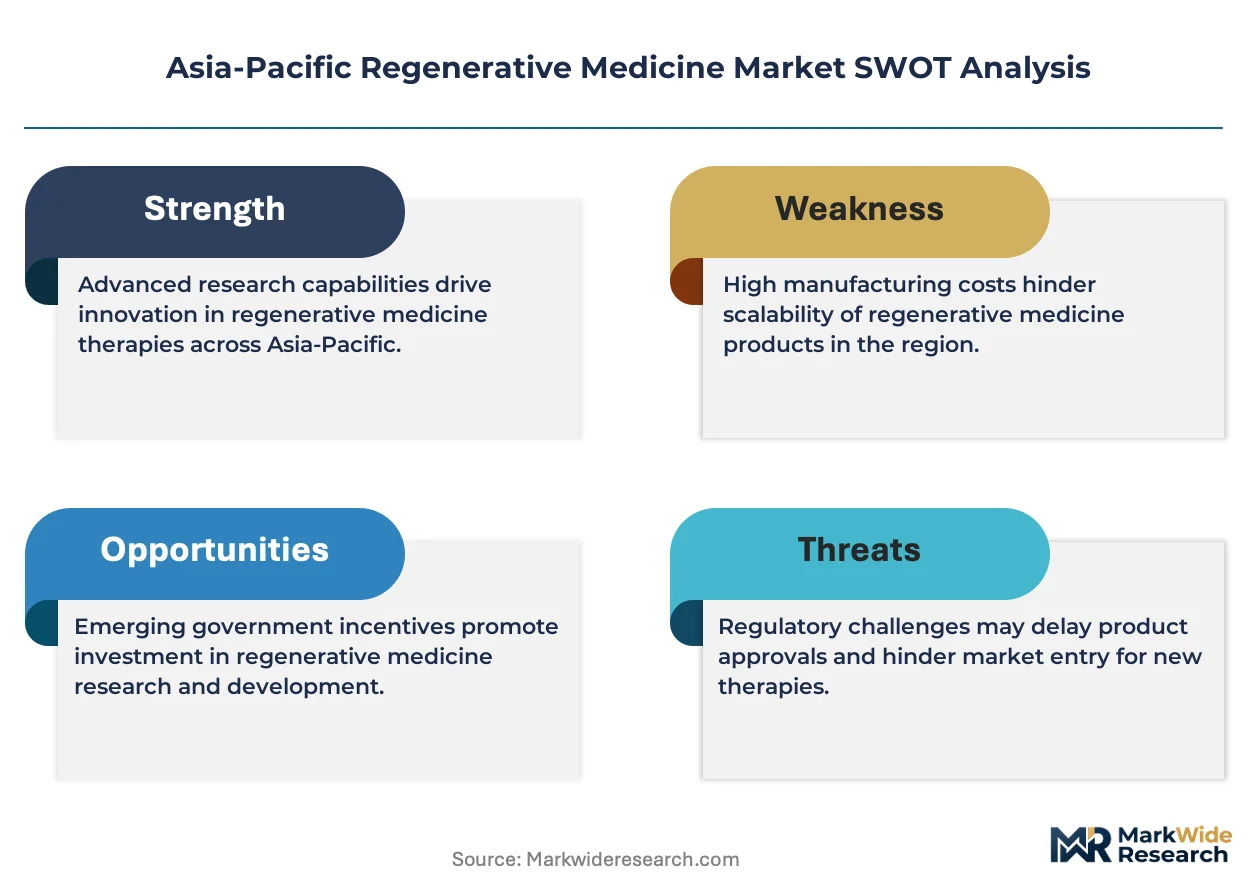
Japan's PMDA conditional accelerated approval framework compresses commercialization timelines, forcing competitors to front-load manufacturing capacity before clinical completion.
Growth Catalysts
- Conditional Approval Frameworks:Japan's Act on Regenerative Medicine Safety compresses review timelines for cell therapies. PMDA's Sakigake designation grants priority review to regenerative products.
- Biocluster Infrastructure:Kansai's regenerative medicine corridor attracts manufacturing investment through METI subsidies. Osaka anchors cell therapy production with dedicated GMP facilities.
- Reimbursement Expansion:Australia's Medical Services Advisory Committee approves coverage for autologous cell therapies. Melbourne's biomedical precinct benefits from aligned public hospital procurement.
Market Restraints
- Plasma Supply Concentration:Australia and New Zealand dominate regional human serum albumin sourcing. Single-source dependency creates batch-to-batch variability risks for cell culture media.
- Cleanroom Construction Costs:ISO 14644-1 Grade B facility builds in Japan exceed standard pharmaceutical capex by 40%. Limited specialized contractors extend commissioning timelines.
- Vector Manufacturing Bottlenecks:Lentiviral and AAV production concentrates in South Korean CDMOs. Capacity constraints delay gene therapy IND submissions across the region.
Strategic Opportunities
- India's CDSCO Pathway Expansion:BIS standards harmonization for imported biologics opens manufacturing partnerships. Mumbai and Hyderabad bioclusters seek GMP-aligned cell therapy infrastructure.
- iPSC Banking Networks:Allogeneic stem cell repositories reduce per-patient manufacturing costs. Academic medical centers in Singapore and Japan pilot HLA-matched master cell banks.
- Digital Twin Integration:Process analytical technology combined with AI-driven quality prediction virtualizes batch release decisions. South Korean MFDS pilots real-time manufacturing oversight protocols.
Industry Challenges
- Cell Therapy Logistics:Cryogenic chain integrity failures exceed 2% in Southeast Asian distribution networks. Cold box validation gaps between manufacturing sites and infusion centers compromise potency.
- GMP Auditor Scarcity:PMDA and MFDS-qualified inspectors command premium consulting rates. Sponsor companies face 6-month delays for pre-approval facility inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Regenerative Medicine Market |
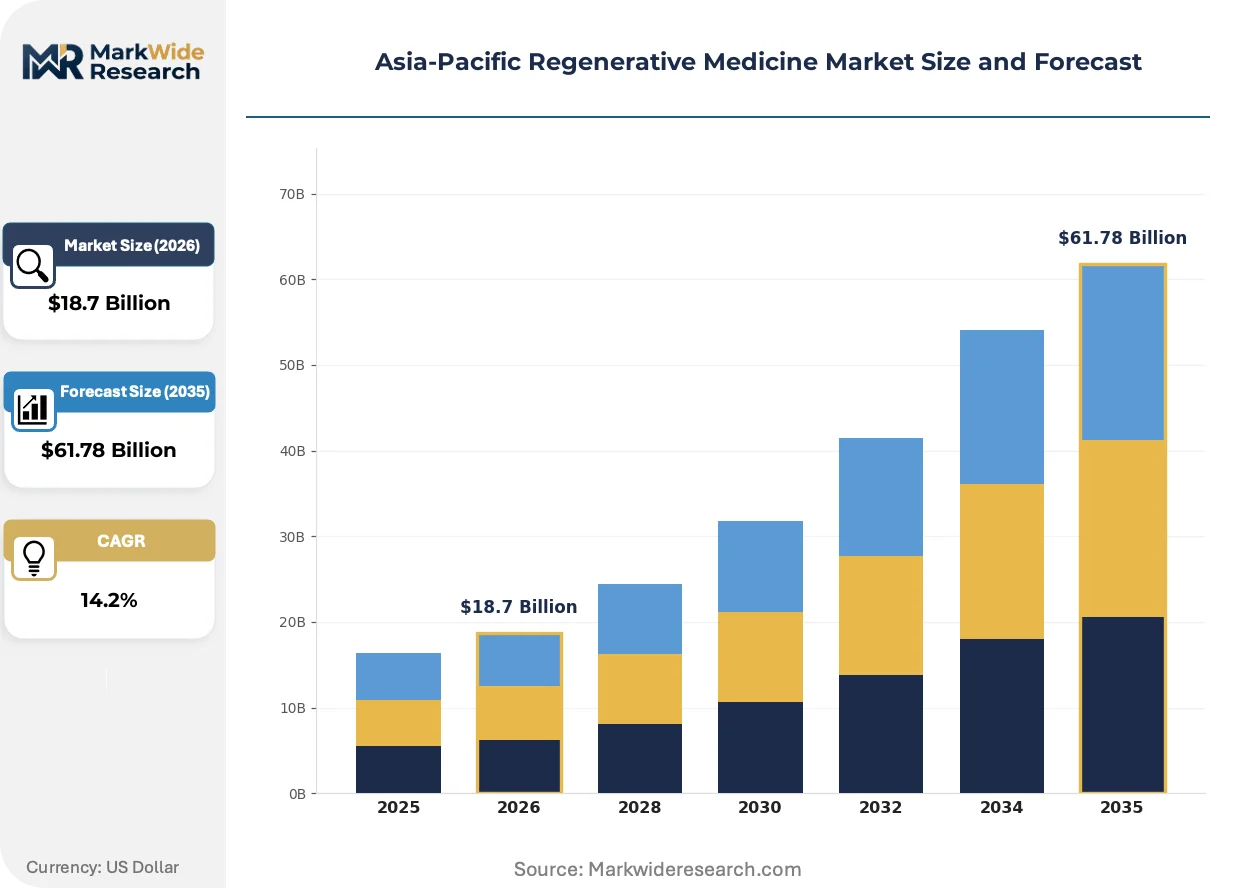
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Therapy, Gene Therapy, Tissue Engineering, Stem Cell Products Application: Orthopedics, Cardiology, Neurology, Wound Healing End User: Hospitals, Research Institutes, Specialty Clinics, Pharmaceutical Companies Technology: 3D Bioprinting, Scaffold Technology, CRISPR, Cell Culture |
| Companies Covered | Takeda Pharmaceutical Company Limited, Astellas Pharma Inc., JCR Pharmaceuticals Co., Ltd., Medtronic PLC, Cook Group Incorporated, Integra LifeSciences Corporation, Smith & Nephew plc, AbbVie, Mesoblast Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Regenerative Medicine Market Strategic Shifts
Digital infrastructure is compressing development timelines across cell and gene therapy workflows. Three convergent forces reshape competitive positioning: computational biology tools, adaptive regulatory frameworks, and decentralized manufacturing models.
Process analytical technology is virtualizing quality control decision-making in cell therapy manufacturing. Japanese biomanufacturers deploy inline Raman spectroscopy and machine learning algorithms for real-time culture monitoring. PMDA's quality-by-design pilot program accepts digital batch records as primary evidence. This compression eliminates traditional 14-day hold periods for sterility testing.
South Korea's MFDS operates parallel review tracks distinguishing cell therapies from gene-modified products. The regulator mandates separate CMC modules for allogeneic versus autologous manufacturing. Singapore's Health Sciences Authority mirrors this bifurcation, accelerating timelines for standardized off-the-shelf products. CDMOs in Songdo and Tuas reconfigure facility layouts to handle dual modality production.
Hospital procurement departments consolidate supplier relationships around integrated service agreements. Australia's public hospital networks bundle cell processing, logistics, and infusion services under single-source contracts. Melbourne's Peter MacCallum Cancer Centre and Royal Melbourne Hospital coordinate volume commitments to secure manufacturing slots. This concentration displaces transactional purchasing of individual therapy doses.
Asia-Pacific Regenerative Medicine Market Segmentation
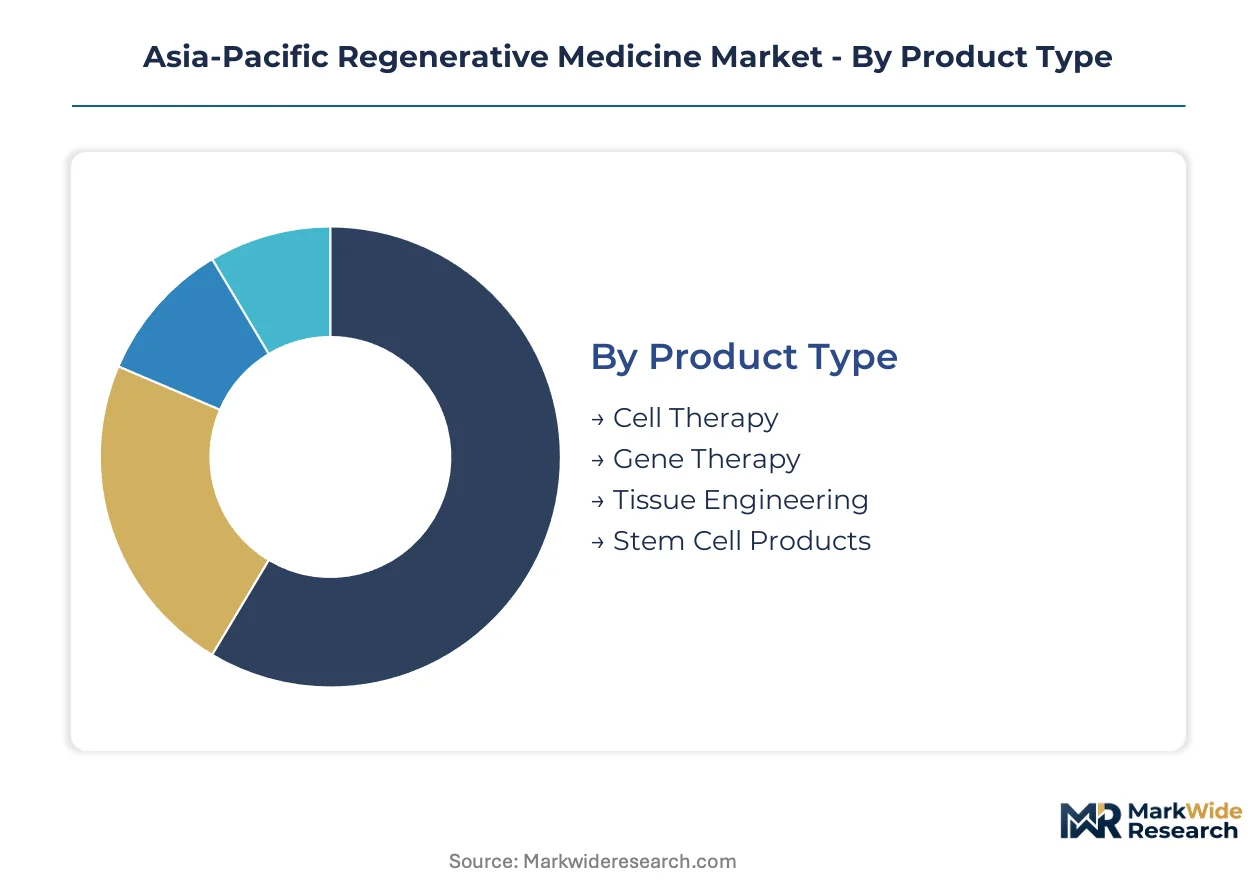
Regenerative medicine segments in Asia-Pacific diverge sharply in manufacturing complexity and post-commercialization service requirements. Cell therapy demands cryogenic logistics networks and patient-specific manufacturing support that reshape competitive economics across each segment boundary.
Product Type:
After-sales service intensity varies dramatically across product categories, with autologous therapies requiring per-patient manufacturing coordination while allogeneic platforms scale through centralized banking.
- Cell Therapy:Autologous and allogeneic cellular products manufactured under GMP conditions with defined potency assays. Japan's PMDA conditional approval pathway compresses timelines for CAR-T and MSC therapies, concentrating demand in Osaka's manufacturing corridor. Cold chain integrity requirements exceed standard biologics by an order of magnitude.
- Gene Therapy:Viral vector-delivered genetic modifications including CRISPR-based protocols and lentiviral gene transfers. South Korean CDMOs anchor regional AAV production capacity, though manufacturing bottlenecks delay IND submissions across Australia and Southeast Asia.
- Tissue Engineering:Biologically active scaffolds integrated with autologous cell harvesting command premium pricing in orthopedic applications.
- Stem Cell Products:iPSC-derived and embryonic stem cell therapies leverage master cell bank architectures to reduce per-patient costs.
Cell therapy holds the largest share; momentum sits with gene therapy as vector manufacturing capacity expands.
Application:
Clinical adoption patterns track reimbursement decisions by national health technology assessment bodies, with musculoskeletal and oncology indications securing earlier coverage.
- Orthopedics:Scaffold-based bone and cartilage regeneration integrates with autologous chondrocyte implantation protocols. Australia's MSAC approval for autologous cell therapies in knee osteoarthritis concentrates procedure volumes in Melbourne's public hospital networks.
- Cardiology:Cardiac cell therapy and tissue-engineered vascular grafts target ischemic heart failure and congenital defects. Japan's Sakigake designation prioritizes regenerative cardiac products, accelerating PMDA review timelines for iPSC-derived cardiomyocyte therapies.
- Neurology:Cell and gene therapies for Parkinson's disease and spinal cord injury remain in advanced clinical development with limited commercial penetration.
- Wound Healing:Chronic diabetic ulcer treatments using epidermal autografts and dermal substitutes address aging population demand in Japan and South Korea.
Orthopedics dominates current revenue; neurology represents the steepest expansion trajectory pending pivotal trial readouts.
End User:
Procurement concentration reshapes supplier relationships, with integrated service agreements displacing transactional dose purchasing across major health systems.
- Hospitals:Tertiary academic medical centers anchor cell therapy infusion capacity with embedded apheresis and cryostorage facilities. South Korean and Japanese hospital systems expand dedicated regenerative medicine units through METI and MFDS-aligned infrastructure subsidies.
- Research Institutes:Academic medical centers pilot HLA-matched master cell banks and iPSC repository networks. Singapore's Agency for Science, Technology and Research coordinates national banking initiatives to reduce allogeneic therapy manufacturing costs.
- Specialty Clinics:Focused orthopedic and aesthetic medicine practices concentrate autologous fat-derived cell processing in Australia's private sector.
- Pharmaceutical Companies:Sponsor organizations internalize early-phase manufacturing through captive GMP facilities or dedicated CDMO partnerships.
Hospitals command the dominant share; research institutes are gaining share fastest through iPSC banking infrastructure investment.
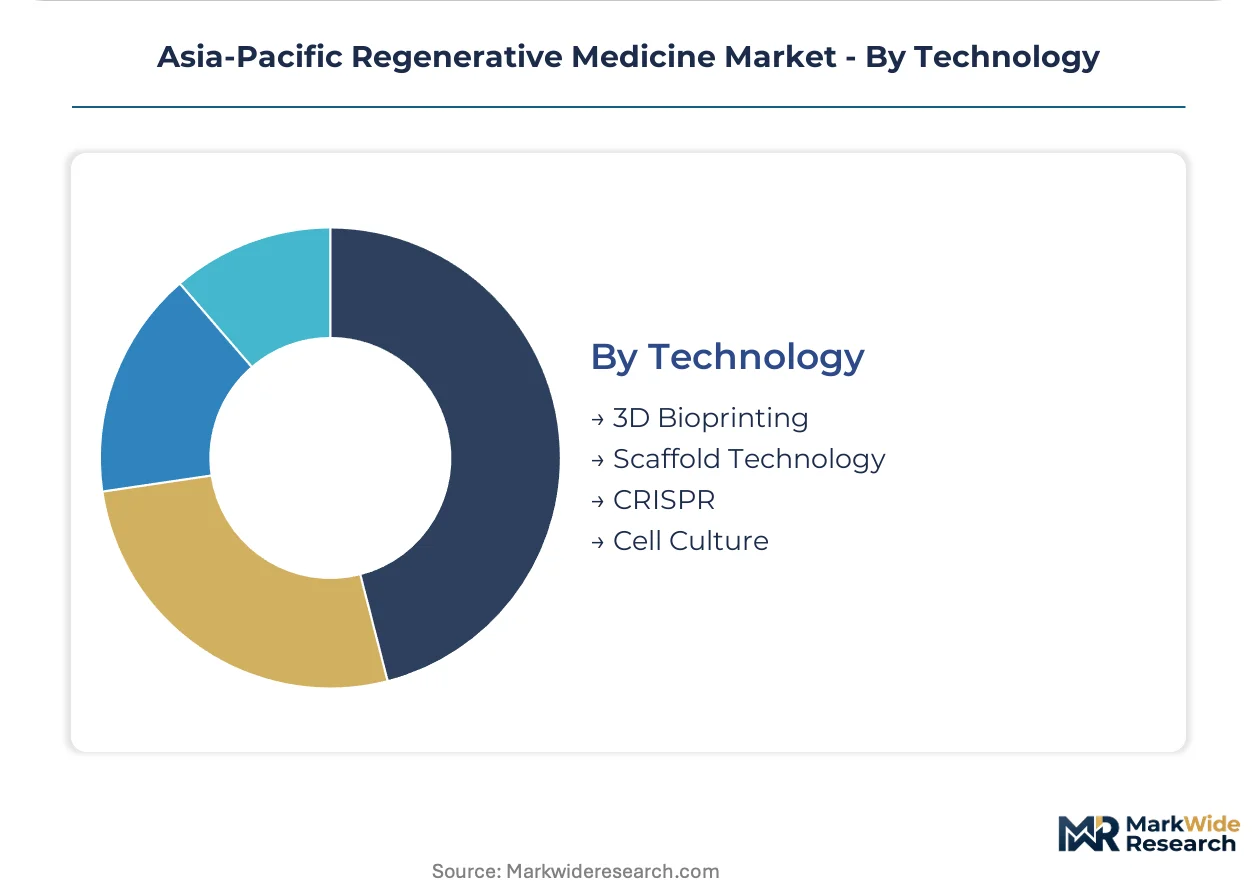
Technology:
Process analytical technology and digital infrastructure compress quality control timelines, with inline monitoring systems eliminating traditional batch hold periods.
- 3D Bioprinting:Extrusion and laser-based additive manufacturing of cell-laden hydrogels for tissue constructs. South Korean manufacturers deploy digital twin integration for real-time print monitoring under MFDS pilot oversight protocols.
- Scaffold Technology:Decellularized matrices and synthetic biodegradable polymers provide structural templates for cell infiltration. Japanese biomanufacturers combine scaffold products with autologous harvesting systems to secure premium positioning.
- CRISPR:Gene editing protocols advance through clinical validation for ex vivo cell modification, with TGA-aligned ISO 14155 investigations proceeding in Australia.
- Cell Culture:Suspension and adherent bioreactor systems for expansion of therapeutic cell populations remain foundational across all product categories.
Cell culture underpins current manufacturing; 3D bioprinting is climbing the fastest as regulatory frameworks mature for printed tissue products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japan's conditional approval corridors while Australian procurement consolidation compresses margins for standard therapies. Manufacturing capex requirements widen the competitive moat between these two demand centers.
Japan
Conditional accelerated approval under PMDA's Sakigake designation compresses commercialization timelines for iPSC-derived therapies. The Act on Regenerative Medicine Safety mandates structured safety reporting that foreign sponsors navigate through Osaka-based regulatory consultants. Kansai's regenerative medicine corridor anchors cell therapy production with METI-subsidized GMP facilities in Osaka and Kobe.
South Korea
MFDS operates parallel review tracks that distinguish cell therapies from gene-modified products, accelerating timelines for standardized allogeneic platforms. The regulator mandates separate CMC modules for autologous versus allogeneic manufacturing. Songdo's biocluster concentrates lentiviral and AAV production capacity, though vector manufacturing bottlenecks delay regional IND submissions.
Australia
Medical Services Advisory Committee approvals for autologous cell therapies in knee osteoarthritis concentrate procedure volumes in public hospital networks. TGA alignment with ISO 14155 streamlines clinical investigation protocols for imported biologics. Melbourne's biomedical precinct bundles cell processing, logistics, and infusion services under single-source procurement contracts with Peter MacCallum Cancer Centre and Royal Melbourne Hospital.
Singapore
Health Sciences Authority bifurcation of review tracks accelerates timelines for off-the-shelf allogeneic products versus patient-specific autologous therapies. The Agency for Science, Technology and Research coordinates national iPSC banking initiatives to reduce per-patient manufacturing costs. Tuas biomedical hub reconfigures facility layouts for dual-modality cell and gene therapy production under real-time manufacturing oversight pilots.
India
CDSCO enforcement of BIS standards for imported biologics opens manufacturing partnerships for GMP-aligned cell therapy infrastructure. Mumbai and Hyderabad bioclusters seek foreign technology licensing to bridge cleanroom construction capability gaps. Domestic plasma supply concentration creates batch-to-batch variability risks for cell culture media that importers manage through New Zealand sourcing agreements.
Asia-Pacific Regenerative Medicine Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying scaffold materials, viral vectors, and cryogenic logistics. The vendor base stratifies between diversified pharmaceutical conglomerates with captive manufacturing and pure-play regenerative medicine developers dependent on CDMO partnerships. Three archetypes dominate: Osaka-based biomanufacturing anchors, Australian hospital-integrated service providers, and South Korean vector production specialists. Competitive moves concentrate on manufacturing capacity pre-commitment ahead of clinical completion and iPSC master cell bank licensing to reduce per-patient costs.
Among Japan-based pharmaceutical conglomerates, Takeda Pharmaceutical Company Limited and Astellas Pharma Inc. occupy positions as platform integrators with biomanufacturing footprints. Mesoblast Ltd. exemplifies the pure-play archetype with proprietary allogeneic cell platforms. These three entities represent the competitive spectrum from diversified pharmaceutical scale to focused regenerative medicine specialization.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Astellas Pharma Inc. |
| JCR Pharmaceuticals Co., Ltd. |
| Medtronic PLC |
| Cook Group Incorporated |
| Integra LifeSciences Corporation |
| Smith & Nephew plc |
| AbbVie |
| Mesoblast Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in South Korean lentiviral vector production drives CDMOs to prioritize contracted sponsors over spot buyers, compressing margins for developers without pre-committed manufacturing slots while inflating premiums for guaranteed capacity.
Pricing Analysis
The customization-premium spread between patient-specific autologous therapies and standardized allogeneic platforms exceeds threefold in Japan's PMDA-approved products. Pricing stratifies across premium, standard, and economy tiers based on manufacturing complexity and cold chain requirements. Cost compression in autologous cell processing is intensifying because Australian hospital procurement consolidation favors bundled service agreements over per-dose purchasing. Academic medical centers exhibit lowest price sensitivity due to conditional approval premiums, while private specialty clinics face acute margin pressure from reimbursement caps.
Supply Chain Analysis
Contract manufacturing concentrates at South Korean CDMOs in Songdo for AAV and lentiviral vectors, Japanese GMP facilities in Osaka for cell therapy expansion, and Singapore's Tuas hub for dual-modality production. Raw material dependencies include human serum albumin from Australia and New Zealand, GMP-grade cytokines from Japanese suppliers, and cryopreservation media from specialized chemical manufacturers. Single-source vulnerability in plasma-derived culture components creates batch-to-batch variability risks. Distribution runs through validated cold chain networks with cryogenic monitoring from manufacturing sites to hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through PMDA conditional approval pathways creates sticky relationships between approved sponsors and manufacturing capacity holders.
For Market Incumbents: Pre-empt emerging allogeneic platform competitors by securing exclusive master cell bank licensing from Japanese academic medical centers. Deepen backward integration into viral vector production through dedicated capacity builds in South Korea's Songdo biocluster. Lock in Australian hospital procurement committees with decade-long integrated service agreements before MSAC reimbursement expansion attracts new entrants.
For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-aligned manufacturing partnerships where GMP infrastructure gaps create first-mover advantages for foreign technology licensors. Target Mumbai and Hyderabad bioclusters with turnkey cleanroom construction capabilities. Penetrate through iPSC banking network pilots that reduce per-patient costs below autologous benchmarks.
For Investors and Strategic Acquirers: Long-term, this sits as a platform-royalty play because conditional approval frameworks generate recurring revenue streams from approved products with compressed generic competition timelines. Prioritize acquisition targets with captive GMP facilities in Kansai or Osaka corridors. Monitor PMDA Sakigake designation grants as inflection indicators for manufacturing capacity pre-commitment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Osaka-based GMP expansion anchors regional cell therapy supply security under METI subsidy frameworks. |
| Regulatory Approval Pathway | PMDA Sakigake designation compresses commercialization timelines for iPSC-derived cardiovascular therapies. |
| Licensing Agreement | Master cell bank partnerships with Singapore's A*STAR reduce allogeneic manufacturing cost structures. |
| Clinical Trial Advancement | MFDS-aligned digital twin protocols accelerate gene therapy IND submissions through real-time quality oversight. |
| Pipeline Diversification | CRISPR-based ex vivo protocols target neurology indications with steepest expansion trajectories pending pivotal readouts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across cell therapy development executives, PMDA regulatory consultants, Australian hospital procurement managers, and CDMO facility directors. Secondary validation drew from PMDA approval databases, MFDS manufacturing oversight protocols, ClinicalTrials.gov regenerative medicine entries, and Australian MSAC reimbursement determinations. Bottom-up patient volume modeling triangulated against top-down market sizing across the analysis window.
Calibration anchored historical capacity utilization rates at South Korean and Japanese manufacturing facilities against projected therapy approvals. Segmentation dimensions spanned product type, application, end user, and technology platform across the projection horizon. CAGRs derived from weighted average of clinician adoption curves, reimbursement expansion timelines, and manufacturing capacity buildout schedules. Industry-specific inputs included cold chain logistics cost trajectories and GMP auditor availability constraints.
Sensitivities concentrate around PMDA conditional approval revocation rates, MFDS manufacturing inspection backlogs, and Australian hospital procurement consolidation pace. Forecasts embed assumptions on iPSC banking network proliferation and vector manufacturing capacity expansion. Quarterly review of Sakigake designation grants, MSAC coverage decisions, and CDSCO pathway harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Bioelectric Medicine Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Mesotherapy Guns Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Tumour-Induced Osteomalacia Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Artificial Blood Market
Regenerative Medicine
Atrophic Scar Treatment Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
Cell Damage & Repair Market