
 Europe Longevity and Anti-Senescence Therapy Market | 2026-2036
Europe Longevity and Anti-Senescence Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Longevity and Anti-Senescence Therapy Market Analytics
The European longevity therapy sector is pivoting between premium-priced gene therapies and commodity nutraceutical formulations. Juvenescence Ltd. leverages its portfolio breadth across both tiers, while Unity Biotechnology specializes in senolytic drug development with concentrated R&D operations. Calico Life Sciences anchors its European presence through deep capital reserves and long-horizon research programs.
Longevity and anti-senescence therapy encompasses pharmacological and biological interventions designed to delay, prevent, or reverse cellular senescence through mechanisms including telomere maintenance, senolytic clearance, and epigenetic reprogramming. These therapies target the accumulation of senescent cells that drive systemic inflammation and tissue dysfunction in age-related conditions. Gene therapies command the highest development investment due to their curative potential and complex manufacturing requirements. Stem cell technology segments attract significant academic-industrial collaboration, while senolytics represent the most clinically advanced category with multiple candidates in Phase II trials across European sites.
The EMA's advanced therapy medicinal products framework and the EU Clinical Trials Regulation govern development pathways, with national competent authorities in Germany, France, and Spain conducting parallel scientific advice. REACH compliance shapes sourcing requirements for novel chemical entities, while GDPR provisions constrain patient data utilization in real-world evidence generation. Stakeholders must monitor EMA qualification opinion trends for biomarker acceptance and adaptive licensing structures.
Market Dynamics
The European longevity therapy market pivots on EMA's adaptive licensing pathways for advanced therapy medicinal products, which compress development timelines for senolytic candidates while fragmenting national reimbursement negotiations across member states.
Growth Catalysts
- EU Clinical Trials Regulation:Harmonized submission procedures accelerate multi-site senolytic studies across Germany, France, and Spain, reducing protocol approval delays by consolidating national competent authority reviews.
- University hospital consortia:German academic medical centers anchor regenerative medicine demand through dedicated aging research institutes that procure gene therapy vectors and stem cell platforms at scale.
- Biomarker qualification opinions:EMA's emerging acceptance of p16INK4a and senescence-associated secretory phenotype markers enables surrogate endpoints in Phase II trials, de-risking early-stage development.
Market Restraints
- Plasmid DNA supply concentration:Viral vector manufacturing depends on a narrow base of European contract development organizations, creating bottleneck risks for gene therapy scale-up.
- GDPR constraints on real-world evidence:Cross-border patient data pooling for post-market surveillance faces fragmentation under national implementation variations, limiting adaptive trial designs.
- Small-molecule substitution pressure:Generic metformin and rapamycin analogs compete for wellness-oriented consumers, compressing margins for novel senolytic formulations in preventive applications.
Strategic Opportunities
- Spanish early-access frameworks:Andalusian and Catalan regional health systems operate flexible compassionate use programs that accelerate revenue generation prior to EMA marketing authorization.
- Epigenetic reprogramming convergence:Integration of partial reprogramming factors with existing senolytic protocols opens combination therapy categories not addressed by monotherapy candidates.
- Direct-to-clinic distribution:Specialized logistics providers now offer temperature-controlled last-mile delivery to individual treatment centers, bypassing wholesale pharmacy consolidation.
Industry Challenges
- GMP vector manufacturing talent scarcity:European facilities face acute shortages of process engineers trained in suspension-based AAV production and closed-system bioreactor operations.
- ATMP certification timelines:EMA's classification procedures for borderline products between gene therapy and somatic cell therapy create protracted scientific advice cycles that delay IND-enabling studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Longevity and Anti-Senescence Therapy Market |
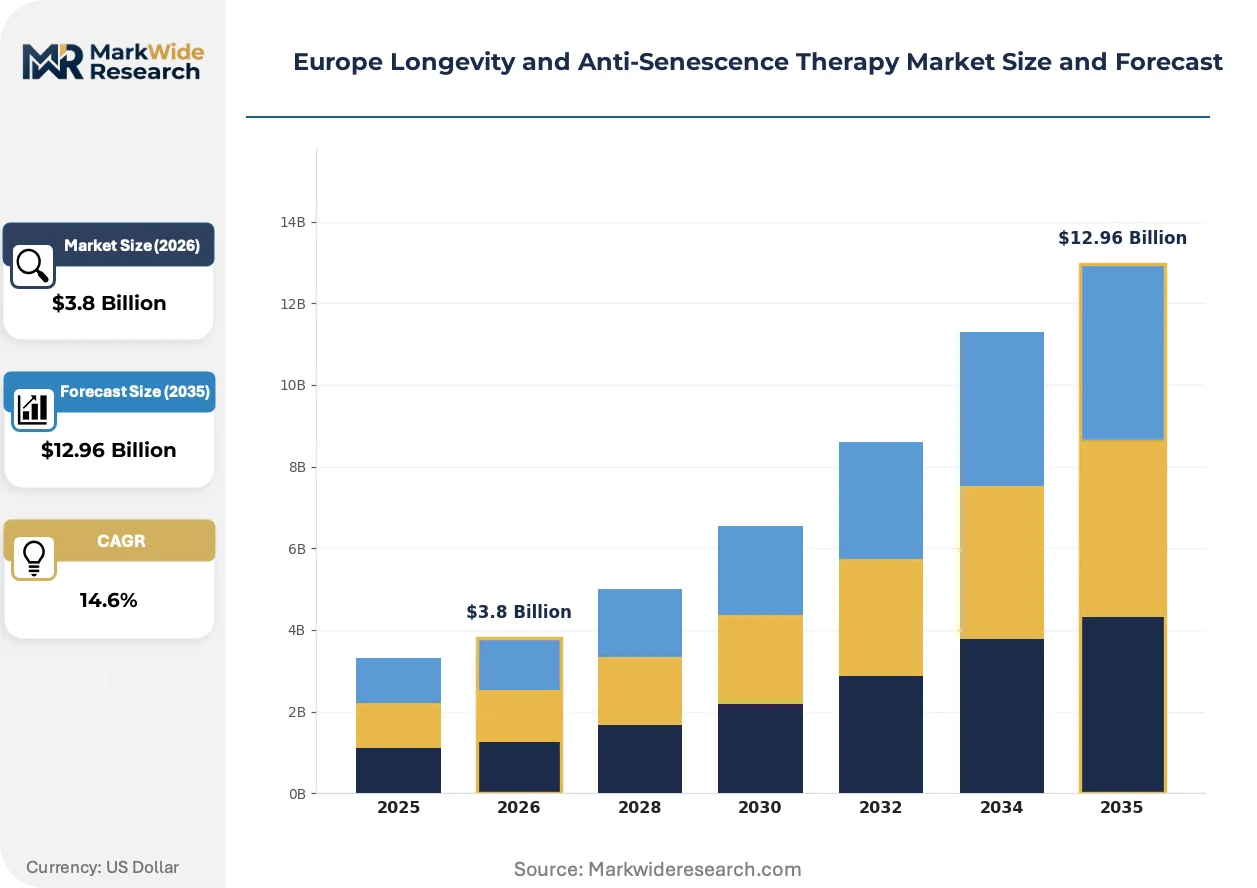
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapies, Nutraceuticals, Gene Therapies, Cell Therapies Technology: CRISPR, Stem Cell Technology, Senolytics, Telomere Extension Application: Regenerative Medicine, Anti-Aging Treatments, Chronic Disease Management, Wellness Programs End User: Clinics, Research Institutions, Pharmacies, Wellness Centers |
| Companies Covered | Juvenescence Ltd., Calico Life Sciences, Unity Biotechnology, Insilico Medicine, Life Biosciences, AgeX Therapeutics, CohBar, Oisin Biotechnologies, Bristol-Myers Squibb Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Longevity and Anti-Senescence Therapy Market Evolving Landscape
European longevity therapy development is bifurcating between precision gene interventions and scalable small-molecule platforms, with manufacturing modality choices increasingly determining competitive positioning before clinical readouts.
Senolytic drug candidates targeting BCL-2 family proteins and p53-MDM2 pathways are overtaking early-generation dasatinib-quercetin combinations in investigator-initiated trials. British and Dutch academic centers now prioritize these next-generation mechanisms in their procurement specifications for aging biology consortia. The shift is compressing development investment into modalities with clearer regulatory precedents from oncology applications.
EMA's qualification opinion process for novel biomarkers is reshaping trial design requirements for anti-senescence therapies. Sponsors must now demonstrate pharmacodynamic engagement through accepted senescence markers prior to Phase IIb initiation, raising the evidentiary bar for adaptive licensing. German and French regulators are conducting parallel scientific advice that diverges on acceptable surrogate endpoints, forcing sponsors to design separate evidence packages.
Hospital procurement for longevity therapies is consolidating through centralized tendering at the national level in France and regional level in Germany. British NHS England's specialized commissioning frameworks are replacing individual trust purchasing for high-cost gene therapies, concentrating volume with approved treatment centers. This channel compression favors developers with dedicated market access teams capable of navigating health technology assessment timelines exceeding eighteen months.
Europe Longevity and Anti-Senescence Therapy Market Segmentation
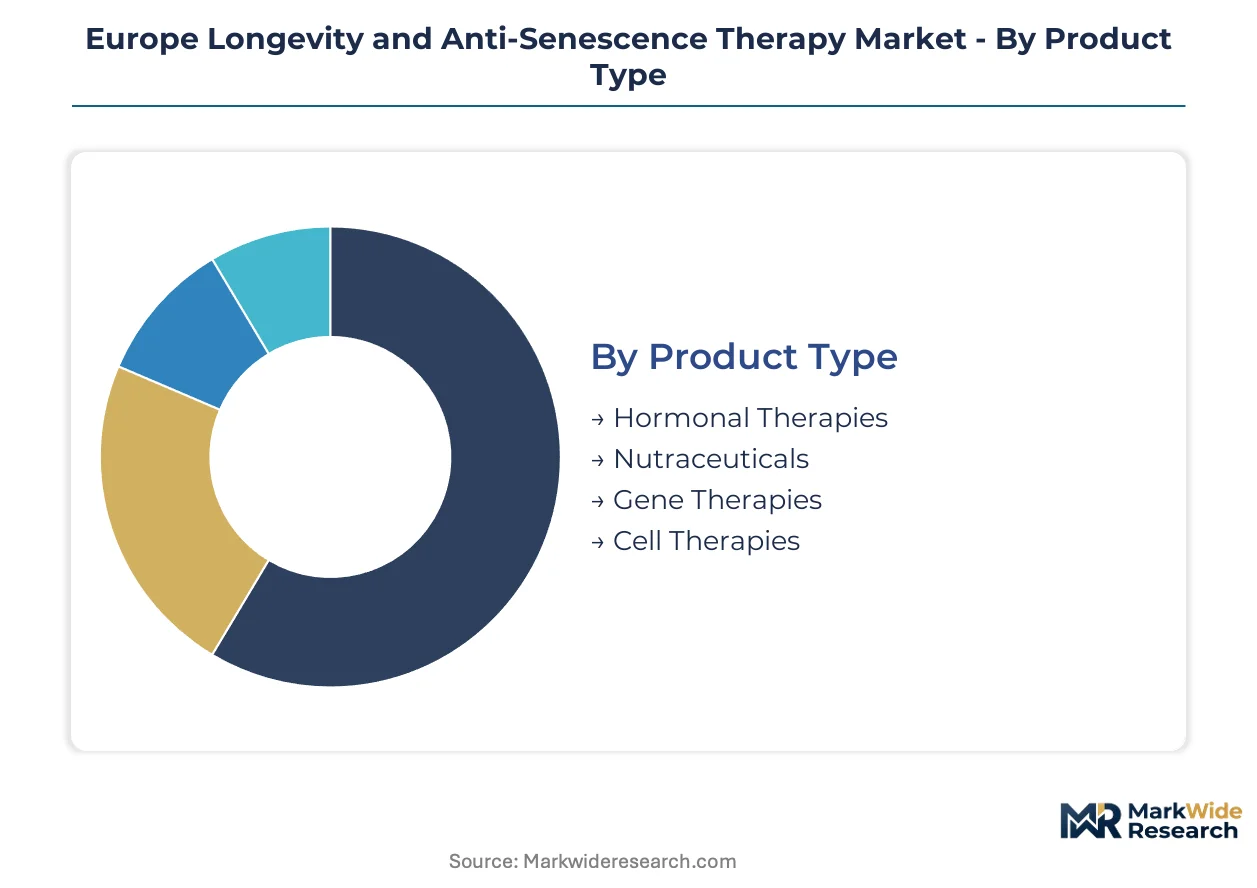
Europe's longevity therapy market segments along therapeutic modality, intervention mechanism, clinical application, and care delivery setting. Each dimension carries distinct regulatory pathways, pricing architectures, and procurement behaviors that shape commercial strategy.
Product Type:
Upgrade cycles in longevity therapy track patent expirations and EMA marketing authorizations, with providers replacing earlier-generation small molecules as advanced therapy medicinal products gain reimbursement.
- Gene Therapies:Viral vector-delivered interventions targeting cellular senescence pathways require GMP-certified manufacturing facilities. German university hospitals and British NHS specialized commissioning frameworks concentrate procurement for these high-cost one-time treatments.
- Cell Therapies:Autologous and allogeneic stem cell products target tissue regeneration through paracrine signaling mechanisms. Spanish early-access frameworks accelerate compassionate use revenue ahead of formal EMA authorization.
- Hormonal Therapies:Peptide and growth hormone formulations address endocrine decline patterns in aging populations.
- Nutraceuticals:Over-the-counter formulations including NAD+ precursors and polyphenol compounds compete on wellness retail shelves.
Volume placements concentrate in Cell Therapies; the faster expansion belongs to Gene Therapies.
Technology:
Technology selection in European longevity R&D pivots on manufacturing scalability and regulatory precedent, with modalities borrowing validation from adjacent therapeutic areas.
- Senolytics:Small-molecule agents selectively clear senescent cells through BCL-2 inhibition or p53-MDM2 modulation. British and Dutch academic centers prioritize next-generation candidates in aging biology consortium procurement specifications.
- Stem Cell Technology:Pluripotent and mesenchymal cell platforms enable tissue-specific regeneration through differentiation or secretome delivery. French national tendering consolidates hospital purchasing for these advanced modalities.
- CRISPR:Gene-editing approaches target epigenetic clocks and longevity-associated loci.
- Telomere Extension:Telomerase activation strategies aim to restore replicative capacity in somatic cells.
Procurement volume clusters around Senolytics; Stem Cell Technology claims the steepest expansion trajectory.
Application:
Application segmentation reflects the tension between curative intent and preventive positioning, with reimbursement codes favoring disease-modifying claims over wellness optimization.
- Regenerative Medicine:Tissue repair applications in osteoarthritis and cardiovascular disease leverage established clinical endpoints. German aging research institutes anchor demand through dedicated procurement budgets for gene therapy vectors and stem cell platforms.
- Chronic Disease Management:Senolytic interventions target age-related comorbidities including idiopathic pulmonary fibrosis and chronic kidney disease. EMA biomarker qualification opinions for p16INK4a enable surrogate endpoints in Phase II trials.
- Anti-Aging Treatments:Aesthetic and functional optimization applications operate largely outside reimbursement.
- Wellness Programs:Preventive protocols in private clinics and longevity centers emphasize lifestyle integration.
Hospital procurement concentrates in Regenerative Medicine; Chronic Disease Management is expanding most quickly.
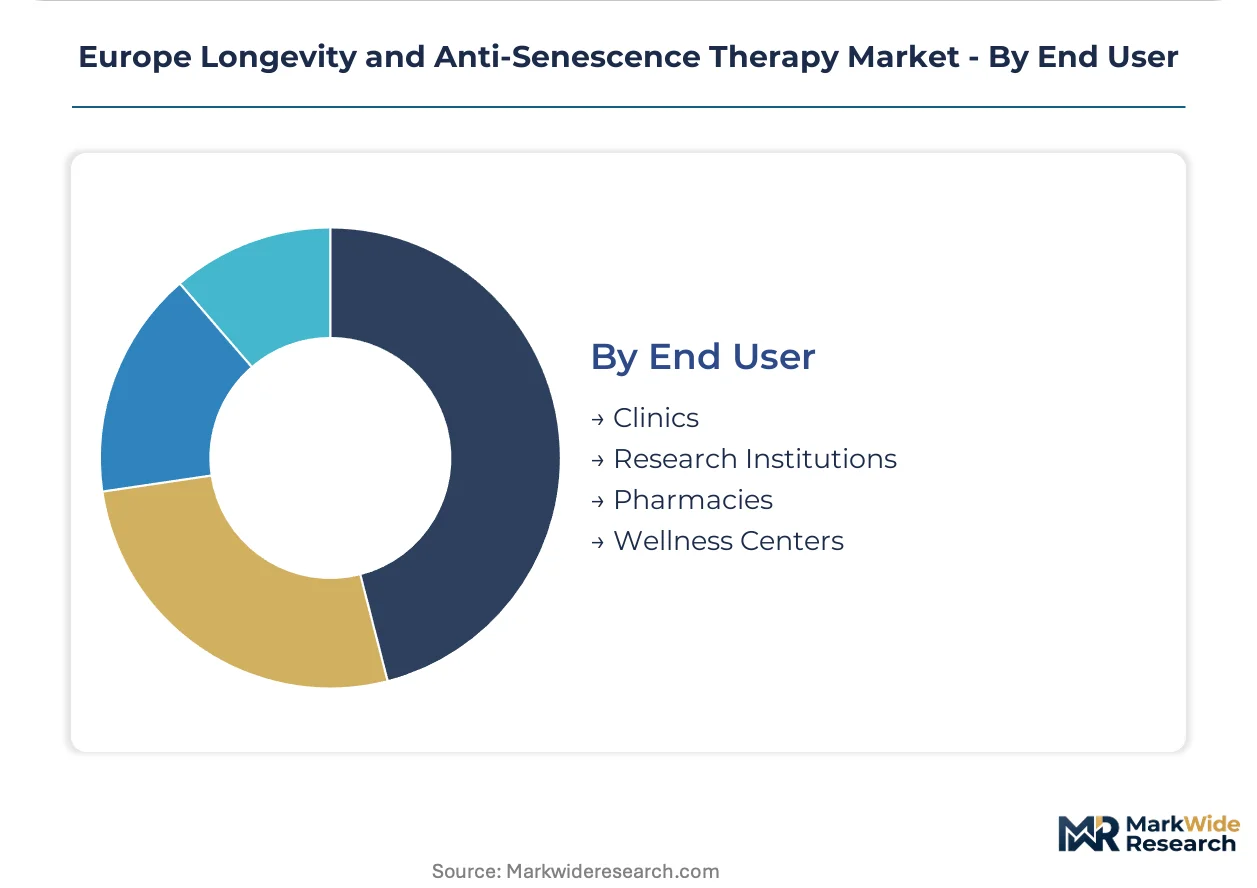
End User:
End-user segmentation tracks the divergence between institutional research demand and commercial clinical delivery, with channel structure determining pricing power and patient access.
- Research Institutions:University hospitals and academic medical centers drive early-phase demand through investigator-initiated trials. British research consortia and German university hospitals procure senolytic candidates and gene therapy vectors at scale.
- Clinics:Specialized treatment centers deliver approved therapies under EMA marketing authorizations. NHS England's specialized commissioning frameworks concentrate volume with approved centers.
- Wellness Centers:Private facilities offer non-reimbursed preventive protocols and nutraceutical regimens.
- Pharmacies:Retail and specialty pharmacy channels handle small-molecule senolytics and compounded formulations.
Procurement volume clusters in Research Institutions; Clinics are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London anchors European longevity therapy development through concentrated venture capital flows and NHS England specialized commissioning frameworks that aggregate procurement for high-cost gene therapies.
Germany
German university hospitals drive regenerative medicine demand through dedicated aging research institutes in Heidelberg and Berlin. The national competent authority, BfArM, coordinates parallel scientific advice with EMA on senolytic trial designs. Bavarian biotech clusters around Munich concentrate GMP viral vector manufacturing for gene therapy scale-up.
United Kingdom
British research consortia procure senolytic candidates at scale through the UK Research and Innovation aging biology networks. MHRA operates post-Brexit recognition procedures for EMA marketing authorizations while maintaining distinct national reimbursement negotiations. London-Oxford-Cambridge golden triangle anchors early-phase clinical operations and specialized commissioning frameworks.
France
French national tendering consolidates hospital purchasing for stem cell platforms and advanced therapy medicinal products. ANSM conducts divergent scientific advice with German regulators on acceptable surrogate endpoints for anti-senescence trials. Paris-Saclay research cluster hosts epigenetic reprogramming programs alongside dedicated aging biology institutes.
Spain
Andalusian and Catalan regional health systems operate flexible compassionate use programs that accelerate revenue generation prior to EMA marketing authorization. AEMPS coordinates early-access frameworks with regional authorities while maintaining REACH compliance for novel chemical entities. Barcelona biotech corridor concentrates contract development organizations for plasmid DNA supply.
Switzerland
Swissmedic maintains autonomous marketing authorization pathways that attract sponsors seeking accelerated timelines outside EU centralized procedures. Basel-Zurich corridor anchors pharmaceutical R&D through legacy chemical biology expertise applied to longevity targets. Federal procurement frameworks enable early reimbursement negotiations independent of EMA health technology assessments.
Europe Longevity and Anti-Senescence Therapy Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the European longevity therapy sector, with viral vector manufacturers maintaining distinct capability moats from senolytic drug developers. The market structures around three tiers: integrated biopharmaceutical conglomerates with gene therapy platforms, specialized senolytic biotechnology firms, and hybrid nutraceutical-gene therapy portfolio companies. Strategic moves concentrate on manufacturing capacity reservations and biomarker qualification partnerships with EMA.
Within the integrated biotechnology tier, Juvenescence Ltd. and Unity Biotechnology exemplify divergent strategic archetypes. Juvenescence occupies a portfolio-breadth position spanning gene therapies and commodity nutraceutical formulations, while Unity Biotechnology anchors specialized senolytic drug development with concentrated R&D operations. Calico Life Sciences represents the capital-reserve archetype, sustaining long-horizon research programs through deep funding structures rather than near-term revenue dependence.
| Leading Market Players |
|---|
| Juvenescence Ltd. |
| Calico Life Sciences |
| Unity Biotechnology |
| Insilico Medicine |
| Life Biosciences |
| AgeX Therapeutics |
| CohBar |
| Oisin Biotechnologies |
| Bristol-Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Suspension-based AAV production methods are displacing adherent-cell platforms across European GMP facilities, simultaneously collapsing per-dose manufacturing costs and concentrating viral vector supply within Bavarian and Swiss contract development organizations. This technological transition compresses gene therapy pricing premiums while creating dependency on a narrow base of qualified manufacturers.
Pricing Analysis
Value-based pricing anchors on clinical outcomes in chronic disease management applications, with reimbursement tied to measurable reductions in age-related comorbidity progression. Price differentiation rests on ATMP certification status and manufacturing modality, with EMA-authorized gene therapies commanding substantial premiums over compassionate-use stem cell products. Pricing pressure stems from generic metformin and rapamycin analogs competing for wellness-oriented consumers outside reimbursement channels. Hospital procurement committees demonstrate highest price sensitivity, while private longevity clinics show relative inelasticity for novel senolytic formulations.
Supply Chain Analysis
Reverse-logistics frameworks for temperature-sensitive viral vectors remain underdeveloped across European distribution networks, limiting recovery of spoiled batches and constraining cost optimization. Supply concentrates in Germany, Switzerland, and Spain, with Bavarian facilities and the Barcelona biotech corridor anchoring plasmid DNA and AAV production capacity. Raw material dependencies include HEK293 cell lines, transfection reagents, and specialized bioreactor consumables. Single-source vulnerability pervades GMP-grade plasmid supply, with contract development organization concentration creating bottleneck risks for gene therapy scale-up. Distribution runs through specialized cold-chain logistics providers delivering directly to approved treatment centers under NHS England and French national tendering frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive control over GMP viral vector manufacturing to secure supply certainty and capture margin that currently accrues to contract development organizations.
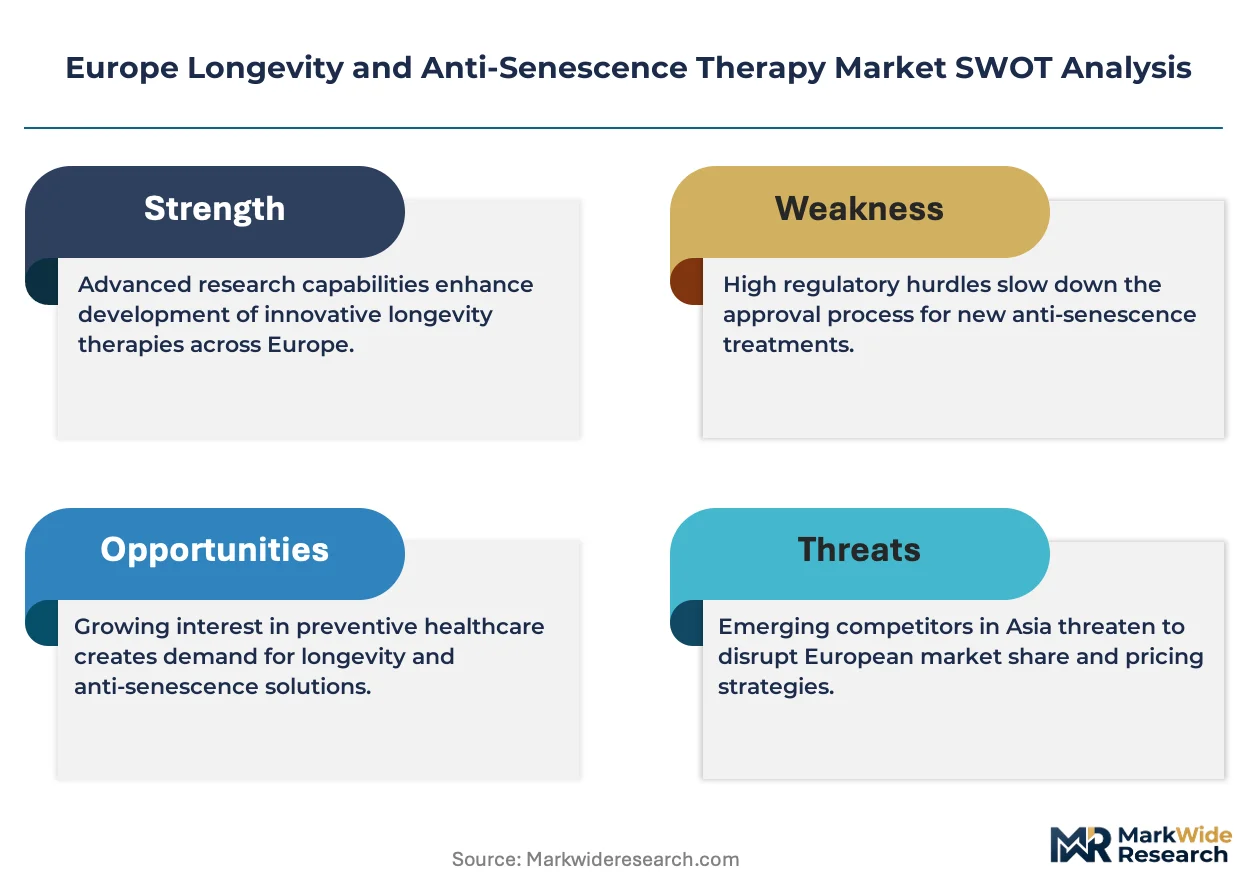
For Market Incumbents: Cement manufacturing capacity reservations with Bavarian and Swiss contract development organizations before competitor lock-up. Acquire biomarker qualification partnerships with EMA to shape surrogate endpoint acceptance for adaptive licensing. Generic small-molecule substitution in wellness applications threatens novel senolytic margins; defend through clinical data differentiation in reimbursed chronic disease indications.
For New Entrants and Emerging Players: Capture early-access revenue through Spanish regional compassionate use frameworks ahead of formal EMA authorization. Target epigenetic reprogramming convergence opportunities combining partial reprogramming factors with existing senolytic protocols, a white-space category unaddressed by current monotherapy candidates. Pursue direct-to-clinic distribution partnerships bypassing wholesale pharmacy consolidation.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated biopharmaceutical conglomerates seeking gene therapy platform capabilities. Long-term viability favors asset-light senolytic developers with clear regulatory precedents from oncology applications over capital-intensive viral vector manufacturers facing talent scarcity. Monitor EMA qualification opinion trends for p16INK4a and senescence-associated secretory phenotype biomarkers as inflection indicators for adaptive licensing feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Partnership | EMA acceptance of p16INK4a markers enables surrogate endpoints, compressing Phase IIb timelines. |
| GMP Manufacturing Scale-Up | Bavarian facility expansion addresses acute process engineer shortages in suspension-based AAV production. |
| Regional Early-Access Framework | Andalusian and Catalan compassionate use programs accelerate revenue ahead of centralized authorization. |
| Combination Therapy Development | Integration of partial reprogramming factors with senolytics opens novel therapeutic categories. |
| Direct-to-Clinic Distribution | Specialized cold-chain logistics bypass NHS England and French national tendering concentration. |
Research Methodology
Document review covered EMA marketing authorization databases, ClinicalTrials.gov senolytic trial registrations, and EU Clinical Trials Regulation implementation reports, complemented by interviews with drug development executives, regulatory affairs leads at biopharmaceutical sponsors, hospital procurement managers in German university hospitals, and payer access specialists within NHS England specialized commissioning frameworks. Secondary validation drew from REACH compliance filings, national competent authority scientific advice records, and health technology assessment documentation from NICE and HAS. Bottom-up demand modeling triangulated against top-down market sizing across therapeutic modality segments.
Segment-level projections incorporate gene therapy, cell therapy, and small-molecule senolytic categories across regenerative medicine, chronic disease management, and wellness applications, with geographic disaggregation by national reimbursement framework. CAGRs derive from patent expiration schedules, EMA approval probability-weighted revenue forecasts, and hospital procurement budget trajectories. Industry-specific inputs include viral vector manufacturing capacity utilization rates and EMA biomarker qualification opinion issuance patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA adaptive licensing precedent shifts and GDPR implementation variations affecting real-world evidence generation. Forecasts reflect assumptions regarding continued EMA-ANSM-BfArM regulatory convergence and sustained venture capital availability for pre-revenue biotechnology platforms. Practitioners should monitor EMA qualification opinion issuance rates and GMP vector manufacturing talent pipeline indicators for early signals of timeline compression or expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
US Scar Treatment Market
Regenerative Medicine
US Platelet Rich Plasma Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
China Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Orthopedic Regenerative Medicine Market
Regenerative Medicine
Longevity and Anti-Senescence Therapy for Cancer Market
Regenerative Medicine
Tooth Regeneration Market
Regenerative Medicine
Stromal Vascular Fraction Market
Regenerative Medicine
Asia-Pacific Regenerative Medicine Market
Regenerative Medicine
Global Breast Reconstruction Market
Regenerative Medicine
Personalized Immunotherapy Market
Regenerative Medicine
Tenosynovial Giant Cell Tumor Treatment Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Autologous Fat Grafting Market