
 Empty Container Repositioning Optimization Platforms Market | 2026-2036
Empty Container Repositioning Optimization Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Empty Container Repositioning Optimization Platforms Market Insights
Real-time container visibility layered with predictive demand algorithms is tilting platform architecture toward cloud-native, API-first stacks. Maersk leverages its integrated logistics arm to embed repositioning logic directly into booking workflows. MSC Mediterranean Shipping Company sustains one of the largest owned container fleets, giving its optimization engine captive data scale that third-party platforms cannot replicate. CMA CGM differentiates through AI-driven port selection that balances dwell cost against repositioning distance.
Empty container repositioning optimization platforms are software systems that algorithmically match surplus container inventory at discharge ports with anticipated export demand at origin locations, typically processing variables including vessel schedules, rail connections, depot capacity, and per-diem penalties to minimize unproductive moves. Cloud-based deployments lead platform type adoption because maritime operators prioritize elastic compute for seasonal trade volume spikes without capital-heavy infrastructure commitments. Demand matching functionality captures disproportionate R&D investment since carrier margins compress fastest on empty miles, while scheduling automation remains comparatively mature with established rule-based engines. Terminal operators represent the fastest-growing end-user category as port authorities bundle repositioning modules into broader terminal operating system upgrades.
The International Maritime Organization's carbon intensity indicator rules and the EU Emissions Trading System extension to maritime shipping are tightening the regulatory noose on unoptimized empty moves, effectively mandating digital repositioning tools for compliance. China's Ministry of Transport port throughput reporting standards and SAMR data localization requirements further shape platform deployment architecture in the world's largest container handling market. Stakeholders must weigh whether to build proprietary optimization engines or absorb vendor platforms as regulatory complexity outpaces in-house software development cycles.
Market Dynamics
Cloud-native API architectures are compressing deployment cycles for maritime operators, forcing legacy on-premise systems into obsolescence as carriers chase elastic compute for seasonal volume spikes. This infrastructure shift rewrites vendor competitive dynamics and procurement criteria.
Growth Catalysts
- EU Emissions Trading System maritime extension:Carbon pricing on empty container moves creates direct financial pressure to adopt algorithmic repositioning tools. Carriers face compliance deadlines that mandate digital optimization infrastructure.
- Terminal operator system consolidation:Port authorities bundle repositioning modules into broader terminal operating system upgrades, expanding addressable market beyond shipping lines to infrastructure operators.
- China's port throughput reporting standards:SAMR data localization requirements force platform architecture adaptations that incidentally improve domestic supply chain visibility for multinational carriers.
Market Restraints
- Data sovereignty fragmentation:China's SAMR localization mandates, EU GDPR restrictions, and US CLOUD Act extraterritoriality create architectural conflicts that inflate compliance engineering costs for global deployments.
- Container manufacturing concentration:Chinese producers control over 95% of global container output, creating supply-side lock-in that limits platform flexibility on asset origin tracking and lifecycle data integration.
- Legacy system entrenchment:Decades-old terminal operating systems at major transshipment hubs resist API integration, forcing expensive middleware layers that erode cloud-native cost advantages.
Strategic Opportunities
- Rail-intermodal corridor digitization:China-Europe block train operators lack container visibility across the 11,000-kilometer corridor, creating white space for repositioning platforms that synchronize ocean and rail schedules.
- IMO carbon intensity indicator enforcement gaps:Smaller carriers without in-house analytics capabilities present vendor acquisition targets for platform providers offering compliance-as-a-service bundles.
- Depot automation convergence:Integration with automated container yard systems at Singapore, Rotterdam, and Qingdao enables predictive maintenance scheduling that reduces dwell-based repositioning penalties.
Industry Challenges
- Maritime data science talent scarcity:The intersection of container logistics domain expertise and machine learning engineering remains thinly staffed, inflating implementation timelines and customization costs.
- Multi-stakeholder coordination complexity:Shipping lines, terminal operators, freight forwarders, and depot managers maintain conflicting incentive structures that resist algorithmic optimization without contractual renegotiation.
- Per-diem penalty calculation standardization:Carrier-specific detention and demurrage rule variations prevent universal optimization models, forcing costly client-by-client algorithm tuning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Empty Container Repositioning Optimization Platforms Market |
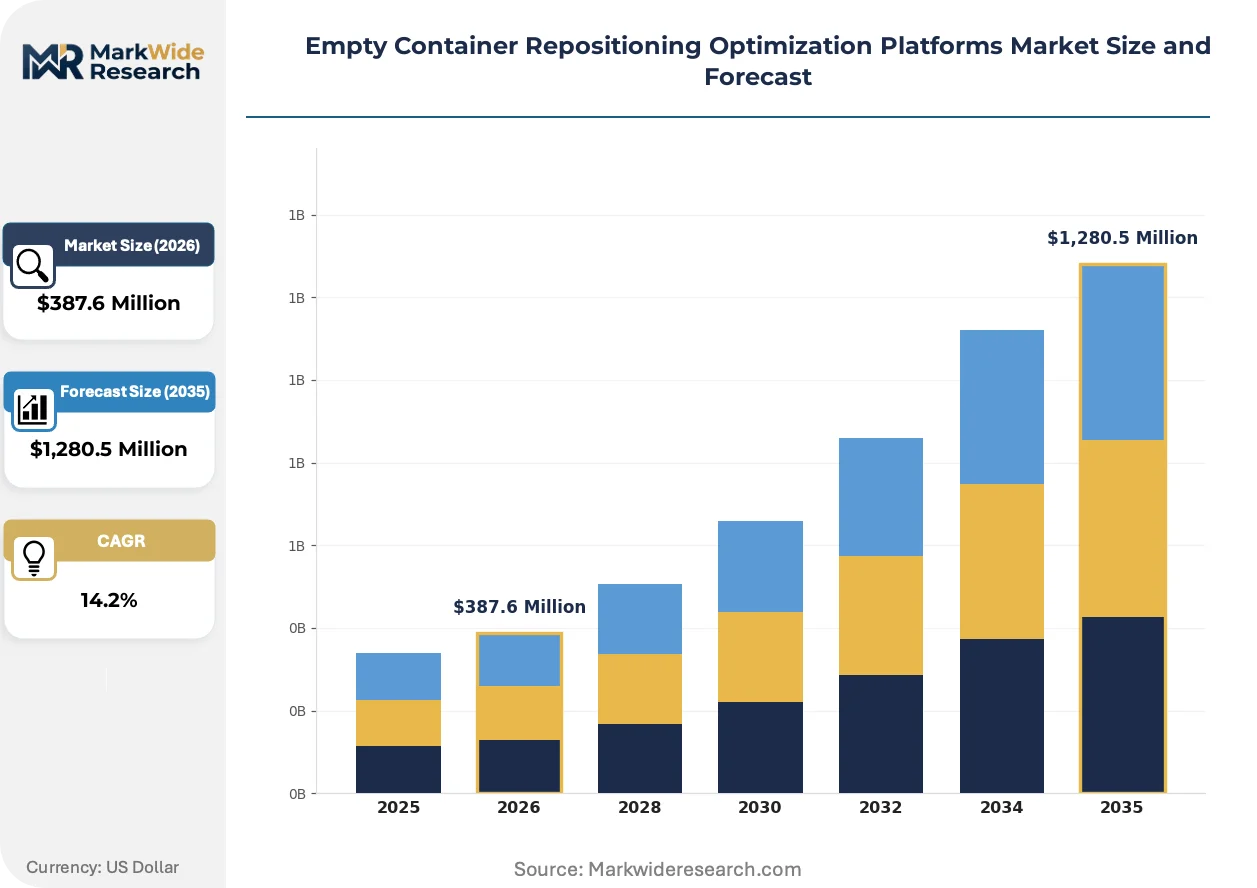
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-based, On-Premise, Hybrid, Edge Computing Functionality: Route Planning, Inventory Forecasting, Demand Matching, Cost Analysis, Scheduling Automation End User: Shipping Lines, Freight Forwarders, Logistics Providers, Terminal Operators, Cargo Owners Integration Capability: ERP Systems, TMS, IoT Sensors, Blockchain Networks, AI Analytics, Legacy Systems |
| Companies Covered | Pacific International Lines, Ocean Network Express, Maersk, MSC Mediterranean Shipping Company, CMA CGM, Hapag-Lloyd, Evergreen Marine, Yang Ming Marine Transport, Cosco Shipping Lines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Empty Container Repositioning Optimization Platforms Market Trends and Innovations
Algorithmic demand forecasting is migrating from deterministic to probabilistic models, enabling repositioning decisions under supply uncertainty rather than static point predictions. This probabilistic turn reshapes platform architecture and buyer evaluation criteria.
Digital twin technology for container fleet simulation is hybridizing with live AIS vessel tracking data. Large carriers deploy these fused systems to stress-test repositioning strategies against weather disruptions and port congestion scenarios before committing assets. The hybridizing capability compresses decision windows from days to hours, eroding competitive advantage for operators relying on spreadsheet-based planning.
The EU Green Deal's emissions disclosure mandates now extend to Scope 3 upstream logistics, compelling carriers to document CO2 per container move with auditable granularity. This regulatory pressure forces platform providers to embed carbon accounting modules directly into optimization engines rather than bolt-on reporting tools. Asia-Pacific carriers serving EU trade lanes face the steepest compliance engineering investments.
Consolidation among freight forwarders is concentrating buying power and demanding outcome-based repositioning guarantees rather than software licenses. Forwarder networks in Germany and the Netherlands now negotiate penalty clauses tied to empty mile reduction targets, transferring performance risk to platform vendors. This procurement evolution favors vendors with captive container data assets over pure-software challengers.
Empty Container Repositioning Optimization Platforms Market Segmentation
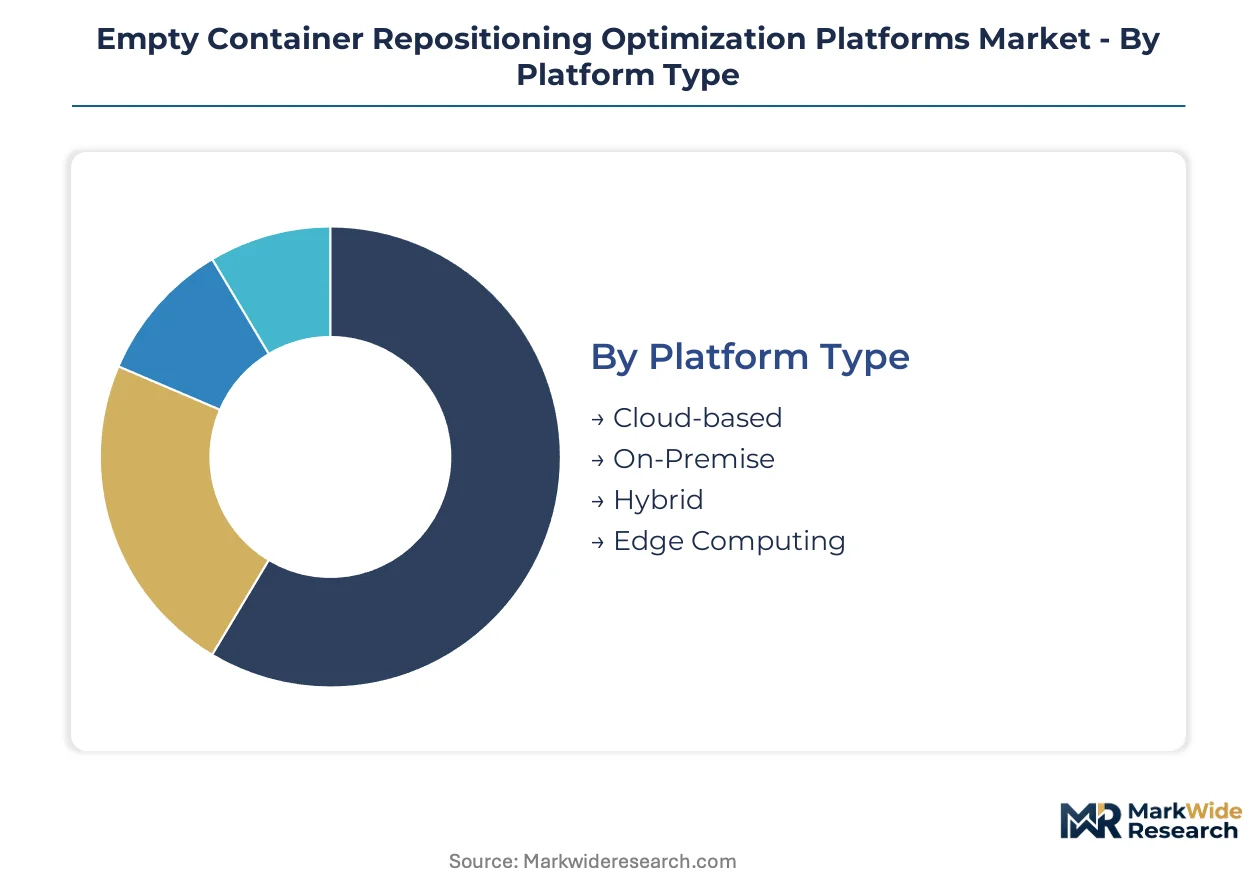
Repositioning platform segmentation reveals divergent deployment economics across infrastructure models and functional modules. Carriers with seasonal volume volatility favor elastic architectures, while integrated operators prioritize functionality that compresses empty mile decision cycles.
Platform Type:
Cloud-based platforms turn over fastest with quarterly release cycles, while on-premise installations cycle slowest through multi-year procurement and certification timelines.
- Cloud-based:Elastic compute architectures enable maritime operators to scale processing capacity during peak trade seasons without capital infrastructure commitments. Demand concentrates among Asia-Pacific carriers serving EU trade lanes where EU Emissions Trading System compliance deadlines mandate rapid deployment timelines.
- On-Premise:Dedicated hardware installations at carrier headquarters maintain data sovereignty for classified vessel schedules and proprietary rate negotiations. State-owned shipping lines in China favor this model under SAMR data localization requirements despite longer implementation windows.
- Hybrid:Split architectures process sensitive optimization algorithms locally while pushing non-critical analytics to public cloud tiers.
- Edge Computing:Container-mounted processing units at depots enable real-time repositioning decisions without latency to central servers.
Cloud-based platforms dominate installed base. Edge Computing is where expansion concentrates.
Functionality:
Cost tier differentiation separates modules by implementation complexity, with demand matching commanding premium pricing against commoditized scheduling automation.
- Demand Matching:Probabilistic algorithms pair surplus container inventory at discharge ports with anticipated export bookings, processing vessel schedules, rail connections, and per-diem penalties simultaneously. Investment concentrates here as carrier margins compress fastest on unproductive empty miles across China-Europe corridors.
- Scheduling Automation:Rule-based engines execute vessel stowage plans and depot dispatch orders with established optimization libraries. Terminal operators at Rotterdam and Singapore deploy mature implementations with limited customization requirements.
- Route Planning:Multi-modal path optimization across ocean, rail, and truck legs.
- Inventory Forecasting:Predictive models projecting container availability weeks ahead of physical positioning.
- Cost Analysis:Detention, demurrage, and fuel expenditure tracking against repositioning alternatives.
Scheduling Automation dominates installed base. Demand Matching is climbing the fastest.
End User:
Customer type segmentation tracks procurement authority concentration, with terminal operators gaining platform influence through port authority system consolidation mandates.
- Terminal Operators:Port authorities bundle repositioning modules into terminal operating system upgrades, expanding addressable market beyond traditional shipping line customers. Implementation accelerates at Qingdao, Rotterdam, and Singapore where automated container yard systems enable predictive maintenance scheduling.
- Shipping Lines:Integrated carriers embed repositioning logic directly into booking workflows and vessel allocation systems. Maersk and MSC Mediterranean Shipping Company deploy proprietary engines leveraging captive fleet data scale.
- Freight Forwarders:Consolidating networks in Germany and the Netherlands now negotiate outcome-based guarantees with penalty clauses tied to empty mile reduction targets.
- Logistics Providers:Third-party operators serving multiple carrier clients require multi-tenant platform architectures.
- Cargo Owners:Large beneficial cargo owners demand visibility into container availability for supply chain planning.
Shipping Lines dominate installed base. Terminal Operators represent the fastest-growing trajectory.
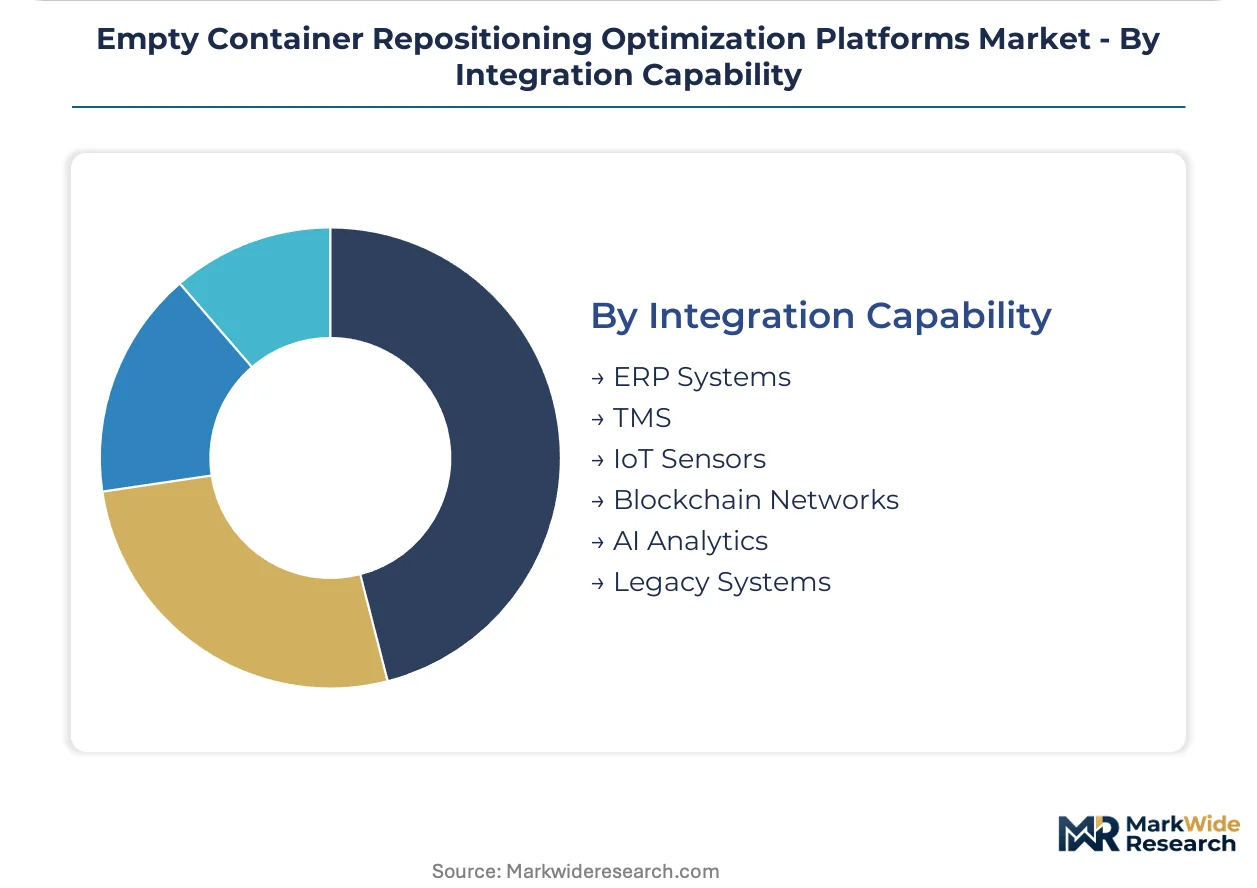
Integration Capability:
Supply concentration in legacy system adapters reflects entrenched terminal operating systems at major transshipment hubs resisting API-native connectivity.
- Legacy Systems:Middleware layers translate decades-old terminal operating system protocols into modern API formats, preserving existing infrastructure investments. Engineering costs inflate at major transshipment hubs where cloud-native cost advantages erode against integration complexity.
- IoT Sensors:Real-time container condition monitoring feeds repositioning algorithms with location, temperature, and shock data streams.
- ERP Systems:Financial and procurement system connectivity for cost allocation and vendor management.
- TMS:Transportation management system synchronization for multi-modal execution.
- Blockchain Networks:Distributed ledger verification of container handoff events and documentation integrity.
- AI Analytics:Machine learning model pipelines for demand forecasting and anomaly detection.
Legacy Systems dominate installed base. IoT Sensors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China-Europe container flows generate the highest empty repositioning inefficiencies, with surplus equipment accumulating at European discharge ports while Asian export demand outstrips supply. This trade asymmetry concentrates platform deployment investment along the corridor's terminal networks and intermodal handoff points.
China
Port congestion at Shanghai and Ningbo-Zhoushan creates severe container stacking imbalances that optimization platforms must resolve within compressed vessel windows. SAMR data localization requirements force cloud architecture adaptations that incidentally improve domestic supply chain visibility for multinational carriers. Qingdao's automated container yard systems enable predictive maintenance scheduling that reduces dwell-based repositioning penalties.
Germany
Hamburg and Bremerhaven handle the largest European volumes of Asia-imported containers, generating surplus equipment that platforms must match against Baltic and Mediterranean export bookings. EU Emissions Trading System maritime extension imposes carbon pricing on empty moves that mandates algorithmic optimization infrastructure. Forwarder networks in the Netherlands and Germany negotiate outcome-based guarantees with penalty clauses tied to empty mile reduction targets.
Singapore
The transshipment hub's position between Asia-Europe and intra-Asian trade lanes creates complex equipment pooling decisions across multiple carrier alliances. Port authority system consolidation bundles repositioning modules into terminal operating system upgrades. PSA Singapore's automated container yard infrastructure enables real-time repositioning decisions without latency to central servers.
United States
Los Angeles-Long Beach port complex exhibits chronic container imbalance from Asia-Pacific import dominance, forcing rail-bound empty repositioning to Houston and Savannah export corridors. Legacy terminal operating systems at major transshipment hubs resist API integration, forcing expensive middleware layers. Chicago's rail intermodal terminals concentrate equipment pooling decisions for Midwest manufacturing export demand.
Netherlands
Rotterdam's European gateway status generates empty container surpluses that platforms must redirect toward German industrial export zones and Scandinavian trade lanes. GDPR restrictions on cross-border data flows create architectural conflicts with carrier global deployment architectures. ECT Delta terminal's automated yard systems enable predictive maintenance scheduling integration with repositioning algorithms.
Empty Container Repositioning Optimization Platforms Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that tilts toward integrated shipping lines with captive fleet data assets. Consolidation dynamics favor carriers embedding repositioning logic directly into booking workflows rather than standalone software vendors. Three archetypes dominate: integrated logistics operators with proprietary engines, terminal operators bundling modules into system upgrades, and pure-software challengers serving fragmented forwarder networks. Competitive moves concentrate on M&A for data asset acquisition and strategic partnerships with rail-intermodal operators.
Among Asia-Pacific shipping lines, Pacific International Lines, Ocean Network Express, and Cosco Shipping Lines occupy positions that exemplify the integrated carrier archetype, leveraging captive container fleet scale to generate optimization data unavailable to third-party platforms. These Singapore-based and Chinese operators represent channel-controlling players whose equipment ownership creates natural barriers to pure-software competitors.
| Leading Market Players |
|---|
| Pacific International Lines |
| Ocean Network Express |
| Maersk |
| MSC Mediterranean Shipping Company |
| CMA CGM |
| Hapag-Lloyd |
| Evergreen Marine |
| Yang Ming Marine Transport |
| Cosco Shipping Lines |
| Others |
Pricing and Supply Chain Analysis
Chronic undercapacity at European discharge ports tilts supplier behavior toward premium pricing for demand-matching modules while compressing margins on commoditized scheduling automation. Carriers absorb higher per-license costs to secure algorithmic optimization that cuts empty miles and satisfies EU Emissions Trading System compliance deadlines.
Pricing Analysis
Cloud-native platform pricing diverges sharply from legacy on-premise installations, with API-first architectures commanding subscription premiums against depreciating perpetual-license models. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity, with legacy system adapters priced highest due to middleware engineering requirements. Price differentiation hinges on real-time data feed density and carbon accounting module inclusion. Cost compression in standard-tier SaaS offerings is intensifying because freight forwarder consolidation concentrates buying power and demands outcome-based guarantees. Terminal operators prove least price-sensitive, absorbing implementation premiums to bundle repositioning modules into port authority-mandated system upgrades.
Supply Chain Analysis
Extended payment terms from Chinese state-owned shipping lines distort working capital dynamics for software vendors deploying under SAMR data localization requirements. Platform development concentrates in China, Germany, and Singapore, where maritime technology clusters feed from adjacent port automation and vessel tracking industries. Core inputs include cloud compute capacity from hyperscalers, AIS vessel tracking data feeds, and terminal operating system API licenses. Single-source vulnerability runs through container manufacturing concentration, where Chinese producers control over 95% of global output and limit asset lifecycle data integration. Distribution runs through direct enterprise sales to integrated carriers and channel partnerships with terminal operating system vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container trade volume cyclicality positions this market for recovery as Asia-Europe lane utilization rebounds from inventory destocking troughs. Platform demand accelerates when carrier fleet deployment rates tighten and empty mile penalties compound.
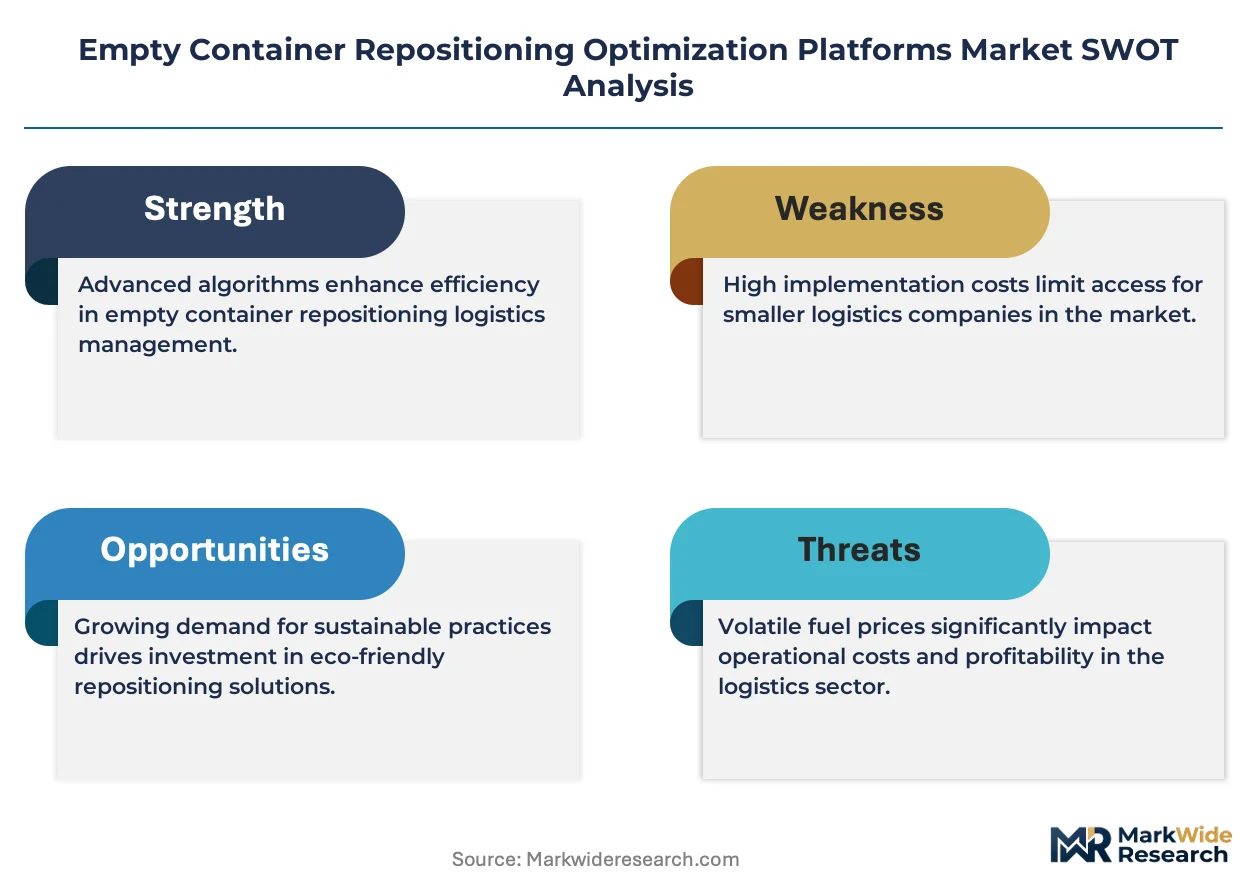
For Market Incumbents: Build data network effects moats by deepening integration with automated container yard systems at Singapore, Rotterdam, and Qingdao. Incumbents should acquire rail-intermodal visibility providers to extend optimization logic beyond maritime legs, while embedding carbon accounting modules directly into optimization engines to preempt EU Green Deal Scope 3 disclosure mandates. Vertical integration into depot automation hardware preserves margin position against pure-software challengers.
For New Entrants and Emerging Players: Build out white-space coverage across China-Europe block train corridors where container visibility gaps persist across the 11,000-kilometer rail span. New entrants should target smaller carriers lacking in-house analytics capabilities, offering compliance-as-a-service bundles that bundle IMO carbon intensity indicator reporting with repositioning optimization. Go-to-market traction concentrates on outcome-based pricing with penalty clauses tied to empty mile reduction guarantees.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because emissions disclosure mandates and carbon pricing mechanisms embed repositioning platforms into carrier operating requirements regardless of trade cycle positioning. Acquisition targets include rail-intermodal visibility specialists and depot automation software vendors with predictive maintenance capabilities. The signal to watch is EU Emissions Trading System enforcement stringency against smaller carriers, which would accelerate vendor consolidation and expand addressable market for compliance-focused platform providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Intermodal Corridor Integration | Synchronizes ocean and block train schedules across China-Europe routes where visibility gaps persist. |
| Carbon Accounting Module Embedding | Aligns platform architecture with EU Green Deal Scope 3 emissions disclosure mandates for auditable CO2 per container move. |
| Depot Automation Convergence | Links repositioning algorithms with automated yard systems at Singapore and Rotterdam to cut dwell-based penalties. |
| Compliance-as-a-Service Bundling | Captures smaller carriers lacking IMO carbon intensity indicator analytics through outsourced regulatory infrastructure. |
| API-First Architecture Migration | Replaces legacy middleware layers at transshipment hubs with cloud-native stacks that compress deployment cycles. |
Research Methodology
A spread of perspectives from shipping line fleet optimization directors, terminal operating system procurement leads, freight forwarder network managers, and maritime software engineers converged on the working assumptions driving platform adoption trajectories. Primary fieldwork combined structured interviews with secondary validation against customs trade data, port authority throughput disclosures, carrier SEC filings, and EU regulatory implementation notices. Bottom-up sizing of platform deployments by carrier fleet scale and top-down triangulation against total addressable container movements cross-validated demand estimates.
Demand-supply balance modeling across the projection horizon weighted seasonal trade volatility, regulatory compliance deadlines, and terminal operator system consolidation mandates. Segmentation dimensions included platform deployment architecture, functional module priority, end-user procurement authority, and integration complexity tier. CAGRs were derived from fitted adoption curves against historical container fleet growth and empty mile penalty rate escalations. Forecast inputs incorporated EU Emissions Trading System carbon price assumptions and SAMR data localization implementation timelines.
Stress conditions across trade lane volume collapse, regulatory enforcement delay, and cloud infrastructure cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding carrier digital transformation budgets and port authority upgrade cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Secure Logistics Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Switzerland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Freight Forwarding Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Germany Dangerous Goods Logistics Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
France Parcel Market
Logistics and Shipping
Government and Education Logistics Market
Logistics and Shipping
Intralogistics Containers Market