
 Global Intelligent Transportation System (ITS) Market | 2026-2036
Global Intelligent Transportation System (ITS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Transportation System (ITS) Market Foresight
Buyer concentration among municipal authorities is expanding as city governments consolidate vendor relationships under multi-year smart city contracts. Siemens AG leverages its traffic management software portfolio to anchor large-scale deployments across German and Austrian urban corridors. Thales Group competes through specialized signaling and rail-integrated ITS platforms for intermodal transit hubs. Hitachi Ltd. differentiates by extending its digital infrastructure expertise from energy systems into real-time traffic analytics for Asian megacities.
An intelligent transportation system constitutes an integrated framework of sensors, communication networks, and control software designed to optimize vehicle flow, enhance road safety, and reduce emissions through real-time data exchange between infrastructure and mobile assets. These systems typically process sub-second latency inputs from radar arrays, video analytics nodes, and GPS tracking feeds to dynamically adjust signal timing and route assignments. Traffic management solutions currently occupy the largest solution-type position due to persistent urban congestion and aging signal infrastructure in legacy metropolitan networks. Vehicle-to-infrastructure communication represents the fastest-expanding technology segment as 5G low-latency networks enable cooperative intelligent transport systems. Fleet management applications for logistics operators command premium pricing because fuel optimization and regulatory compliance create measurable return thresholds for commercial buyers.
The U.S. Department of Transportation's ITS deployment guidelines, the EU's F-Gas Regulation affecting sensor coolant requirements, and Japan's METI-connected vehicle standards collectively shape product certification pathways and procurement eligibility across major markets. China's MIIT mandates GB-standard interoperability for domestic ITS deployments, creating a parallel compliance track for foreign technology suppliers. Stakeholders must monitor evolving spectrum allocation decisions for dedicated short-range communications, as regulatory commitment to C-V2X versus DSRC directly determines hardware architecture investments and partnership strategies.
Market Dynamics
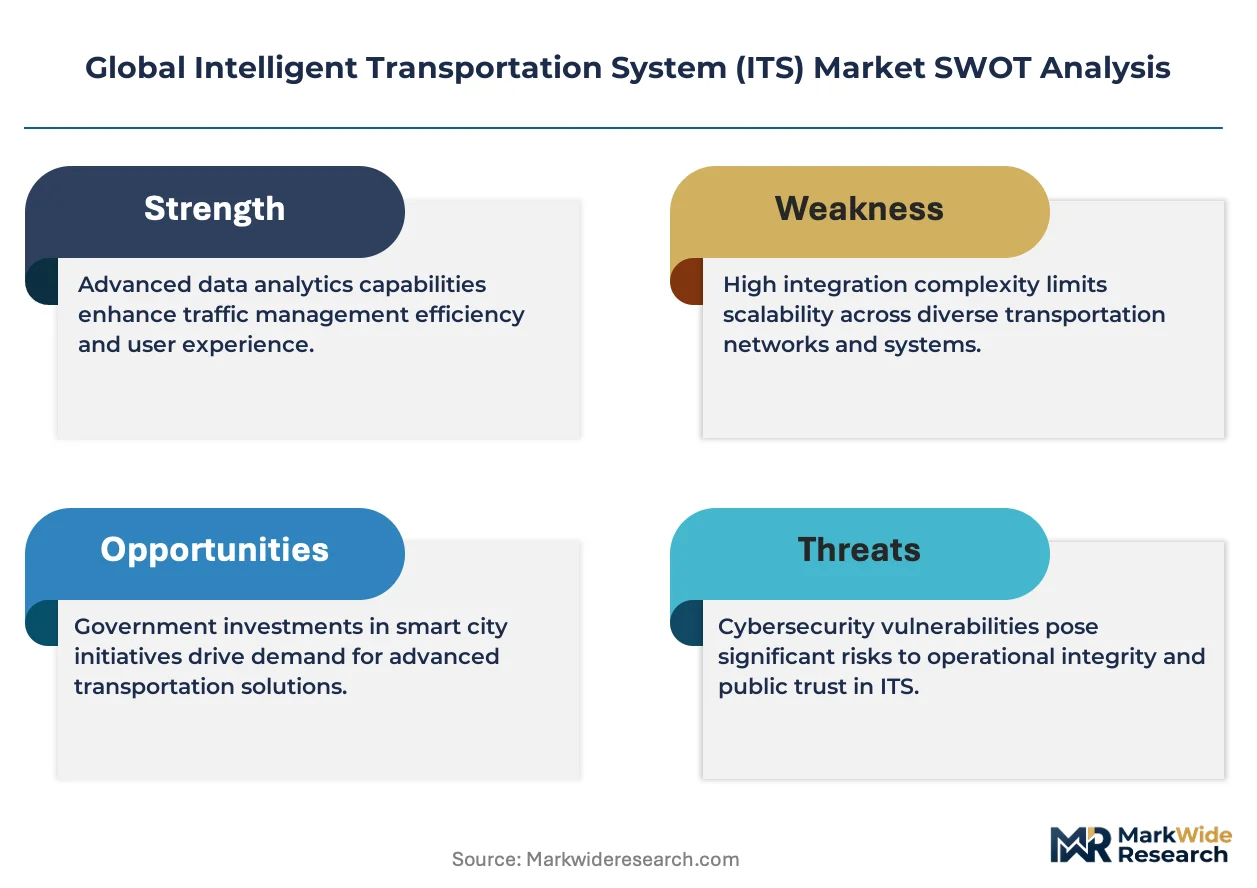
Municipal procurement consolidation is compressing vendor margins while accelerating platform standardization across urban corridors. Cities now demand interoperable traffic management stacks that bind hardware, software, and data analytics under unified long-term service agreements.
Growth Catalysts
- EU Green Deal congestion mandates:Binding emissions reduction targets for urban transport are forcing metropolitan authorities to deploy real-time signal optimization and low-emission zone enforcement infrastructure.
- 5G C-V2X network rollouts:Telecommunications carriers in Germany, South Korea, and the United States are prioritizing dedicated spectrum for vehicle-to-infrastructure communication, enabling cooperative intelligent transport systems.
- Federal highway digitization programs:Germany's Autobahn GmbH is channeling capital into digital corridor pilot projects that integrate sensor arrays with centralized traffic control centers.
Market Restraints
- Semiconductor supply concentration:Radar and lidar sensor modules depend on fabrication capacity concentrated in Taiwan and South Korea, exposing deployment timelines to foundry allocation volatility.
- DSRC versus C-V2X regulatory fragmentation:The United States has not mandated a single protocol, forcing suppliers to engineer dual-compatible hardware and raising unit costs.
- Legacy signal infrastructure replacement cycles:Municipal budget constraints extend depreciation periods for electromechanical traffic controllers, delaying digital upgrade paths.
Strategic Opportunities
- India's smart city mission expansion:The Ministry of Housing and Urban Affairs is tendering integrated traffic management systems for 100 designated urban clusters with limited incumbent vendor presence.
- Rail-integrated multimodal platforms:Convergence of urban rail signaling with roadside ITS infrastructure is creating demand for unified control software at intermodal transit hubs.
- Japan's METI-connected vehicle standards:Regulatory clarity on V2X interoperability is accelerating fleet operator pilot programs for commercial vehicle platooning and automated yard management.
Industry Challenges
- Cyber-physical systems engineering talent scarcity:The intersection of civil infrastructure, embedded systems, and real-time software development requires hybrid skill sets that universities and vocational programs have not scaled.
- Interoperability certification timelines:Multi-vendor integration testing for GB-standard compliance in China and ETSI conformance in Europe extends product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Transportation System (ITS) Market |
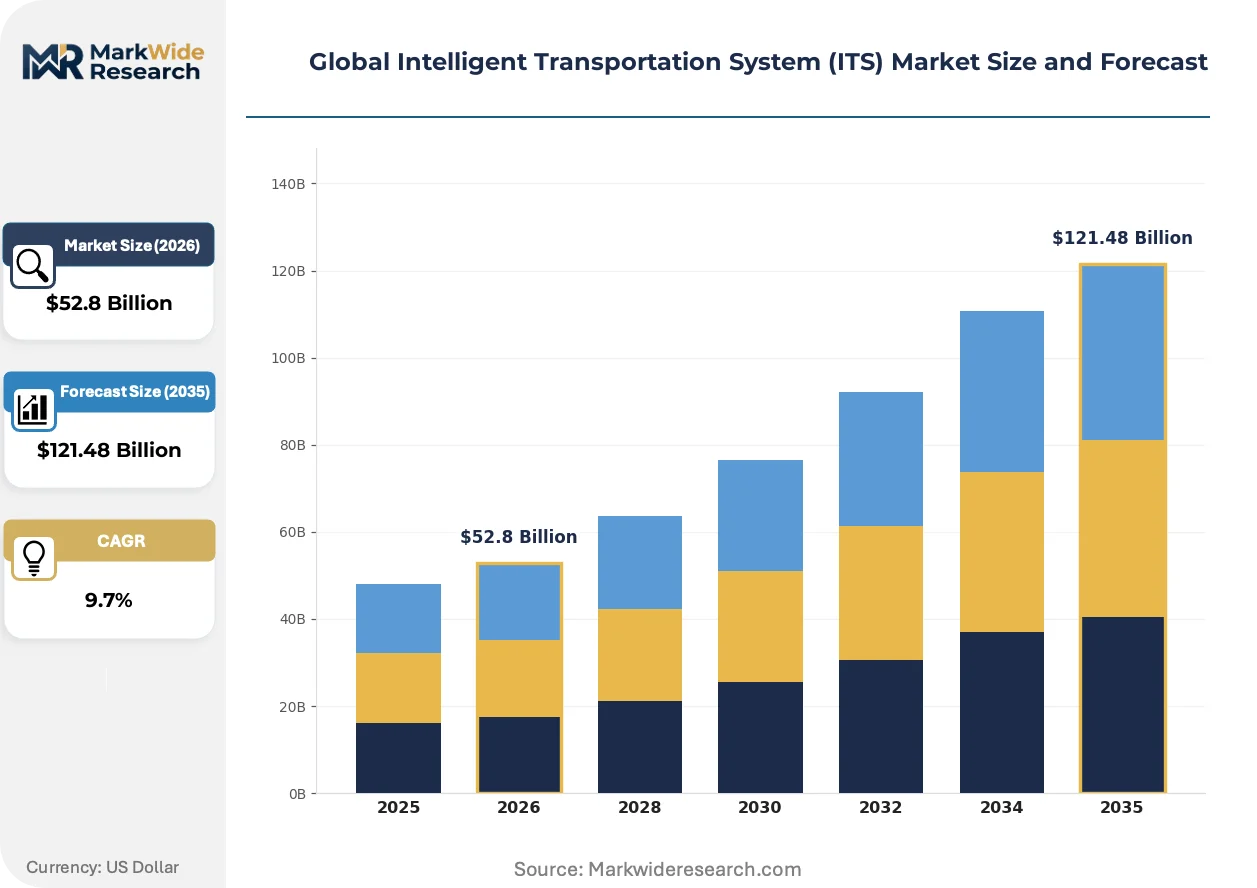
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $121.48 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Traffic Management, Electronic Toll Collection, Incident Detection, Fleet Management, Public Transit Management Technology: Radar, LiDAR, Video Analytics, GPS Tracking, Vehicle-to-Infrastructure Communication Application: Road Safety Enhancement, Traffic Congestion Control, Smart Parking, Emergency Response, Freight Monitoring End User: Municipal Authorities, Transportation Agencies, Logistics Operators, Public Transit Providers, Infrastructure Managers |
| Companies Covered | Siemens AG, Thales Group, Hitachi Ltd., DENSO Corporation, Kapsch TrafficCom AG, Cubic Corporation, EFKON GmbH, Indra Sistemas, TomTom International BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Transportation System (ITS) Market Shifts & Advancements
Edge computing architectures are redistributing data processing from centralized cloud nodes to roadside units, slashing latency for safety-critical collision avoidance applications. This shift is compressing hardware form factors and rewriting software stack requirements.
Computer vision algorithms embedded in traffic camera networks are automating incident detection, wrong-way driver identification, and pedestrian conflict prediction. State departments of transportation in California and Texas are deploying these systems at high-fatality interchange corridors. The technology is automating response dispatch decisions that previously required human operator judgment, compressing emergency services arrival times.
The EU F-Gas Regulation is phasing down hydrofluorocarbon coolants used in thermal imaging sensors, forcing manufacturers to redesign infrared detection modules with alternative refrigerants or solid-state alternatives. German sensor suppliers are absorbing compliance costs through engineering redesign rather than supply chain relocation. Rail-integrated ITS platforms face the steepest cost adjustments due to extended operating temperature requirements.
Fleet operators are consolidating vendor relationships under performance-based service contracts that tie payments to congestion reduction metrics and fuel efficiency gains. Logistics buyers in the Benelux region are displacing transactional hardware procurement with ten-year managed service agreements. This restructuring concentrates purchasing power among large commercial transport operators and marginalizes small municipal suppliers.
Global Intelligent Transportation System (ITS) Market Segmentation
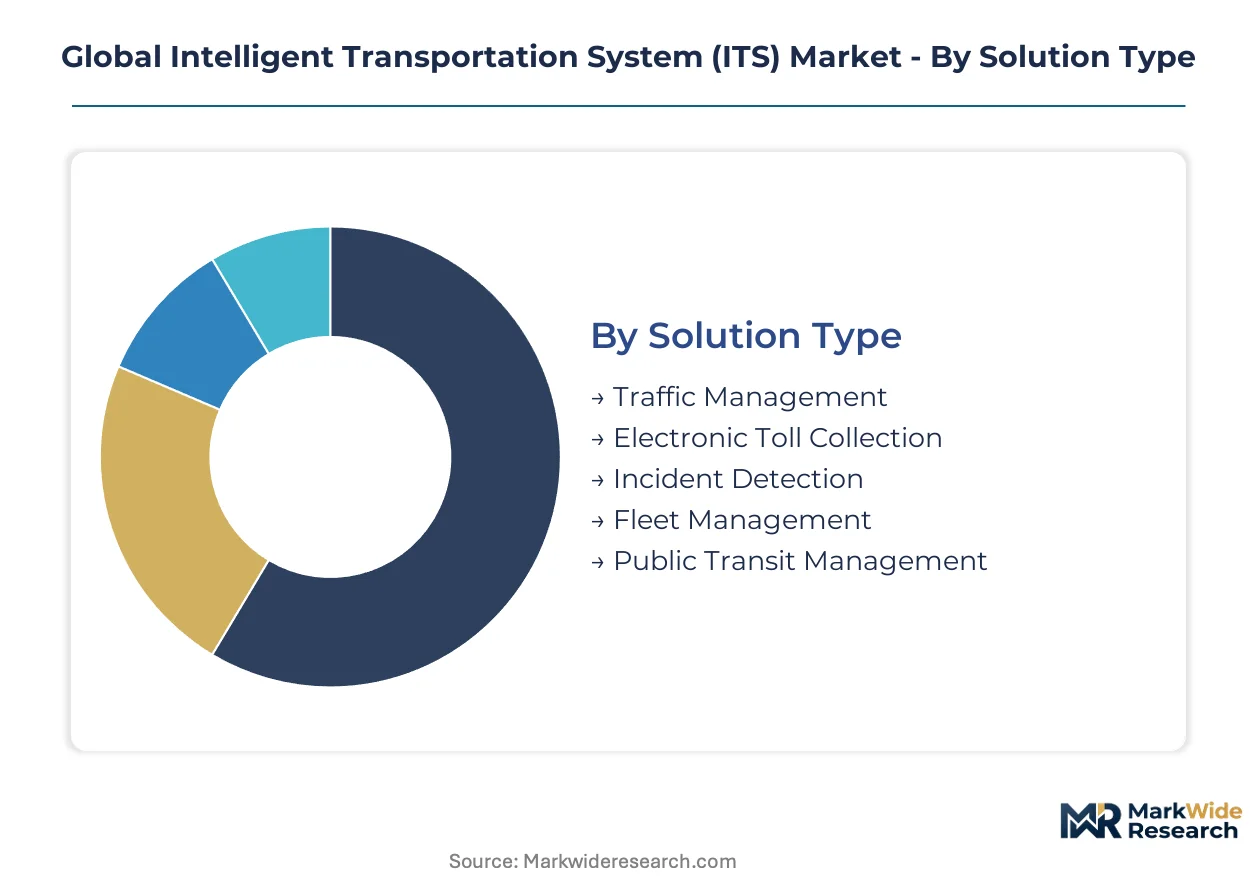
ITS procurement decisions hinge on interoperability requirements, legacy infrastructure compatibility, and measurable congestion reduction outcomes. Municipal buyers evaluate segments through total cost of ownership lenses spanning hardware deployment, software licensing, and decade-long maintenance obligations.
Solution Type:
Municipal procurement consolidation favors vendors bundling hardware, software, and analytics under unified service agreements.
- Traffic Management:Integrated signal control platforms process real-time sensor feeds to optimize intersection timing and corridor flow. German federal highway digitization programs and California DOT deployments anchor demand concentration as cities replace electromechanical controllers with adaptive systems.
- Fleet Management:Commercial vehicle telematics platforms combine GPS tracking, fuel monitoring, and regulatory compliance automation for logistics operators. Benelux logistics buyers are displacing transactional procurement with ten-year performance contracts tied to congestion reduction metrics.
- Electronic Toll Collection:Multi-lane free-flow tolling systems eliminate physical plaza infrastructure.
- Incident Detection:Automated collision identification systems dispatch emergency services without operator intervention.
- Public Transit Management:Real-time passenger information and priority signaling systems for bus and rail networks.
Volume sits with Traffic Management; growth tilts toward Fleet Management.
Technology:
Technology selection follows regulatory spectrum commitments and latency requirements for safety-critical applications.
- Vehicle-to-Infrastructure Communication:Cooperative intelligent transport systems enable real-time data exchange between roadside units and connected vehicles through C-V2X or DSRC protocols. Germany's Autobahn GmbH digital corridor pilots and South Korean 5G network rollouts concentrate pilot deployment demand.
- Video Analytics:Edge-embedded computer vision algorithms automate incident detection, wrong-way driver identification, and pedestrian conflict prediction. Texas and California state transportation departments are deploying these systems at high-fatality interchange corridors.
- Radar:Doppler and frequency-modulated continuous-wave sensors for vehicle detection and speed measurement.
- LiDAR:Pulsed laser ranging systems for high-precision object detection and mapping.
- GPS Tracking:Satellite-based positioning for fleet location monitoring and route optimization.
Deployment volume clusters in Video Analytics; steepest expansion trajectory belongs to Vehicle-to-Infrastructure Communication.
Application:
Application prioritization reflects municipal budget cycles and federal funding program eligibility windows.
- Traffic Congestion Control:Real-time signal optimization and dynamic route guidance systems reduce urban vehicle delay. EU Green Deal binding emissions targets for urban transport are forcing metropolitan authorities in Germany and the Netherlands to prioritize deployment.
- Road Safety Enhancement:Intersection conflict warning systems and pedestrian detection networks target high-collision corridors. State departments of transportation in Texas and California allocate capital specifically to automated incident detection at fatality hotspots.
- Smart Parking:Sensor-guided space availability systems and automated payment platforms.
- Emergency Response:Automated dispatch coordination and priority preemption for first responders.
- Freight Monitoring:Commercial vehicle weight compliance and hazardous materials tracking systems.
Capital allocation concentrates in Traffic Congestion Control; Road Safety Enhancement is climbing the fastest.
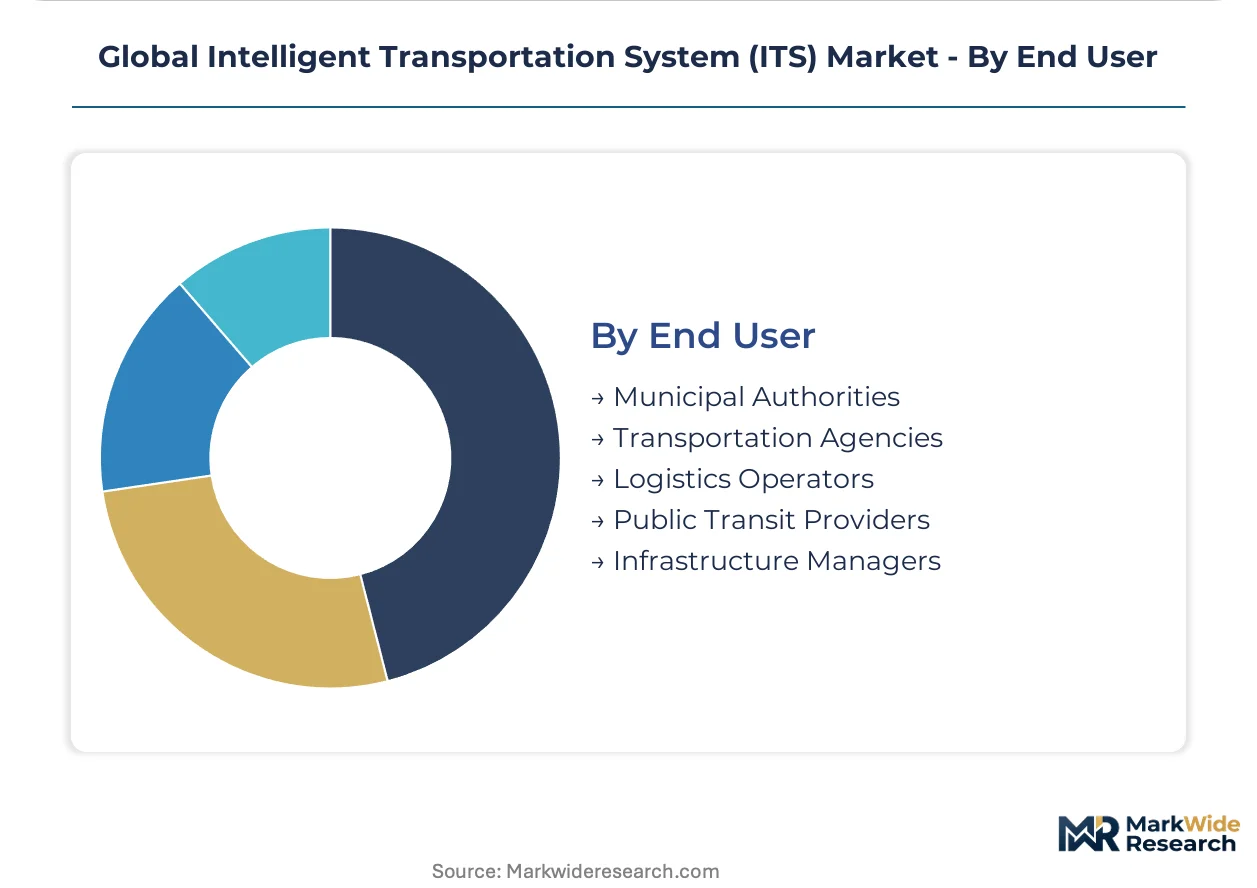
End User:
End-user purchasing power is consolidating under multi-year smart city contracts that marginalize transactional hardware vendors.
- Municipal Authorities:City governments procure integrated traffic management stacks spanning signal control, parking enforcement, and emissions monitoring. Procurement consolidation across North American and European urban corridors is compressing vendor margins while accelerating platform standardization.
- Logistics Operators:Commercial fleet operators demand fuel optimization and regulatory compliance automation with measurable return thresholds. Large Benelux transport operators are consolidating vendor relationships under performance-based service contracts.
- Transportation Agencies:State and provincial departments of transportation managing interurban highway networks.
- Public Transit Providers:Rail and bus operators requiring priority signaling and real-time passenger information.
- Infrastructure Managers:Toll road concessionaires and bridge operators maintaining revenue collection systems.
Revenue concentration rests with Municipal Authorities; Logistics Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German federal highway digitization programs channel the densest concentration of vehicle-to-infrastructure investment, while municipal procurement consolidation across North American and European urban corridors compresses vendor margins and accelerates platform standardization.
United States
State departments of transportation in California and Texas deploy computer vision systems at high-fatality interchange corridors. The U.S. Department of Transportation's ITS deployment guidelines shape product certification pathways and procurement eligibility. Dallas-Fort Worth and Los Angeles metropolitan areas anchor demand for automated incident detection and wrong-way driver identification networks.
Germany
Autobahn GmbH channels capital into digital corridor pilot projects integrating sensor arrays with centralized traffic control centers. The EU Green Deal and F-Gas Regulation force redesign of infrared detection modules with alternative refrigerants. Munich and Hamburg urban corridors concentrate deployment of cooperative intelligent transport systems through 5G C-V2X network rollouts.
China
MIIT mandates GB-standard interoperability for domestic ITS deployments, creating a parallel compliance track for foreign technology suppliers. The country's national telecommunications regulator shapes spectrum allocation decisions for dedicated short-range communications. Shenzhen and Shanghai metropolitan clusters prioritize real-time traffic analytics for megacity congestion control.
Japan
METI-connected vehicle standards accelerate fleet operator pilot programs for commercial vehicle platooning and automated yard management. Regulatory clarity on V2X interoperability enables cooperative intelligent transport system deployment. Tokyo and Osaka urban corridors concentrate demand for rail-integrated multimodal platforms at intermodal transit hubs.
India
The Ministry of Housing and Urban Affairs tenders integrated traffic management systems for 100 designated urban clusters with limited incumbent vendor presence. The country's national urban development mission expansion creates procurement opportunities for adaptive signal control platforms. Mumbai and Delhi metropolitan regions anchor smart city mission deployment of real-time congestion management infrastructure.
Global Intelligent Transportation System (ITS) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge computing architectures and AI-enabled video analytics. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with traffic management software portfolios, specialized signaling and rail-integrated platform providers, and digital infrastructure specialists extending expertise from adjacent sectors. Dominant competitive moves include multi-year smart city service agreements that bundle hardware, software, and analytics under unified contracts, and geographic expansion through regional partnership networks to meet interoperability certification requirements.
Within the diversified industrial tier, Siemens AG and Hitachi Ltd. exemplify archetypes leveraging broad technology portfolios to anchor large-scale municipal deployments. Thales Group occupies a position among specialized signaling providers targeting intermodal transit hub convergence. These three entities represent distinct strategic postures: conglomerate-backed platform breadth, rail-integrated technical depth, and digital infrastructure cross-sector extension.
| Leading Market Players |
|---|
| Siemens AG |
| Thales Group |
| Hitachi Ltd. |
| DENSO Corporation |
| Kapsch TrafficCom AG |
| Cubic Corporation |
| EFKON GmbH |
| Indra Sistemas |
| TomTom International BV |
| Others |
Supply & Pricing Matrix
Municipal procurement consolidation under multi-year smart city contracts anchors pricing power with city governments, compressing vendor margins while shifting revenue recognition toward subscription-based service agreements. This buyer concentration forces suppliers to absorb upfront hardware costs against decade-long maintenance obligations, fundamentally restructuring cash flow profiles across the competitive landscape.
Pricing Analysis
Volume concentrates in standardized traffic signal controllers where municipal budget constraints enforce commodity-like procurement, while margins persist in fleet management platforms where fuel optimization metrics justify value-based pricing. Three-tier pricing structure across premium, standard, and economy levels separates rail-integrated multimodal systems from basic intersection controllers from legacy electromechanical replacements. Cost compression in the standard tier is intensifying because semiconductor supply volatility forces suppliers to buffer inventory carrying costs. Logistics operators in the Benelux region demonstrate the lowest price sensitivity due to measurable fuel efficiency returns, whereas small municipal authorities in India's smart city clusters exhibit acute budget-driven procurement delays.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for radar and lidar sensor module fabrication, exposing deployment timelines to foundry allocation volatility. Component supply draws from German engineering for traffic control software, Chinese manufacturing for camera hardware, and Japanese precision optics for infrared detection modules. Tariff exposure runs through cross-border semiconductor shipments amid evolving trade policy frameworks. Distribution runs through systems integrators that bundle hardware procurement with installation services and long-term maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Intelligent Transportation System Market functions as a vertical-integration race where control over edge computing chip design and embedded software stacks determines margin retention. Players are pursuing backward integration into sensor manufacturing to escape foundry queue dependency.
For Market Incumbents:Cement platform stickiness through multi-year municipal service agreements that bundle predictive maintenance analytics with hardware refresh cycles. Deepen in-house production of edge computing modules to reduce exposure to Taiwan semiconductor allocation volatility. Threat substitution from AI-native video analytics startups demands accelerated R&D investment in computer vision algorithm development.
For New Entrants and Emerging Players:Enter via India's Ministry of Housing and Urban Affairs tender pipeline for 100 designated smart city clusters where incumbent presence remains thin. Target fleet management applications for commercial vehicle platooning where performance-based contracting creates vendor-switching opportunities. Pursue partnership-based go-to-market models with established systems integrators to bypass lengthy interoperability certification timelines.
For Investors and Strategic Acquirers:The window for entry favors edge computing architecture specialists with proven latency reduction capabilities in safety-critical applications. Long-term viability hinges on regulatory clarity spectrum allocation for C-V2X versus DSRC protocols across major markets. Watch for federal highway digitization program funding authorization as the primary inflection indicator for infrastructure deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Siemens AG leverages traffic management software to anchor unified municipal deployments across German urban corridors. |
| Acquisition of Specialist Firm | Computer vision algorithm developers enable automated incident detection capabilities for California DOT safety corridors. |
| Strategic Partnership | Telecommunications carriers in South Korea prioritize 5G spectrum allocation for vehicle-to-infrastructure communication networks. |
| Geographic Expansion | Regional partnership networks satisfy GB-standard compliance requirements for foreign suppliers accessing China's MIIT-mandated deployments. |
| Product Launch | Rail-integrated multimodal platforms address convergence demand at Tokyo and Osaka intermodal transit hubs. |
Research Methodology
Multi-period observation of municipal procurement contract awards, federal highway digitization program allocations, and telecommunications carrier spectrum deployment anchored the trend analysis, supplemented by interviews with traffic management systems procurement officers, state DOT planning directors, fleet operator logistics executives, and smart city program managers. Secondary validation drew from EU Green Deal implementation tracking, F-Gas Regulation compliance filings, METI-connected vehicle standard publications, and MIIT GB-standard certification databases. Bottom-up deployment pipeline tracking and top-down infrastructure investment flow analysis enabled triangulation across data sources.
Input-output matrix modeling connected solution-type deployment volumes with technology adoption curves and end-user procurement consolidation patterns across the projection horizon. Segmentation dimensions included solution type, communication protocol, application priority, and regional regulatory cluster. CAGRs were derived from infrastructure investment commitment trajectories and technology substitution elasticity estimates. Forecast inputs incorporated 5G network rollout schedules and semiconductor foundry capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory protocol fragmentation scenarios and geopolitical trade policy shifts. Forecasts reflect documented assumptions regarding municipal budget cycle continuity and federal funding program eligibility stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Telematics in Automotive Market
Telematics and Infotainment
V2X Communication Module Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Edge Computing in Automotive Market