
 Vehicle Analytics Market | 2026-2036
Vehicle Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Analytics Market Analysis
The EU Green Deal is shifting demand toward emissions-monitoring vehicle analytics platforms across European commercial fleets. Geotab Inc. leverages its cloud-native architecture to capture fleet telematics data at scale across multiple jurisdictions. IBM Corporation anchors its position through AI-driven predictive maintenance algorithms that process sensor streams from connected vehicles. SAP SE differentiates by embedding vehicle analytics into broader enterprise resource planning workflows for logistics customers.
Vehicle analytics encompasses the collection, processing, and interpretation of operational data from connected vehicles using telematics devices, onboard diagnostics, and external sensor networks to optimize fleet performance, driver safety, and asset utilization. The technology layer spans telematics infrastructure, AI analytics engines, IoT sensor arrays, and machine learning models that translate raw vehicle signals into actionable operational intelligence. Fleet management solutions currently occupy the largest solution type segment due to established commercial fleet digitization, while predictive maintenance applications are gaining traction fastest as OEMs seek to reduce unplanned downtime through algorithmic failure prediction. Cloud deployment models dominate new implementations, though edge computing architectures are emerging for latency-sensitive applications such as real-time driver behavior intervention.
The EPA enforces emissions reporting standards that compel US fleet operators to adopt verified telematics systems for regulatory compliance documentation. EMA and EU Green Deal frameworks across Europe mandate CO2 monitoring and verification protocols that directly shape product requirements for analytics platforms serving cross-border logistics. NHTSA safety regulations in the United States further steer investment toward driver behavior analytics with crash avoidance and fatigue detection capabilities. Stakeholders must evaluate whether their data architectures can accommodate diverging regional compliance specifications without fragmenting platform development roadmaps.
Market Dynamics
Fleet digitization mandates are compressing deployment timelines for connected vehicle platforms, as commercial operators face simultaneous pressure from emissions compliance deadlines and insurance cost optimization requirements.
Growth Catalysts
- EU Green Deal mandates:CO2 monitoring protocols are compelling logistics providers across Germany, France, and the Netherlands to install verified telematics systems for cross-border freight documentation.
- Predictive maintenance algorithms:Machine learning models processing sensor streams from heavy-duty trucks are reducing unplanned downtime for long-haul fleet operators.
- Edge computing architectures:Latency-sensitive driver behavior intervention systems are enabling real-time safety alerts in commercial vehicles operating on high-speed corridors.
Market Restraints
- Semiconductor supply concentration:Telematics control unit production depends on chip fabrication capacity concentrated in Taiwan and South Korea, creating procurement bottlenecks for fleet-scale deployments.
- Cellular connectivity cost volatility:Data transmission expenses for continuous vehicle monitoring fluctuate with roaming agreements across jurisdictions, compressing margins for multi-national fleet operators.
- Legacy fleet integration friction:Pre-OBD-II commercial vehicles require aftermarket hardware retrofits that increase total cost of ownership for aging asset bases.
Strategic Opportunities
- Underpenetrated last-mile delivery:Small parcel carriers in India and Brazil lack unified analytics platforms, creating whitespace for cloud-native fleet management solutions.
- Autonomous vehicle data monetization:Sensor fusion from LiDAR and camera arrays is converging with fleet telematics to generate high-definition mapping datasets for logistics optimization.
- EMA pharmacovigilance spillover:Cold chain transport regulations for temperature-sensitive pharmaceuticals are creating demand for integrated cargo-environment analytics in European healthcare logistics.
Industry Challenges
- Embedded systems cybersecurity certification:UN ECE R155 compliance timelines for vehicle type approval are stretching engineering resources at telematics hardware vendors.
- Data science talent scarcity:Fleet operators struggle to recruit machine learning engineers capable of translating raw CAN bus signals into actionable maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Analytics Market |
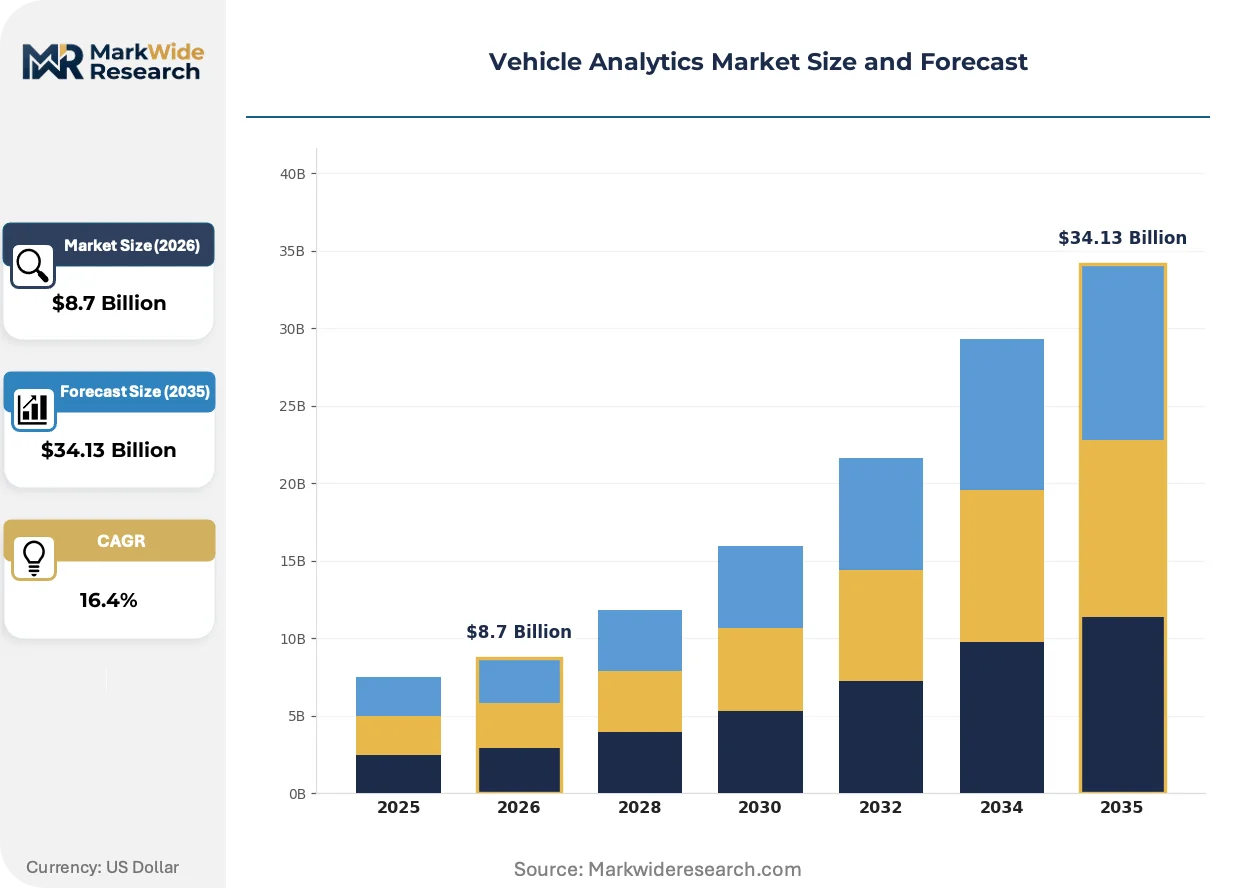
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Fleet Management, Driver Behavior, Predictive Maintenance, Usage-Based Insurance Technology: Telematics, AI Analytics, IoT Sensors, Machine Learning Deployment Model: Cloud, On-Premises, Hybrid, Edge Computing End User: Transportation, Logistics, Insurance, Fleet Operators |
| Companies Covered | Geotab Inc., Verizon Communications Inc., TomTom International B.V., MiX Telematics Limited, SAP SE, IBM Corporation, Genetec Inc., HARMAN International Industries Inc., Teletrac Navman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Analytics Market Emerging Trajectories
Artificial intelligence inference is migrating from cloud data centers toward vehicle-mounted hardware, reshaping how fleet operators balance computational latency against infrastructure costs.
Digital twin modeling for commercial vehicles is converging with physics-based degradation simulation to forecast component failure before sensor anomalies trigger alerts. Heavy-duty truck manufacturers in North America are embedding these capabilities directly into powertrain control modules. This convergence is compressing the window between predictive maintenance recommendations and actual service interventions, reducing roadside breakdown frequency.
The EPA's SmartWay program is tightening emissions verification requirements for freight carriers seeking fuel efficiency certifications. Fleet operators must now submit telematics-derived documentation rather than self-reported fuel logs. Long-haul trucking segments serving California ports are accelerating hardware refresh cycles to meet CARB compliance deadlines.
Usage-based insurance pricing is displacing fixed premium models for commercial auto coverage, with underwriters demanding granular telematics data on harsh braking, acceleration, and cornering events. Fleet managers in the United Kingdom are consolidating vendor relationships to reduce data fragmentation across multiple insurer portals. This behavioral shift is most visible among mid-size logistics providers with 50-200 vehicle fleets seeking rate optimization.
Vehicle Analytics Market Segmentation
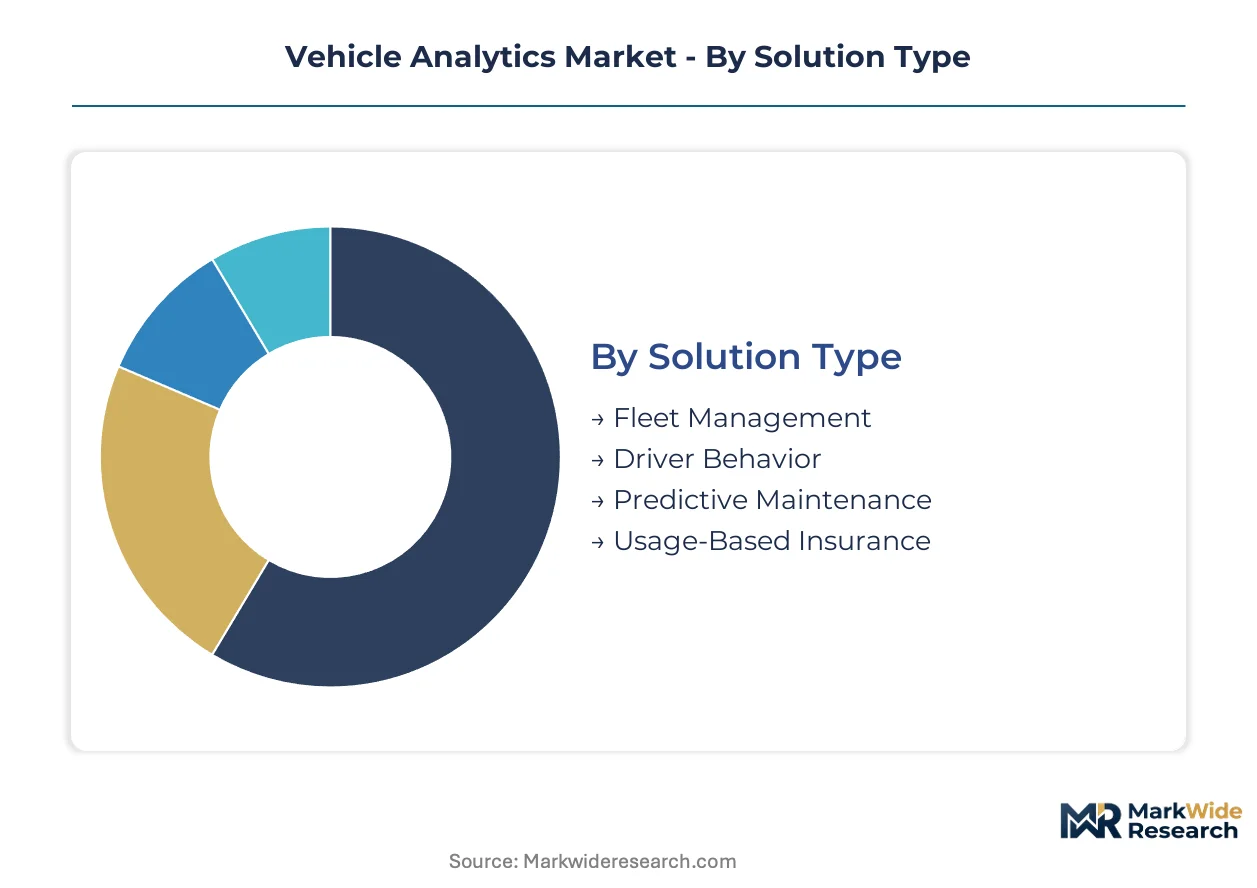
Vehicle analytics vendors structure their portfolios around four distinct axes that shape procurement decisions. Solution type determines whether buyers prioritize operational efficiency, safety compliance, or risk transfer. Technology and deployment choices reflect IT maturity and latency tolerance. End-user segmentation reveals diverging feature requirements between asset-heavy operators and data-centric intermediaries.
Solution Type:
Fleet operators select solutions based on whether their primary pain point centers on asset visibility, human risk, mechanical failure, or financial exposure.
- Fleet Management:Real-time location tracking, route optimization, and fuel consumption monitoring form the core capability set. Demand concentrates among German and Dutch logistics providers facing EU Green Deal documentation requirements for cross-border freight. Established commercial digitization has made this the most penetrated segment, though margin compression from commoditized telematics hardware is accelerating vendor consolidation.
- Predictive Maintenance:Algorithmic processing of vibration, temperature, and pressure sensor streams forecasts component degradation before failure. North American heavy-duty truck operators deploy these systems to minimize unplanned downtime on long-haul corridors. OEMs are embedding these capabilities directly into powertrain control modules, reshaping aftermarket service relationships.
- Driver Behavior:Harsh event detection, fatigue monitoring, and coaching workflows target insurance cost reduction. UK mid-size fleets with 50-200 vehicles are consolidating vendor relationships to satisfy usage-based insurance data requirements.
- Usage-Based Insurance:Granular telematics feeds enable dynamic premium pricing based on actual risk exposure rather than demographic proxies. Underwriters in the United States are mandating these data streams for commercial auto coverage renewals.
Volume sits with Fleet Management; growth tilts toward Predictive Maintenance.
Technology:
Technology selection separates buyers with legacy fleet investments from those building greenfield connected vehicle architectures.
- Telematics:GPS positioning, cellular connectivity, and OBD-II data extraction provide foundational vehicle-to-cloud communication. Pre-OBD-II commercial vehicles in aging North American fleets require aftermarket retrofits that increase total cost of ownership. Telematics control unit production faces procurement bottlenecks from semiconductor fabrication concentration in Taiwan and South Korea.
- AI Analytics:Cloud-native inference engines process aggregated fleet data to identify operational patterns. Cloud deployment models dominate new implementations, though latency-sensitive applications are pushing inference toward edge architectures. Data science talent scarcity constrains fleet operators from translating raw CAN bus signals into actionable maintenance schedules.
- IoT Sensors:External temperature, humidity, and cargo-condition monitors extend analytics beyond vehicle mechanics. European healthcare logistics operators deploy these for EMA pharmacovigilance compliance in cold chain pharmaceutical transport.
- Machine Learning:Supervised and unsupervised models improve prediction accuracy as training datasets scale across multi-jurisdictional fleets. Physics-based degradation simulation is converging with digital twin modeling to compress the window between maintenance recommendations and service interventions.
Telematics commands current deployment volume; AI Analytics is climbing the fastest as cloud infrastructure matures.
Deployment Model:
Infrastructure strategy hinges on whether analytics priorities favor computational scale, data sovereignty, or millisecond response times.
- Cloud:Centralized data lakes enable cross-fleet benchmarking and model training at scale. Cloud-native architectures from vendors like Geotab capture telematics data across multiple jurisdictions without on-premises hardware investment.
- On-Premises:Local server deployments satisfy data residency requirements in regulated industries. Insurance and healthcare logistics segments favor this model for sensitive driver and cargo records.
- Hybrid:Partitioned architectures process sensitive data locally while pushing anonymized aggregates to cloud analytics engines. This configuration is gaining traction among multinational fleet operators navigating divergent regional compliance specifications.
- Edge Computing:Vehicle-mounted inference hardware enables real-time driver behavior intervention without cellular latency. High-speed corridor operators in Germany and the United States are piloting these systems for crash avoidance applications.
Cloud dominates new implementations; Edge Computing is gaining share fastest where safety-critical latency thresholds apply.
End User:
Buyer category determines whether analytics procurement serves direct operational control or intermediary risk assessment.
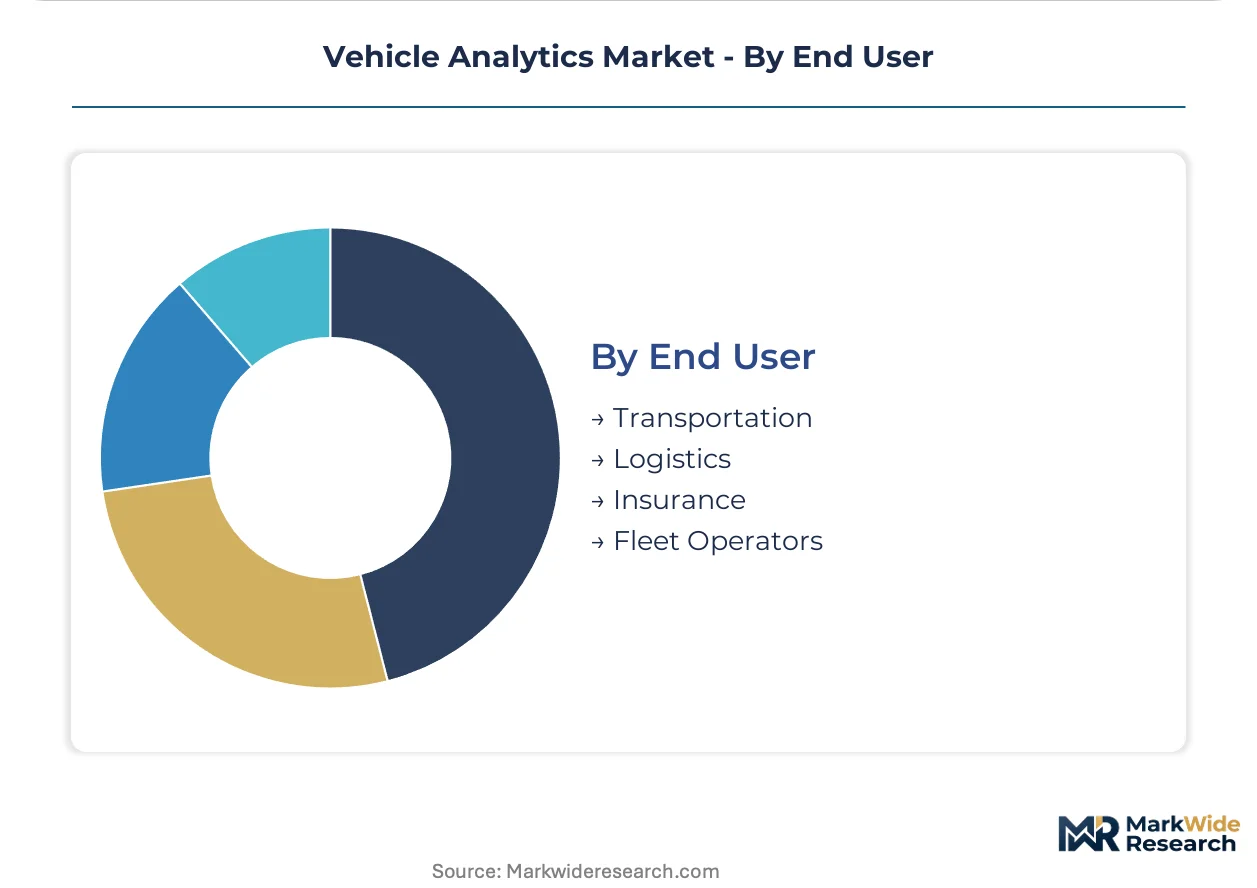
- Transportation:Passenger and freight carriers prioritize route efficiency, on-time performance, and regulatory compliance documentation. EPA SmartWay program participants in the United States must submit telematics-derived emissions verification rather than self-reported fuel logs.
- Logistics:Third-party providers integrate analytics into customer-facing service level agreements. Small parcel carriers in India and Brazil present whitespace opportunities for unified cloud-native platforms.
- Insurance:Underwriters consume telematics data for risk pricing and claims verification. Fixed premium models are displacing toward granular behavioral pricing based on harsh braking, acceleration, and cornering event frequency.
- Fleet Operators:Asset owners balance total cost of ownership against uptime guarantees. Semiconductor supply concentration and cellular roaming cost volatility compress margins for fleet-scale deployments across multiple jurisdictions.
Fleet Operators represent the largest addressable base; Insurance is expanding most quickly as usage-based pricing displaces traditional underwriting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors commercial fleet analytics adoption as German automotive OEMs integrate telematics into connected vehicle architectures. The EU Green Deal's emissions mandates are reshaping procurement patterns across European logistics corridors.
United States
Long-haul trucking operators deploy predictive maintenance algorithms to minimize unplanned downtime on interstate corridors. The EPA's SmartWay program now mandates telematics-derived emissions documentation rather than self-reported fuel logs. California port operators are accelerating hardware refresh cycles to meet CARB compliance deadlines.
Germany
Commercial fleet managers in the Rhine-Ruhr industrial belt prioritize driver behavior analytics for insurance cost optimization. The EU Green Deal's CO2 monitoring protocols compel cross-border freight operators to install verified telematics systems. Munich-based automotive suppliers are embedding AI analytics directly into powertrain control modules.
United Kingdom
Mid-size logistics providers with 50-200 vehicle fleets consolidate vendor relationships to satisfy usage-based insurance data requirements. NHTSA-equivalent safety regulations steer investment toward fatigue detection and crash avoidance capabilities. London's last-mile delivery sector shows accelerating cloud-native platform adoption.
Netherlands
Rotterdam-Europoort logistics hubs demand integrated cargo-environment analytics for cold chain pharmaceutical transport under EMA pharmacovigilance rules. Cross-border freight operators face compressed deployment timelines from simultaneous emissions compliance and insurance optimization pressures. Amsterdam-based fleet operators pilot edge computing architectures for real-time driver intervention.
India
Small parcel carriers in Mumbai and Bengaluru lack unified analytics platforms, creating whitespace for cloud-native fleet management solutions. The country's national logistics regulator is tightening commercial vehicle tracking mandates for interstate freight. Hyderabad's technology corridor hosts emerging telematics service providers targeting underpenetrated last-mile segments.
Vehicle Analytics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across data infrastructure sophistication and regulatory certification depth. The vendor base clusters around three strategic archetypes: cloud-native telematics platforms, enterprise software integrators, and automotive OEM-embedded systems providers. Consolidation pressure is intensifying as commoditized hardware margins accelerate vendor rollup activity. Dominant competitive moves include strategic partnerships with cellular network operators and vertical integration into edge computing hardware.
Within the cloud-native platform tier, Geotab Inc. and MiX Telematics Limited exemplify vendors capturing fleet telematics data at scale across multiple jurisdictions. IBM Corporation anchors the enterprise AI analytics segment through predictive maintenance algorithm development. SAP SE occupies a position bridging vehicle analytics with broader enterprise resource planning workflows for logistics customers.
| Leading Market Players |
|---|
| Geotab Inc. |
| Verizon Communications Inc. |
| TomTom International B.V. |
| MiX Telematics Limited |
| SAP SE |
| IBM Corporation |
| Genetec Inc. |
| HARMAN International Industries Inc. |
| Teletrac Navman |
| Others |
Supply Flow & Price Mechanics
Semiconductor spot price indices for automotive-grade chips cascade through telematics hardware manufacturing into three distinct pricing tiers for fleet analytics platforms, with EU Green Deal compliance certification commanding premium positioning against uncertified alternatives.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for predictive maintenance solutions, where North American heavy-duty truck operators pay premiums tied to guaranteed vehicle availability rather than per-device fees. Three-tier pricing structure across premium, standard, and economy levels separates OEM-embedded systems from aftermarket telematics and basic GPS tracking. Cost compression in the economy tier intensifies because commoditized hardware margins are accelerating vendor consolidation. Small parcel carriers in emerging markets exhibit highest price sensitivity, while German automotive OEMs prioritize certification depth over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 automotive suppliers mandate multi-supplier qualification for telematics control units, forcing fleet-scale buyers to maintain relationships across Taiwan, South Korea, and Japan. Raw material dependencies center on automotive-grade semiconductors, lithium-ion power cells, and cellular modem chipsets. Single-source vulnerability concentrates in Taiwan's foundry capacity for vehicle-grade processors. Distribution runs through OEM captive channels, aftermarket installer networks, and direct enterprise sales to multinational fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication bottlenecks for automotive-grade chips prop pricing power for vendors with secured foundry allocation, creating supply-constrained conditions that favor incumbents with established supplier relationships.
For Market Incumbents: Extend cloud-native platform capabilities into edge computing hardware to capture latency-sensitive safety applications before specialized chip vendors enter the driver intervention segment. Backward integration into semiconductor procurement through long-term foundry agreements defends against Taiwan capacity constraints threatening fleet-scale deployment timelines.
For New Entrants and Emerging Players: Capture whitespace in India's underpenetrated last-mile delivery segment where Mumbai and Bengaluru small parcel carriers lack unified analytics infrastructure. Cloud-native fleet management solutions with localized cellular roaming partnerships offer the strongest go-to-market angle against incumbent global platforms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated telematics hardware vendors with captive semiconductor supply in South Korea and Japan during foundry allocation crunches. Long-term viability hinges on regulatory certification depth across EPA SmartWay and EU Green Deal frameworks. Watch for CARB compliance deadline acceleration as the inflection signal for hardware refresh cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Integration | Vehicle-mounted inference chips enable millisecond driver alerts without cellular latency. |
| EMA Pharmacovigilance Certification | Cold chain cargo-environment analytics unlock European healthcare logistics contracts. |
| Cellular Roaming Partnership Expansion | Multi-jurisdiction data agreements reduce cost volatility for cross-border fleet operators. |
| Predictive Maintenance Algorithm Licensing | OEM powertrain module embedding reshapes aftermarket service revenue streams. |
| Usage-Based Insurance Data Integration | Granular telematics feeds enable dynamic premium pricing for commercial auto underwriters. |
Methodological Framework
SEC filings from telematics vendors, EPA SmartWay program documentation, and EU Green Deal regulatory databases formed the secondary backbone, supplemented by customs records for telematics hardware trade flows. Primary interviews with fleet operations directors, automotive OEM platform engineers, cellular network procurement leads, and insurance underwriter data strategists validated demand assumptions. Bottom-up and top-down triangulation reconciled equipment shipment data against enterprise software licensing disclosures.
Bottom-up modeling aggregated telematics control unit volumes, cloud subscription tiers, and professional services attach rates across deployment models, end-user segments, and regional regulatory clusters. Top-down validation cross-checked aggregate spend patterns against fleet operator IT budget surveys. CAGRs derived from logistic curve adoption modeling for connected vehicle platforms, with sensor data velocity and machine learning inference costs as key forecast inputs across the analysis window.
The model holds under stable semiconductor foundry allocation and cellular roaming tariff regimes; deviation in Taiwan capacity constraints or EU emissions verification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Subscription Services Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Car Subscription Market
Automotive Services
Americas MAP Market
Automotive Services
Motorsports Market
Automotive Services
Automotive Retail Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
Mobility Scooters Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Tow Truck Market
Automotive Services
Driver's License Market
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
GCC Car Rental Market
Automotive Services
US Quick Lube Equipment Market