
 Traffic Jam Assist (TJA) Market | 2026-2036
Traffic Jam Assist (TJA) Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Jam Assist (TJA) Market Analytics
Modular sensor bundling is recalibrating how OEMs configure Traffic Jam Assist packages across vehicle trim levels. Robert Bosch GmbH leverages its integrated radar-camera production to anchor supply contracts with European mass-market brands. Continental AG dominates ultrasonic sensor integration for low-speed congestion scenarios. Mobileye Global Inc. competes through proprietary EyeQ chip architectures that consolidate perception processing.
Traffic Jam Assist constitutes a Level 2 partial automation system that fuses radar, camera, and ultrasonic inputs to execute longitudinal and lateral vehicle control below approximately 60 km/h in dense traffic. Its primary purpose is to reduce driver workload during stop-and-go congestion while maintaining safe following distances and lane positioning. Camera Systems capture the fastest-growing technology share as OEMs prioritize visual lane-keeping fidelity over pure radar solutions. Passenger Cars represent the deepest margin pool, though Fleet Operators are scaling faster as logistics companies automate urban delivery routes.
NHTSA, the EU's General Safety Regulation framework, and Japan's METI each mandate automatic emergency braking and lane-keeping as baseline requirements for new vehicle type approvals. These rules compress adoption timelines by removing TJA's optional status in major automotive markets. Stakeholders must monitor how software-defined vehicle architectures reshape hardware supplier relationships as automakers pursue in-house perception stack development.
Market Dynamics
Sensor fusion architectures are forcing wholesale redesigns of Traffic Jam Assist hardware stacks as automakers consolidate perception processing onto centralized compute platforms.
Growth Catalysts
- NHTSA crash-avoidance mandates:Updated federal requirements for automatic emergency braking and lane-keeping assistance are removing TJA's optional status in the United States, compressing OEM adoption timelines.
- Urban fleet automation:Logistics operators deploying automated urban delivery vehicles are specifying TJA as baseline equipment for last-mile route efficiency.
- Camera-first perception:Visual lane-keeping fidelity is displacing radar-dominant configurations as OEMs prioritize high-resolution imaging for congested-scenario accuracy.
Market Restraints
- Lidar cost structure:Solid-state lidar units remain prohibitively expensive for mass-market TJA bundling, constraining Level 2+ feature penetration below premium segments.
- German supply concentration:Bosch, Continental, and ZF anchor European tier-1 sensor supply, creating geographic vulnerability to regional production disruptions.
- Edge-case perception failures:Adverse weather and construction-zone ambiguity continue degrading camera-reliant systems below human-equivalent reliability thresholds.
Strategic Opportunities
- Software-defined vehicle architectures:Centralized compute platforms are enabling automakers to decouple hardware refresh cycles from feature upgrade paths, opening recurring revenue models.
- EU General Safety Regulation tailwind:Mandated lane-keeping and intelligent speed assistance for all new vehicle types from 2024 is standardizing TJA as baseline equipment across European mass-market brands.
- India urban congestion:Stop-and-go traffic density in metropolitan corridors creates addressable white space for localized TJA calibration targeting two-wheeler intrusion scenarios.
Industry Challenges
- Functional safety certification:ISO 26262 ASIL-D compliance for braking actuation systems extends development timelines and strains validation budgets.
- Perception-stack talent scarcity:Deep-learning optimization for embedded automotive processors commands premium compensation, constraining supplier engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Jam Assist (TJA) Market |
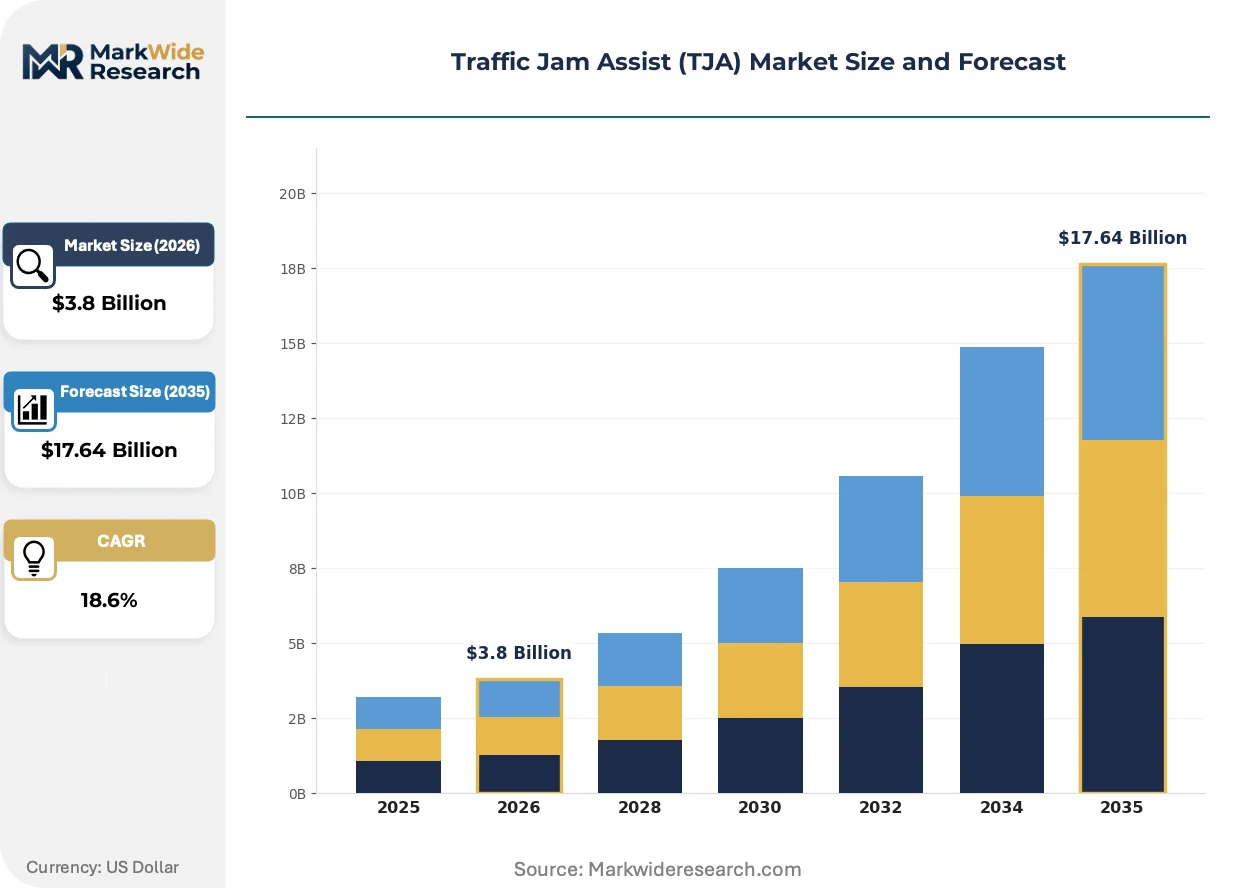
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Automatic Emergency Braking, Lane Keep Assist, Collision Avoidance End User: Commercial Vehicles, Passenger Cars, Fleet Operators, Ride-Sharing Services Technology: Radar Systems, Lidar Systems, Camera Systems, Ultrasonic Sensors Application: Urban Driving, Highway Driving, Autonomous Driving, Driver Assistance |
| Companies Covered | Denso Corporation, Toyota Motor Corporation, Robert Bosch GmbH, Delphi Technologies PLC, Hyundai Motor Company, Continental AG, Volkswagen AG, Mobileye Global Inc., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Jam Assist (TJA) Market Evolving Landscape
Computational consolidation and regulatory harmonization are compressing hardware diversity while expanding software-defined feature upgradeability across vehicle lifecycles.
Camera-centric perception is overtaking radar-first architectures in TJA system design. Multi-megapixel imaging sensors paired with neural-network lane detection deliver superior edge-case performance in faded markings and construction zones. European mass-market OEMs are adopting this stack fastest, collapsing the historical radar-camera sensor redundancy that dominated Level 2 deployments.
EU's General Safety Regulation framework is mandating intelligent speed assistance and lane-keeping systems as baseline for all new vehicle type approvals from 2024. This regulatory compression eliminates TJA's optional status across the European market, forcing tier-1 suppliers to standardize hardware configurations. Mass-market passenger car segments face the steepest compliance-driven cost absorption.
Fleet procurement specifications are unbundling TJA from full ADAS suites as logistics operators seek modular automation for urban delivery routes. Tier-1 suppliers now face direct commercial vehicle OEM relationships that bypass traditional passenger car platform negotiations. Germany and the Netherlands demonstrate the strongest fleet-driven specification divergence from retail consumer packaging.
Traffic Jam Assist (TJA) Market Segmentation
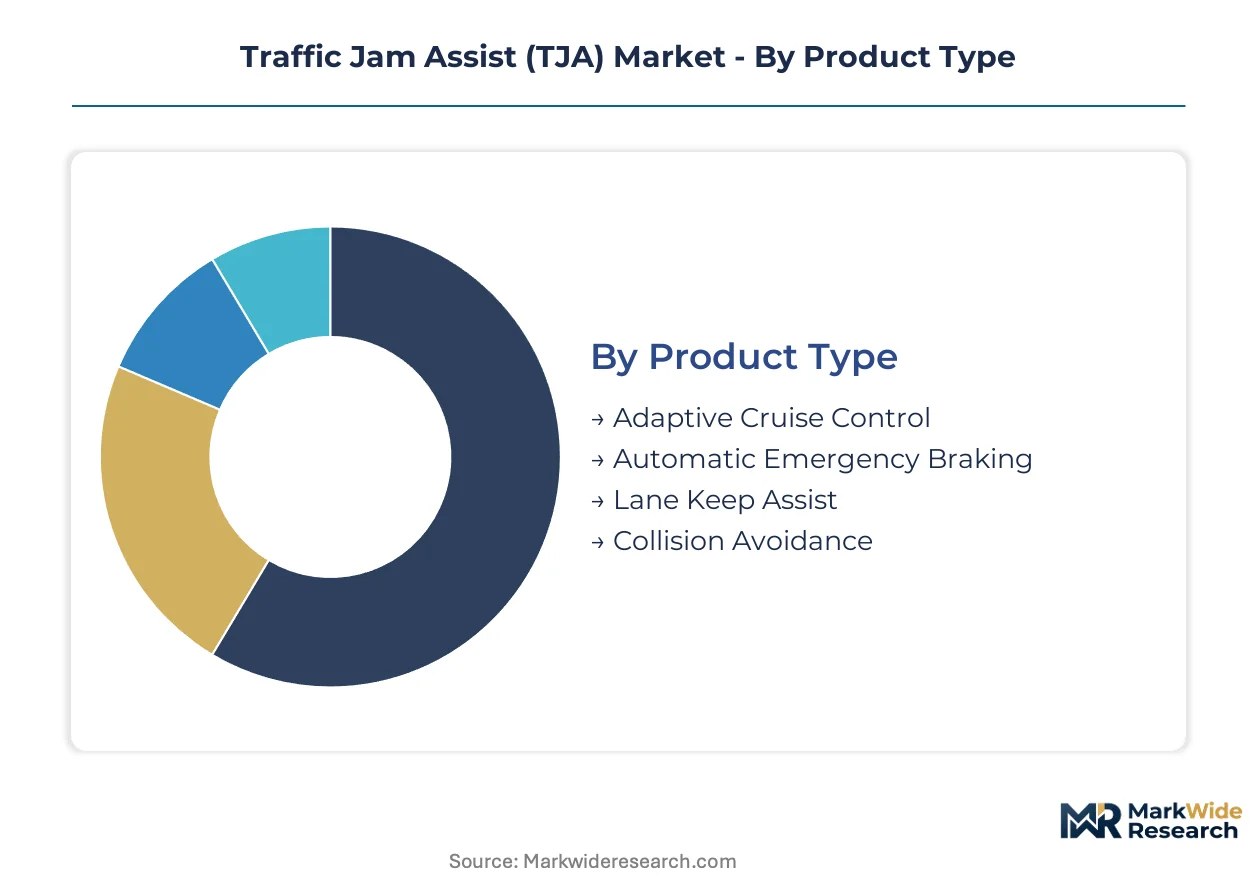
Traffic Jam Assist configurations diverge sharply between embedded ADAS bundles and standalone modules, with integration depth determining sensor selection, compute requirements, and OEM pricing flexibility. Understanding these segment boundaries clarifies where tier-1 suppliers retain design control versus where automakers internalize perception stacks.
Product Type:
Standalone modules command premium positioning in retrofit and fleet aftermarket channels, while embedded variants dominate factory-installed production lines.
- Adaptive Cruise Control:Fuses radar or camera inputs to modulate vehicle speed relative to traffic flow, maintaining safe following distances in congested corridors. German mass-market OEMs specify this as the baseline TJA anchor in European platform architectures.
- Lane Keep Assist:Executes lateral control through camera-based lane boundary detection, correcting steering when drift exceeds calibrated thresholds. Camera-first configurations from Mobileye and Bosch are displacing radar-dominant alternatives in stop-and-go scenarios.
- Automatic Emergency Braking:NHTSA mandates this as standard equipment for US type approvals, compressing optional-to-baseline transitions across all vehicle classes.
- Collision Avoidance:Integrates multi-sensor fusion to predict and mitigate imminent contact scenarios, typically bundled with higher-trim ADAS packages.
Adaptive Cruise Control leads volumes today; Lane Keep Assist is gaining share fastest.
End User:
Volume concentration shifts between retail consumers and commercial procurement, with divergent specification priorities around uptime guarantees versus feature richness.
- Passenger Cars:Premium and luxury segments absorb highest per-vehicle TJA content, though mass-market compliance mandates are standardizing baseline configurations across trim levels.
- Fleet Operators:Logistics companies specify modular TJA unbundled from full ADAS suites, prioritizing route efficiency and driver fatigue reduction over consumer-facing feature depth.
- Commercial Vehicles:Urban delivery chassis integrate TJA for last-mile automation, with direct tier-1 supplier relationships bypassing traditional passenger car platform negotiations.
- Ride-Sharing Services:Fleet-scale deployments demand high-reliability sensor configurations with minimal edge-case intervention requirements.
Fleet Operators are climbing the fastest; Passenger Cars retain the deepest margin pool.
Technology:
Sensor modality selection determines perception accuracy, cost structure, and weather resilience across deployment environments.
- Camera Systems:Multi-megapixel imaging paired with neural-network lane detection delivers superior performance in faded markings and construction zones. European OEMs are adopting this stack fastest, collapsing historical radar-camera redundancy.
- Radar Systems:Provides robust distance measurement and velocity tracking independent of lighting conditions, anchoring sensor fusion architectures in adverse weather scenarios.
- Ultrasonic Sensors:Continental dominates integration for low-speed congestion scenarios where close-proximity object detection suffices.
- Lidar Systems:Solid-state units remain prohibitively expensive for mass-market TJA bundling, constraining penetration to premium segments and robotaxi prototypes.
Camera Systems anchor new design wins; Radar Systems sustain installed-base volumes.
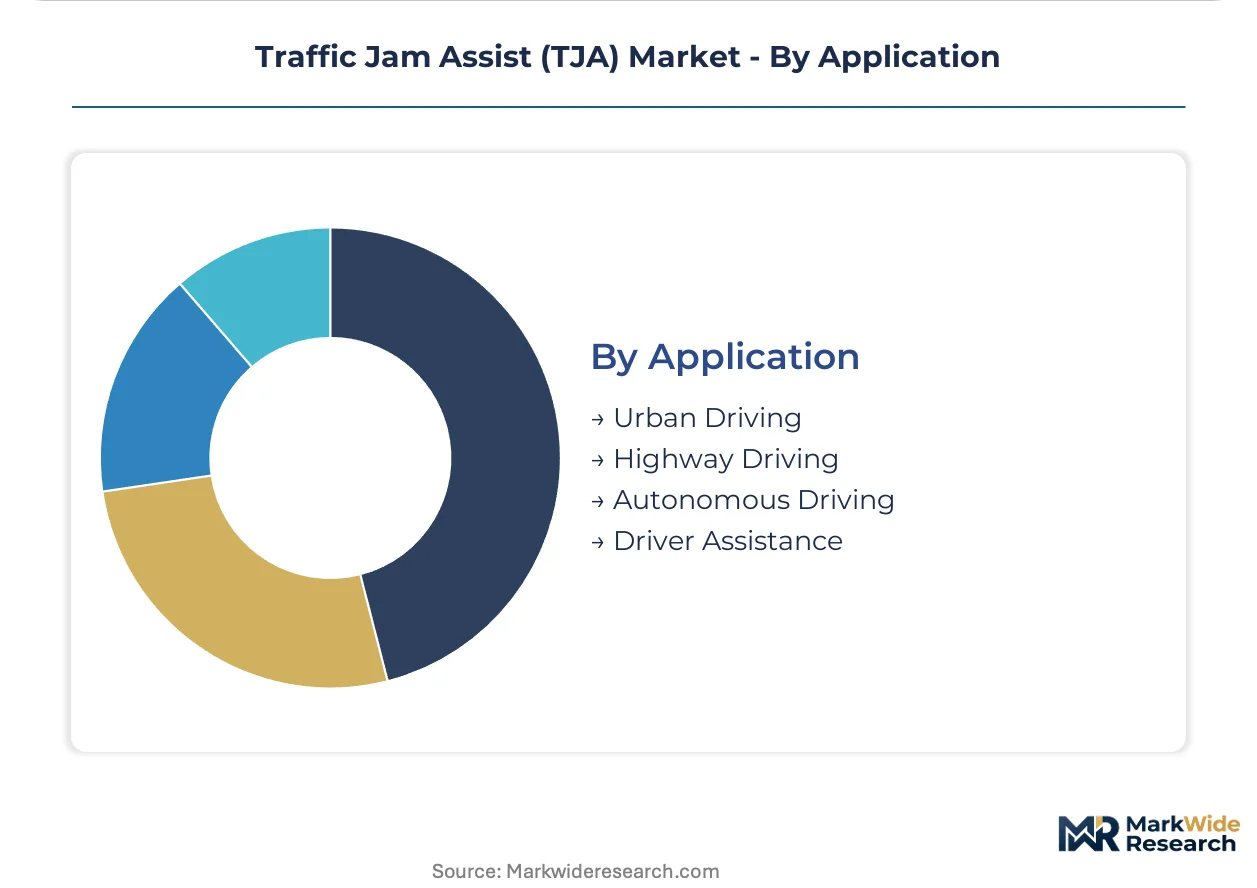
Application:
Use-case specificity dictates sensor fusion complexity, with urban scenarios demanding highest perception density.
- Urban Driving:Stop-and-go congestion below 60 km/h defines core TJA functionality, requiring tight integration of longitudinal and lateral control with frequent intervention thresholds.
- Driver Assistance:Level 2 partial automation reduces operator workload while maintaining human oversight, representing the dominant regulatory classification for current TJA deployments.
- Highway Driving:Higher-speed scenarios extend TJA-adjacent functionality into lane-centering and traffic jam chauffeur modes, though distinct from core congestion-focused systems.
- Autonomous Driving:Full self-driving stacks incorporate TJA as a subsystem module, though with redundant compute and sensor configurations exceeding standard ADAS specifications.
Urban Driving commands specification attention; Driver Assistance scales across the broadest vehicle parc.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive engineering pioneered Traffic Jam Assist integration through Bosch and Continental's early radar-camera fusion systems for European mass-market platforms. This technical foundation established the regulatory and supply-chain templates now diffusing into North American and Asian markets.
United States
NHTSA's updated automatic emergency braking mandates compress OEM adoption timelines across Detroit and foreign transplant operations. Federal Motor Vehicle Safety Standards now treat lane-keeping assistance as baseline equipment, removing optional status for MY2029 compliance. Michigan's Ann Arbor corridor hosts validation facilities where suppliers test sensor fusion against domestic traffic patterns.
Germany
Bosch, Continental, and ZF anchor tier-1 supply chains serving Volkswagen Group and BMW's premium platform architectures. EU General Safety Regulation mandates intelligent speed assistance and lane-keeping systems from 2024, standardizing TJA across mass-market segments. Stuttgart and Ingolstadt production clusters integrate camera-first perception stacks for congested autobahn scenarios.
Japan
METI's automated driving roadmaps prioritize Level 2 partial automation for urban congestion relief in Tokyo and Osaka metropolitan corridors. Domestic OEMs specify TJA for kei-car platforms where space constraints favor compact sensor packaging. Toyota City and Hiroshima manufacturing bases calibrate systems for narrow-lane stop-and-go density.
China
MIIT's intelligent vehicle standards accelerate domestic supplier development for camera-dominant perception in Shenzhen and Shanghai traffic conditions. Local OEMs bundle TJA with intelligent cockpit features targeting younger consumer segments. Yangtze River Delta electronics clusters produce multi-megapixel imaging sensors at scale for cost-competitive integration.
South Korea
MFDS automotive safety guidelines align with global crash-avoidance benchmarks while Hyundai and Kia differentiate through HMI design for Seoul's dense arterial networks. Domestic tier-1s supply radar modules for export platform variants. Busan-Ulsan manufacturing complexes integrate ultrasonic proximity detection for low-speed congestion protocols.
Traffic Jam Assist (TJA) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor fusion complexity and software-defined upgradeability. The vendor base stratifies between integrated tier-1s controlling full-stack production and specialized component suppliers feeding perception modules into OEM architectures. Three archetypes dominate: diversified automotive electronics conglomerates with captive semiconductor fabrication, vision-processing specialists licensing IP to multiple OEM programs, and diversified industrial groups leveraging cross-sector sensor expertise. Competitive moves concentrate on strategic partnerships for centralized compute platform access and geographic expansion into fleet procurement channels bypassing traditional retail distribution.
Within the diversified tier-1 tier, Robert Bosch GmbH and Continental AG exemplify integrated production spanning radar, camera, and ultrasonic modalities. Mobileye Global Inc. occupies a distinct position as a vision-processing specialist whose EyeQ architectures consolidate perception computation for multiple OEM customers. ZF Friedrichshafen AG anchors the industrial-diversified archetype through chassis-system integration capabilities that bundle TJA with steering and braking actuation hardware.
| Leading Market Players |
|---|
| Denso Corporation |
| Toyota Motor Corporation |
| Robert Bosch GmbH |
| Delphi Technologies PLC |
| Hyundai Motor Company |
| Continental AG |
| Volkswagen AG |
| Mobileye Global Inc. |
| ZF Friedrichshafen AG |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ISO 26262 ASIL-D compliant braking systems and lower-tier configurations manifests in both component pricing and supplier sourcing patterns. NHTSA mandates compress the premium tier downward while German tier-1s anchor supply contracts for validated actuation hardware.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the TJA component market. Price differentiation rests on ASIL certification grade and sensor fusion complexity, with camera-first stacks commanding premiums over radar-dominant alternatives. Cost compression in standard-tier ultrasonic modules intensifies because Continental and Bosch compete for mass-market platform slots. Fleet operators exhibit highest price sensitivity, while premium passenger car OEMs absorb certification-driven premiums with minimal negotiation leverage.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific sensor component sourcing is reshaping regional procurement strategies for European and North American automakers. Production gravity centers on Germany, China, and South Korea for radar modules, multi-megapixel imaging sensors, and EyeQ processor fabrication respectively. Raw material dependencies span silicon wafers, rare-earth magnets for lidar motors, and specialized optical glass. Single-source vulnerability concentrates in Mobileye's proprietary chip architectures. Distribution runs through tier-1 supplier direct contracts with OEM platform engineering teams, bypassing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Traffic Jam Assist market functions as a stable compounder, with regulatory mandate compression ensuring baseline equipment penetration across vehicle segments regardless of consumer preference cycles.
For Market Incumbents: Deploy software-defined architecture roadmaps to decouple hardware refresh from feature upgrade revenue. Bosch and Continental must accelerate centralized compute platform partnerships before OEMs internalize perception stacks. Defensive consolidation of ultrasonic sensor production in low-speed congestion modules counters emerging Chinese imaging suppliers. For New Entrants and Emerging Players: Camera-dominant perception algorithms optimized for two-wheeler intrusion scenarios offer the most penetrable wedge into India's urban congestion aftermarket. Target fleet procurement channels in Germany and the Netherlands where logistics operators unbundle TJA from full ADAS suites. A direct tier-1 commercial vehicle relationship bypasses passenger car platform negotiation barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where tier-1 suppliers lack software-defined vehicle architecture access and face OEM in-house development threats. Long-term viability favors vision-processing specialists with licensable IP portfolios over hardware-commoditized sensor manufacturers. Watch for OEM vertical integration announcements as the inflection signal for supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables decoupled hardware refresh cycles from feature upgrade paths for recurring revenue. |
| Sensor Fusion Platform Standardization | Reduces validation costs across Volkswagen Group and BMW multi-brand architectures. |
| Fleet Procurement Channel Expansion | Bypasses retail consumer packaging to capture logistics operator modular automation specifications. |
| Camera-First Perception R&D | Addresses edge-case performance in faded markings where radar-dominant systems fail. |
| EU General Safety Regulation Compliance | Mandates intelligent speed assistance and lane-keeping as baseline from 2024 onward. |
Research Methodology
Multiple input streams — OEM platform engineering interviews, tier-1 supplier procurement disclosures, and regulatory filing analysis — were reconciled against vehicle production databases and sensor content per vehicle estimates. Primary discussions with ADAS program managers, automotive semiconductor sourcing leads, and fleet procurement officers at logistics operators were validated through secondary sources including NHTSA Federal Motor Vehicle Safety Standards, EU General Safety Regulation technical documentation, and MIIT intelligent vehicle standards. Bottom-up component demand modeling and top-down OEM platform adoption rates were triangulated to constrain forecast variance.
Data-stream reconciliation across the projection horizon employed segmentation by vehicle class, propulsion architecture, sensor modality mix, and regional regulatory cluster. CAGRs were derived from fitted adoption curves reflecting mandate-driven baseline transitions and fleet operator specification divergence. Industry-specific forecast inputs incorporated NHTSA automatic emergency braking compliance timelines and EU intelligent speed assistance phase-in schedules.
The model holds under stable regulatory enforcement and continued OEM platform consolidation; deviation in software-defined vehicle architecture adoption speed or lidar cost breakthroughs would shift component demand composition. Forecasts reflect documented assumptions about sensor fusion complexity trajectories and tier-1 supplier relationship durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automotive Brake System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Vehicle Tracking Systems Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
In-Cabin Monitoring System (ICMS) Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market