
 Global Cargo Handling Equipment Market | 2026-2036
Global Cargo Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cargo Handling Equipment Market Analysis
Modular equipment configurations are replacing fixed-function machines, and this bundling flexibility is realigning procurement patterns across port operators and third-party logistics providers. KION Group AG leverages its integrated automation portfolio to anchor contracts with European distribution hubs. Toyota Industries Corporation dominates electric forklift manufacturing through in-house battery cell production. Sany Heavy Industry extends its reach in automated crane systems across Asia-Pacific terminals.
Cargo handling equipment encompasses powered industrial vehicles and stationary systems engineered to lift, transport, and position goods within supply chain nodes, typically rated by load capacity from one to over fifty metric tons and operating at speeds governed by site safety protocols. Forklifts and crane systems command the largest installed base, though conveyor systems represent the fastest-expanding segment as e-commerce sortation centers demand continuous-flow throughput. Electric technology leads new order intake in warehousing and retail applications, while diesel configurations retain share in heavy-port loading and unloading operations where duty cycles exceed battery endurance thresholds.
The EPA enforces Tier 4 Final emission standards for off-road diesel engines in the United States, compelling manufacturers to develop hybrid powertrains or risk market exclusion. The EU Green Deal and REACH frameworks in Europe mandate carbon footprint disclosure and restrict hazardous substances in battery systems, reshaping supplier qualification criteria. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance-driven product fragmentation that inflates engineering costs.
Market Dynamics
The electrification mandate from the EU Green Deal and EPA Tier 4 Final standards is forcing equipment manufacturers to reengineer powertrain architectures while port operators face compressed replacement cycles for diesel fleets.
Growth Catalysts
- EU Green Deal carbon targets:Terminal operators in Hamburg and Rotterdam are accelerating electric forklift and automated guided vehicle procurement to meet 2030 emission reduction deadlines.
- E-commerce fulfillment density:Sortation centers in China and the United States are installing continuous-flow conveyor systems to handle parcel volumes exceeding 100 million units daily during peak cycles.
- Lithium iron phosphate batteries:Cell chemistry improvements are extending electric forklift duty cycles to match diesel endurance in multi-shift warehousing operations.
Market Restraints
- Steel and rare earth input volatility:Crane superstructure fabrication depends on Chinese steel pricing, while permanent magnet motors require neodymium supply concentrated in Inner Mongolia processing facilities.
- Battery endurance thresholds:Heavy-port loading operations exceeding 18-hour continuous cycles cannot yet substitute diesel with electric propulsion without operational disruption.
- REACH substance restrictions:European battery system suppliers face requalification costs when cobalt and nickel compounds trigger hazardous substance disclosure requirements.
Strategic Opportunities
- India port modernization:Jawaharlal Nehru Port Trust and Mundra Port are expanding automated stacking crane capacity under Sagarmala infrastructure financing.
- 5G-enabled fleet telematics:Real-time equipment health monitoring converges with predictive maintenance algorithms to unbundle traditional service contracts.
- IRA clean vehicle credits:United States warehouse operators capture federal incentives for electric material handling equipment purchases above 25 kilowatt-hour battery capacity.
Industry Challenges
- Automation integration complexity:Terminal operating systems from legacy providers require middleware development to coordinate new robotic equipment with existing crane fleets.
- Certification timeline compression:CE marking and EPA certification processes for hybrid powertrains extend product launch windows by 8-14 months versus conventional diesel variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cargo Handling Equipment Market |
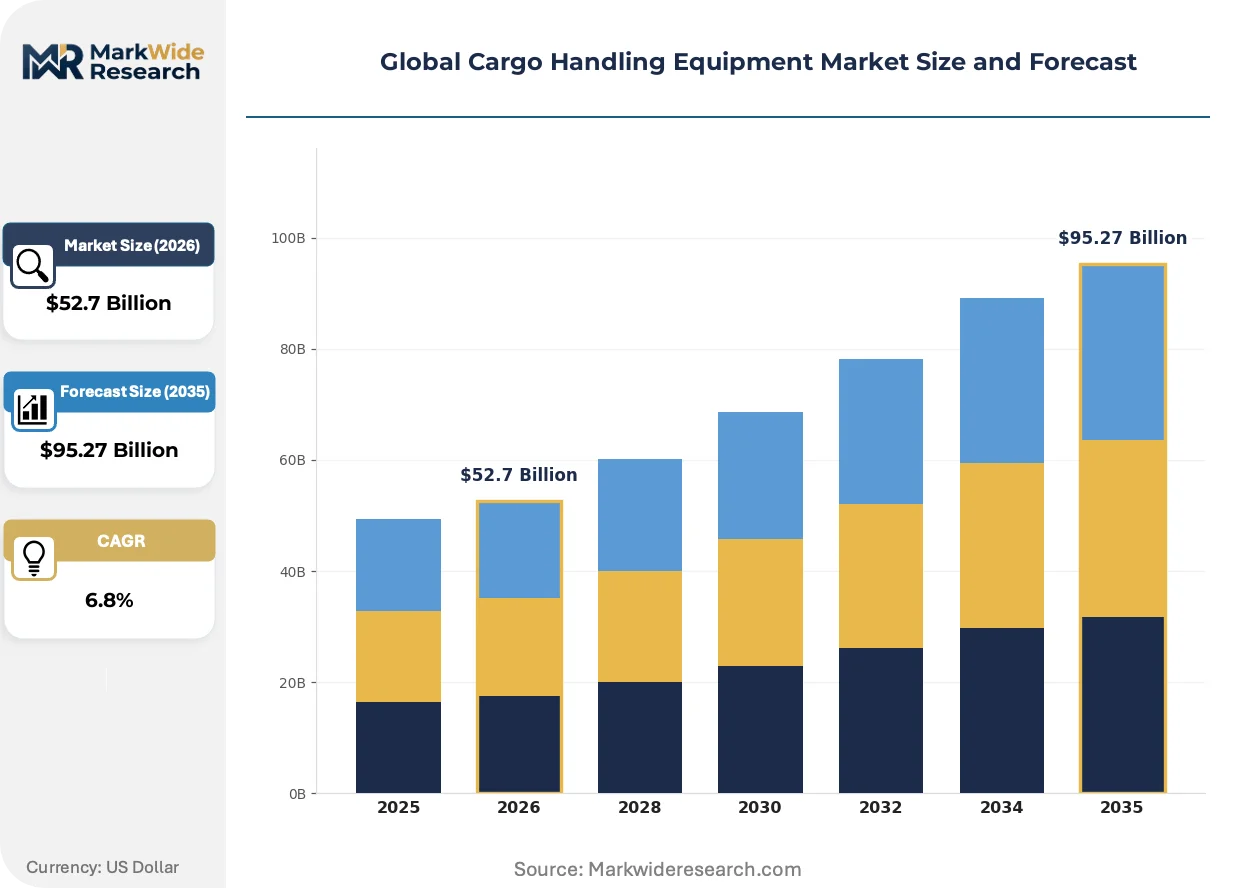
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklifts, Pallet Jacks, Crane Systems, Conveyor Systems End User: Logistics Providers, Warehousing, Manufacturing, Retail Technology: Electric, Diesel, LPG, Hybrid Application: Loading, Unloading, Storage, Distribution |
| Companies Covered | Toyota Industries Corporation, KION Group AG, Konecranes, Cargotec Corporation, Liebherr Group, Terex Corporation, Sany Heavy Industry, Mitsubishi Heavy Industries, Jungheinrich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cargo Handling Equipment Market Emerging Trajectories
Equipment architecture is fragmenting from monolithic systems toward configurable subassemblies, enabling port operators to resequence capital deployment and match capability upgrades to traffic volume shifts.
Container handling equipment is modularizing around standardized electric drivetrain skids and swappable battery packs. Port authorities in Singapore and Long Beach are piloting configurations where crane hoisting machinery, gantry systems, and power modules upgrade independently. This architecture compresses capital commitment by allowing incremental capability expansion without full system replacement.
REACH framework substance disclosure requirements are reshaping supplier qualification in European markets. Battery system manufacturers must document carbon footprint across cell production, module assembly, and end-of-life recycling stages. German distribution hubs are prioritizing suppliers with verified closed-loop cobalt recovery programs to preempt regulatory exclusion.
Third-party logistics providers are unbundling equipment procurement from maintenance services, creating direct manufacturer relationships that displace traditional dealer networks. Amazon fulfillment centers and DHL supply chain operations in the United States are negotiating power-by-the-hour contracts where OEMs retain asset ownership and guarantee uptime availability. This model shifts balance sheet risk from operator to manufacturer while demanding real-time performance telemetry integration.
Global Cargo Handling Equipment Market Segmentation
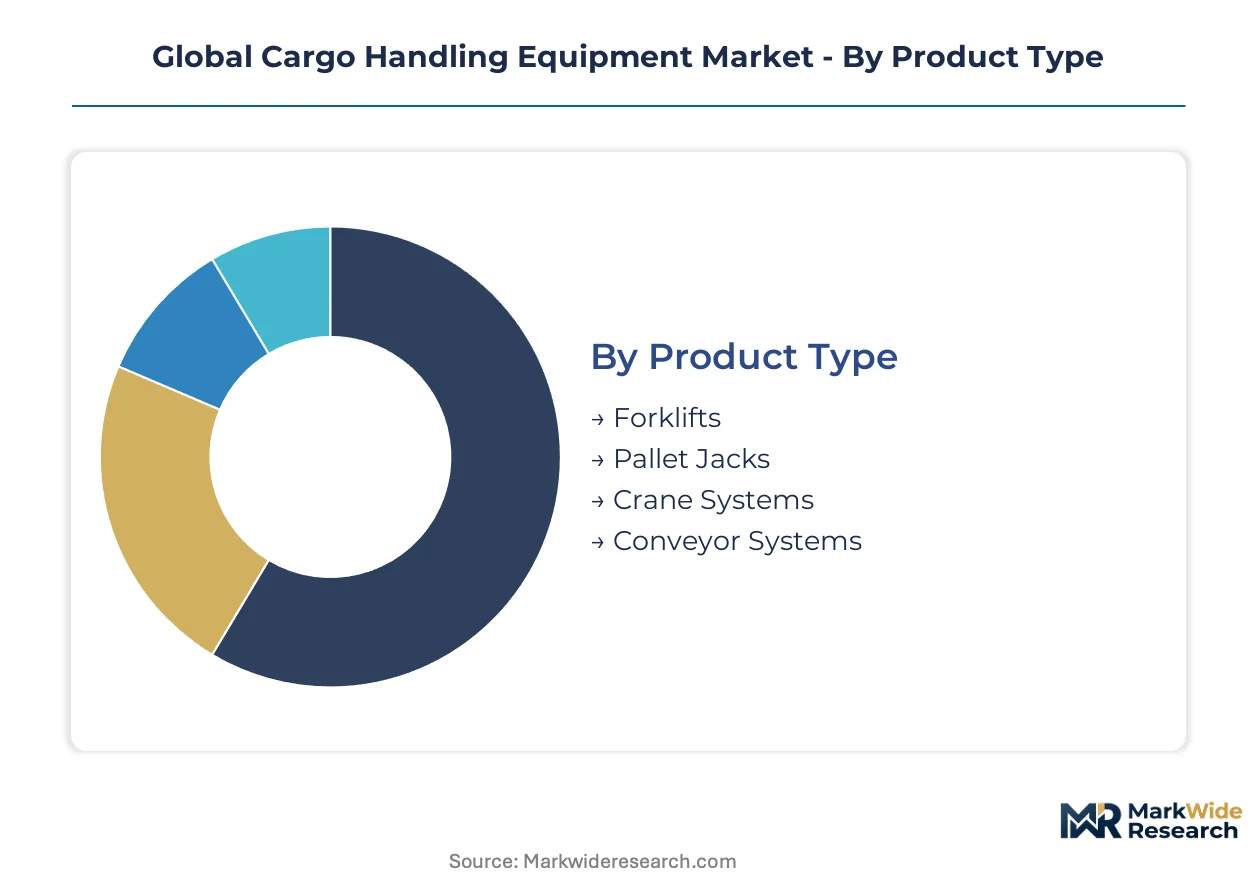
Cargo handling equipment segmentation reveals how procurement patterns diverge across operational contexts. Supply chain nodes impose distinct duty cycle demands, while regulatory pressure reshapes technology preferences within each category.
Product Type:
Supply concentration in crane superstructure fabrication and forklift powertrain manufacturing creates divergent competitive dynamics across equipment categories.
- Forklifts:Counterbalanced and reach truck configurations dominate warehousing fleets with load capacities spanning one to fifty metric tons. Demand clusters in German automotive distribution hubs and Chinese e-commerce fulfillment centers where multi-shift operations require lithium iron phosphate endurance.
- Crane Systems:Gantry, overhead, and container handling cranes engineered for heavy-port loading cycles exceeding eighteen continuous hours. Rotterdam and Hamburg terminal operators drive specification requirements for hybrid powertrains under EU Green Deal compliance deadlines.
- Pallet Jacks:Manual and electric walkie configurations serve last-mile distribution density in urban logistics corridors.
- Conveyor Systems:Belt, roller, and sortation architectures enable continuous-flow throughput in parcel processing facilities.
Today's leader: Forklifts. Tomorrow's challenger: Conveyor Systems.
End User:
Cost tier stratification separates capital-intensive port operators from asset-light third-party logistics providers, fragmenting procurement authority and contract structures.
- Logistics Providers:DHL and Amazon fulfillment networks negotiate power-by-the-hour contracts where OEMs retain asset ownership and guarantee uptime availability. This model demands real-time telemetry integration and shifts balance sheet risk from operator to manufacturer.
- Warehousing:Automated storage and retrieval system integration drives specification requirements for electric forklift fleets with swappable battery architectures. Singapore and Long Beach distribution hubs pilot modular configurations enabling independent capability upgrades.
- Manufacturing:Just-in-time production lines require synchronized material flow equipment with predictive maintenance algorithms.
- Retail:Seasonal volume volatility favors rental and short-term lease structures over capital purchase.
Volume concentrates with Logistics Providers. Margin expansion sits with Warehousing.
Technology:
Application context determines powertrain viability, with duty cycle duration and emission zone classification filtering technology adoption.
- Electric:Lithium iron phosphate and lithium-ion configurations lead new order intake in warehousing and retail applications where EPA Tier 4 Final and EU Green Deal mandates accelerate diesel displacement. Cell chemistry improvements now match diesel endurance in multi-shift operations.
- Diesel:Tier 4 Final compliant off-road engines retain share in heavy-port loading and unloading where continuous cycles exceed battery endurance thresholds. Hamburg and Rotterdam terminal operators face compressed replacement cycles under emission reduction deadlines.
- LPG:Propane configurations serve indoor-outdoor transitional operations requiring rapid refueling without charging infrastructure investment.
- Hybrid:Parallel and series hybrid architectures bridge emission compliance and endurance requirements for variable-duty port equipment.
Procurement momentum favors Electric. Diesel defends the heavy-port perimeter.
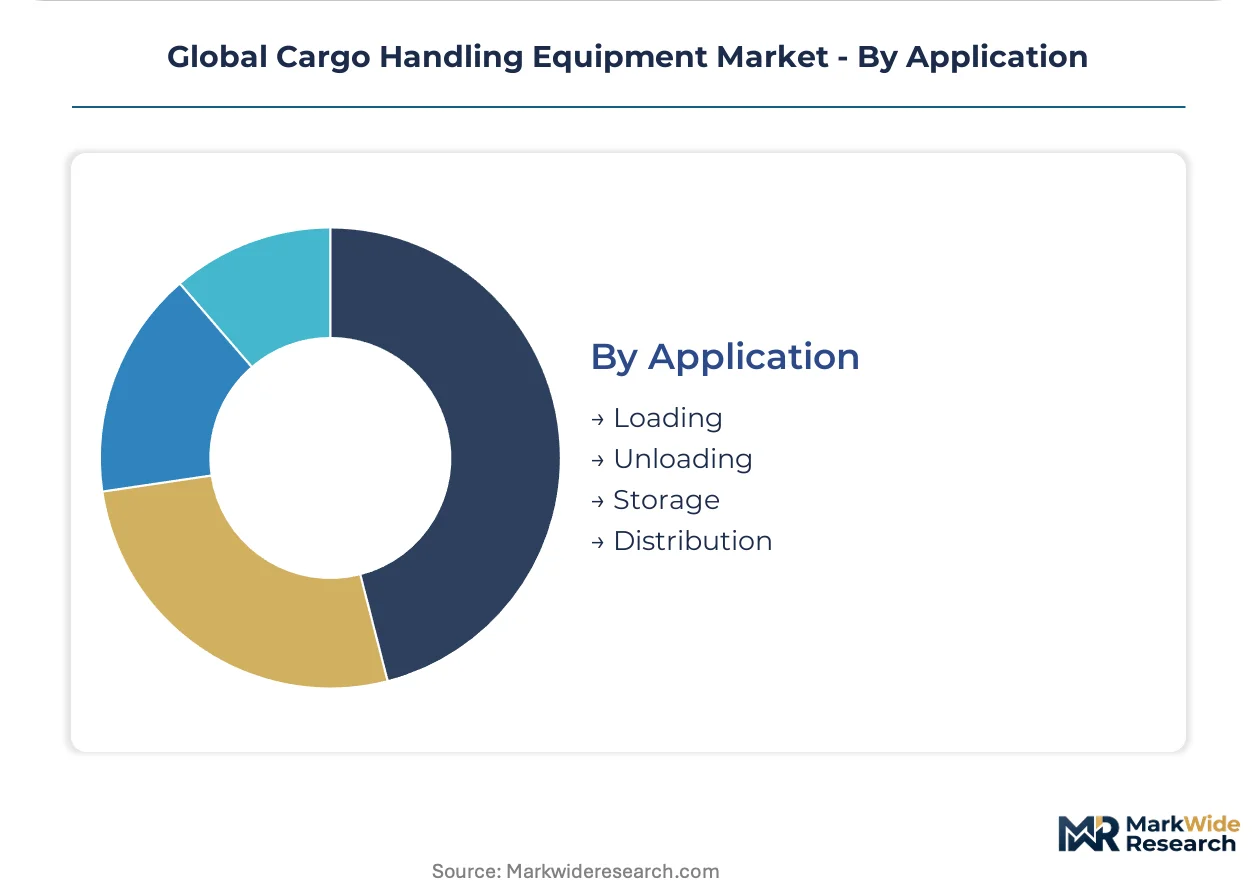
Application:
Customer type fragmentation separates continuous-flow operations from intermittent cycle demands, reshaping equipment specification and service contract structures.
- Storage:Automated stacking cranes and retrieval systems anchor capital deployment in Jawaharlal Nehru Port Trust and Mundra Port modernization under Sagarmala infrastructure financing. Vertical storage density maximization drives specification for high-bay reach trucks and automated guided vehicles.
- Distribution:Sortation centers in China and the United States install continuous-flow conveyor systems handling parcel volumes exceeding one hundred million units daily during peak cycles. Real-time fleet telematics integration enables predictive maintenance unbundling from traditional service contracts.
- Loading:Ship-to-shore crane cycles and container stacking operations impose endurance requirements favoring diesel and hybrid configurations.
- Unloading:Bulk material handling and break-bulk cargo operations require specialized grab and hook attachments.
Investment intensity peaks in Storage. Operational complexity concentrates in Distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container handling equipment originated in European port engineering traditions, with Hamburg and Rotterdam terminal operators establishing specification standards that persist across modern procurement cycles worldwide.
United States
EPA Tier 4 Final emission standards compress diesel fleet replacement timelines at Long Beach and Savannah port complexes. The Inflation Reduction Act delivers clean vehicle credits for electric material handling equipment above 25 kilowatt-hour battery capacity. Amazon fulfillment centers and DHL supply chain operations in the Midwest and Southeast negotiate power-by-the-hour contracts that shift balance sheet risk to manufacturers.
Germany
REACH framework substance disclosure requirements and EU Green Deal carbon targets reshape supplier qualification criteria for distribution hub operators. Hamburg terminal authorities accelerate electric forklift and automated guided vehicle procurement to meet 2030 emission reduction deadlines. KION Group AG anchors contracts with European logistics providers through integrated automation portfolios.
China
E-commerce fulfillment density drives sortation center expansion handling parcel volumes exceeding 100 million units daily during peak cycles. Dual carbon goals and MIIT industrial standards accelerate electric propulsion adoption in warehousing applications. Sany Heavy Industry extends automated crane system deployments across Asia-Pacific terminals from manufacturing bases in key coastal provinces.
India
Sagarmala infrastructure financing supports automated stacking crane capacity expansion at Jawaharlal Nehru Port Trust and Mundra Port. BIS certification requirements and central pollution control mandates filter equipment import specifications. Maharashtra and Gujarat coastal zones concentrate warehousing automation investments from third-party logistics providers serving manufacturing corridors.
Singapore
Port authorities pilot modular equipment configurations where crane hoisting machinery, gantry systems, and power modules upgrade independently. Maritime and Port Authority regulations enforce emission benchmarks for terminal operations. Tuas Port development anchors next-generation container handling infrastructure with 5G-enabled fleet telematics integration.
Global Cargo Handling Equipment Market Vendor Landscape
Premium-margin players sit above commodity-margin players across automation integration depth and battery chemistry control. The vendor base clusters around three strategic archetypes: integrated automation platform providers, in-house battery cell manufacturers, and crane superstructure specialists. Consolidation pressure concentrates among European distribution hub suppliers and Asia-Pacific terminal equipment fabricators. Dominant competitive moves include vertical integration into battery cell production and geographic expansion through port authority framework agreements.
Among Japan-based industrial conglomerates, Toyota Industries Corporation and Mitsubishi Heavy Industries exemplify scale-driven platform providers with captive supply chain control. Within the European integrated automation tier, KION Group AG and Jungheinrich AG occupy positions defined by warehouse fleet electrification capabilities. At the heavy-port equipment vector, Liebherr Group and Cargotec Corporation represent crane system specialists navigating hybrid powertrain certification complexity.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| KION Group AG |
| Konecranes |
| Cargotec Corporation |
| Liebherr Group |
| Terex Corporation |
| Sany Heavy Industry |
| Mitsubishi Heavy Industries |
| Jungheinrich AG |
| Others |
Supply Flow & Price Mechanics
EU Green Deal emission deadlines gate qualified supply and premium-tier pricing access, compressing procurement timelines for certified electric propulsion systems while excluding uncertified manufacturers from Hamburg and Rotterdam terminal contracts. Port operators now pay compliance premiums for REACH-documented battery systems with verified cobalt recovery, reshaping supplier qualification as a pricing threshold.
Pricing Analysis
Power-by-the-hour contracting dominates procurement for automated material handling fleets, shifting balance sheet risk from Amazon and DHL fulfillment networks to OEMs who retain asset ownership. Price differentiation hinges on EPA Tier 4 Final certification tier and real-time telemetry integration depth, with certified electric configurations commanding premiums over diesel alternatives. Cost compression in standard forklift tiers intensifies as Chinese manufacturers expand lithium iron phosphate production. Third-party logistics providers exhibit highest price sensitivity due to volume volatility, while port authorities with Sagarmala infrastructure financing show lowest sensitivity given sovereign-backed capital deployment.
Supply Chain Analysis
Steel superstructure fabrication rests on Chinese mill capacity, while permanent magnet motor production draws from Inner Mongolia rare earth processing facilities. Neodymium, lithium carbonate, and high-grade structural steel constitute critical input dependencies. Single-source vulnerability concentrates in rare earth magnet supply chains subject to export licensing volatility. Distribution runs through port authority framework agreements and OEM direct relationships that displace traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cargo Handling Equipment Market functions as a regulatory compounder where EPA Tier 4 Final and EU Green Deal mandates accelerate fleet replacement cycles and reengineer procurement authority structures.
For Market Incumbents: To counter battery chemistry commoditization from Chinese cell producers, KION Group AG and Toyota Industries Corporation should deepen backward integration into lithium iron phosphate manufacturing and anchor exclusive supply contracts with European distribution hubs. Certification investment for REACH-compliant closed-loop cobalt recovery programs defends margin position against regulatory exclusion. For New Entrants and Emerging Players: Capture Sagarmala-financed port modernization at Jawaharlal Nehru Port Trust and Mundra Port where automated stacking crane demand outpaces established vendor capacity. India warehousing automation presents the most penetrable geography given BIS certification barriers filter import competition. A 5G-enabled fleet telematics go-to-market angle unbundles traditional service contracts for third-party logistics providers. For Investors and Strategic Acquirers: Roll-up economics work for crane superstructure specialists with captive port authority relationships because terminal operating system integration complexity creates sticky incumbent positions. Five-to-ten year viability favors hybrid powertrain certification capabilities bridging emission compliance and endurance requirements. The signal to watch is IRA clean vehicle credit expansion for material handling equipment above 25 kilowatt-hour thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Toyota Industries Corporation secures lithium iron phosphate supply for multi-shift warehousing endurance. |
| Port Authority Framework Agreements | Sany Heavy Industry anchors automated crane deployments across Asia-Pacific terminals from coastal manufacturing bases. |
| REACH-Compliant Cobalt Recovery Programs | German distribution hubs preempt regulatory exclusion with verified closed-loop battery recycling documentation. |
| 5G-Enabled Fleet Telematics Integration | Singapore Tuas Port pilots real-time equipment health monitoring converging with predictive maintenance algorithms. |
| Modular Equipment Architecture Development | Long Beach and Singapore port authorities compress capital commitment through independent capability upgrades. |
Methodological Framework
Bottom-up port operator and logistics provider modeling reconciled against top-down crane and forklift manufacturing tracking forms the analytical core of this study. Primary interviews with terminal operations directors, warehouse automation engineers, OEM procurement teams, and aftermarket service heads combined with secondary validation from EPA certification databases, EU ECHA substance registrations, customs trade data, and SEC equipment manufacturer filings. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices segment volume and value across equipment type, propulsion technology, end-user category, and regional regulatory cluster throughout the projection horizon. CAGRs derive from installed base replacement cycles, e-commerce fulfillment center expansion pipelines, and emission mandate compliance deadlines. Forecast inputs include lithium iron phosphate cell chemistry improvement curves and Sagarmala infrastructure financing disbursement trajectories.
Raw material price volatility, battery endurance threshold breakthroughs, and regulatory timeline acceleration are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Manual Lifting Mobile Light Tower Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Weighbridge Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Hoist Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Industrial Carts Market