
 Swivel Coupler Market | 2026-2036
Swivel Coupler Market Size, Share, and Industry Trends Forecast 2026-2036
Swivel Coupler Market Insights
Galvanized carbon steel is hardening its cost advantage over stainless steel variants in mass-market swivel coupler production. PERI Group leverages captive forging capacity across German plants to sustain margin control on double-swivel products. Layher GmbH & Co. KG anchors European distribution through its system-scaffold ecosystem, while GAINFORD Equipment (Dongguan) Limited competes on export volume from Pearl River Delta manufacturing bases.
A swivel coupler is a rotational pipe-fitting device, typically drop-forged from carbon or alloy steel with a 48.3 millimeter bore to receive standard scaffold tubes, enabling angular connection between two structural members while permitting rotation around one axis. Its primary purpose is to transmit loads across non-perpendicular joints in temporary access structures, shoring systems, and modular staging. Carbon steel variants dominate volume due to their strength-to-cost ratio in construction end-use, while stainless steel fittings command premium positioning in maritime and oilfield services where chloride corrosion resistance determines replacement cycles. Aluminum alloy segments are gaining traction in hydraulic systems applications where weight reduction justifies higher unit costs.
EN 74 load-class standards in Europe, OSHA Subpart L scaffold regulations in the United States, and BIS IS 2750 specifications in India collectively shape product certification requirements and market access thresholds for swivel coupler manufacturers. These frameworks mandate proof-load testing, traceable material grades, and periodic third-party inspection, effectively filtering out uncertified producers from formal procurement channels. Stakeholders must monitor evolving national infrastructure codes and pre-qualification protocols as public-sector construction spending redirects toward standardized modular systems.
Market Dynamics
Modular scaffolding standardization across India's infrastructure corridors and tightening EN 74 Class B load-rating specifications in Europe are compressing procurement cycles for forged steel fittings while elevating material traceability requirements.
Growth Catalysts
- EN 74 Class B Mandates:European tightening of material specifications for forged steel fittings is filtering uncertified producers from formal procurement channels, consolidating demand around verified suppliers.
- India's Infrastructure Corridors:Delhi-Mumbai-Bangalore linking projects are concentrating modular scaffolding procurement into standardized system contracts with specified swivel coupler volumes.
- Drop-Forging Automation:Press and die technology advances are reducing unit production costs for carbon steel variants while maintaining 48.3 millimeter bore precision tolerances.
Market Restraints
- Zinc Price Volatility:Hot-dip galvanizing input costs for carbon steel couplers fluctuate with London Metal Exchange zinc futures, compressing margin stability for mass-market producers.
- Pearl River Delta Concentration:Export-volume manufacturing clusters in Dongguan and surrounding Guangdong province create geographic supply risk from regional logistics disruptions or trade policy shifts.
- Stainless Steel Substitution:Maritime and offshore oilfield services specify chloride-corrosion-resistant fittings with longer replacement cycles, displacing carbon steel in premium applications.
Strategic Opportunities
- Southeast Asia Modular Expansion:Construction firms in Vietnam, Indonesia, and the Philippines are expanding system-scaffold procurement as urban verticalization accelerates.
- Hydraulic Systems Lightweighting:Aluminum alloy swivel couplers are penetrating mobile elevated work platforms and aerial lift applications where weight reduction justifies unit cost premiums.
- BIS IS 2750 Pre-Qualification:Indian public-sector infrastructure pre-qualification protocols are redirecting construction spending toward certified modular system suppliers.
Industry Challenges
- Proof-Load Testing Bottlenecks:Third-party inspection capacity for traceable material grades and periodic certification is creating queue delays for manufacturer market access.
- Legacy Inventory Integration:Rental fleet operators face technical complexity mixing new EN 74 Class B compliant fittings with existing Class A stock in active scaffolding systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swivel Coupler Market |
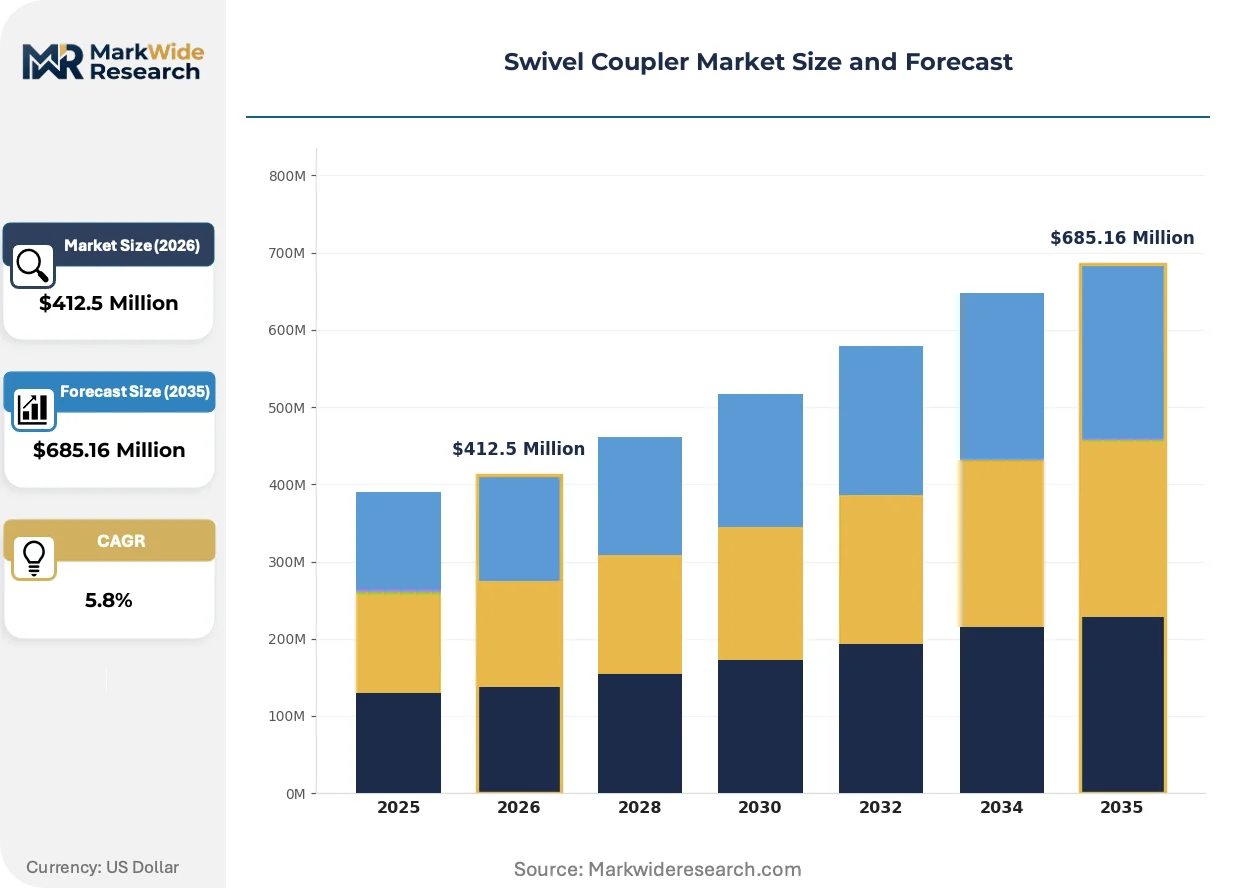
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Double Swivel, Single Swivel, Male Coupler, Female Coupler Material: Carbon Steel, Stainless Steel, Aluminum Alloy, Brass, Polymer Composite End Use Industry: Construction, Maritime, Oilfield Services, Agricultural Equipment, Heavy Machinery Application: Hydraulic Systems, Pneumatic Assemblies, Fluid Transfer, Mechanical Linkages, Industrial Automation |
| Companies Covered | Supertek Scafform, Apollo Scaffold Services Ltd., Layher GmbH & Co. KG, GAINFORD Equipment (Dongguan) Limited, Rizhao Fast & Fasten Scaffold Co., Ltd., PERI Group, ScaffoldMart, XSF Xtreme Structures & Fabrication, HAKI AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swivel Coupler Market Trends and Innovations
Digital traceability systems and automated forging controls are compressing quality assurance timelines while regulatory load-rating upgrades are rewriting material specification hierarchies across construction procurement.
Automated drop-forging with real-time dimensional feedback is rewriting production economics for 48.3 millimeter bore swivel couplers. German captive forging plants are adopting sensor-integrated presses that reduce dimensional variance below 0.2 millimeters. This precision is enabling just-in-time inventory models for system-scaffold assemblers while compressing warranty claim rates on structural failure.
REACH substance restriction expansions and EU Green Deal embodied-carbon tracking are tightening material documentation requirements for steel inputs into construction fittings. European importers now face mandatory supply chain disclosure for alloy traceability. This regulatory layer is favoring producers with integrated melt-shop-to-forge operations over traders of commodity steel billets.
Rental fleet operators are consolidating supplier relationships around full-system providers rather than component traders. Large scaffolding contractors in Germany and France now specify single-source accountability for coupler-tube-board compatibility. This behavior shift is compressing distributor margins while elevating vertical integration advantages for manufacturers with captive forging and galvanizing capacity.
Swivel Coupler Market Segmentation
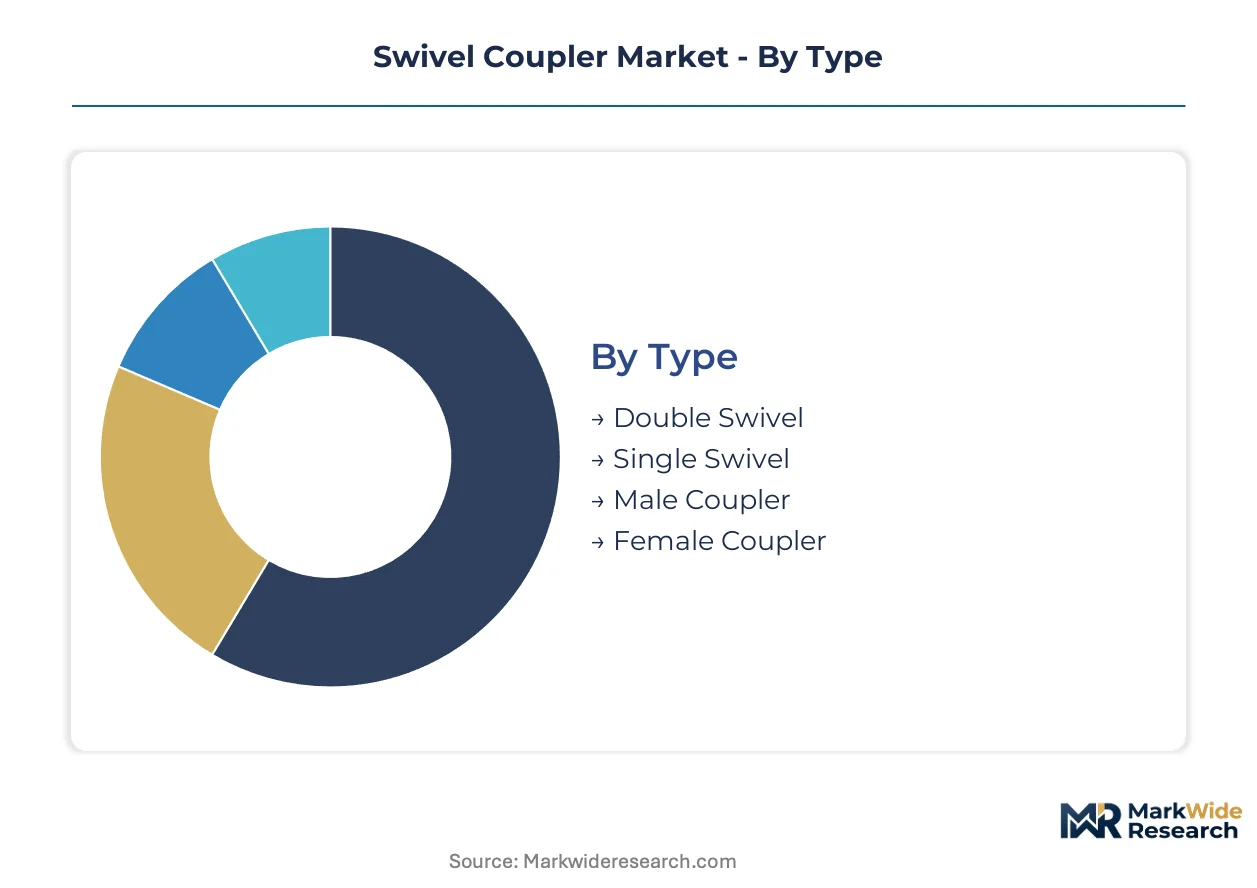
Swivel coupler procurement patterns diverge sharply across material grades and load-rating specifications, with replacement cycles in construction rental fleets running shorter than corrosion-driven intervals in maritime applications. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume scales.
Type:
Upgrade cycles for EN 74 Class B compliance are compressing replacement timelines across European rental fleets, favoring forged fittings with higher load ratings over legacy Class A stock.
- Double Swivel:Two-axis rotation capability enables complex angular connections in modular system scaffolding. German and French rental operators specify these for high-load perimeter applications where EN 74 Class B proof-load certification is mandatory.
- Single Swivel:Permits rotation around one axis only, simplifying installation in standard tube-and-coupler assemblies. India's infrastructure corridor contractors are consolidating procurement around single-swivel volumes for Delhi-Mumbai-Bangalore linking projects.
- Male Coupler:Externally threaded connection interface for hydraulic and pneumatic line integration. Agricultural equipment manufacturers specify these for mobile irrigation systems.
- Female Coupler:Internally bored receptacle for receiving male-threaded fittings. Oilfield service providers favor these for quick-connect pressure line assemblies.
Volume placements concentrate in Single Swivel; the faster expansion belongs to Double Swivel.
Material:
Cost tier stratification separates commodity construction procurement from premium corrosion-resistant specifications, with zinc-input volatility squeezing mid-grade carbon steel margins.
- Carbon Steel:Drop-forged construction with hot-dip galvanizing dominates mass-market scaffolding. Hot-dip galvanizing input costs fluctuate with London Metal Exchange zinc futures, compressing margin stability for mass-market producers.
- Stainless Steel:AISI 316 and 304 grades deliver chloride corrosion resistance for maritime and offshore exposure. North Sea oilfield operators specify these for extended replacement cycles in salt-air environments.
- Aluminum Alloy:Lightweight 6061-T6 and 7075 variants penetrate mobile elevated work platforms where weight reduction justifies unit cost premiums.
- Brass:Copper-zinc alloy offers machinability for low-pressure fluid transfer fittings. Plumbing and irrigation system assemblers specify these for potable water compatibility.
- Polymer Composite:Glass-reinforced nylon and PEEK variants serve electrical isolation and chemical resistance niches. Semiconductor cleanroom equipment manufacturers specify these for static-dissipative properties.
Carbon Steel captures the dominant placement volume; Aluminum Alloy is climbing the fastest as hydraulic systems lightweighting accelerates.
End Use Industry:
Application maturity varies from standardized modular scaffolding in construction to specification-heavy corrosion engineering in offshore services.
- Construction:Temporary access structures, shoring systems, and modular staging drive standardized 48.3 millimeter bore demand. Southeast Asian urban verticalization is expanding system-scaffold procurement in Vietnam, Indonesia, and the Philippines.
- Maritime:Shipboard staging and dockside maintenance platforms require salt-spray-resistant specifications. Stainless steel fittings with extended replacement cycles displace carbon steel in these premium applications.
- Oilfield Services:Offshore platform maintenance and drilling rig staging operate under API and NORSOK structural standards. North Sea and Gulf of Mexico operators specify high-load-rated forged fittings.
- Agricultural Equipment:Mobile irrigation systems and harvester hydraulic lines use lower-pressure swivel connections. Brazilian and Ukrainian grain belt equipment manufacturers specify these for seasonal deployment cycles.
- Heavy Machinery:Mining excavators and material handlers incorporate swivel couplers in articulating joint hydraulic systems. Australian iron ore and Chilean copper mining fleets drive replacement part demand.
Construction maintains the deepest volume base; Maritime is gaining share fastest as offshore wind installation expands European fleet specifications.
Application:
Functional performance requirements separate high-pressure hydraulic specifications from low-tolerance mechanical linkage applications.
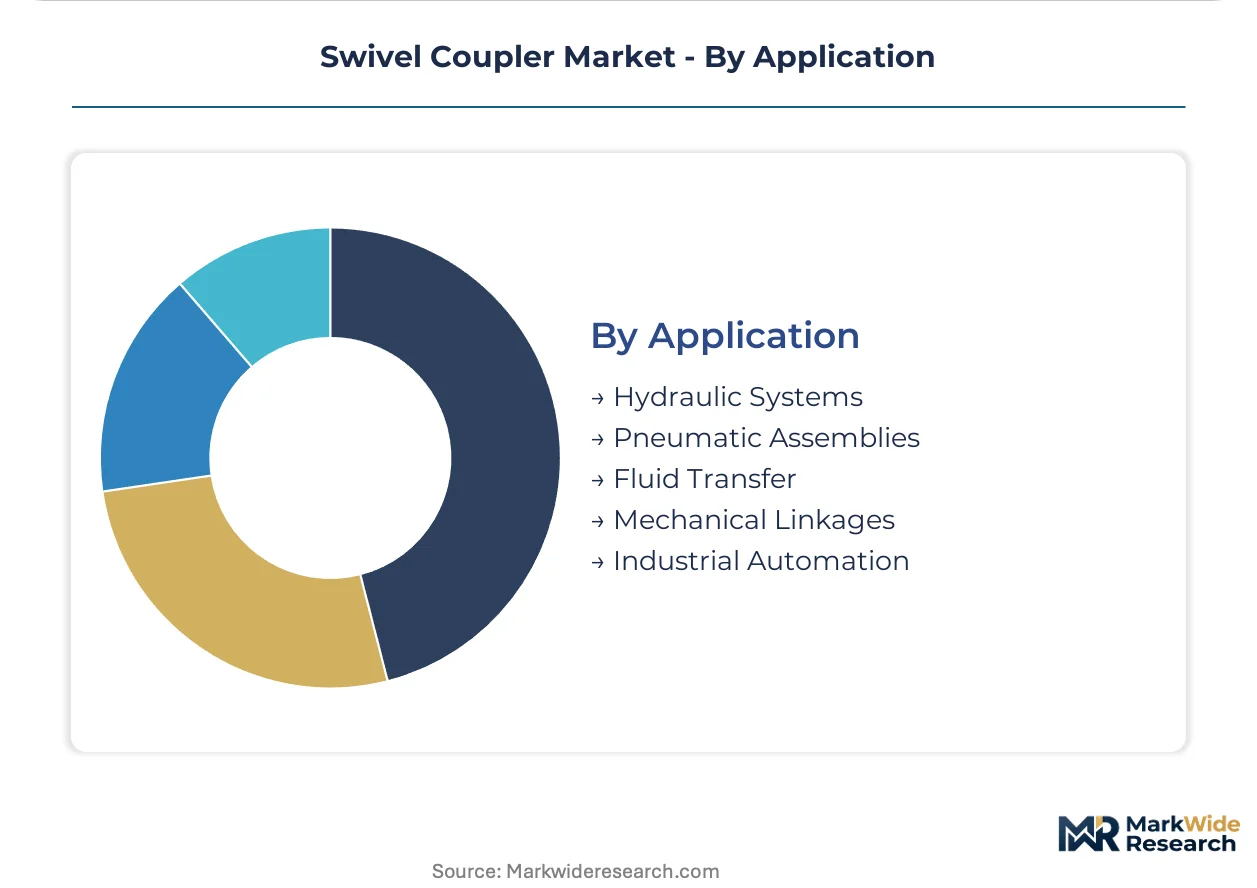
- Hydraulic Systems:High-pressure fluid power transmission demands precision-machined bores and seal-compatible surface finishes. Mobile elevated work platform manufacturers specify aluminum alloy variants for weight-critical aerial lift mechanisms.
- Pneumatic Assemblies:Compressed air line connections prioritize rapid assembly and leak-tight sealing. Automotive paint shop automation systems specify these for tool-changing stations.
- Fluid Transfer:Liquid and gas conveyance applications span potable water to chemical process streams. Food and beverage processing equipment assemblers specify brass and stainless grades for regulatory compliance.
- Mechanical Linkages:Load-bearing angular connections without fluid sealing requirements. Agricultural implement manufacturers specify carbon steel single-swivel fittings for three-point hitch attachments.
- Industrial Automation:Robotic arm joints and automated guided vehicle steering mechanisms require repeatable precision. German automotive assembly line integrators specify these for just-in-time manufacturing cells.
Hydraulic Systems anchor the largest installed base; Industrial Automation is expanding most quickly as manufacturing robotics penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Dedicated Freight Corridor industrial zones and China's Pearl River Delta special economic regions are concentrating swivel coupler manufacturing capacity through infrastructure tax incentives and export processing privileges.
India
Delhi-Mumbai-Bangalore infrastructure corridor projects are consolidating modular scaffolding procurement into standardized system contracts. BIS IS 2750 specifications mandate traceable material grades and third-party inspection for public-sector pre-qualification. Manufacturing clusters in Haryana and Gujarat are scaling drop-forging capacity to serve these corridor-linked construction volumes.
Germany
EN 74 Class B load-rating mandates are filtering uncertified producers from formal procurement channels across rental fleet operators. REACH substance restrictions and EU Green Deal embodied-carbon tracking tighten steel input documentation requirements. Captive forging plants in Bavaria and North Rhine-Westphalia are integrating sensor-integrated presses for dimensional precision below 0.2 millimeters.
China
Pearl River Delta export manufacturing bases in Dongguan and surrounding Guangdong province dominate volume production for international scaffolding distributors. GB standards and dual carbon goals are elevating environmental compliance costs for steel-intensive forging operations. Shanghai and Tianjin port logistics clusters handle bulk export consolidation for Southeast Asian construction markets.
United States
OSHA Subpart L scaffold regulations shape certification requirements for temporary access structure components across commercial construction. Infrastructure Investment and Jobs Act spending is redirecting public procurement toward standardized modular systems. Texas and California metropolitan construction markets are absorbing elevated import volumes from Asian manufacturing clusters.
Vietnam
Urban verticalization in Ho Chi Minh City and Hanoi is accelerating system-scaffold procurement from regional suppliers. The country's national construction regulator is aligning technical standards with ASEAN harmonization protocols for cross-border equipment certification. Manufacturing zones near Hai Phong port are attracting component assembly investment from Chinese forging specialists.
Swivel Coupler Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-system providers commanding rental fleet relationships while commodity fabricators serve volume export channels. The vendor base organizes around three archetypes: vertically integrated European specialists with captive forging and galvanizing capacity, scale-driven Chinese export manufacturers operating from Pearl River Delta clusters, and regional rental fleet operators consolidating around single-source system accountability. Competitive positioning depends on proof-load certification speed and zinc-input cost management rather than product differentiation alone. M&A activity concentrates on galvanizing asset acquisition and regional distribution network consolidation.
Among German-based system-scaffold specialists, PERI Group and Layher GmbH & Co. KG exemplify the vertically integrated archetype with in-house forging capacity and European distribution control. GAINFORD Equipment (Dongguan) Limited represents the export-volume manufacturer position anchored in Pearl River Delta manufacturing bases. These three occupy distinct competitive tiers: full-system accountability versus component volume versus integrated quality control.
| Leading Market Players |
|---|
| Supertek Scafform |
| Apollo Scaffold Services Ltd. |
| Layher GmbH & Co. KG |
| GAINFORD Equipment (Dongguan) Limited |
| Rizhao Fast & Fasten Scaffold Co., Ltd. |
| PERI Group |
| ScaffoldMart |
| XSF Xtreme Structures & Fabrication |
| HAKI AB |
| Others |
Pricing and Supply Chain Analysis
EN 74 Class B procurement mandates across European rental fleets are compressing supplier qualification timelines, forcing forge shops to absorb certification costs while zinc-input volatility squeezes margin buffers on mass-market carbon steel couplers.
Pricing Analysis
Short-lead-time premiums separate urgent replacement orders from scheduled contract volumes in the swivel coupler trade. Three-tier pricing structure across EN 74 Class B certified, Class A legacy, and uncertified economy grades reflects proof-load testing investment and material traceability documentation. Pricing pressure stems from London Metal Exchange zinc futures fluctuation feeding into hot-dip galvanizing costs. Volume contractors in India's infrastructure corridors exhibit highest price sensitivity, while North Sea oilfield operators prioritize chloride-corrosion resistance over unit cost.
Supply Chain Analysis
Carbon steel billet supply rests on integrated melt-shop operations in China, India, and Germany. Drop-forging capacity concentrates around Dongguan export zones, Haryana corridor-linked clusters, and Bavarian captive plants. Zinc ingot sourcing and third-party inspection queue bottlenecks create single-source vulnerability for certification speed. Distribution runs through system-scaffold full-service providers consolidating rental fleet relationships over component traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Third-party proof-load inspection capacity constraints are propping pricing power for certified suppliers, as queue delays filter uncertified competitors from formal procurement channels.
For Market Incumbents: Deepen captive galvanizing asset control to buffer zinc-input volatility and compress lead times on EN 74 Class B certified volumes. Expand sensor-integrated forging press deployment in German plants to sustain dimensional precision below 0.2 millimeters against emerging automation competitors. Prioritize single-source system accountability contracts with French and German rental fleet operators consolidating supplier relationships. For New Entrants and Emerging Players: Regional distributors in Vietnam and Indonesia present channel partnership opportunities for certified component suppliers seeking ASEAN market access. White-space concentration sits with aluminum alloy swivel couplers for mobile elevated work platform manufacturers lightweighting aerial lift mechanisms. Pursue BIS IS 2750 pre-qualification status to capture redirected Indian public-sector infrastructure spending. For Investors and Strategic Acquirers: The window for entry favors integrated forge-to-galvanize specialists with captive European distribution control. Long-term viability centers on embodied-carbon documentation capabilities aligning with EU Green Deal supply chain disclosure mandates. Monitor REACH substance restriction expansion timelines as inflection signal for alloy traceability compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing Assets | Captive zinc-coating capacity buffers LME futures volatility for margin stability. |
| Sensor-Integrated Forging Automation | German press technology sustains sub-0.2 millimeter bore precision for warranty reduction. |
| EN 74 Class B Certification Fast-Track | Accelerated proof-load testing access filters uncertified competitors from European procurement. |
| Aluminum Alloy Product Line Expansion | 6061-T6 variants penetrate mobile elevated work platform weight-critical applications. |
| ASEAN Distribution Network Buildout | Vietnam and Indonesia urban verticalization concentrates system-scaffold procurement growth. |
Research Methodology
Document review covered trade customs records, SEC filings from listed scaffolding manufacturers, and BIS certification registries, complemented by interviews with rental fleet procurement directors, drop-forging plant managers, and third-party inspection engineers. Primary fieldwork with German system-scaffold specialists and Pearl River Delta export manufacturers cross-referenced against EN 74 compliance databases and zinc futures market data. Bottom-up volume triangulation from country-level construction spending data reconciled with top-down manufacturer capacity estimates.
Historical shipment patterns from Haryana and Gujarat forging clusters cross-referenced against panel input from infrastructure corridor contractors. Segmentation modeling spanned material grade, load-rating class, end-use industry, and regional regulatory framework across the projection horizon. CAGRs derived from trend extrapolation of modular scaffolding procurement volumes and zinc-input cost pass-through elasticity. Forecast inputs incorporated ASEAN harmonization protocol alignment timelines and EU Green Deal embodied-carbon disclosure phase-ins.
Caveats apply where zinc price volatility spikes, Pearl River Delta logistics disruptions, or REACH restriction expansions could materially shift the outlook for certified supplier margins and replacement cycle timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Hoist Controller Market
Material Handling Equipment
Sand Washing Machine Market
Material Handling Equipment
Slow Speed Shredding Machines Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Motorized Decoiler Machine Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Pipe Jacking Machines Market