
 Manual Lifting Mobile Light Tower Market | 2026-2036
Manual Lifting Mobile Light Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Lifting Mobile Light Tower Market Insights
The EU Green Deal is recalibrating procurement criteria for mobile lighting across European public works, pushing rental fleets toward lower-emission technologies. Generac Power Systems leverages its North American manufacturing scale to supply manual-lift towers with reduced fuel consumption profiles. Wacker Neuson anchors its position through specialized compact designs optimized for confined construction environments. Atlas Copco competes on technology leadership in LED retrofit compatibility across its existing tower installed base.
A manual lifting mobile light tower is a portable illumination unit employing mechanical lift mechanisms—crank, ratchet, pulley, or hydraulic systems—to raise lamp arrays typically between 15 and 30 feet, powered by onboard diesel generators, battery banks, or solar arrays for temporary job-site lighting. Crank lift configurations dominate rental fleet inventories due to mechanical simplicity and field repairability, while LED technology segments capture expanding margin pools through extended lamp life and reduced fuel consumption. Hydraulic lift variants occupy premium niches in mining operations where rapid deployment under heavy contamination demands sealed systems.
The Occupational Safety and Health Administration in the United States enforces minimum illumination levels for construction and mining operations, directly shaping product lumen output requirements and tower height specifications. The European Union's F-Gas Regulation and Machinery Directive constrain refrigerant-based cooling in generator sets and mandate CE-marked structural stability for towable equipment. Stakeholders must monitor evolving battery-electric runtime standards and solar hybrid certification protocols as these frameworks increasingly determine market access eligibility.
Market Dynamics
LED retrofit compatibility and battery-electric runtime standards are compressing product development cycles across manual lifting mobile light tower manufacturing, forcing suppliers to reengineer mechanical lift systems around electrified powertrains.
Growth Catalysts
- EU Green Deal procurement recalibration:European public works authorities now mandate lower-emission mobile lighting equipment, redirecting rental fleet investment toward solar hybrid and battery-electric units.
- Department of Transportation night-work mandates:US utility contractors face escalating illumination requirements for highway maintenance, expanding rental channel demand for crank-lift LED towers.
- Confined construction specialization:Compact tower designs optimized for urban job sites with restricted footprint are capturing premium positioning in German and Australian occupational safety compliance markets.
Market Restraints
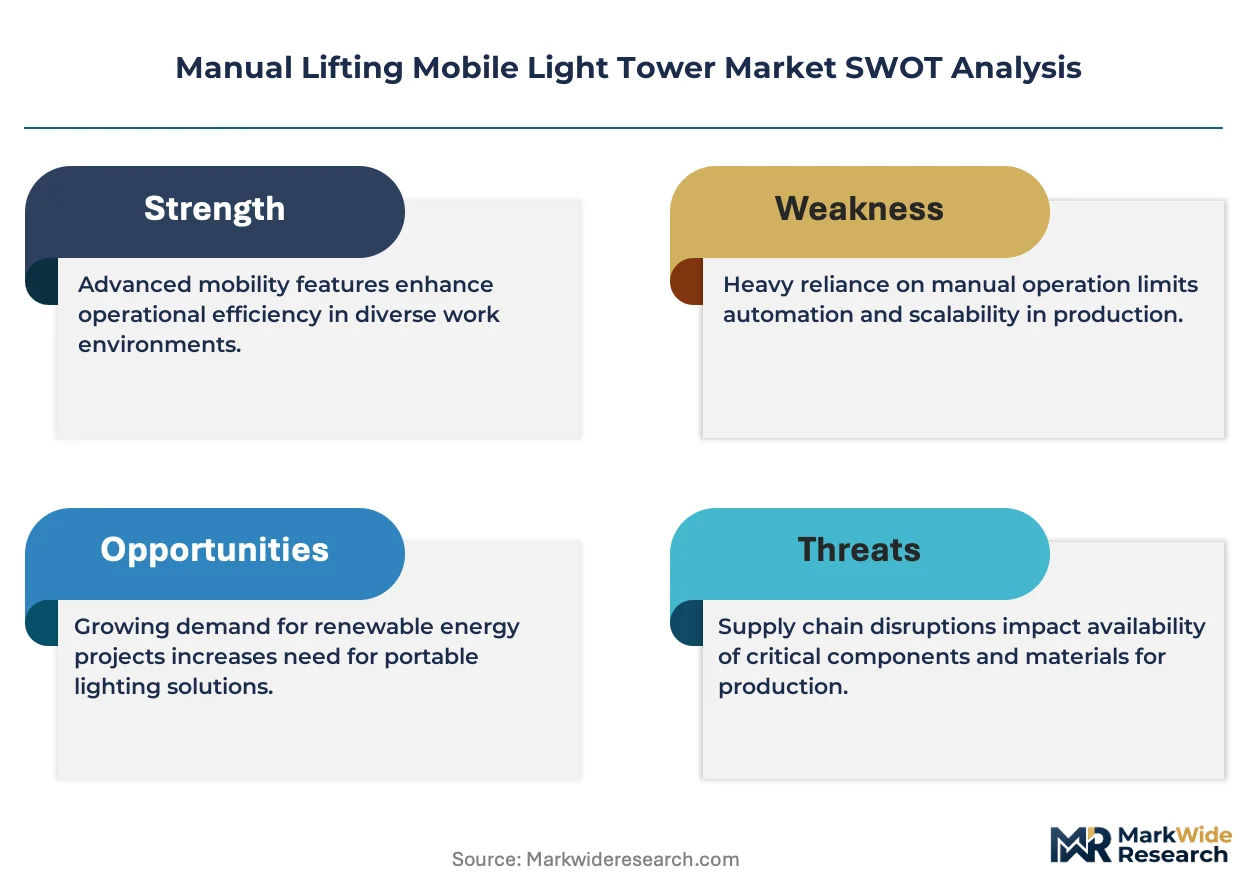
- Diesel generator input cost volatility:Fluctuating fuel prices and emission control component costs compress margins on conventional powered units still dominant in rental inventories.
- Battery cell supply concentration:Lithium-ion pack sourcing depends on limited East Asian cell manufacturers, creating vulnerability for electric tower production scaling.
- F-Gas Regulation cooling constraints:EU restrictions on refrigerant-based generator cooling systems add engineering complexity and certification delays for towable equipment.
Strategic Opportunities
- Solar hybrid certification protocols:Emerging standards for photovoltaic-integrated towers create first-mover advantage for manufacturers achieving early compliance in European markets.
- Mining rapid-deployment niche:Hydraulic lift variants with sealed systems face limited competition in heavy-contamination environments, supporting premium pricing.
- Rental fleet electrification services:Channel partners seek bundled maintenance and battery swap programs, opening recurring revenue streams beyond equipment sales.
Industry Challenges
- Electromechanical integration skill gaps:Field service technicians require cross-training in both mechanical lift systems and battery management electronics.
- CE marking structural stability timelines:Extended certification cycles for towable equipment under Machinery Directive slow product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Lifting Mobile Light Tower Market |
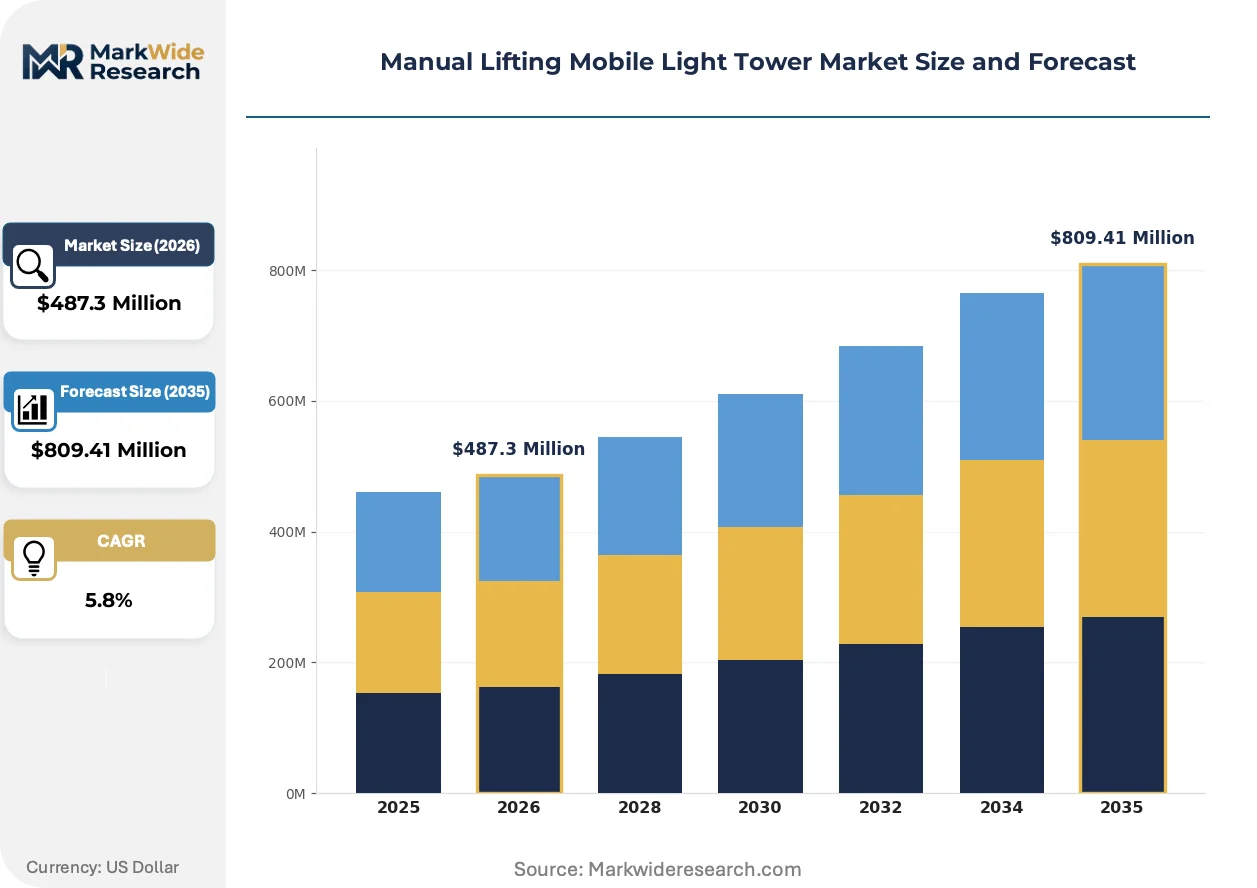
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Lift, Pulley System, Ratchet Lift, Crank Lift Technology: Halogen, LED, Metal Halide, Solar Powered, Fluorescent Application: Construction Sites, Event Lighting, Emergency Services, Film Production, Mining Operations End User: Government Agencies, Rental Companies, Security Firms, Transportation Services, Utility Contractors |
| Companies Covered | Generac Power Systems, Wacker Neuson, Doosan Portable Power, Atlas Copco, Terex, Caterpillar, J C Bamford Excavators, HIMOINSA, Larson Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Lifting Mobile Light Tower Market Trends and Innovations
Mechanical lift architectures are being reengineered around electrified powertrains and intelligent controls, compressing the traditional separation between illumination hardware and energy management systems.
Photovoltaic panel integration is integrating into tower masts and trailer surfaces, enabling partial battery recharging during daylight deployment. Mining operators in Australia are piloting these hybrid units to reduce diesel resupply frequency in remote sites. The technology is integrating fuel consumption monitoring with predictive maintenance alerts, shifting competitive differentiation from lumen output to total cost of ownership metrics.
OSHA minimum illumination enforcement for construction and mining operations is tightening lumen output verification requirements. Inspectors now demand documented lux-level compliance across work zones, not just tower specifications. Rental companies in the United States are responding by specifying higher-output LED arrays and integrated light-level sensors.
Short-term rental models are displacing capital purchase patterns among mid-sized contractors. Equipment-as-a-service arrangements bundle maintenance, transport, and fuel or charging logistics into per-day rates. This shift concentrates most visible in US utility and German construction verticals where project duration uncertainty favors operational expenditure flexibility over asset ownership.
Manual Lifting Mobile Light Tower Market Segmentation
Segmentation in manual lifting mobile light towers reveals how capital deployment, regulatory exposure, and operational intensity vary across mechanical architectures and power technologies. Procurement patterns diverge sharply between rental fleets seeking field-serviceable simplicity and mining operators demanding sealed hydraulic systems for contamination-heavy environments.
Product Type:
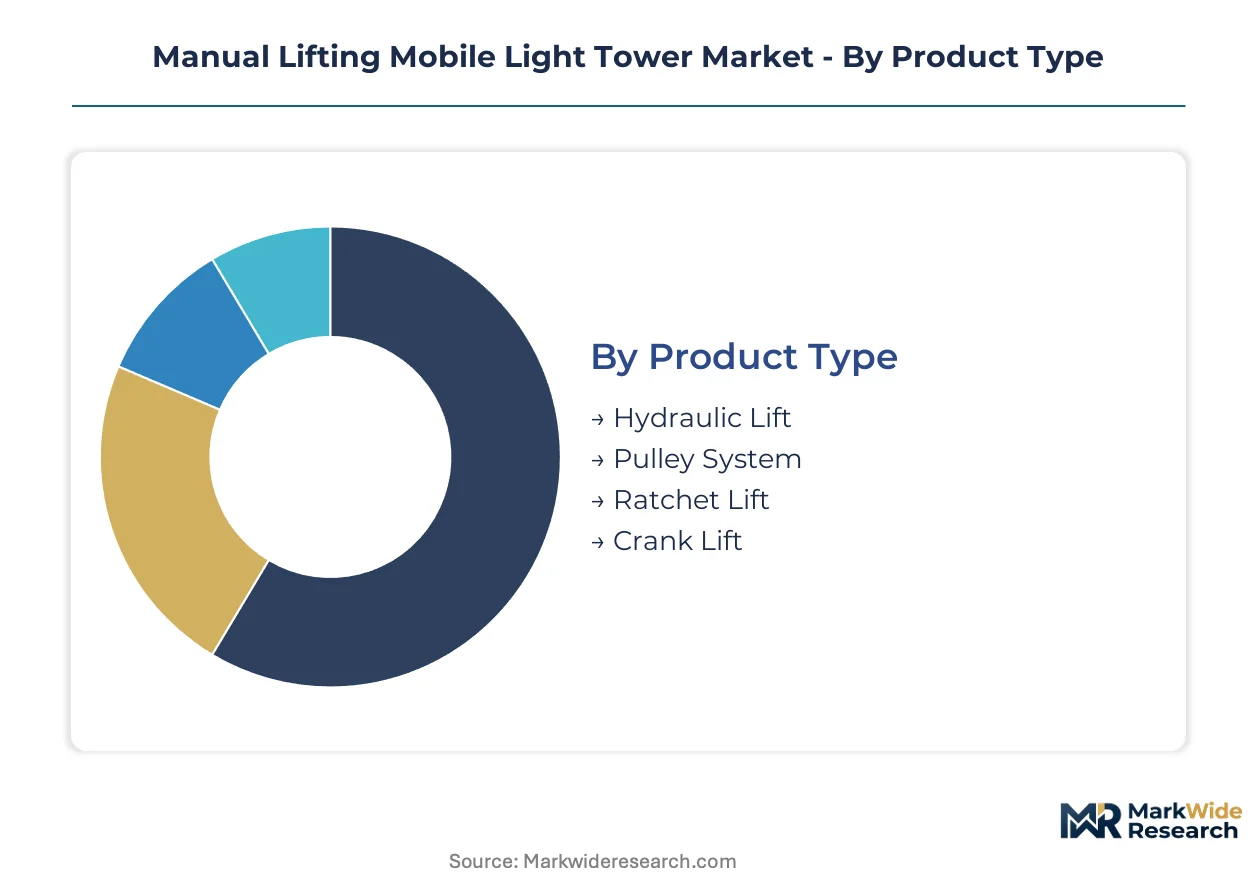
Capital intensity peaks with hydraulic lift variants requiring precision-machined cylinders and sealed actuator assemblies, while crank and ratchet mechanisms demand lower upfront tooling investment.
- Hydraulic Lift:Sealed piston systems withstand abrasive particulate loads in open-pit extraction environments. Australian mining contractors specify these units for rapid vertical deployment where mechanical contamination would degrade exposed gear trains. Premium positioning reflects specialized cylinder sourcing and extended certification timelines under EU Machinery Directive stability requirements.
- Crank Lift:Manual worm-gear mechanisms dominate rental fleet inventories across the United States due to field-repairable simplicity and minimal spare parts diversity. Utility contractors facing Department of Transportation night-work mandates favor these units for highway maintenance where deployment speed matters less than operational reliability.
- Pulley System:Counterweighted rope-and-sheave configurations occupy mid-market positioning between mechanical simplicity and vertical reach extension.
- Ratchet Lift:Incremental pawl-and-gear systems serve confined construction sites in Germany where OSHA-aligned occupational safety frameworks restrict uncontrolled load descent.
Most installed capacity flows through crank lift configurations. Expansion is steepest in hydraulic lift variants for heavy-contamination mining applications.
Technology:
Power technology choices stratify by total cost of ownership horizons, with battery-electric and solar hybrid architectures requiring higher initial capital outlays against diesel and halogen alternatives.
- LED:Solid-state arrays deliver lumen maintenance above 50,000 hours with directional beam control reducing spill light penalties. German construction site operators specify LED retrofit-compatible towers to comply with tightened workplace illumination standards under national occupational safety frameworks. Fuel consumption monitoring integration shifts competitive differentiation toward operational expenditure metrics rather than capital cost alone.
- Solar Powered:Photovoltaic-integrated masts enable partial battery regeneration during daylight deployment, reducing diesel resupply frequency in remote Australian mining locations. EU Green Deal procurement recalibration is redirecting European public works rental investment toward these units despite higher upfront panel and charge controller costs.
- Halogen:Tungsten-filament sources persist in emergency services rapid-response inventories where immediate availability trumps efficiency optimization.
- Metal Halide:Ceramic arc-discharge lamps retain niche positioning in film production for color rendering index requirements exceeding LED current capabilities.
- Fluorescent:Linear tube configurations occupy economy tiers in temporary event lighting with short-duration deployment cycles.
Technology mix concentrates in LED for rental channel standardization. Solar hybrid architectures are climbing the fastest as European public works procurement tightens emission criteria.
Application:
Application segmentation tracks exposure to regulatory enforcement intensity and project duration predictability, with mining and construction showing divergent procurement patterns.
- Construction Sites:Urban job sites with restricted footprint demand compact tower designs optimized for German and Australian occupational safety compliance. Wacker Neuson anchors positioning through specialized form factors serving confined European construction environments where CE-marked structural stability determines market access.
- Mining Operations:Remote extraction locations prioritize rapid deployment under heavy contamination, favoring sealed hydraulic systems with limited field-service requirements. Australian operators pilot photovoltaic-integrated hybrid units to reduce fuel logistics burden in inaccessible terrain.
- Event Lighting:Short-duration entertainment deployments favor lightweight crank-lift units with rapid setup protocols.
- Emergency Services:First-response agencies specify diesel-generator reliability for disaster illumination where grid independence is mandatory.
- Film Production:Color-accurate metal halide sources serve location cinematography despite efficiency penalties against LED alternatives.
Volume concentration sits with construction site deployments. Mining applications show steepest technology upgrade trajectory as hybrid powertrains penetrate remote extraction logistics.
End User:
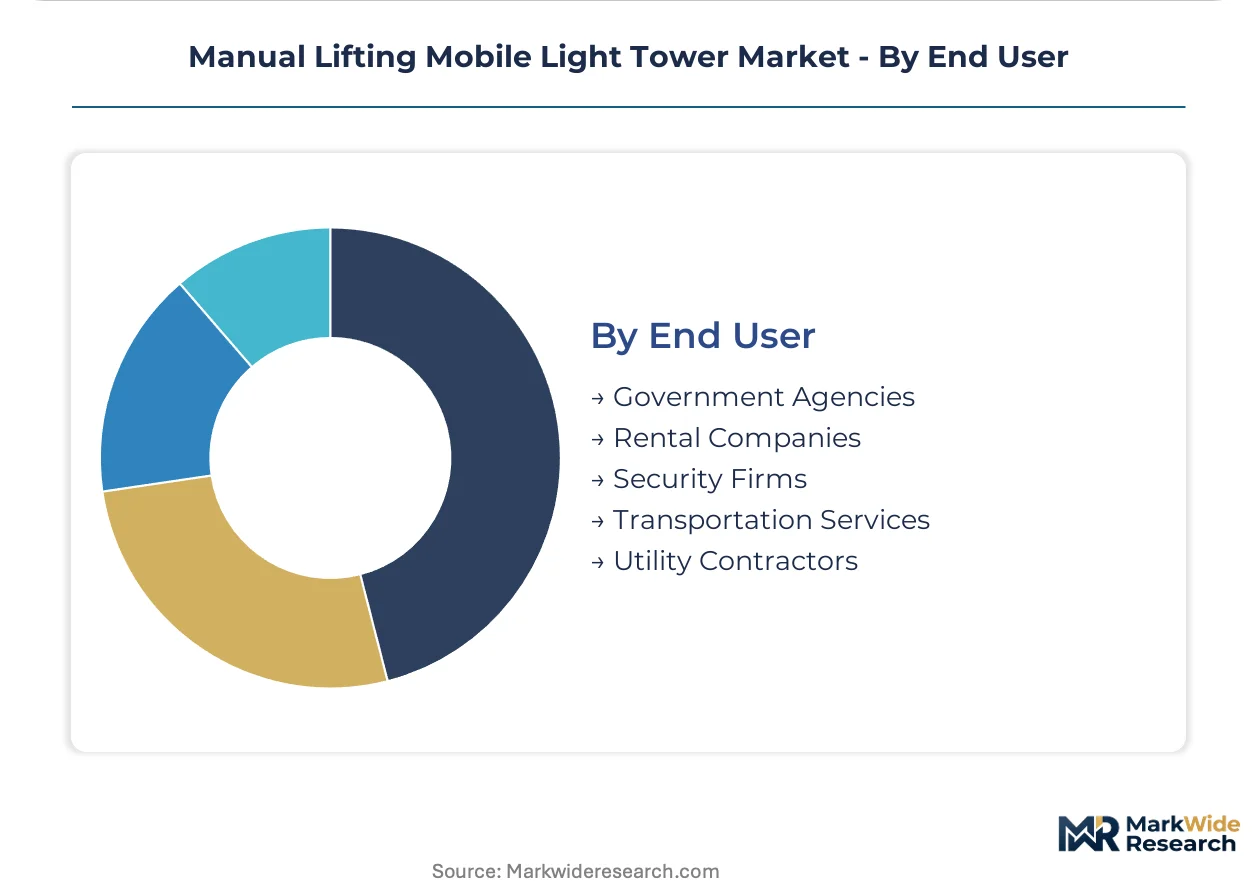
End user segmentation reflects channel structure concentration, with rental companies intermediating capital ownership risk for project-based contractors.
- Rental Companies:Fleet operators aggregate demand across fragmented contractor bases, concentrating procurement leverage for LED and crank-lift standardization. United States utility contractors access equipment through rental channels to convert capital expenditure into operational flexibility under uncertain project duration.
- Utility Contractors:Highway maintenance and electrical infrastructure operators face escalating night-work mandates from the Department of Transportation, expanding specification requirements for documented lux-level compliance across work zones.
- Government Agencies:Public works procurement under EU Green Deal frameworks is mandating lower-emission mobile lighting, redirecting specification toward solar hybrid and battery-electric units.
- Security Firms:Perimeter illumination contracts favor portable diesel units with rapid relocation capability.
- Transportation Services:Rail and airport maintenance operations specify tower height and lumen output to meet OSHA minimum illumination enforcement.
Channel flow runs predominantly through rental company intermediation. Direct procurement by utility contractors is gaining share fastest where night-work mandates tighten specification ownership requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The manual lifting mobile light tower industry traces its commercial origins to post-war European construction equipment manufacturing, with German engineering firms pioneering crank-lift mechanisms for temporary job-site illumination before global rental channels emerged.
United States
Utility contractors drive demand through Department of Transportation night-work mandates for highway maintenance operations. OSHA enforces minimum illumination levels across construction zones, tightening lumen output verification requirements. Rental company channels in Texas and California aggregate fleet procurement for fragmented contractor bases seeking operational expenditure flexibility.
Germany
Construction site operators expand compact tower fleets to comply with tightened workplace illumination standards under national occupational safety frameworks. The EU Green Deal redirects public works procurement toward lower-emission solar hybrid and battery-electric units. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate specialized manufacturing for confined urban job sites.
Australia
Mining contractors in Western Australia and Queensland pilot photovoltaic-integrated hybrid units to reduce diesel resupply frequency in remote extraction terrain. TGA-aligned state occupational safety regulators enforce illumination compliance across open-pit operations. Sealed hydraulic lift variants dominate Pilbara iron ore sites where rapid deployment under heavy contamination is mandatory.
China
Domestic infrastructure investment sustains manufacturing scale for crank-lift exports while MIIT battery-electric runtime standards reshape product development cycles. GB standards and dual carbon goals constrain diesel generator acceptance in municipal public works. Yangtze River Delta production clusters supply LED retrofit-compatible towers to Southeast Asian rental markets.
United Arab Emirates
Expo-led infrastructure development and year-round construction activity sustain demand for rapid-deployment illumination systems. Dubai and Abu Dhabi municipal procurement under federal sustainability mandates favors solar hybrid architectures for desert deployment. Security perimeter contracts around critical infrastructure drive diesel-reliability specifications for grid-independent operation.
Manual Lifting Mobile Light Tower Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing strategies. The vendor base separates between integrated power equipment manufacturers with captive generator supply and specialized tower fabricators sourcing engines and lamp assemblies externally. Three archetypes dominate: North American full-line power equipment houses, European compact machinery specialists, and Asian contract manufacturers serving private-label rental channels. Competitive moves concentrate on LED retrofit compatibility engineering and battery-electric platform development.
Among North American power equipment houses, Generac Power Systems occupies a position representing manufacturing scale advantages in integrated generator-tower configurations. Wacker Neuson exemplifies the European compact machinery specialist archetype with German-engineered form factors. Atlas Copco anchors the technology leadership tier through multinational industrial equipment distribution reach.
| Leading Market Players |
|---|
| Generac Power Systems |
| Wacker Neuson |
| Doosan Portable Power |
| Atlas Copco |
| Terex |
| Caterpillar |
| J C Bamford Excavators |
| HIMOINSA |
| Larson Electronics |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up rental fleet operators concentrate procurement leverage across United States and German markets, compressing margins on standardized crank-lift diesel units while rewarding suppliers with captive battery-swap service capabilities. This ownership pattern channels pricing discipline through volume commitment tiers and bundled maintenance contracts rather than transactional spot purchasing.
Pricing Analysis
Three-tier pricing structure across premium hydraulic, standard crank-lift, and economy halogen configurations anchors market transactions. Price differentiation rests on CE marking tier and after-sales service bundling rather than raw lumen output. Cost compression in economy diesel tiers is intensifying because generator emission control component costs escalate under F-Gas Regulation constraints. Rental companies show highest price sensitivity, while Australian mining contractors accept premium positioning for sealed hydraulic systems with rapid-deployment specifications.
Supply Chain Analysis
Refurbishment flows for rental fleet LED retrofits create secondary value recovery channels extending asset lifecycles. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta clusters supplying LED arrays and Bavarian engineering centers producing precision hydraulic cylinders. Lithium-ion cell sourcing draws from East Asian manufacturers, creating single-source vulnerability for battery-electric tower scaling. Distribution runs through rental company intermediaries aggregating fragmented contractor demand across highway maintenance and confined construction verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The manual lifting mobile light tower market compounds steadily through regulatory tightening of workplace illumination standards across construction and mining jurisdictions.
For Market Incumbents: Acquire battery management system engineering capabilities to defend against pure-play electrification specialists entering through solar hybrid certification protocols. Deepen upstream control over LED driver electronics sourcing to offset lithium cell supply concentration. Anchor channel position by embedding predictive maintenance software into rental fleet service contracts. For New Entrants and Emerging Players: Launch via equipment-as-a-service arrangements targeting mid-sized German contractors facing project duration uncertainty under EU Green Deal procurement recalibration. White-space sits with photovoltaic-integrated hybrid units for Australian mining logistics reduction. Penetrate through bundled transport and charging logistics rather than capital equipment sales. For Investors and Strategic Acquirers: Power equipment manufacturers with captive generator production are the most active acquirer in this space, seeking LED retrofit platform targets. Five-to-ten year viability hinges on battery-electric runtime standard compliance rather than mechanical lift patent positions. Watch for MIIT battery certification announcements in China as inflection signal for production scaling viability.| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Platform Development | Atlas Copco extends technology leadership through backward compatibility engineering across existing tower installed base. |
| Battery Swap Service Network | Rental channel partners lock in recurring revenue streams beyond equipment sales through operational expenditure bundling. |
| Solar Hybrid Certification Achievement | First-mover manufacturers secure EU Green Deal procurement eligibility ahead of F-Gas Regulation enforcement tightening. |
| Hydraulic Lift Sealed System Specialization | Premium positioning in Australian Pilbara iron ore sites commands pricing power through contamination resistance specifications. |
| Predictive Maintenance Software Integration | Competitive differentiation shifts from lumen output metrics to total cost of ownership optimization for rental fleet operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with rental fleet managers, mining procurement officers, construction safety directors, and aftermarket service heads with secondary validation against OSHA enforcement records, EU Machinery Directive certification databases, and customs trade flows. Bottom-up unit deployment estimates triangulated against top-down rental channel revenue aggregation.
Historical reference periods anchored projection assumptions across the modeling period, with segmentation dimensions spanning lift mechanism architecture, power technology configuration, application intensity, and end-user channel structure. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns in LED and battery-electric categories. Forecast inputs incorporated diesel fuel price volatility scenarios and lithium cell supply elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery-electric runtime standard acceleration or F-Gas Regulation cooling system restriction tightening. Practitioners should monitor TGA enforcement intensity in Australian mining jurisdictions and Department of Transportation night-work mandate expansion for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Rubber Tyre Gantry Crane Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Brazil Forklift Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
North America Screw Conveyor Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Vertical Lifts Market