
 Rough Terrain Lift Truck Market | 2026-2036
Rough Terrain Lift Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Rough Terrain Lift Truck Market Outlook
North American rough terrain lift truck production capacity is expanding across Oklahoma and Texas manufacturing corridors. Hyster-Yale Materials Handling Inc. leverages its vertical integration into mast and chassis fabrication to control cost structures in volatile steel markets. Komatsu Ltd. anchors its position through deep R&D investment in hydrostatic transmissions for uneven ground conditions. Manitou Group differentiates via specialized telehandler architectures purpose-built for European forestry slopes.
Rough terrain lift trucks are four-wheel-drive material handling vehicles engineered with oscillating axles, minimum 12-inch ground clearance, and reinforced frames to operate on unpaved surfaces exceeding 20 percent grades. These machines primarily serve construction, mining, and agricultural zones where conventional warehouse forklifts cannot maintain traction or stability. Diesel configurations still dominate installed bases due to torque requirements and refueling infrastructure in remote job sites, though hybrid powertrains are capturing fastest growth in emission-sensitive European forestry and urban construction applications. Electric variants remain niche but are deepening penetration in underground mining where ventilation constraints limit internal combustion operation. Capacity demand clusters at 3-ton and 5-ton ratings for multi-pallet construction logistics and heavy component placement.
EPA Tier 4 Final and OSHA powered industrial truck standards govern US product certification, while EU Stage V and machinery CE marking directives shape European market access and engine technology roadmaps. These frameworks compel manufacturers to absorb exhaust after-treatment costs or pivot toward electrified architectures. Stakeholders must monitor battery energy density breakthroughs and charging infrastructure buildouts in remote extraction zones to assess when electric platforms can displace diesel economics without sacrificing duty-cycle performance.
Market Dynamics
Emissions compliance deadlines are compressing powertrain development cycles across the rough terrain lift truck sector, forcing manufacturers to absorb after-treatment costs or accelerate electrification roadmaps ahead of remote-site charging infrastructure readiness.
Growth Catalysts
- EPA Tier 4 Final:US shale patch operators face mandated fleet turnover, triggering replacement demand for compliant diesel and hybrid units in Oklahoma and Texas extraction corridors.
- Telehandler architectures:Specialized boom configurations purpose-built for European forestry slopes are expanding addressable terrain grades beyond conventional forklift limits.
- Australian mining corridors:Underground ventilation constraints are accelerating electric platform trials where diesel particulate exposure exceeds occupational exposure limits.
Market Restraints
- Steel input volatility:Mast and chassis fabrication costs fluctuate with scrap and alloy pricing, squeezing margin structures for manufacturers without captive metallurgical supply.
- Battery energy density ceilings:Current lithium-ion chemistries cannot match diesel duty-cycle endurance for multi-shift remote operations without mid-cycle swapping infrastructure.
- EU Stage V compliance costs:Exhaust after-treatment systems add capital burden and maintenance complexity for equipment deployed across dispersed European construction sites.
Strategic Opportunities
- Brazil construction acceleration:Infrastructure investment programs are expanding rough terrain lift truck deployment in unpaved urban periphery zones lacking grid connectivity for pure electric alternatives.
- OSHA powered industrial truck standards:Updated certification requirements create competitive differentiation for manufacturers with in-house testing capabilities versus third-party-dependent competitors.
- Hydrostatic transmission convergence:Integration of continuously variable drive systems with telematics platforms enables predictive maintenance revenue streams in high-utilization rental fleets.
Industry Challenges
- Certification timeline compression:Parallel EPA, OSHA, and EU machinery directive approvals require dedicated regulatory affairs capacity that strains mid-tier engineering organizations.
- Electrification skill gaps:Field technician pools trained in internal combustion diagnostics require reskilling for high-voltage battery management and thermal runaway protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rough Terrain Lift Truck Market |
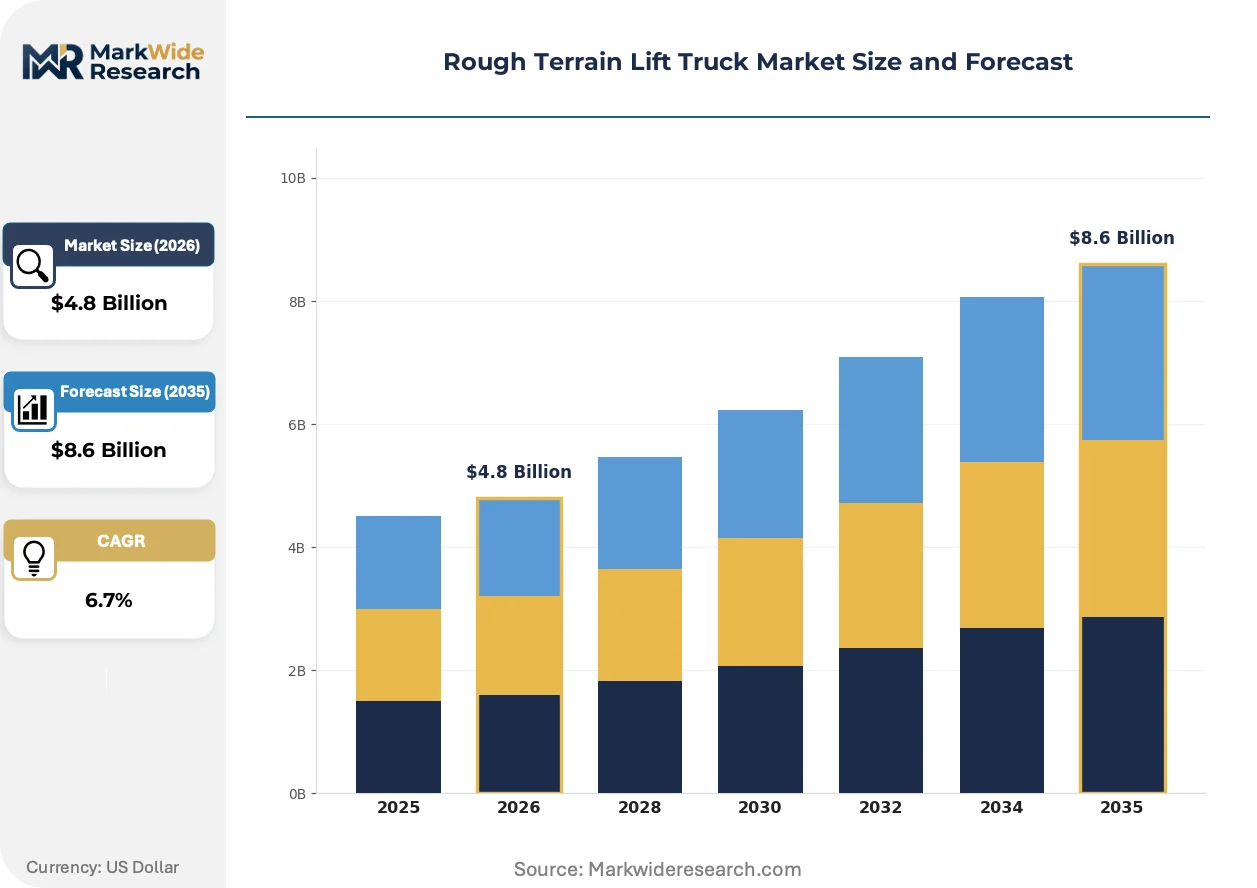
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel, Electric, Hybrid, Gasoline End User: Construction, Agriculture, Mining, Forestry Capacity: 1 Ton, 2 Ton, 3 Ton, 5 Ton Application: Material Handling, Loading, Unloading, Transport |
| Companies Covered | Hyster-Yale Materials Handling Inc., Mitsubishi Logisnext Co., Ltd., Toyota Industries Corporation, Komatsu Ltd., Manitou Group, KION Group AG, Crown Equipment Corporation, Doosan Industrial Vehicle, Jungheinrich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rough Terrain Lift Truck Market Strategic Shifts
Powertrain electrification and connected fleet management are converging to redefine equipment utilization models, shifting competitive advantage from mechanical durability toward software-enabled uptime guarantees and energy cost predictability.
Hydrostatic transmission systems with integrated terrain-sensing load modulation are rewriting traction control performance standards for uneven ground operation. Underground mining contractors in Australia are adopting these configurations to maintain productivity on 20 percent grades without wheel slippage. The technology is compressing the performance gap between diesel torque delivery and electric motor responsiveness in low-speed high-load cycles.
EU Stage V emissions enforcement is mandating diesel particulate filter and selective catalytic reduction installation across all non-road mobile machinery categories. Manufacturers serving European forestry and construction verticals must reconfigure engine bays and cooling systems to accommodate after-treatment hardware. Equipment deployed in German and Austrian alpine zones faces additional altitude derating complications that favor larger displacement powerplants or hybrid architectures.
Rental fleet operators are unbundling maintenance contracts from equipment leases and pricing service intervals as variable consumption. Construction contractors in North American shale regions are selecting providers based on guaranteed availability metrics rather than capital cost alone. This behavioral shift concentrates procurement authority with national rental chains possessing distributed parts inventories and mobile technician networks.
Rough Terrain Lift Truck Market Segmentation
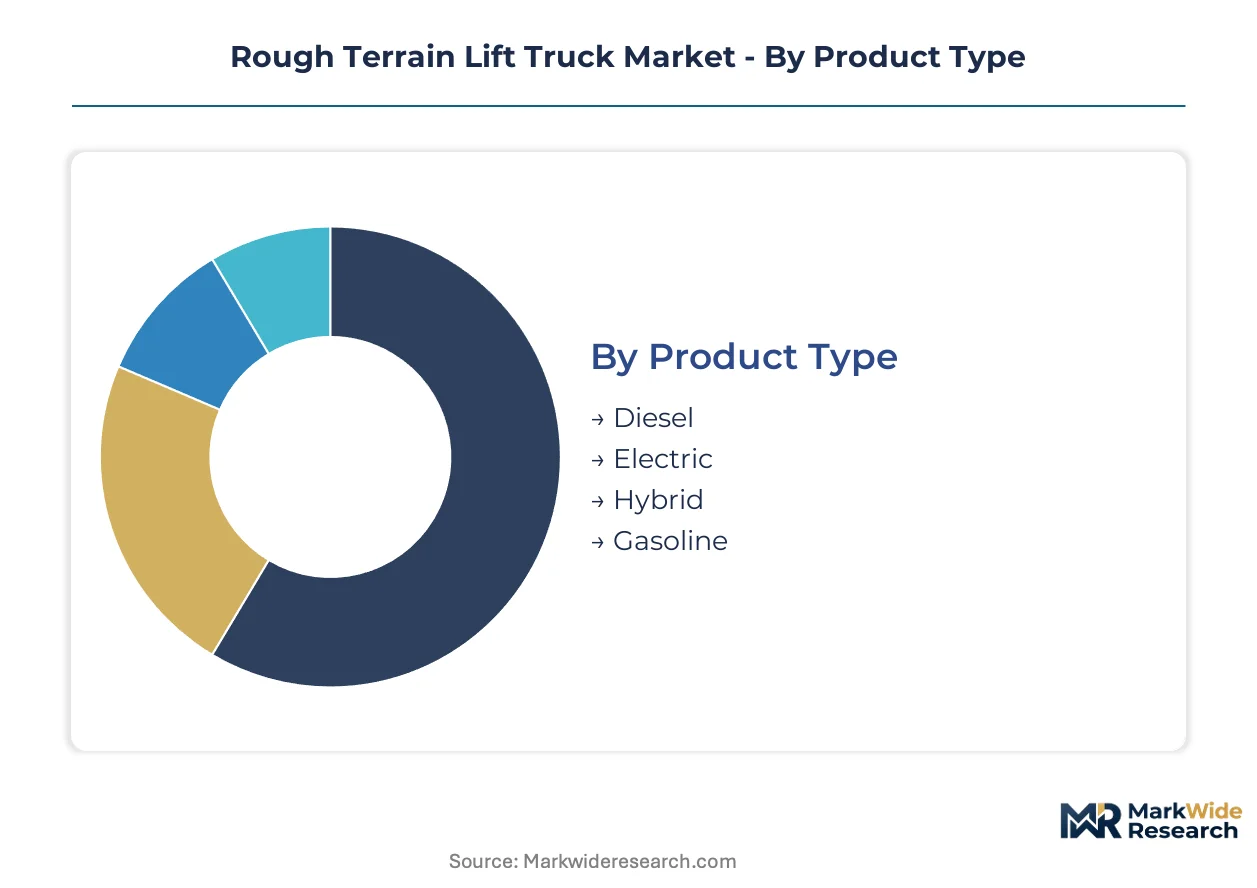
Rough terrain lift truck procurement patterns diverge sharply across powertrain types, with emissions compliance deadlines and remote-site refueling infrastructure dictating segment selection. Capacity ratings cluster around specific end-use workflows, while application intensity determines fleet replacement cycles and aftermarket service revenue potential.
Product Type:
Diesel configurations carry the heaviest certification burden under EPA Tier 4 Final and EU Stage V, while electric and hybrid variants navigate OSHA electrical safety standards and machinery CE marking for high-voltage systems.
- Diesel:Compression-ignition engines with exhaust after-treatment hardware dominate installed bases across Australian mining corridors and Brazilian construction zones lacking grid connectivity. Remote-site refueling infrastructure and torque requirements for 20 percent grades sustain demand despite emissions compliance costs.
- Electric:Lithium-ion battery packs with thermal management systems penetrate underground mining operations where ventilation constraints limit internal combustion. Australian contractors in Western Australia and Queensland lead adoption where diesel particulate exposure exceeds occupational limits.
- Hybrid:Parallel electric-diesel architectures capture fastest growth in European forestry slopes facing Stage V deadlines. German and Austrian alpine equipment faces altitude derating complications that favor hybrid torque supplementation over pure diesel downsizing.
- Gasoline:Spark-ignition units serve niche agricultural applications with intermittent duty cycles and lower capital budgets. Brazilian smallholder operations and North American hobby farms represent primary deployment zones.
Diesel sits at the top of the volume ranking, with hybrid climbing the fastest as European emissions deadlines compress powertrain transition timelines.
End User:
Customer procurement authority concentrates with rental fleet operators in construction, while mining and forestry verticals favor direct manufacturer relationships for specialized configurations.
- Construction:Multi-pallet logistics and heavy component placement on unpaved sites drive 3-ton and 5-ton demand clusters. North American shale patch operators in Oklahoma and Texas prioritize guaranteed availability metrics over capital cost in rental selections.
- Mining:Underground ventilation constraints and 20 percent grade traction requirements shape specification priorities. Australian corridor contractors adopt hydrostatic transmission configurations to maintain productivity without wheel slippage.
- Agriculture:Seasonal utilization patterns and capital budget constraints favor lower-capacity units with simplified maintenance protocols. Brazilian infrastructure investment programs expand deployment in unpaved urban periphery zones.
- Forestry:Specialized telehandler architectures with extended reach and slope stability systems address European terrain grades beyond conventional forklift limits. EU Stage V compliance adds after-treatment complexity for dispersed site service.
Construction commands the largest fleet volumes, with mining gaining share fastest as electrification trials accelerate in ventilation-constrained extraction zones.
Capacity:
Manufacturing cost structures scale non-linearly with capacity, with 5-ton frames requiring reinforced metallurgy that exposes producers to steel input volatility.
- 3 Ton:Multi-pallet construction logistics represent the commercial sweet spot for rental fleet standardization. Oklahoma and Texas shale operators specify this rating for balance between lifting capability and transportability between dispersed well pads.
- 5 Ton:Heavy component placement in mining and infrastructure applications demands reinforced frames and oscillating axle systems. Mast and chassis fabrication costs fluctuate with scrap and alloy pricing, squeezing margin structures.
- 1 Ton:Compact units serve agricultural maintenance and light construction with lower capital barriers. Brazilian smallholder operations favor this rating for intermittent duty cycles.
- 2 Ton:Mid-range capacity bridges light agricultural use and secondary construction support roles. European forestry contractors specify 2-ton units for slope stability in thinning operations.
3-ton ratings anchor volume leadership, with 5-ton specifications expanding most quickly in mining corridor capital investment cycles.
Application:
Intensity of duty cycle and terrain interaction severity determine component wear rates and aftermarket service attach rates across application types.
- Material Handling:Continuous load cycling on uneven surfaces drives axle and mast stress concentration. Australian mining contractors prioritize hydrostatic transmission integration for terrain-sensing load modulation.
- Loading:High-impact entry into dump trucks and hoppers subjects frames to shock loading beyond steady-state ratings. Brazilian construction acceleration in urban periphery zones strains equipment durability.
- Unloading:Precision placement requirements on slopes demand telehandler boom configurations with load moment indicators. European forestry slopes exceed conventional forklift stability limits.
- Transport:Road travel between dispersed sites imposes vibration fatigue distinct from operational loading cycles. North American shale patch mobility requirements favor compact 3-ton configurations.
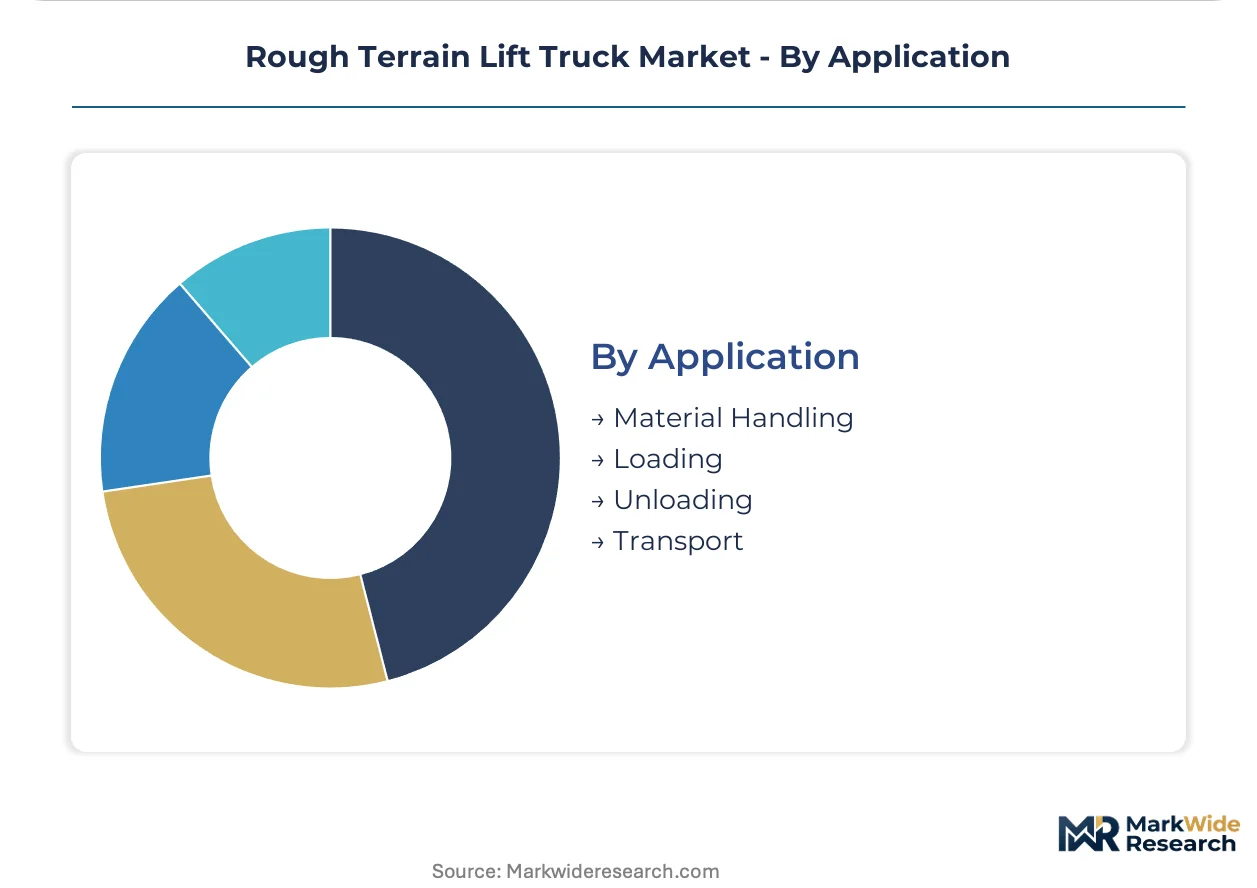
Material Handling generates the highest fleet hours, with Loading applications showing steepest expansion trajectory as Brazilian infrastructure programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian mining corridors and Brazilian construction zones present contrasting electrification trajectories, with ventilation-constrained underground operations accelerating battery adoption while grid-limited peripheries sustain diesel dominance.
United States
Shale patch operators in Oklahoma and Texas drive replacement demand as EPA Tier 4 Final deadlines compress fleet turnover timelines. OSHA powered industrial truck standards govern certification protocols for rental fleet deployments. The Permian Basin extraction corridor concentrates procurement authority with national rental chains emphasizing guaranteed availability metrics over capital cost.
Australia
Western Australian and Queensland underground mining contractors prioritize electric platforms where diesel particulate exposure exceeds occupational limits. State-level mining safety regulators enforce ventilation standards that effectively mandate zero-emission trials in deep extraction zones. The Pilbara iron ore corridor hosts accelerated hydrostatic transmission adoption for 20 percent grade traction without wheel slippage.
Brazil
Federal infrastructure investment programs expand rough terrain lift truck deployment across unpaved urban periphery zones lacking grid connectivity. ANVISA occupational health standards intersect with environmental licensing for mining-adjacent construction projects. São Paulo state construction corridors concentrate diesel and hybrid unit procurement for multi-pallet logistics on developing road networks.
Germany
Alpine forestry contractors face EU Stage V compliance deadlines that favor hybrid architectures over pure diesel downsizing given altitude derating complications. The country's federal motor transport authority enforces machinery CE marking directives for cross-border equipment mobility. Bavarian and Baden-Württemberg forestry zones exceed conventional forklift stability limits, driving specialized telehandler specification.
Japan
Domestic construction machinery producers advance hydrostatic transmission R&D for export markets while domestic demand concentrates on compact urban applications. METI industrial standards shape high-voltage system certification for emerging electric platforms. The Chubu manufacturing corridor around Nagoya anchors precision component fabrication for oscillating axle assemblies.
Rough Terrain Lift Truck Market Competitive Environment
North American producers anchor one tier; European specialists hold differentiated positions in slope-specific architectures. The vendor base separates into three tiers: integrated chassis-mast fabricators controlling metallurgical input costs, transmission technology licensors, and regional assemblers dependent on outsourced powertrains. Two strategic archetypes dominate: vertically integrated manufacturers absorbing steel volatility through captive supply, and technology-focused developers monetizing hydrostatic and electrification intellectual property. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with particular emphasis on distributed service networks for rental fleet coverage.
Within the integrated manufacturing tier, Hyster-Yale Materials Handling Inc. and Komatsu Ltd. exemplify divergent geographic anchoring and scale positioning. Manitou Group occupies a specialization node purpose-built for European terrain grades. Among Japanese industrial conglomerates, Toyota Industries Corporation and Mitsubishi Logisnext Co., Ltd. represent scale-driven entries with cross-sector material handling portfolios. Doosan Industrial Vehicle and Jungheinrich AG sit within the European-Germanic engineering tradition emphasizing precision transmission integration.
| Leading Market Players |
|---|
| Hyster-Yale Materials Handling Inc. |
| Mitsubishi Logisnext Co., Ltd. |
| Toyota Industries Corporation |
| Komatsu Ltd. |
| Manitou Group |
| KION Group AG |
| Crown Equipment Corporation |
| Doosan Industrial Vehicle |
| Jungheinrich AG |
| Others |
Value Chain & Pricing Dynamics
Hydrostatic transmission convergence across North American and European assembly plants is compressing component procurement timelines while redistributing margin capture toward transmission technology licensors and away from pure chassis fabricators. This manufacturing-method transition forces tier-two suppliers to absorb steel volatility or cede pricing power to integrated OEMs with captive metallurgical supply.
Pricing Analysis
Capacity additions in Oklahoma and Texas are reshaping price floors for 3-ton and 5-ton diesel configurations serving shale patch operators. Three-tier pricing structure across EPA Tier 4 Final-certified premium units, standard diesel platforms, and economy gasoline variants reflects certification cost absorption and steel input exposure. Pricing pressure stems from alloy scrap volatility squeezing mast fabrication margins. Rental fleet operators show lowest price sensitivity due to guaranteed availability contracting, while Brazilian smallholder agricultural buyers drive economy-tier volume.
Supply Chain Analysis
Domestic-content mandates under Brazil's infrastructure investment programs and Australia's local procurement preferences for mining equipment are reshaping sourcing patterns for oscillating axle assemblies and high-strength chassis components. Manufacturing gravity centers on Japan, Germany, and the United States for precision transmission systems, with mast and chassis fabrication drawing from Chinese and South Korean steel processing. Supply chain risk hinges on single-source vulnerability for hydrostatic transmission controllers. Distribution runs through national rental chains with captive service networks rather than independent dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rough terrain lift truck market functions as a geographic-arbitrage play between EU Stage V compliance costs accelerating hybrid adoption in alpine forestry zones and Brazilian grid-limited peripheries sustaining diesel economics without after-treatment burden.
For Market Incumbents: Deepen backward integration into high-strength alloy supply to defend margin structures against scrap price volatility threatening mast fabricators. Prioritize captive metallurgical capacity over outsourced chassis production. Certify electric platforms under OSHA electrical safety standards ahead of ventilation-constrained mining demand inflection to preempt emerging pure-play battery OEMs.
For New Entrants and Emerging Players: Telematics-enabled predictive maintenance platforms offer the lowest-friction entry path into North American rental fleet procurement workflows. Target Australian underground mining contractors for electric platform trials where diesel particulate exposure limits create immediate substitution demand. Lead with guaranteed uptime contracting rather than capital cost positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers dependent on outsourced powertrains facing EPA and EU certification timeline compression. Long-term viability favors integrated chassis-mast fabricators with captive steel supply and in-house regulatory affairs capacity. Monitor battery energy density breakthroughs in heavy-duty mining applications as the signal for electric platform economics crossing diesel parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive metallurgical capacity insulates margin structures from scrap volatility affecting mast fabrication costs. |
| Hydrostatic Transmission R&D Partnership | Continuously variable drive integration with terrain-sensing load modulation commands premium positioning in Australian mining corridors. |
| Electric Platform OSHA Certification | Early electrical safety standard compliance creates differentiation for ventilation-constrained underground mining procurement. |
| Telematics-Enabled Predictive Maintenance | Software-layer revenue streams transform rental fleet relationships from equipment lessor to uptime guarantor. |
| Brazilian Local Content Manufacturing | Domestic assembly presence satisfies infrastructure program procurement preferences in grid-limited construction zones. |
Study Parameters
Coverage spans North America, Europe, Australia, and Brazil, with primary inputs from each region's construction and mining corridors. The approach combines interviews with maintenance directors at rental fleet operators, OEM procurement teams specifying hydrostatic transmissions, aftermarket service heads managing distributed technician networks, and plant engineers in shale extraction zones. Secondary validation draws from EPA certification filings, EU machinery directive documentation, Australian mining safety regulator guidance, and Brazilian ANVISA occupational health standards. Bottom-up unit demand modeling triangulates against top-down market value reconstruction.
Granularity extends to powertrain type, capacity rating, and end-use vertical with regional regulatory cluster differentiation. Segmentation dimensions include diesel-electric-hybrid-gasoline architectures, 1-ton through 5-ton capacity tiers, and construction-mining-agriculture-forestry applications. CAGRs derive from fitted growth curves against historical replacement cycles and emissions compliance deadline impacts. Forecast inputs incorporate steel price trajectory assumptions and battery energy density evolution pathways for underground mining electrification.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for diesel displacement timelines. Forecasts reflect assumptions regarding EPA and EU enforcement consistency, mining ventilation regulation stringency, and infrastructure investment continuity across the analysis window. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Material Handling Monorails Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Shaft Shredder Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Global Dewatering Equipment Market
Material Handling Equipment
Global Hopper Loader Market