
 Brazil Contraceptive Devices Market | 2026-2036
Brazil Contraceptive Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Contraceptive Devices Market Outlook
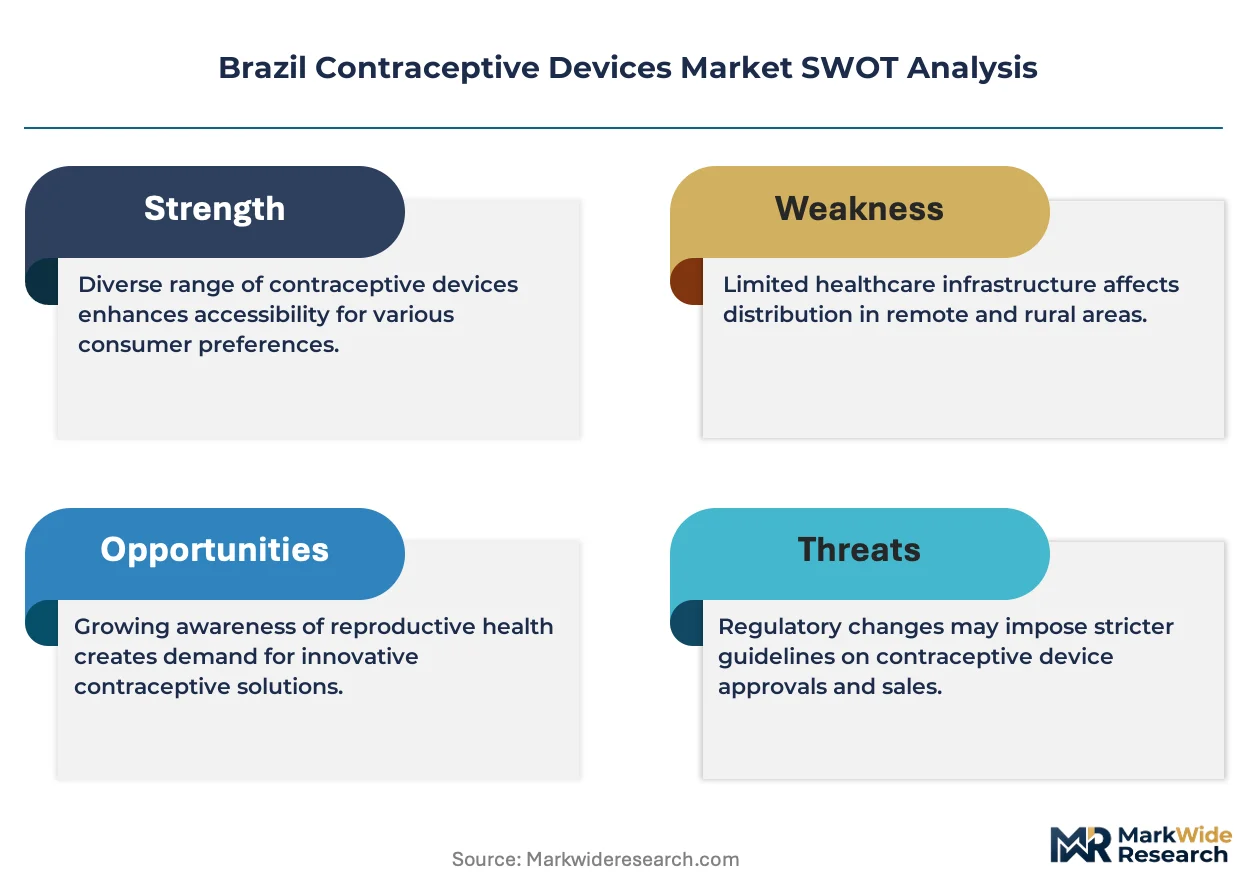
Brazil's National Health Surveillance Agency (ANVISA) updated medical device quality guidelines is rebalancing procurement standards toward higher-assurance product tiers. Bayer AG leverages its hormonal intrauterine device portfolio to sustain institutional contracts with the Unified Health System. Church & Dwight Co., Inc. anchors its position through over-the-counter condom distribution across pharmacy chains nationwide. CooperSurgical Inc. specializes in clinical training programs that differentiate its implant insertion services from commodity competitors.
Contraceptive devices encompass intrauterine systems, barrier methods, subdermal implants, and cervical barriers engineered from medical-grade polymers, silicone elastomers, or copper alloys, designed to prevent pregnancy through hormonal release, physical obstruction, or spermicidal action. Intrauterine devices command the largest installed base among product types due to their multi-year efficacy and reimbursement alignment with public health budgets. Contraceptive implants represent the fastest-expanding segment as healthcare providers shift toward long-acting reversible methods that reduce patient non-compliance. Over-the-counter delivery mode channels capture significant volume through pharmacy networks, though prescription pathways retain margin concentration for clinic-administered implants and IUD insertions.
ANVISA governs pre-market registration, good manufacturing practice certification, and post-market surveillance for all contraceptive devices commercialized in Brazil. The Ministry of Health's incorporation guidelines into the Unified Health System determine which products achieve national reimbursement, directly shaping manufacturer market access and pricing negotiations. State health secretariats in São Paulo, Minas Gerais, and Rio de Janeiro administer regional procurement tenders that fragment purchasing power across sub-national jurisdictions. Stakeholders must monitor ANVISA's alignment with International Organization for Standardization medical device standards and anticipate how municipal budget cycles redistribute access between public clinics and private pharmacy channels.
Market Dynamics
ANVISA's streamlined registration pathways for hormonal implants are compressing time-to-market cycles and reallocating procurement power toward manufacturers with established quality assurance systems. This regulatory acceleration is restructuring competitive positioning around institutional contract capture rather than retail channel dominance.
Growth Catalysts
- Unified Health System expansion:Public health clinics in São Paulo and Rio de Janeiro metropolitan networks are prioritizing long-acting reversible contraceptive uptake, creating institutional demand pull for implant and IUD suppliers.
- ANVISA registration streamlining:The agency's updated medical device quality guidelines are reducing pre-market approval timelines, enabling faster product availability for hormonal implant manufacturers.
- Silicone elastomer advances:Medical-grade polymer improvements are extending implant efficacy durations and reducing insertion-related complications, improving patient retention rates.
Market Restraints
- Copper alloy supply concentration:Non-hormonal IUD manufacturers face input cost volatility from concentrated copper sourcing channels, compressing margins on public sector tenders.
- Regional procurement fragmentation:State health secretariats in Minas Gerais and Rio de Janeiro administer independent purchasing systems, diluting volume leverage and complicating national distribution strategies.
- Religious institution opposition:Catholic healthcare networks in Brazil's Northeast region restrict contraceptive device availability, creating geographic access gaps that limit market penetration.
Strategic Opportunities
- Pharmacy chain integration:Over-the-counter condom and emergency contraceptive distribution through nationwide retail networks offers volume expansion beyond clinic-dependent segments.
- Clinical training service bundling:Implant insertion competency programs create differentiation for manufacturers targeting private healthcare providers seeking to expand long-acting reversible method offerings.
- Municipal budget cycle alignment:Timing product launches and contract negotiations with São Paulo state fiscal calendars captures procurement windows that competitors miss.
Industry Challenges
- Insertion skill scarcity:Subdermal implant administration requires specialized clinical training that remains unevenly distributed across Brazil's public health workforce, limiting rollout velocity.
- Post-market surveillance compliance:ANVISA's adverse event reporting requirements demand sustained pharmacovigilance infrastructure that smaller manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Contraceptive Devices Market |
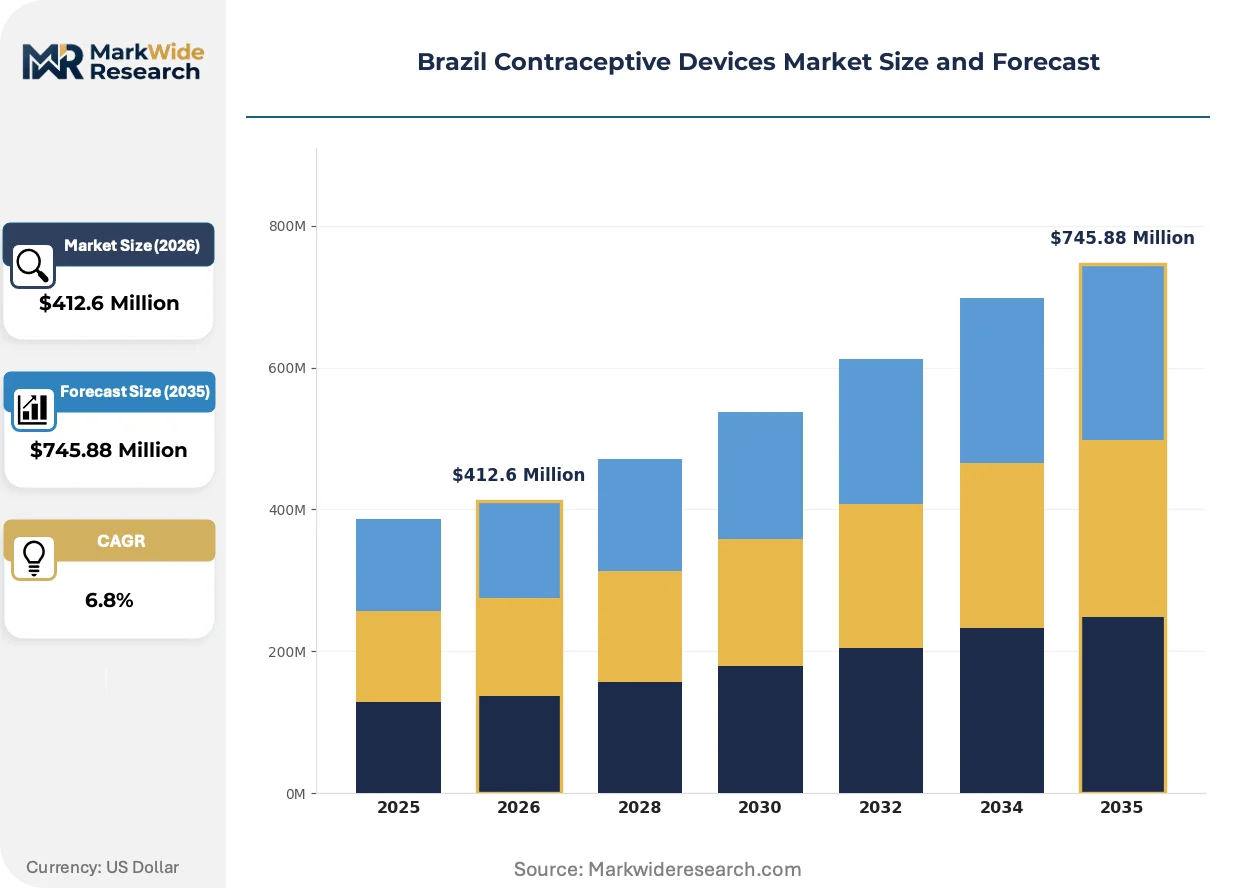
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intrauterine Devices, Condoms, Contraceptive Implants, Diaphragms End User: Healthcare Providers, Pharmacies, Clinics, Hospitals Delivery Mode: Prescription, Over-the-Counter, Online, Direct Distribution Age Group: Adolescents, Adults, Middle-Aged, Seniors |
| Companies Covered | Bayer AG, Ansell Ltd, Reckitt Benckiser Group plc, Church & Dwight Co., Inc., LifeStyles Healthcare, Hypera Pharma S.A., CooperSurgical Inc., Merck & Co., Pfizer Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Contraceptive Devices Market Strategic Shifts
Biocompatible material science and digital health integration are reshaping contraceptive device development trajectories. Manufacturers are repositioning around patient adherence monitoring and provider workflow efficiency rather than efficacy alone.
Biodegradable polymer technology is integrating hormone-release kinetics with structural degradation timelines, enabling single-implant designs that eliminate removal procedures. Private clinics in São Paulo are piloting these systems for patient segments prioritizing convenience. The technology is integrating insertion and follow-up services into unified care bundles that command premium positioning.
ANVISA's alignment with International Organization for Standardization medical device standards is elevating certification requirements for imported hormonal implants. European manufacturers with existing ISO 13485 quality systems are gaining faster market access than competitors relying on legacy documentation. Domestic distributors are responding by pre-qualifying suppliers against these standards before tender participation.
Patient preference for discreet, long-acting methods is compressing switching cycles from oral contraceptives toward clinic-administered implants and IUDs. Young adult demographics in Rio de Janeiro metropolitan networks are driving this shift, with pharmacy chains adapting by expanding referral partnerships with private clinics. The Southeast region exhibits the strongest behavioral pivot away from daily compliance-dependent methods.
Brazil Contraceptive Devices Market Segmentation
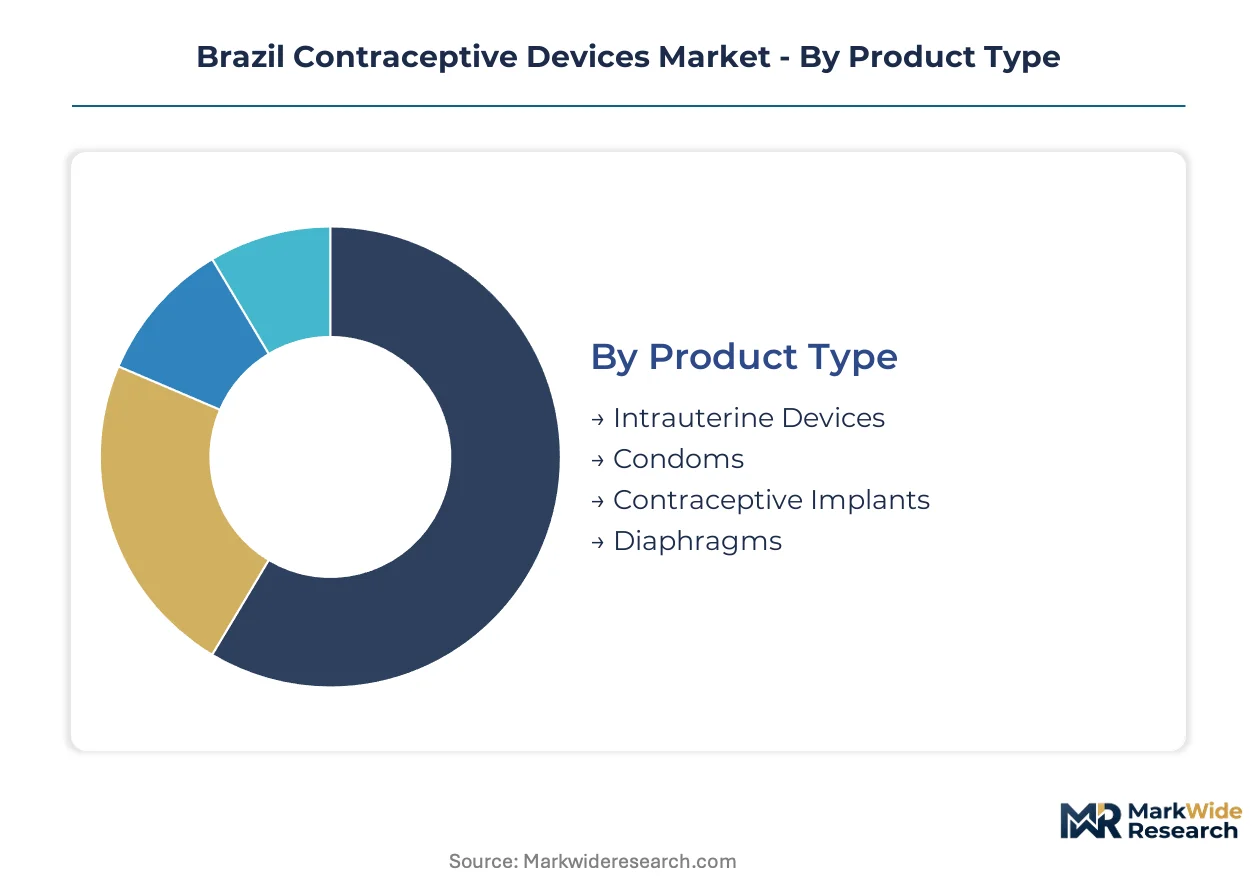
Brazil's contraceptive devices market fragments across four distinct dimensions that determine procurement pathways and margin structures. Product type dictates reimbursement eligibility under the Unified Health System, while delivery mode shapes competitive intensity between institutional tenders and retail pharmacy networks.
Product Type:
Clinical efficacy duration and insertion complexity drive provider selection between long-acting and user-administered methods.
- Intrauterine Devices:Copper and hormonal variants fabricated from medical-grade polymers or copper alloys deliver multi-year pregnancy prevention. São Paulo metropolitan clinics prioritize IUD uptake for patient retention, though copper alloy input costs pressure margins on non-hormonal tenders.
- Contraceptive Implants:Subdermal rods release progestin through silicone elastomer matrices over three to five years. Rio de Janeiro private clinics are expanding implant services fastest as young adults abandon daily compliance-dependent methods.
- Condoms:Latex and polyurethane barrier methods dominate pharmacy over-the-counter channels through nationwide retail distribution.
- Diaphragms:Cervical barriers require clinical fitting and spermicide co-application, limiting uptake to specialized family planning services.
Volume sits with Intrauterine Devices; growth tilts toward Contraceptive Implants.
End User:
Procurement authority concentration varies sharply between centralized public health systems and fragmented private retail networks.
- Healthcare Providers:Unified Health System clinics in Southeast Brazil administer subsidized implants and IUDs through trained nursing staff. Budget cycle alignment with São Paulo state fiscal calendars determines contract capture timing.
- Pharmacies:Over-the-counter condom and emergency contraceptive sales flow through chains with national distribution infrastructure. Church & Dwight anchors shelf presence through volume commitments.
- Clinics:Private facilities in Rio de Janeiro metropolitan networks bundle insertion services with follow-up care, commanding premium positioning for long-acting methods.
- Hospitals:Maternity wards and gynecological departments provide postpartum IUD insertion, capturing patients at high-compliance decision moments.
Procurement concentrates with Healthcare Providers; margin expansion favors Clinics.
Delivery Mode:
Regulatory pathway complexity separates prescription-controlled clinic administration from unrestricted retail access.
- Prescription:ANVISA-mandated medical supervision applies to hormonal implants and IUDs, creating barrier-to-entry for manufacturers lacking clinical training infrastructure.
- Over-the-Counter:Condoms and select emergency contraceptives bypass prescription requirements, driving volume through pharmacy chain density in Minas Gerais and Rio de Janeiro.
- Online:E-commerce platforms expand reach to remote municipalities underserved by physical pharmacy networks, though last-mile logistics remain uneven.
- Direct Distribution:Manufacturers bypass wholesalers to supply large clinic chains, preserving margin on high-value implant and IUD products.
Volume flows through Over-the-Counter; regulatory streamlining accelerates Prescription pathways.
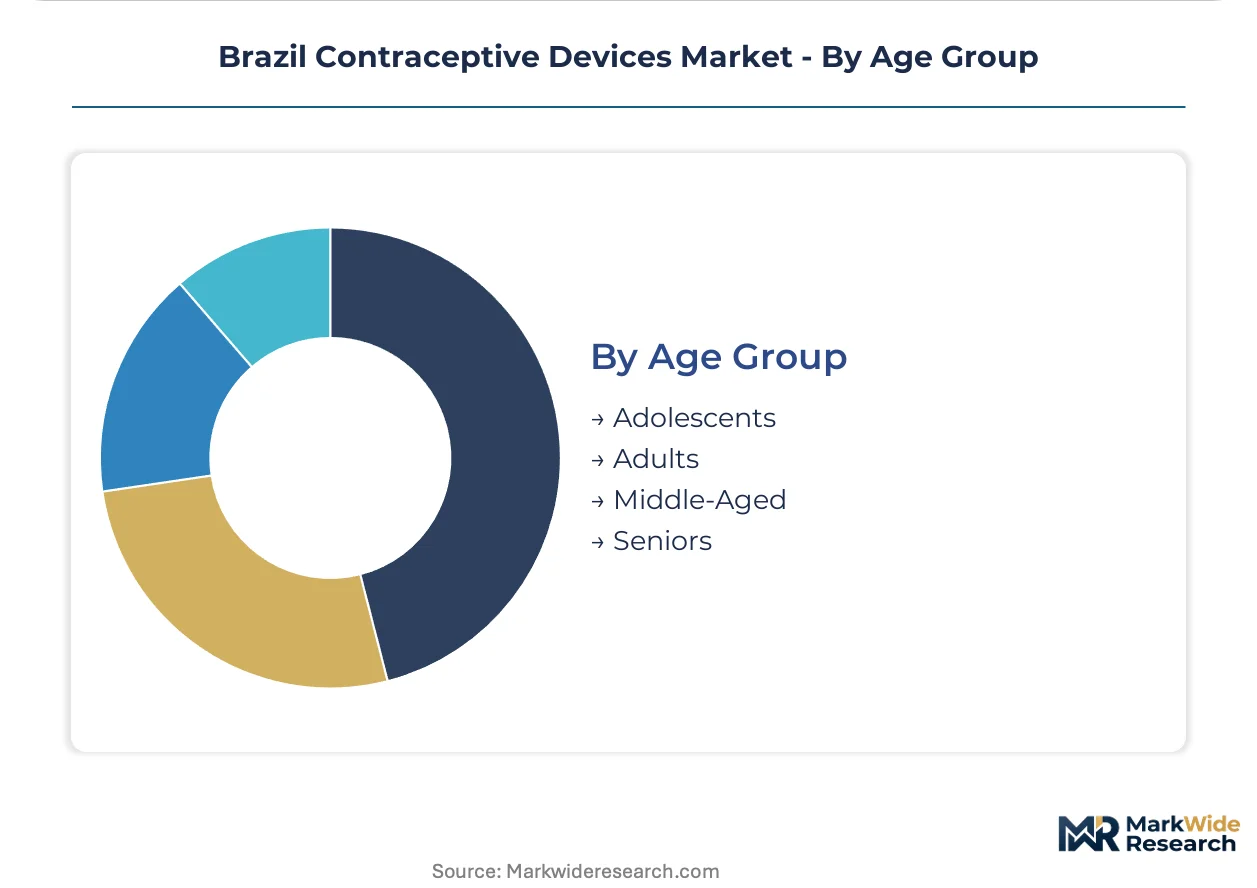
Age Group:
Life-stage contraceptive needs shift method preference from initiation education through menopausal transition.
- Adults:Women aged 18-35 in Southeast Brazil drive fastest uptake of long-acting reversible methods as career timing priorities displace daily pill compliance.
- Adolescents:School-based health programs in São Paulo state distribute condoms and counseling, though parental consent requirements create access friction.
- Middle-Aged:Perimenopausal women transition from hormonal methods to barrier alternatives as fertility decline reduces pregnancy risk calculus.
- Seniors:Post-menopausal populations exit active contraceptive use, though STI protection needs sustain marginal condom demand.
Demand concentrates with Adults; policy attention targets Adolescents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Brazil's contraceptive devices activity through its dense metropolitan network of Unified Health System clinics and private healthcare facilities. The Southeast region generates the strongest demand concentration, with state health secretariats in São Paulo, Rio de Janeiro, and Minas Gerais administering independent procurement systems that fragment purchasing power across sub-national jurisdictions.
São Paulo
Metropolitan São Paulo drives institutional volume through its network of public health clinics prioritizing long-acting reversible contraceptive uptake. ANVISA's streamlined registration pathways enable faster product availability for hormonal implant manufacturers targeting this market. The state's fiscal calendar determines contract capture timing for suppliers aligned with municipal budget cycles.
Rio de Janeiro
Rio de Janeiro's private clinics expand implant services fastest as young adults abandon daily compliance-dependent methods. State health secretariats administer procurement tenders independently from São Paulo, diluting national volume leverage. The metropolitan network bundles insertion services with follow-up care, commanding premium positioning for clinic-administered methods.
Minas Gerais
Minas Gerais exhibits pharmacy chain density that channels over-the-counter condom volume through nationwide retail distribution networks. ANVISA governs pre-market registration and post-market surveillance for all commercialized devices in the state. Regional procurement fragmentation complicates distribution strategies for manufacturers seeking consistent supply.
Rio Grande do Sul
Rio Grande do Sul maintains established healthcare infrastructure with moderate contraceptive device penetration relative to Southeast neighbors. The Ministry of Health's incorporation guidelines into the Unified Health System determine product reimbursement eligibility. Municipal health networks in Porto Alegre administer localized procurement with varying budget allocations.
Bahia
Bahia presents geographic access gaps where Catholic healthcare networks restrict contraceptive device availability in certain municipalities. ANVISA's alignment with International Organization for Standardization medical device standards elevates certification requirements for imported products. Salvador's metropolitan clinics represent the primary institutional demand concentration in the Northeast region.
Brazil Contraceptive Devices Market Competitive Environment
The competitive structure tilts toward diversified healthcare conglomerates with institutional contract capabilities. Pharmaceutical and medical device multinationals occupy premium positioning through hormonal implant and intrauterine device portfolios, while consumer health specialists dominate over-the-counter channels. Three archetypes prevail: integrated pharma-device conglomerates, consumer health distributors, and clinical service bundlers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers seek to capture Unified Health System tenders.
Among the integrated healthcare conglomerates, Bayer AG and Merck & Co. exemplify the pharmaceutical-device hybrid archetype through institutional contract positioning. Church & Dwight Co., Inc. anchors the consumer health tier with nationwide pharmacy distribution infrastructure. CooperSurgical Inc. occupies a specialist position emphasizing clinical training capabilities that differentiate service offerings from commodity competitors.
| Leading Market Players |
|---|
| Bayer AG |
| Ansell Ltd |
| Reckitt Benckiser Group plc |
| Church & Dwight Co., Inc. |
| LifeStyles Healthcare |
| Hypera Pharma S.A. |
| CooperSurgical Inc. |
| Merck & Co. |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive production of medical-grade silicone elastomers and copper alloys anchors supply positioning for implant and IUD manufacturers, directly shaping their pricing power in Brazil's fragmented procurement environment. ANVISA's ISO 13485 alignment requirements favor integrated players with in-house polymer compounding capabilities, compressing margins for distributors dependent on third-party sourcing.
Pricing Analysis
Value-based pricing tied to multi-year efficacy outcomes dominates the hormonal implant segment, with three-tier pricing structure across premium, standard, and economy levels separating ANVISA-certified imports from domestic reprocessors. Price differentiation rests on certification tier and clinical training bundling, with São Paulo state tenders showing acute sensitivity to unit cost while Rio de Janeiro private clinics absorb premium positioning for service-integrated offerings. Cost compression in copper IUD tenders is intensifying because of concentrated alloy sourcing, squeezing non-hormonal manufacturers most severely.
Supply Chain Analysis
Direct-to-clinic channels handle institutional demand from Brazil's Unified Health System, bypassing wholesale intermediaries to preserve margin on high-value implant products. Geographic supply concentration centers on Germany, the Netherlands, and Finland for hormonal implant APIs, with medical-grade silicone elastomers drawing from specialty polymer producers in the United States and Japan. Single-source vulnerability in copper alloy feedstock creates procurement risk for non-hormonal IUD manufacturers tendering into Minas Gerais and Rio Grande do Sul state health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's contraceptive devices market is becoming a vertical-integration race as manufacturers pursue backward control over medical-grade polymer supply to secure ANVISA certification advantages and pricing leverage in state tender processes.
For Market Incumbents: Anticipate margin compression from European manufacturers with pre-established ISO 13485 systems by accelerating captive silicone elastomer compounding investments in São Paulo industrial corridors. Defensive consolidation through clinical training academy acquisitions protects service-bundled positioning against commodity implant competitors, while state-level procurement database subscriptions enable tender timing precision that offsets volume fragmentation. For New Entrants and Emerging Players: The price-point gap between premium hormonal implants and economy copper IUDs offers white-space targeting for mid-tier biodegradable polymer entrants with simplified removal profiles. Minas Gerais pharmacy chains represent the most penetrable distribution channel for over-the-counter barrier method expansion, with municipal health secretariat partnership programs providing the essential go-to-market credential for Unified Health System inclusion. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to pharmaceutical-device conglomerates seeking Brazilian institutional contract capabilities. Long-term viability hinges on ANVISA registration velocity and state tender win rates rather than retail pharmacy shelf presence alone. The signal to watch is ANVISA's harmonization pace with MDR standards, which would elevate quality system investments from competitive advantage to market access prerequisite.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Acceleration | Compressed approval timelines for hormonal implants reshape competitive entry dynamics. |
| Clinical Training Academy Buildout | Insertion competency programs differentiate service offerings in Rio de Janeiro private clinics. |
| Backward Integration into Silicone Compounding | In-house polymer production secures supply continuity for ANVISA quality audits. |
| State Tender Database Subscription | Fiscal calendar visibility enables procurement window capture in São Paulo and Minas Gerais. |
| Biodegradable Polymer R&D Partnership | Elimination of removal procedures commands premium positioning in young adult segments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted among biomedical engineers, GPO contracts managers, hospital purchasing committee members, and ANVISA regulatory affairs specialists. Secondary sources included ANVISA registration databases, Ministry of Health incorporation guidelines, São Paulo state health secretariat tender records, and ISO medical device certification registries. Bottom-up demand modeling from clinic-level procurement volumes was triangulated against top-down manufacturer shipment data.
Reconciliation of shipment volumes, tender awards, and pharmacy distribution audit data enabled cross-validation across the projection horizon. Segmentation dimensions modeled encompassed product type, delivery mode, end-user channel, and regional state cluster. CAGRs were derived from fitted growth curves applied to base-year estimates, with ANVISA registration pipeline velocity and state budget allocation patterns serving as key forecast sensitivity inputs.
Inputs from ANVISA registration filings and state health secretariat procurement portals were available through the study window; gaps in private clinic pricing disclosure introduce uncertainty bands around margin estimates. Forecasts reflect assumptions regarding ANVISA streamlining continuity, copper alloy price stability, and religious institution opposition intensity in Northeast municipalities. Periodic stress-testing of base assumptions against municipal budget cycle shifts and regulatory harmonization announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Otoscope Market
Medical Devices
India Hemostats Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Midline Catheters Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Intradermal Injections Market
Medical Devices
Europe Incontinence Devices and Ostomy Market