
 Global Pacemakers Market | 2026-2036
Global Pacemakers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pacemakers Market Foresight
Hospital procurement committees is reorganizing evaluation criteria around total cost of ownership and remote monitoring integration. Medtronic leverages its end-to-end cardiac rhythm portfolio to anchor institutional contracts across integrated delivery networks. Abbott competes through leadless pacing miniaturization that reduces complication rates in frail patient cohorts. Boston Scientific differentiates via proprietary battery chemistry that extends device longevity beyond competitive benchmarks.
A pacemaker is an implantable pulse generator that delivers electrical stimuli to myocardial tissue through transvenous leads or wirelessly to an intracardiac capsule, typically operating at 2.5–3.6 volts with hermetic titanium enclosures and lithium-iodine power cells. Its commercial purpose centers on correcting pathological bradycardia and conduction disorders while enabling synchronous ventricular activation in heart failure. Dual chamber systems command premium positioning due to physiological pacing algorithms that preserve atrioventricular synchrony. Leadless technology represents the fastest-growing product category as elimination of transvenous leads reduces infection and lead-fracture liabilities. MRI-compatible technology has transitioned from premium niche to standard-of-care expectation across major reimbursement markets.
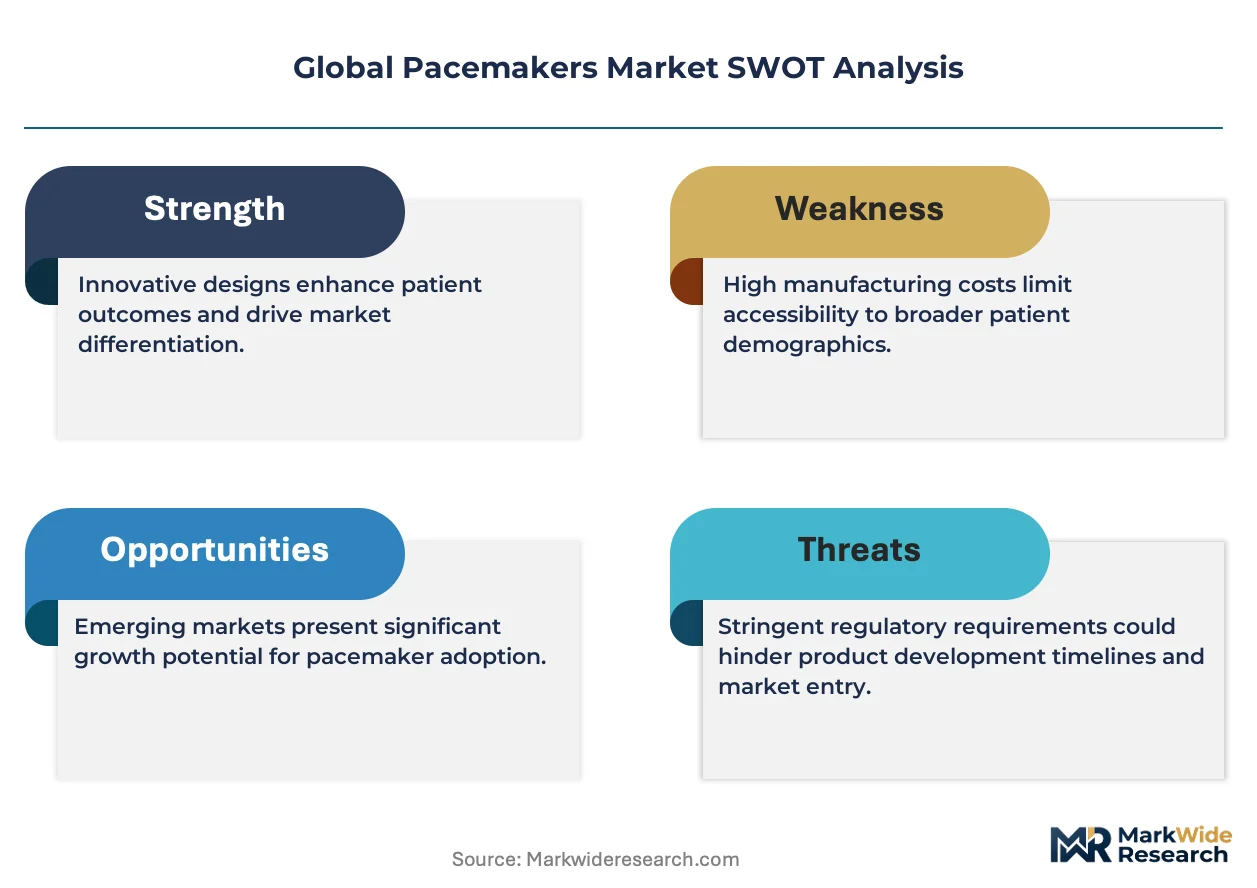
The FDA enforces premarket approval pathways with rigorous clinical evidence requirements for novel pacing modalities, while the EMA's Medical Device Regulation mandates enhanced post-market surveillance and unique device identification traceability. Japan's PMDA maintains stringent quality system inspections that constrain market entry timelines for non-domestic manufacturers. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC as connected cardiac devices expand attack surfaces and liability exposure.
Market Dynamics
Leadless pacing technology is fragmenting established cardiac rhythm management economics by eliminating transvenous lead costs while creating parallel reimbursement and training infrastructure demands.
Growth Catalysts
- Japan's PMDA streamlined review pathways:Accelerated approval timelines for MRI-compatible dual-chamber systems reduce market entry barriers for novel entrants targeting elderly populations.
- Integrated delivery network consolidation:Hospital systems in the United States negotiate enterprise-wide device contracts that bundle pacemakers with remote monitoring services.
- Lithium-iodine cell chemistry advances:Extended device longevity reduces replacement procedure frequency and total cost of ownership for Medicare reimbursement calculations.
Market Restraints
- Titanium enclosure supply concentration:Hermetic sealing capabilities concentrate among specialized metallurgical suppliers in Germany and Japan, creating single-source vulnerability.
- FDA premarket approval clinical evidence requirements:Novel wireless pacing modalities face 18-36 month evidence generation timelines that compress competitive windows.
- Cardiac resynchronization therapy substitution:CRT-D devices capture moderate bradycardia cases with concomitant heart failure, narrowing pure pacemaker addressable indications.
Strategic Opportunities
- India's underpenetrated electrophysiology infrastructure:Tier-2 and Tier-3 cities lack catheterization laboratory density, creating first-mover advantage for leadless systems requiring simpler implant logistics.
- Cybersecurity liability insurance products:Connected cardiac devices expose hospitals to ransomware attack surfaces; vendors bundling cyber coverage differentiate procurement evaluations.
- AI-enabled predictive arrhythmia algorithms:Convergence of machine learning with implantable diagnostics enables preemptive intervention workflows in integrated care networks.
Industry Challenges
- Electrophysiologist training pipeline constraints:Leadless implant techniques require distinct catheter skills; fellowship programs lack dedicated curriculum slots.
- Legacy EMR integration complexity:Remote monitoring data streams from proprietary platforms fail to populate electronic health record fields, forcing manual transcription workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pacemakers Market |
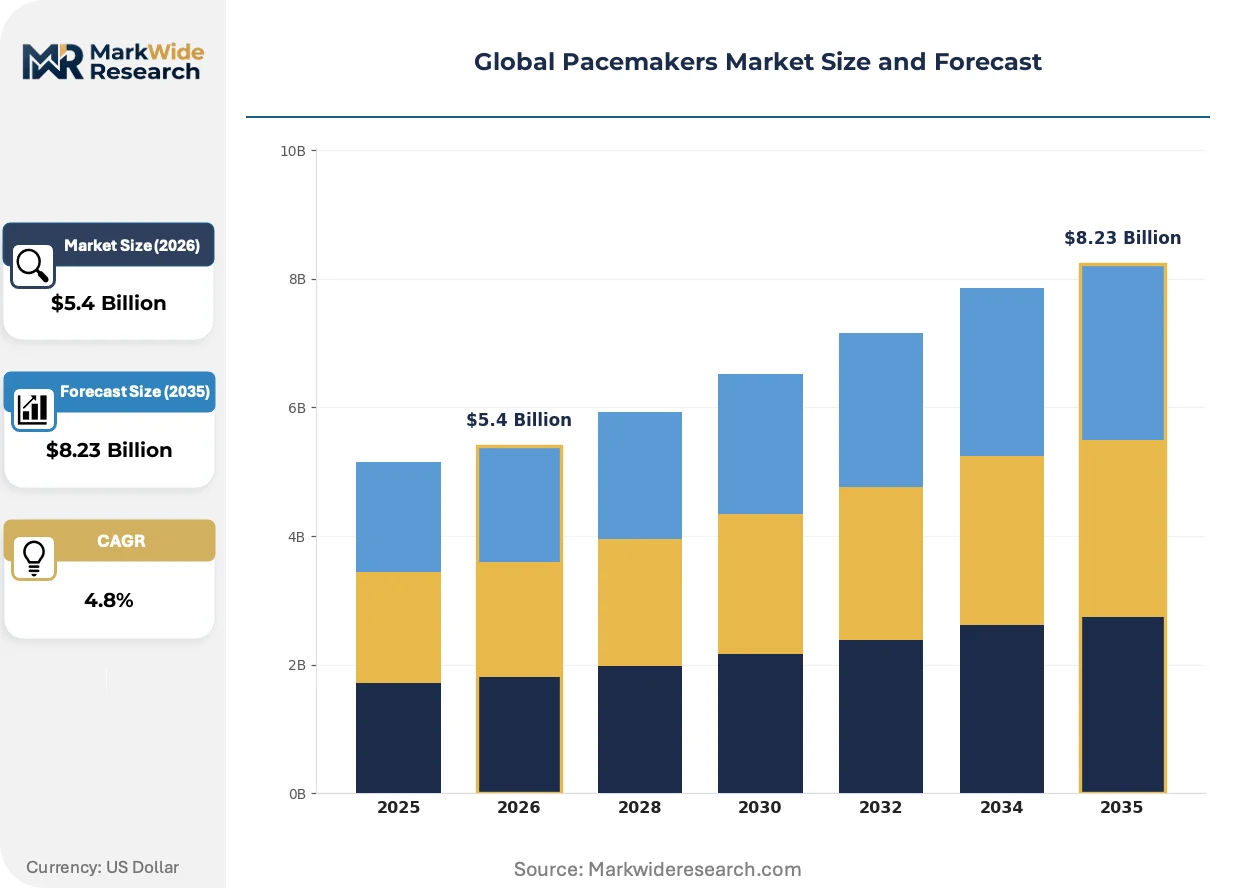
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Chamber, Dual Chamber, Biventricular, Leadless Technology: Rate Responsive, MRI Compatible, Wireless, Rechargeable Battery Application: Bradycardia, Heart Failure, Atrial Fibrillation, Tachycardia End User: Cardiology Clinics, Specialized Heart Centers, Ambulatory Surgical Centers, Research Institutes |
| Companies Covered | Medtronic, Abbott, Boston Scientific, BIOTRONIK, MicroPort Scientific Corporation, Lepu Medical Technology, OSYPKA Medical, MEDICO, Shree Pacetronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pacemakers Market Shifts & Advancements
Digital health integration and miniaturization are converging to redefine how cardiac pacing devices generate, transmit, and monetize physiological data across care continuums.
Leadless intracardiac capsules are fragmenting traditional pacemaker architecture by eliminating header-block and lead components entirely. Cardiology clinics in Germany and Japan are adopting these systems for frail patients with compromised vascular access. The technology is fragmenting service revenue models by shifting procedure economics toward implant simplicity and away from long-term lead management.
EMA's Medical Device Regulation mandates unique device identification traceability and enhanced post-market surveillance for all implantable active devices. Manufacturers must maintain quality management system documentation across entire product lifecycles. European hospital procurement committees now require MDR compliance certification as a gate criterion for tender participation.
Hospital buyers are unbundling device procurement from remote monitoring subscriptions. Integrated delivery networks in the United States negotiate hardware and service contracts separately to optimize total cost visibility. This pattern concentrates in Medicare Advantage populations where capitated reimbursement rewards care coordination infrastructure over episodic device placement.
Global Pacemakers Market Segmentation
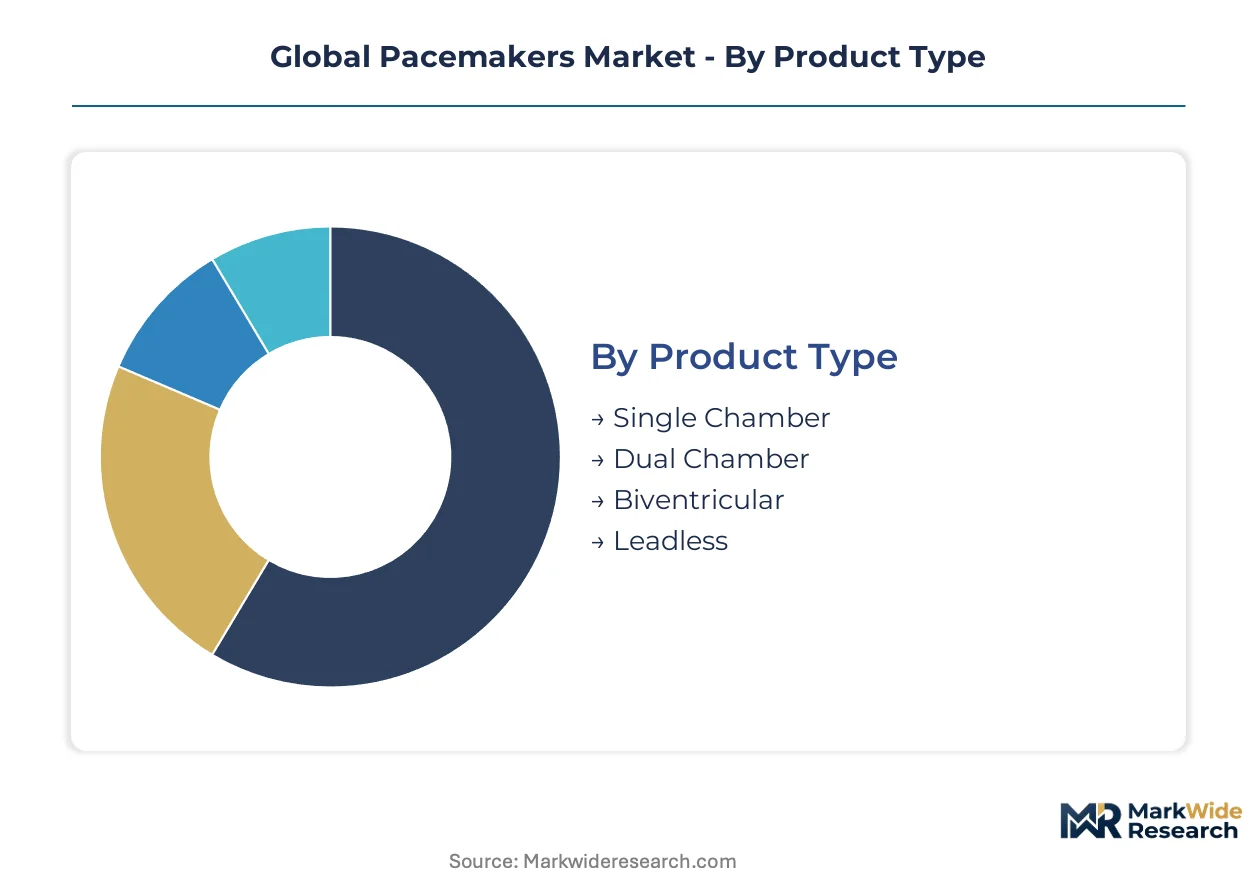
Pacemakers fragment into distinct technical and commercial categories that determine reimbursement pathways, implant site selection, and competitive positioning. Each segment carries unique substitution pressures from alternative cardiac rhythm therapies and diagnostic modalities.
Product Type:
CRT-D systems and subcutaneous ICDs exert substitution pressure most acutely on biventricular and single chamber segments, while leadless architectures disrupt traditional lead-dependent categories.
- Single Chamber:Ventricular-only pacing systems with simplified lead architecture and lower implant complexity. Demand concentrates in Japan's geriatric wards where cost-conscious public reimbursement favors basic pacing solutions for sedentary patients with isolated sinus node dysfunction.
- Dual Chamber:Atrioventricular synchronous systems preserve physiological activation sequences through separate atrial and ventricular leads. German cardiology clinics prioritize these systems for active elderly patients where chronotropic competence maintenance improves functional status scores.
- Biventricular:Cardiac resynchronization therapy pacemakers enabling coordinated septal-lateral activation in dilated cardiomyopathy.
- Leadless:Intracardiac capsule systems eliminating transvenous lead burden entirely.
Single chamber devices anchor the volume base while leadless systems gain share at the steepest rate.
Technology:
Cost tiering separates premium MRI-compatible and wireless platforms from standard rate-responsive systems, with rechargeable architectures creating a distinct longevity-focused tier.
- MRI Compatible:Shielded pulse generators and specialized leads permitting full-body magnetic resonance imaging without device deactivation. United States hospital procurement committees now mandate MRI compatibility as a baseline qualification for tender participation, driven by Medicare Advantage quality metrics.
- Wireless:Leadless and catheter-delivered systems communicating through radiofrequency or conductive coupling. Japanese academic medical centers drive adoption for patients with prior lead infections or vascular access limitations.
- Rate Responsive:Activity-sensing algorithms adjusting pacing rates to metabolic demand.
- Rechargeable Battery:Lithium-ion or alternative chemistry cells permitting transcutaneous energy replenishment.
Rate responsive systems anchor the volume base while wireless configurations expand most quickly.
Application:
Volume distribution tracks the epidemiological prevalence of underlying arrhythmia substrates, with heart failure applications facing the strongest encroachment from combined CRT-D devices.
- Bradycardia:Sinus node dysfunction and atrioventricular block indications representing the foundational pacemaker addressable population. United States ambulatory surgical centers concentrate implant volume for de novo AV block cases with preserved left ventricular function.
- Heart Failure:Conduction system pacing and resynchronization for reduced ejection fraction. Specialized heart centers in Germany favor biventricular systems over pure pacemakers when QRS duration exceeds 150 milliseconds.
- Atrial Fibrillation:Rhythm control and ventricular rate management in permanent AF.
- Tachycardia:Anti-tachycardia pacing and overdrive suppression applications.
Bradycardia applications anchor the volume base while heart failure pacing climbs the fastest amid expanding guideline indications.
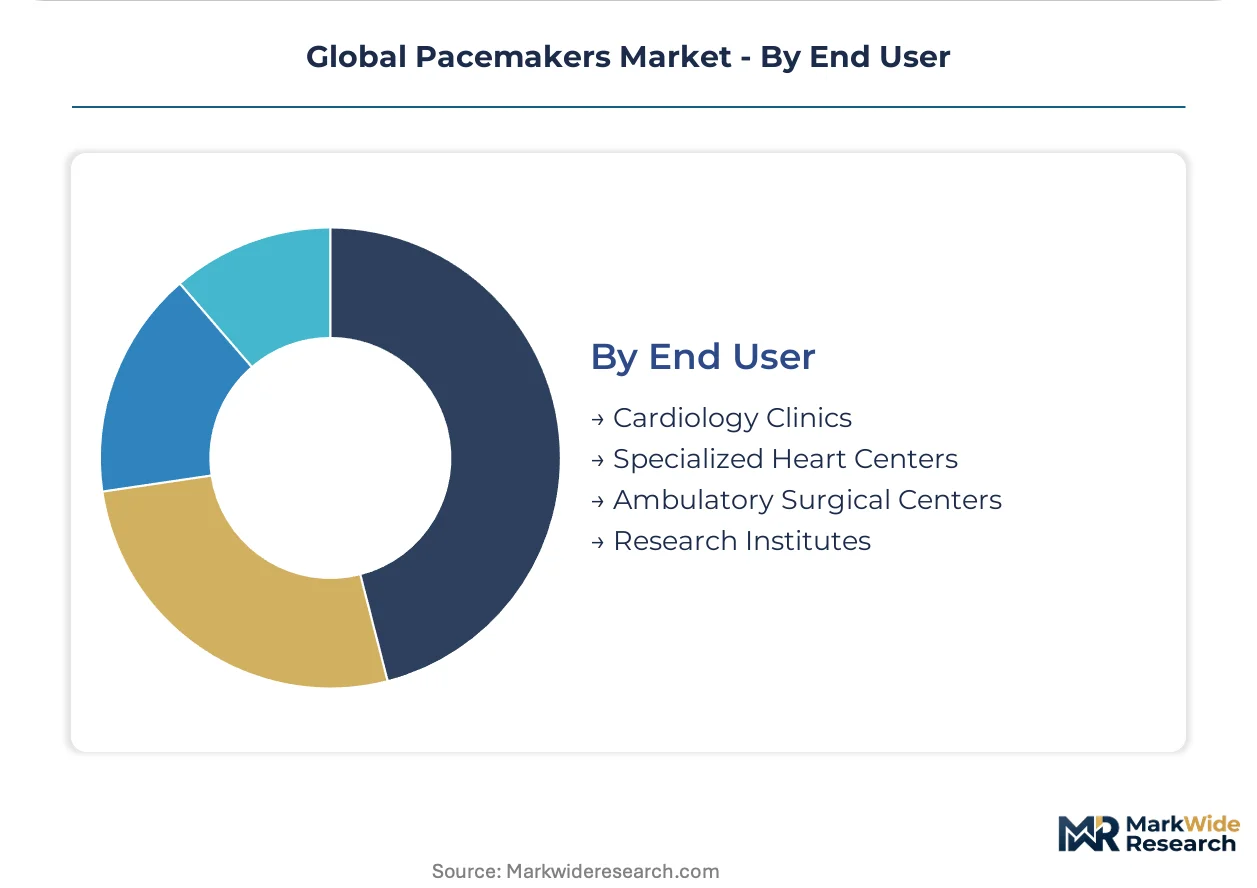
End User:
Site-of-care economics and procedural complexity determine customer segmentation, with ambulatory migration threatening traditional hospital-based implant volumes.
- Cardiology Clinics:Office-based electrophysiology practices performing straightforward single and dual chamber implants. Japan's clinic-based pacemaker programs expand through PMDA streamlined review pathways that reduce device approval delays.
- Specialized Heart Centers:Tertiary academic institutions managing complex lead extraction and upgrade procedures. United States integrated delivery networks consolidate high-acuity pacing cases within flagship cardiovascular institutes.
- Ambulatory Surgical Centers:Same-day discharge facilities capturing low-risk de novo implants.
- Research Institutes:Investigational device evaluation and first-in-human protocol execution.
Cardiology clinics anchor the volume base while ambulatory surgical centers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic's cardiac rhythm management infrastructure anchors North American procedural volume, while Japan's PMDA regulatory pathways and Germany's metallurgical supplier networks shape distinct competitive dynamics across three continents.
United States
Medicare Advantage capitation models accelerate ambulatory surgical center migration for de novo implants. The FDA's breakthrough device designation compresses MRI-compatible system approval timelines from 36 to 18 months. Integrated delivery networks in Texas and Florida consolidate procurement through enterprise-wide contracts bundling hardware with remote monitoring.
Germany
EMA Medical Device Regulation mandates unique device identification traceability for all active implantables entering European tenders. Baden-Württemberg's precision metallurgy clusters supply hermetic titanium enclosures to pulse generator manufacturers. Cardiology clinics in Munich and Heidelberg prioritize dual-chamber systems for active elderly cohorts.
Japan
PMDA streamlined review pathways reduce market entry barriers for MRI-compatible dual-chamber devices targeting geriatric populations. METI quality system inspections constrain non-domestic manufacturer timelines. Tokyo and Osaka academic medical centers drive leadless adoption for patients with prior lead infections.
India
Tier-2 and Tier-3 cities lack catheterization laboratory density, creating infrastructure gaps for traditional transvenous systems. CDSCO medical device regulations mandate enhanced post-market surveillance for imported active implantables. Maharashtra's Mumbai-Pune corridor concentrates private hospital investment in electrophysiology infrastructure.
Global Pacemakers Market Competitive Landscape
Concentration sits with diversified cardiac rhythm management conglomerates that leverage end-to-end portfolios to anchor institutional contracts. The vendor base stratifies across three tiers: full-spectrum rhythm management houses, leadless technology specialists, and regional battery chemistry innovators. Dominant competitive moves include backward integration into lithium-iodine cell production and strategic partnerships with integrated delivery networks for remote monitoring bundling.
Among North American rhythm management houses, Medtronic and Boston Scientific exemplify diversified portfolio archetypes, while Abbott occupies a distinct position through leadless miniaturization specialization. Medtronic's end-to-end cardiac rhythm coverage enables enterprise contract anchoring across United States hospital systems. Boston Scientific represents battery chemistry differentiation through proprietary longevity extensions. Abbott exemplifies the leadless technology vector that reduces complication liabilities in frail patient cohorts.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific |
| BIOTRONIK |
| MicroPort Scientific Corporation |
| Lepu Medical Technology |
| OSYPKA Medical |
| MEDICO |
| Shree Pacetronix |
| Others |
Supply & Pricing Matrix
Lithium-iodine cell chemistry displacing legacy silver-vanadium configurations simultaneously concentrates procurement leverage in Japanese and German metallurgical clusters while compressing margin structures for standard-tier pulse generators. This substitution dynamic reshapes supplier geography toward Baden-Württemberg precision sealing operations and reconfigures hospital procurement evaluations around total cost of ownership metrics that privilege extended device longevity.
Pricing Analysis
Volume-discount tiering separates MRI-compatible dual-chamber systems from basic single-chamber devices and economy-rate-responsive alternatives. Price differentiation rests on certification grade—FDA breakthrough designation versus standard PMA pathways—and after-sales remote monitoring bundling. Cost compression in the standard tier intensifies as integrated delivery networks consolidate procurement through enterprise-wide contracts. Medicare Advantage populations exhibit highest price sensitivity due to capitated reimbursement structures, while specialized heart centers prioritize longevity premiums over acquisition cost.
Supply Chain Analysis
Germany and Japan anchor hermetic titanium enclosure fabrication through specialized metallurgical suppliers in Baden-Württemberg and Osaka industrial corridors. Raw material dependencies center on high-purity titanium sponge, lithium-iodine cell chemistry, and biocompatible polymer header compounds. Single-source vulnerability concentrates in precision laser-welding equipment for hermetic sealing. Distribution runs through GPO-negotiated contracts with integrated delivery networks and direct hospital procurement committees in the United States, supplemented by tender-based purchasing across European hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac resynchronization therapy defibrillators threaten pure pacemaker addressable indications by capturing moderate bradycardia cases with concomitant heart failure, forcing incumbents to defend procedural volume through leadless miniaturization and remote monitoring integration.
For Market Incumbents: Fortify institutional contract anchoring across United States integrated delivery networks by bundling hardware with AI-enabled predictive arrhythmia diagnostics and cybersecurity liability coverage. Backward integration into lithium-iodine cell production reduces exposure to Japanese supplier concentration while extending device longevity beyond competitive benchmarks. Defend against CRT-D substitution by accelerating leadless system training curriculum deployment at electrophysiology fellowship programs. For New Entrants and Emerging Players: Anchor in India's Tier-2 and Tier-3 electrophysiology infrastructure gaps where catheterization laboratory scarcity favors leadless implant logistics over traditional transvenous systems. Target Maharashtra's Mumbai-Pune corridor private hospital investment wave with simplified procedure protocols that reduce training barriers. Pursue CDSCO regulatory pathway efficiency as a first-mover credential against established multinational procurement relationships. For Investors and Strategic Acquirers: The market sits at a substitution-defense phase that favors battery chemistry innovators and leadless technology specialists with proprietary miniaturization IP. Long-term viability over the projection horizon rests on convergence with AI-enabled diagnostics and cybersecurity-hardened connectivity platforms. Acquisition target archetype: mid-cap leadless technology developers with FDA breakthrough designation progress and established Japanese PMDA quality system documentation. Watch electrophysiologist fellowship curriculum expansion rates as inflection indicator for leadless adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pathway | Accelerated MRI-compatible dual-chamber approval timelines compress competitive windows for novel entrants. |
| Hospital System Partnership | Enterprise-wide contracts with United States integrated delivery networks bundle hardware with remote monitoring services. |
| Software Companion Development | AI-enabled predictive arrhythmia algorithms enable preemptive intervention workflows in Medicare Advantage populations. |
| CE Marking Pathway | EMA MDR compliance certification serves as gate criterion for European hospital tender participation. |
| Reimbursement Strategy | Medicare Advantage capitation models reward care coordination infrastructure over episodic device placement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA PMA filings, EMA MDR quality system documentation, Japanese PMDA approval databases, and CMS Medicare reimbursement schedules. Electrophysiologists, hospital purchasing committee chairs, biomedical engineers specializing in cardiac rhythm management, and GPO contracts managers provided qualitative input on procurement evaluation criteria and training pipeline constraints. Bottom-up device shipment triangulation against top-down healthcare expenditure analysis validates volume and value estimates.
Segmentation dimensions modeled span product type, technology tier, application indication, and end-user site-of-care across the projection horizon. CAGRs derive from procedural volume growth trajectories in aging demographics, reimbursement stability assessments, and substitution dynamics from CRT-D devices. Industry-specific forecast inputs incorporate PMDA streamlined review pathway adoption rates and leadless system training curriculum penetration at electrophysiology fellowship programs.
Material uncertainties—regulatory delays in novel wireless pacing modalities, titanium supply concentration disruptions, and cybersecurity liability framework evolution—sit outside the modeled envelope. Forecasts reflect assumptions on reimbursement stability and training infrastructure scaling without guarantee of realization. Recalibration cycles align with material shifts in FDA breakthrough designation velocity and integrated delivery network consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Syringe Filling Machine Market
Medical Devices
Venturi Mask Market
Medical Devices
Pelvic Muscle Probes Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Middle East and Africa Orthotic Devices Market
Medical Devices
Spinal Implant Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Polysomnography Devices Market
Medical Devices
Organ Preservation & Perfusion Products Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Brazil Contraceptive Devices Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Adult Water Flosser Market