
 Global Semiconductor in Healthcare Market | 2026-2036
Global Semiconductor in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Global Semiconductor in Healthcare Market Outlook
Modular sensor-to-processor bundling is restructuring procurement decisions across diagnostic OEMs. Texas Instruments Incorporated leverages its analog portfolio to anchor multi-parameter patient monitoring designs. Analog Devices, Inc. differentiates through high-precision signal chains in MRI and CT modalities. Infineon Technologies AG specializes in power management ICs that sustain reliability under clinical load cycles.
Semiconductor in Healthcare denotes integrated circuits, discrete devices, and sensor assemblies fabricated on silicon, gallium arsenide, or silicon carbide substrates with feature nodes ranging from mature 180nm for implantable longevity to advanced 7nm for computational imaging. These components enable signal acquisition, processing, storage, and wireless transmission within regulated medical devices. Sensors and mixed-signal ICs capture the dominant margin pools as clinicians demand higher-fidelity biometric streams with lower power draw. ASICs for wearable cardiac monitors represent the fastest-expanding product class as ambulatory care models displace episodic hospital visits.
The FDA enforces 21 CFR Part 820 quality system regulations for device manufacturers while the EU Medical Device Regulation mandates clinical evidence for active implantable electronics. Japan's PMDA operates a parallel review track with METI to accelerate innovative semiconductor-based therapeutics. Stakeholders must monitor divergence between FDA digital health guidance and EUDAMED database requirements as dual-market certification costs reshape supplier economics.
Market Dynamics
AI-enabled diagnostic platforms are compressing replacement cycles for legacy medical imaging equipment while forcing semiconductor suppliers to validate mixed-signal architectures under FDA 21 CFR Part 820 and EU MDR simultaneously.
Growth Catalysts
- EU Medical Device Regulation:The MDR's clinical evidence requirements for active implantables are accelerating demand for traceable semiconductor supply chains in Germany and France.
- Silicon carbide power management:SiC substrates enable higher thermal tolerance in MRI gradient amplifiers, extending operational life under continuous clinical load cycles.
- Ambulatory care expansion:Wearable cardiac monitors in Japan's aging population are pulling ASIC volumes for multi-day biometric streaming.
Market Restraints
- 180nm foundry concentration:Mature node capacity for implantable longevity chips concentrates in Taiwan, creating geographic supply vulnerability.
- Dual certification costs:Divergence between FDA digital health guidance and EUDAMED database requirements adds 18-24 months to product launch timelines.
- Gallium arsenide price volatility:GaAs substrate costs for RF components in wireless implants fluctuate with defense electronics demand cycles.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for electronics manufacturing are attracting diagnostic OEM assembly operations to Karnataka and Tamil Nadu.
- Sensor-processor convergence:Edge AI inference at the sensor node reduces cloud dependency for real-time patient monitoring in rural networks.
- Home-based dialysis:Portable renal care devices open new power management IC demand outside hospital infrastructure.
Industry Challenges
- Mixed-signal design talent scarcity:Analog-digital integration expertise for low-noise patient monitoring circuits concentrates among experienced design houses in Boston and Munich.
- ISO 13485 certification backlog:Notified body capacity constraints in Europe delay quality management system approvals for new semiconductor entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Semiconductor in Healthcare Market |
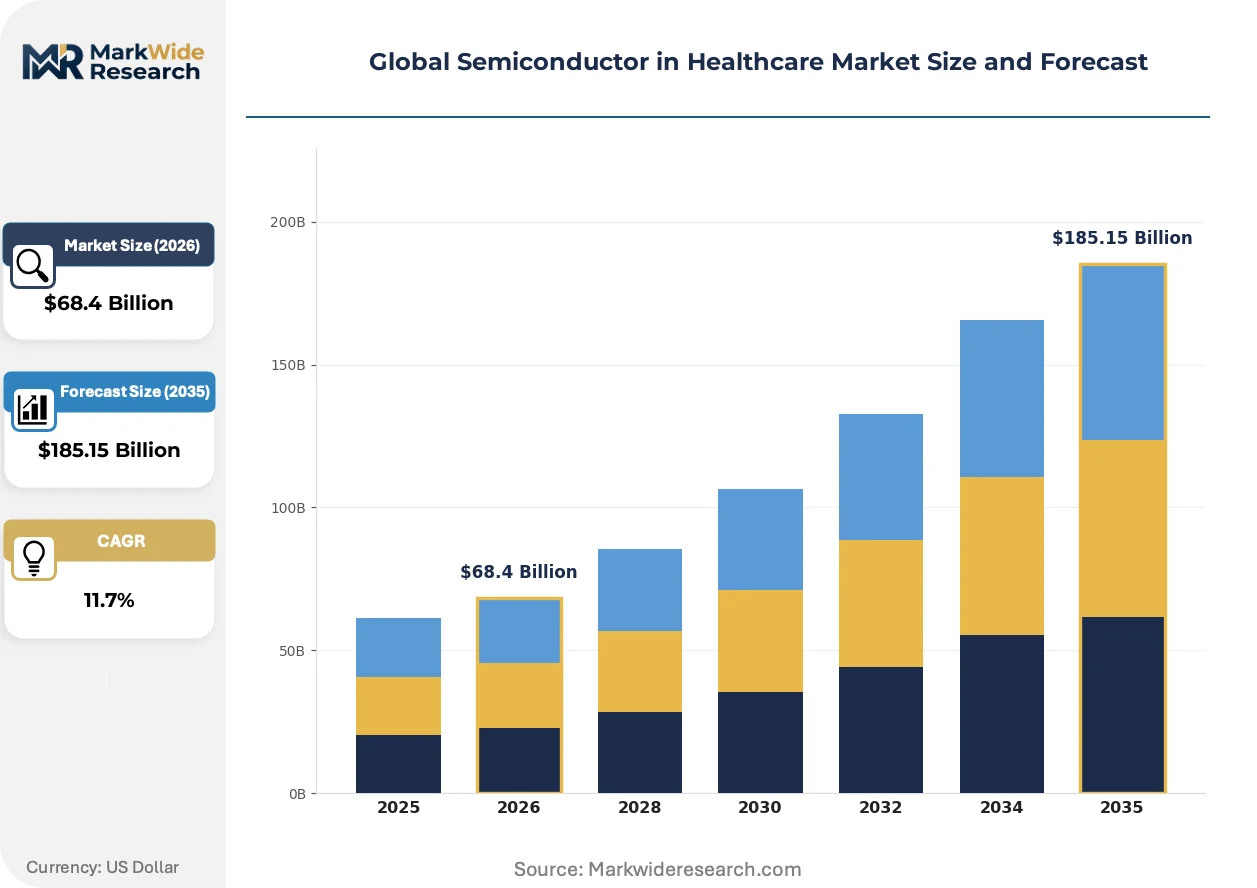
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Sensors, ASICs, FPGAs Application: Medical Imaging, Wearable Devices, Patient Monitoring, Surgical Instruments Technology: Analog, Digital, Mixed-Signal, RF End User: Hospitals, Clinics, Research Labs, Telemedicine Providers |
| Companies Covered | Texas Instruments Incorporated, Analog Devices, Inc., STMicroelectronics N.V., NXP Semiconductors N.V., Infineon Technologies AG, Intel Corporation, onsemi, Broadcom Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Semiconductor in Healthcare Market Strategic Shifts
Computational migration toward edge architectures is redistributing processing load across diagnostic devices, wearables, and hospital networks while compressing latency requirements for real-time clinical decision support.
Edge AI inference engines are decentralizing diagnostic intelligence from centralized PACS servers into portable ultrasound and X-ray systems. Emergency departments in US academic medical centers are deploying these point-of-care platforms to bypass radiology workflow bottlenecks. This shift is decentralizing capital allocation from million-dollar imaging suites toward sub-hundred-thousand-dollar connected devices.
Japan's PMDA parallel review track with METI is compressing approval timelines for semiconductor-based therapeutics by enabling concurrent safety and efficacy evaluation. Domestic manufacturers gain six-to-nine month advantages over foreign competitors navigating sequential submissions. Implantable neuromodulation devices with custom ASICs are the primary beneficiaries of this regulatory streamlining.
Hospital procurement departments are unbundling sensor assemblies from complete system purchases to enable multi-vendor interoperability. German university hospitals are leading this specification shift through framework agreements that mandate open communication protocols. This behavior is fragmenting supplier relationships previously locked into single-source imaging OEM contracts.
Global Semiconductor in Healthcare Market Segmentation
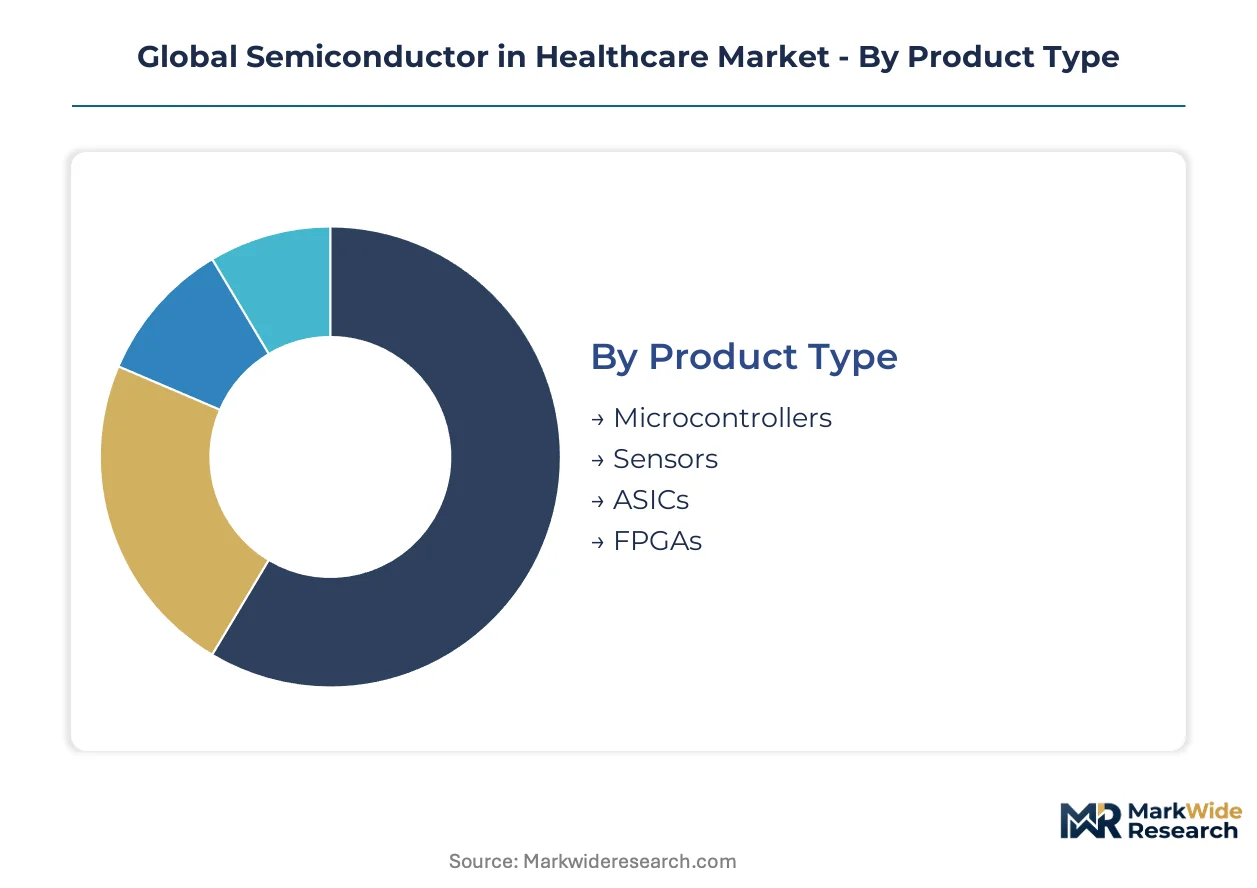
Semiconductor procurement in healthcare diverges sharply by clinical workflow requirements, with imaging systems demanding high-throughput digital architectures while implantables prioritize ultra-low-power analog designs. Supply chains for each segment concentrate among distinct foundry ecosystems, creating divergent vulnerability profiles.
Product Type:
Supply concentration for mature-node healthcare chips clusters among Taiwan-based foundries, while advanced-node AI accelerators depend on leading-edge facilities in South Korea and the United States.
- Sensors:Photodiode arrays and MEMS biopotential electrodes capture physiological signals with microvolt precision. Demand concentrates in Germany's university hospital networks for multi-parameter patient monitoring suites, driven by EU MDR traceability mandates for active implantables.
- ASICs:Custom silicon integrates signal conditioning, processing, and wireless transmission into single-die solutions for implantable neuromodulation. Japanese manufacturers leverage PMDA-METI parallel review tracks to compress clearance timelines for cardiac rhythm management devices.
- Microcontrollers:ARM Cortex-M based units with medical-grade IEC 62304 firmware stacks dominate infusion pump motor control and ventilator sequencing.
- FPGAs:Reconfigurable logic enables algorithm updates in ultrasound beamformers and CT reconstruction pipelines without hardware redesign.
Today's leader: Sensors. Tomorrow's challenger: ASICs.
Application:
Cost tier stratification separates million-dollar imaging capital equipment from sub-hundred-dollar wearable consumables, with entirely different procurement cycles and margin structures.
- Medical Imaging:MRI gradient amplifiers and CT detector arrays require radiation-hardened mixed-signal ICs with 16-bit resolution at megasample rates. Siemens Healthineers and Canon Medical Systems in Japan drive specification roadmaps for next-generation photon-counting CT.
- Wearable Devices:Ambulatory cardiac monitors demand sub-milliwatt ASICs for multi-day biometric streaming. Japan's aging population and reimbursement expansion for remote patient monitoring accelerate volumes for patch-based ECG systems.
- Patient Monitoring:Bedside multi-parameter systems integrate Texas Instruments analog front-ends with NXP microcontrollers for real-time alarm generation in US academic medical centers.
- Surgical Instruments:RF ablation generators and electrosurgical units rely on silicon carbide power transistors for thermal tolerance under continuous clinical load.
Medical imaging commands the highest silicon content per system. Wearable devices are expanding most quickly.
Technology:
Volume distribution across technology nodes reflects the tension between computational intensity and power constraints, with mature geometries dominating implantables and finFET processes capturing AI inference workloads.
- Mixed-Signal:Precision data converters bridge analog sensor outputs to digital processing pipelines in MRI and ultrasound systems. Analog Devices and Texas Instruments anchor this segment through proprietary isolation architectures.
- Analog:Low-noise amplifiers and voltage references establish signal fidelity floors for EEG and ECG acquisition front-ends in German diagnostic OEM designs.
- Digital:CMOS logic at 7nm-28nm nodes powers AI-enabled image reconstruction and real-time pathology screening.
- RF:Sub-6GHz and mmWave transceivers enable wireless capsule endoscopy and implantable glucose monitoring with smartphone connectivity.
Mixed-signal integration defines current competitive differentiation. Digital AI acceleration shows the steepest expansion trajectory.
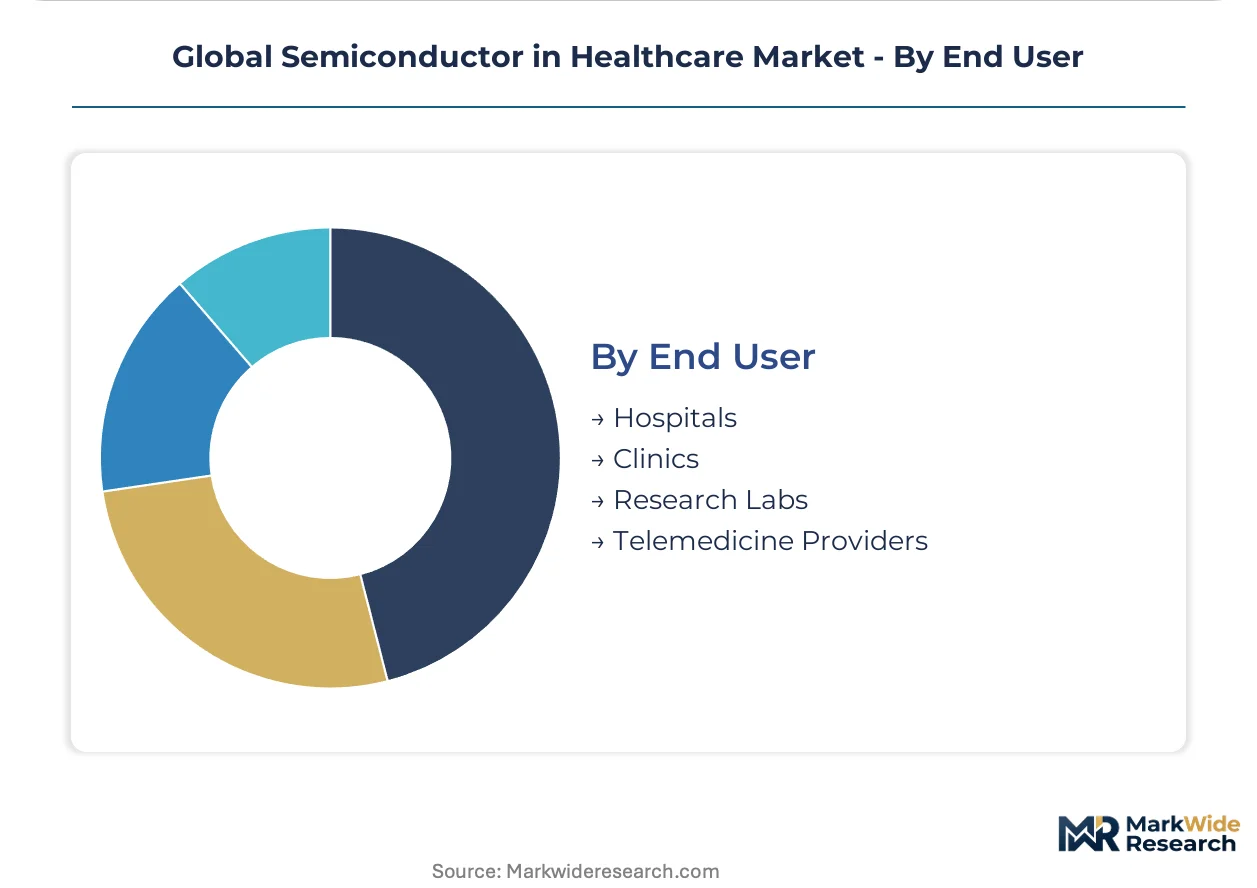
End User:
Customer type determines validation burden and procurement authority, with hospital IDNs negotiating enterprise contracts while telemedicine providers prioritize plug-and-play interoperability.
- Hospitals:Integrated delivery networks in the United States consolidate semiconductor procurement across radiology, cardiology, and surgical service lines, demanding 10-year supply guarantees for capital equipment.
- Telemedicine Providers:Cloud-connected diagnostic peripherals require edge AI inference with minimal IT infrastructure, driving demand for sensor-processor convergence in rural Indian health networks under the PLI scheme.
- Clinics:Outpatient imaging centers prioritize cost-optimized CT and X-ray refurbishment with semiconductor retrofit kits.
- Research Labs:Preclinical device development consumes FPGA-based prototyping platforms and custom ASIC shuttle runs for FDA pre-submission validation.
Hospitals anchor current procurement volume. Telemedicine providers represent the fastest-climbing customer category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor-enabled medical devices trace their commercial origins to post-war instrumentation clusters in the United States and Germany, where defense electronics expertise migrated into clinical monitoring equipment during the 1960s.
United States
Integrated delivery networks in Texas and Massachusetts drive procurement of AI-enabled imaging systems and wearable cardiac monitors. FDA premarket notification pathways for software-as-a-medical-device compress clearance timelines for semiconductor-dependent diagnostics. The Greater Boston corridor anchors mixed-signal design talent for low-noise patient monitoring circuits.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia specify multi-parameter patient monitoring suites with EU MDR traceability mandates. The Medical Device Regulation's clinical evidence requirements for active implantables accelerate demand for auditable semiconductor supply chains. Siemens Healthineers in Erlangen drives specification roadmaps for photon-counting CT detector arrays.
Japan
Ambulatory care expansion for the aging population pulls ASIC volumes for multi-day biometric streaming in patch-based ECG systems. PMDA parallel review tracks with METI compress approval timelines for implantable neuromodulation devices by six-to-nine months. Canon Medical Systems in Tokyo anchors domestic imaging equipment production.
Taiwan
Mature-node foundry capacity for 180nm implantable longevity chips concentrates in Hsinchu Science Park, creating geographic supply vulnerability for cardiac rhythm management devices. The concentration reflects decades of precision manufacturing investment in biomedical microelectronics. Domestic packaging houses specialize in hermetic sealing for long-term implantable applications.
India
Production-linked incentives for electronics manufacturing attract diagnostic OEM assembly operations to Karnataka and Tamil Nadu under the PLI scheme. CDSCO regulatory harmonization with IMDRF standards accelerates market entry for semiconductor-based therapeutics. Bangalore's medical device cluster expands contract manufacturing for wearable glucose monitoring systems.
Global Semiconductor in Healthcare Market Competitive Environment
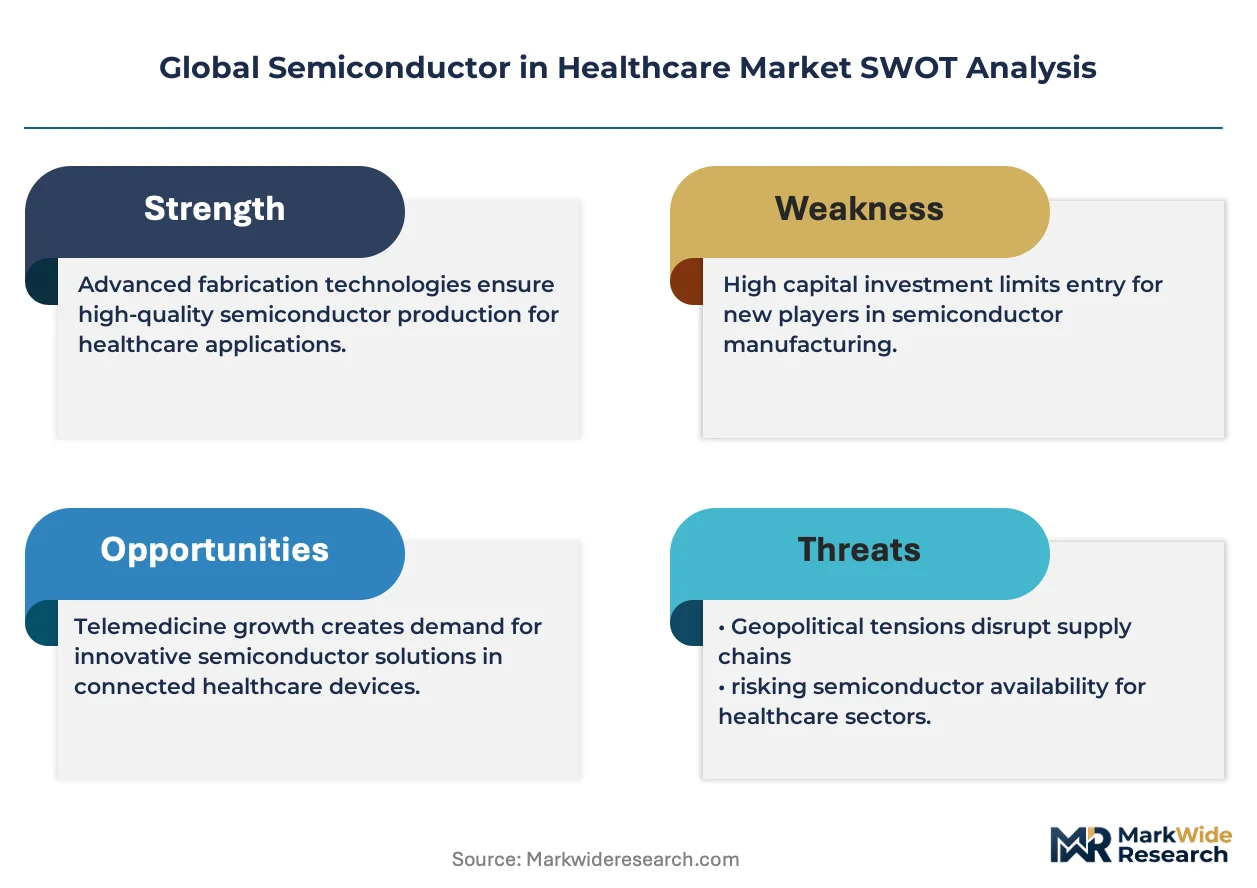
Premium-margin players sit above commodity-margin players across analog precision and mixed-signal integration capabilities. The vendor base stratifies between diversified semiconductor conglomerates with medical-grade quality systems and specialized suppliers focused on implantable power management. Three archetypes dominate: analog-front-end specialists, custom ASIC design houses, and power semiconductor fabricators. Competitive moves center on sensor-processor convergence architectures and backward integration into foundry capacity.
Among diversified analog specialists, Texas Instruments Incorporated and Analog Devices, Inc. occupy positions anchoring multi-parameter patient monitoring and high-precision signal chain supply respectively. Infineon Technologies AG exemplifies the power management tier specializing in silicon carbide reliability under clinical load cycles.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Analog Devices, Inc. |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| Intel Corporation |
| onsemi |
| Broadcom Inc. |
| Renesas Electronics Corporation |
| Others |
Value Chain & Pricing Dynamics
Gallium arsenide substrate price indices cascade through RF component supply chains into three-tier pricing stratification across premium FDA-cleared implants, standard CE-marked devices, and economy-grade refurbishment markets. Taiwan foundry concentration for mature-node silicon amplifies margin compression at the economy tier while premium analog-front-end suppliers defend position through ISO 13485 certification premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hermetically sealed implantable ASICs from industrial-grade patient monitoring chips and refurbished diagnostic retrofit kits. Price differentiation hinges on FDA premarket notification tier and volume scale, with economy-tier sensors facing cost compression from India's PLI scheme assembly migration. Hospital IDNs in the United States exhibit lowest price sensitivity due to 10-year supply guarantees, while telemedicine providers in rural Indian networks prioritize lowest unit cost.
Supply Chain Analysis
Reverse logistics for explanted cardiac devices and end-of-life imaging equipment feeds precious metal recovery and component refurbishment streams back into secondary markets. Geographic supply concentration centers on Taiwan for 180nm implantable longevity chips, South Korea for advanced-node AI accelerators, and Germany for precision analog design. Raw material dependencies encompass silicon carbide substrates for MRI gradient amplifiers, gallium arsenide wafers for wireless implant RF chains, and specialized epoxy resins for hermetic packaging. Single-source vulnerability in Taiwan mature-node capacity threatens cardiac rhythm management device supply. Distribution runs through hospital GPO contracts, diagnostic OEM direct procurement, and emerging telemedicine platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor in healthcare market functions as a regulatory compounder where EU MDR clinical evidence mandates for active implantables continuously expand addressable silicon content per device.
For Market Incumbents: To counter emerging fabless ASIC design houses in Japan and Germany, Texas Instruments and Analog Devices should deepen backward integration into 180nm foundry partnerships in Taiwan and accelerate ISO 13485 certification for next-generation sensor-processor convergence architectures. Capacity addition in South Korea for 7nm AI inference engines preserves leadership in computational imaging. For New Entrants and Emerging Players: The mid-tier price-point gap between premium FDA-cleared neuromodulation ASICs and economy-grade refurbished monitoring chips offers entry space for standard-tier suppliers targeting India's PLI scheme manufacturing clusters. The most penetrable segment comprises telemedicine-connected wearable glucose monitors for Bangalore's contract manufacturing ecosystem. Go-to-market leverage rests on CDSCO-IMDRF harmonization pathways accelerating regulatory clearance. For Investors and Strategic Acquirers: Asymmetric upside sits with mixed-signal design houses possessing both FDA 510(k) clearance experience and EU MDR technical documentation capabilities. Long-term viability favors specialists with captive analog-front-end IP and hospital IDN framework agreement relationships. The signal to watch is PMDA-METI parallel review track expansion to foreign manufacturers as approval timeline arbitrage opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access for active implantable ASICs in German university hospital networks. |
| FDA Software-as-a-Medical-Device Pathway | Compresses clearance timelines for AI-enabled diagnostic platforms in US academic medical centers. |
| Taiwan Foundry Partnership Expansion | Secures 180nm capacity for cardiac rhythm management device longevity requirements. |
| Sensor-Processor Convergence R&D | Reduces cloud dependency for edge AI inference in rural Indian telemedicine deployments. |
| Hospital GPO Framework Agreement | Locks in 10-year supply guarantees for multi-parameter patient monitoring system upgrades. |
Study Parameters
Direct dialogue with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and diagnostic OEM procurement directors grounded qualitative findings, cross-referenced against FDA 510(k) filings, EUDAMED device registrations, CMS Medicare reimbursement databases, and Taiwan Semiconductor Industry Association production statistics. Secondary validation drew from SEC 10-K disclosures of diversified semiconductor suppliers and PMDA approval summaries. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across product type, application, and end-user segments.
Bottom-up modeling of ASIC, sensor, microcontroller, and FPGA volumes across medical imaging, wearable devices, patient monitoring, and surgical instrument applications integrated with top-down semiconductor content per system estimates for MRI, CT, ultrasound, and cardiac monitor equipment. CAGRs derived from regression analysis of historical FDA clearance trajectories, EU MDR implementation pace, and Japan's ambulatory care reimbursement expansion. Industry-specific forecast inputs encompassed foundry capacity utilization rates for mature nodes and AI inference workload migration patterns toward edge architectures.
Caveats apply where Taiwan foundry concentration risk, gallium arsenide price volatility, or divergence between FDA digital health guidance and EUDAMED database requirements could materially shift the outlook. Practitioners should monitor PMDA foreign manufacturer parallel review track expansion, India's PLI scheme capacity buildout, and ISO 13485 notified body backlog resolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vaginal Pessary Market
Medical Devices
IV Equipment Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
US Medical Device Manufacturers Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Capsulotomy Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Prostate Biopsy Devices Market
Medical Devices
Nasal Atomizer Devices Market
Medical Devices
North America Ultrasound Probe Disinfection Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Portable OT Light Market