
 Europe Composite Process Material Kits Market | 2026-2036
Europe Composite Process Material Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Composite Process Material Kits Market Insights
Aerospace procurement is restructuring European composite kit demand as defense and commercial programs scale simultaneously. Airtech Advanced Materials Group leverages its vacuum bagging film portfolio to anchor supply relationships with Airbus tier-one suppliers across Toulouse and Hamburg. Solvay competes through specialty resin formulations certified for pressurized cabin structures. Velocity Composites plc specializes in just-in-time kitting services that reduce material waste for UK-based rotorcraft manufacturers.
Composite process material kits bundle consumables—vacuum bag films, release fabrics, peel plies, sealant tapes, and resin flow media—engineered to precise thickness, temperature, and permeability specifications for autoclave and out-of-autoclave curing cycles. These kits streamline layup operations, minimize contamination risk, and synchronize material consumption with production schedules in high-value manufacturing environments. Fiber kits dominate value capture due to carbon fiber prepreg handling requirements in aerospace programs, while adhesive kits represent the fastest-expanding category as bonded joints replace mechanical fasteners in lightweight automotive structures. Core material kits occupy stable margin pools in marine hull production where balsa and foam core demand ties to superyacht build cycles in Italy and the Netherlands.
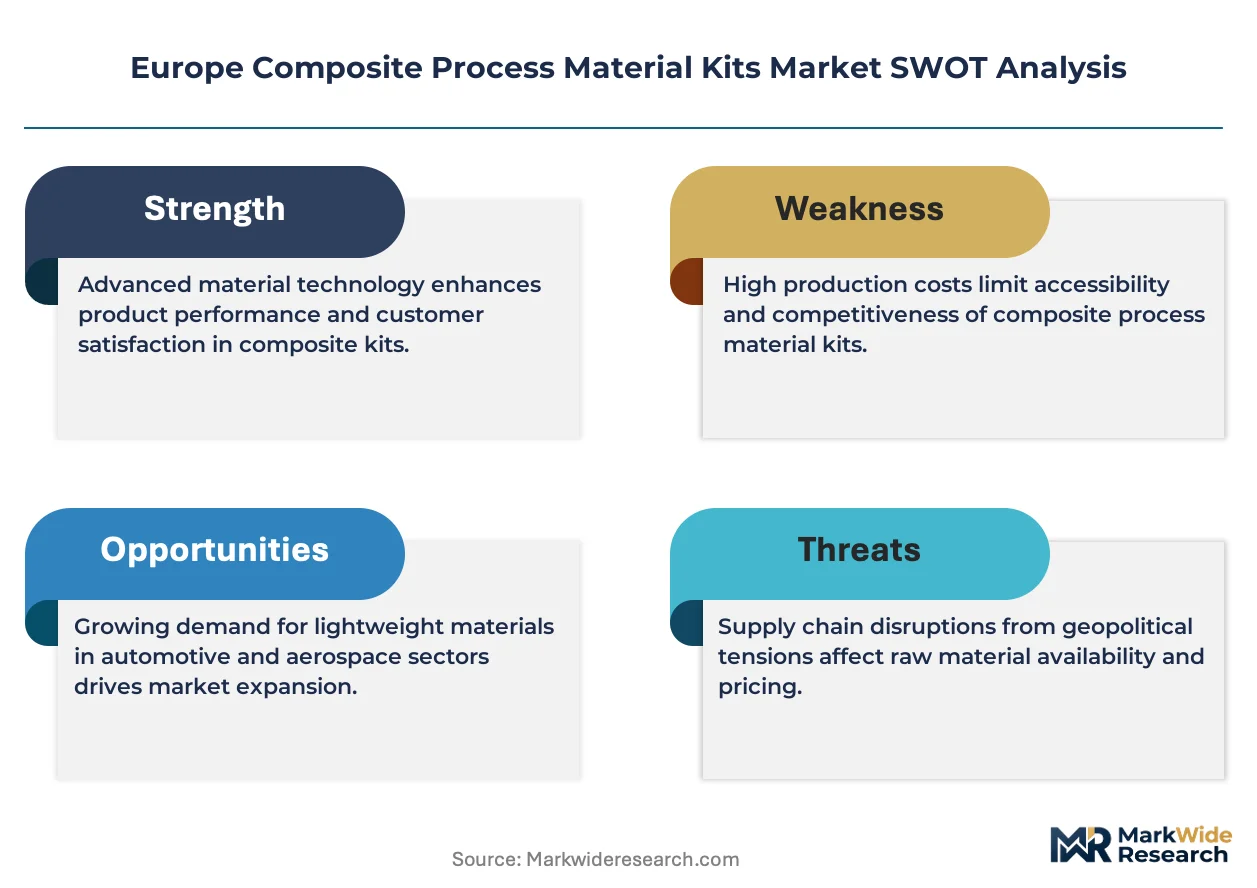
EMA oversees chemical safety assessments for resin components under REACH registration requirements, while the EU Green Deal pushes manufacturers toward lower-VOC adhesive formulations and recyclable process materials. CE marking mandates under the Construction Products Regulation extend to composite materials used in infrastructure applications, creating compliance thresholds for kit suppliers entering bridge and wind tower segments. Stakeholders must monitor evolving ECHA substance restriction proposals for bisphenol derivatives and assess qualification timelines for bio-based epoxy alternatives before specification lock-in at major OEMs.
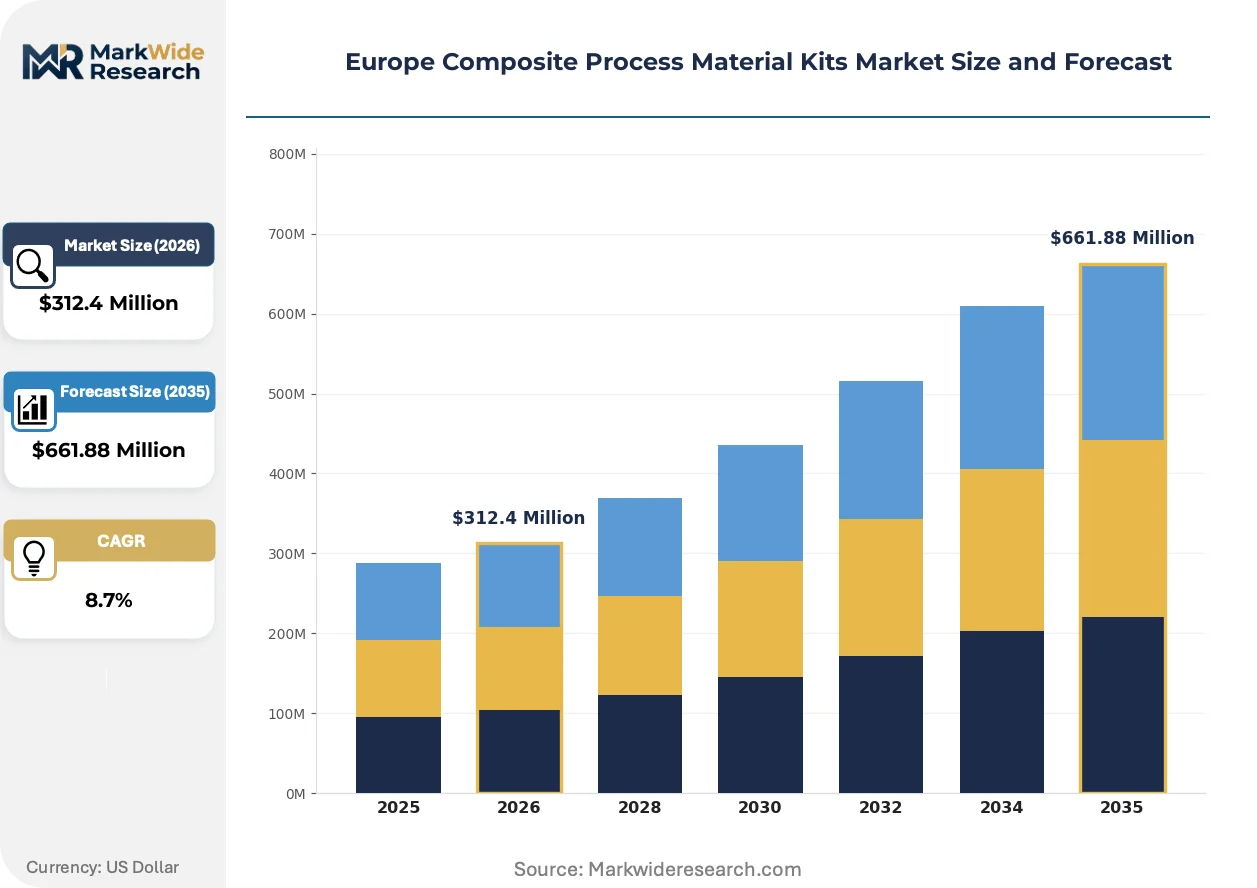
Market Dynamics
Aerospace OEM consolidation in Germany and France is compressing supplier qualification timelines while REACH substance restrictions force rapid resin formulation pivots across European kit manufacturers.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding emissions targets for aviation push Airbus and Safran toward lighter bonded structures, expanding kit demand for adhesive-intensive assembly processes.
- Out-of-autoclave curing expansion:Lower-energy manufacturing methods gain specification in wing production programs, requiring tailored vacuum bagging film and flow media configurations.
- Bavaria aerospace corridor concentration:Airbus Defence and Space operations in Manching anchor regional kit procurement volumes for military transport programs.
Market Restraints
- Petrochemical input volatility:Epoxy resin and polyamide film costs fluctuate with naphtha cracking margins, compressing kit assembler margins on fixed-price contracts.
- Carbon fiber supply concentration:Toray, SGL Carbon, and Hexcel control tow supply into European prepreg channels, creating bottleneck risk for kit synchronization.
- REACH registration cost barriers:ECHA data requirements for novel bio-based hardeners impose six-figure compliance burdens excluding smaller compounders from specification.
Strategic Opportunities
- Poland emerging aerospace manufacturing:Lockheed Martin F-16 sustainment and potential future assembly programs create greenfield kit supply relationships outside established German-French networks.
- CSRD supply chain disclosure requirements:Mandatory Scope 3 emissions reporting drives OEMs toward kit suppliers with certified carbon accounting and recyclable process material streams.
- Digital twin integration:Real-time material consumption tracking via RFID-enabled kitting systems enables predictive replenishment and waste reduction for high-mix rotorcraft production.
Industry Challenges
- Composite technician certification gaps:EASA Part 145 repair station standards for bonded structure maintenance outpace vocational training program output in the UK and Italy.
- Multi-tier qualification latency:Airbus A350 and A400M program changes propagate slowly through three-tier supply chains, causing kit obsolescence and inventory write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Composite Process Material Kits Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin Kits, Fiber Kits, Core Material Kits, Adhesive Kits End User: Aerospace, Automotive, Marine, Construction Application: Manufacturing, Repair, Coating, Parts Fabrication Distribution Channel: Online Sales, Direct Sales, Distributors, Retail |
| Companies Covered | Airtech Advanced Materials Group, Aerovac Composites One, Diatex SAS, Velocity Composites plc, GEFiM, InCom Group, Metyx Composites, Pro-Vac Vacuum Consumables, Solvay, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Composite Process Material Kits Market Trends and Innovations
European kit suppliers are racing to integrate sustainable material streams with digital traceability systems as OEM sustainability audits intensify and curing technologies diversify beyond traditional autoclave methods.
Recyclable thermoplastic vacuum bagging films are consolidating process material categories previously split between single-use nylon and reusable silicone options. Airbus Hamburg and Broughton facilities pilot closed-loop film recovery systems that reduce consumable mass per wing set. This consolidation is compressing supplier portfolios toward integrated film-and-tape providers with recycling partnerships.
REACH restriction proposals targeting bisphenol A derivatives in epoxy hardeners are forcing reformulation investments across German and French resin compounders. ECHA's 2023-2024 substance evaluation timeline creates specification uncertainty for cabin interior kits requiring fire-smoke-toxicity certification. Suppliers with pre-qualified bio-epoxy alternatives capture early mover advantage in A320neo family programs.
Just-in-time kitting services are displacing bulk material procurement for UK rotorcraft and satellite manufacturers. Velocity Composites and Airtech Europe operate regional cutting centers that deliver sequenced layup sets matched to production takt times. This model concentrates most visibly in Broughton and Yeovil where BAE Systems and Leonardo Helicopters operate lean assembly lines.
Europe Composite Process Material Kits Market Segmentation
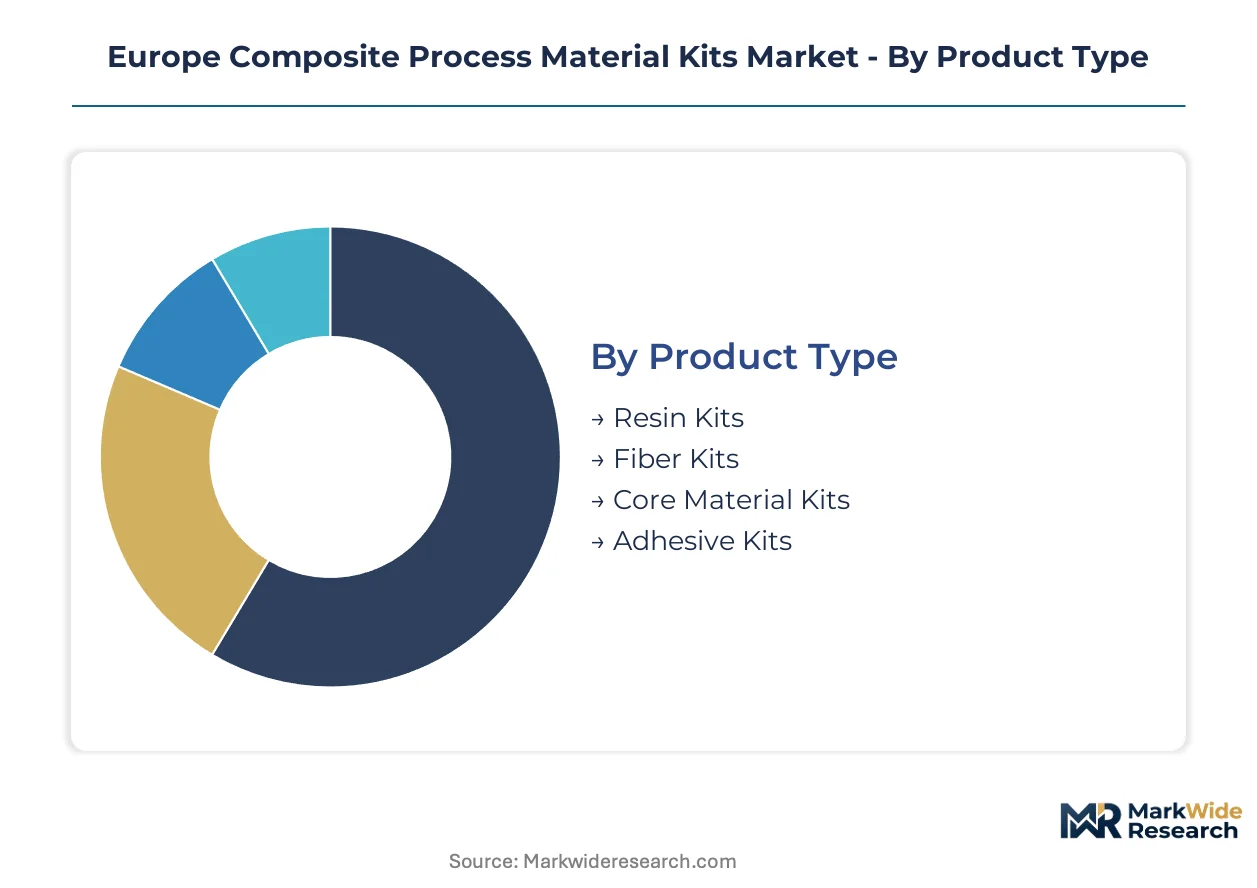
Composite process material kit segmentation reveals how procurement priorities diverge across European manufacturing corridors. Specification requirements for autoclave versus out-of-autoclave curing create fundamentally different bundling strategies among German aerospace OEMs and Italian marine builders.
Product Type:
Material composition dictates kit pricing tiers and qualification complexity for tier-one suppliers.
- Fiber Kits:Bundles of carbon fiber prepreg, glass fiber fabrics, and handling consumables engineered for precise ply orientation and contamination control. Demand concentrates in Airbus wing programs across Hamburg and Broughton, where automated fiber placement requires synchronized material delivery to match takt times.
- Adhesive Kits:Structural film adhesives, paste adhesives, and primer systems packaged for bonded joint assembly in lightweight structures. German automotive OEMs in Bavaria specify these kits for aluminum-composite hybrid body-in-white construction as mechanical fastener elimination accelerates.
- Resin Kits:Epoxy, polyester, and vinyl ester formulations with hardeners and wetting agents for infusion and hand layup processes.
- Core Material Kits:Balsa, foam, and honeycomb core sheets with bonding adhesives and contouring templates for sandwich panel fabrication.
Volume sits with fiber kits; growth tilts toward adhesive kits.
End User:
Customer scale and certification rigor determine supplier margin structures and contract duration.
- Aerospace:Kit specifications tied to EASA Part 21 production organization approvals and OEM-qualified material lists. French and German defense programs in Manching and Toulouse anchor procurement volumes for military transport and combat aircraft structures.
- Automotive:Lower qualification barriers but higher volume volatility as platform cycles compress. Italian supercar manufacturers in Modena and German premium OEMs in Stuttgart drive specification for visible carbon fiber body panels.
- Marine:Superyacht builders in the Netherlands and Italy demand core material kits for hull and deck sandwich construction with extended weathering resistance.
- Construction:Bridge strengthening and wind tower applications requiring CE marking under Construction Products Regulation compliance.
Aerospace commands premium pricing; automotive offers volume scaling.
Application:
Process stage determines consumable turnover rates and kit replenishment frequency.
- Manufacturing:Original equipment production with highest kit specification rigor and longest supplier qualification timelines. Airbus A350 and A320neo family programs in Hamburg and Toulouse dominate European manufacturing kit consumption.
- Repair:EASA Part 145 maintenance station operations with shorter procurement cycles and localized kit cutting services. UK rotorcraft operators in Yeovil and Aberdeen drive demand for rapid-turn repair material sets.
- Coating:Surface preparation and finishing consumables for corrosion protection and aesthetic finishing.
- Parts Fabrication:Tier-two and tier-three component supplier operations with standardized kit configurations.
Manufacturing absorbs the largest kit volumes; repair shows the steepest expansion trajectory.
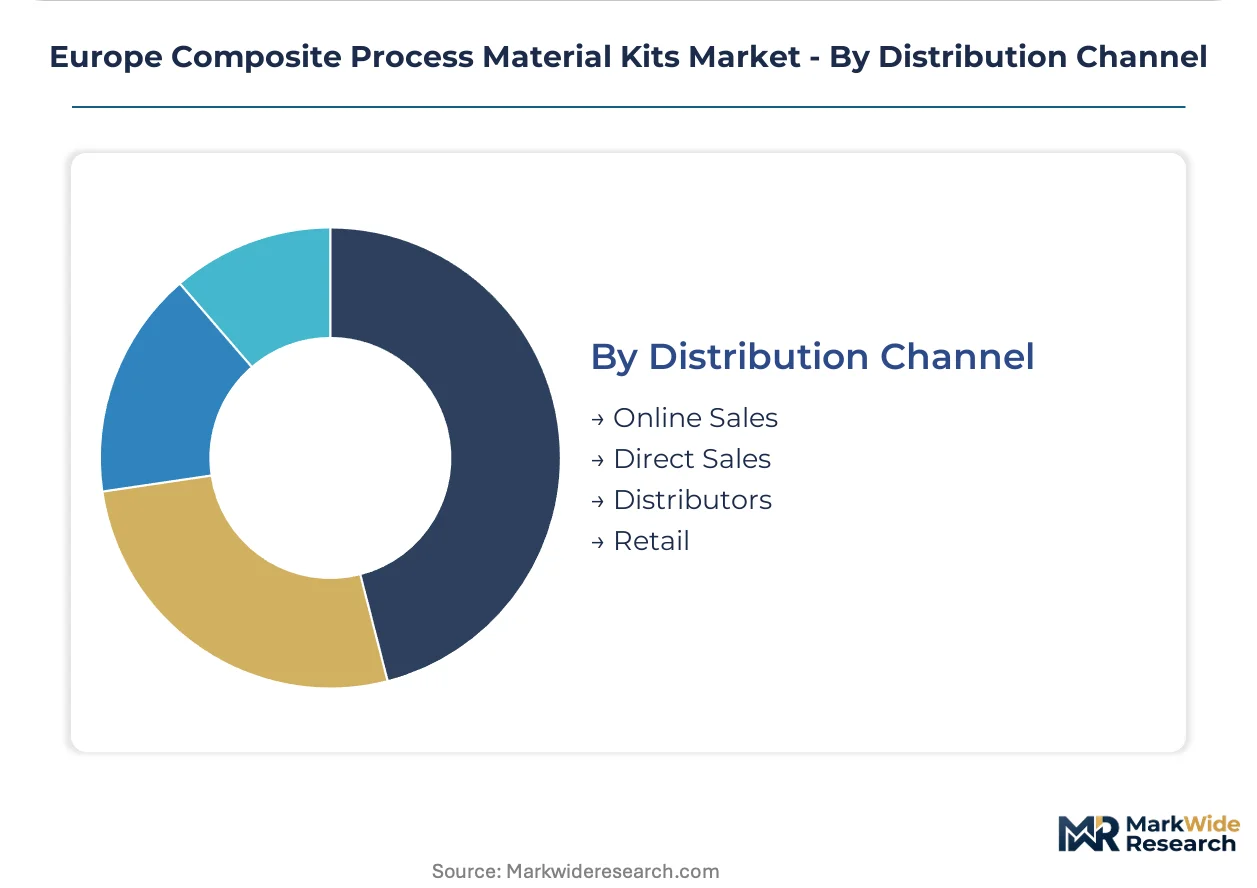
Distribution Channel:
Channel selection reflects customer technical support requirements and order fragmentation.
- Direct Sales:Long-term supply agreements with Airbus, Safran, and BAE Systems involving dedicated kitting centers and consignment inventory. Direct relationships dominate aerospace procurement above specified contract thresholds.
- Distributors:Regional stockholding intermediaries serving fragmented marine and construction customers across Mediterranean ports and North Sea shipyards.
- Online Sales:Catalog-based procurement for standardized consumables among small fabrication shops and training institutions.
- Retail:Limited to hobbyist and educational market segments with minimal commercial significance.
Direct sales capture aerospace value; distributors serve geographic fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Bavaria and Baden-Württemberg drive German aerospace concentration, while French aerospace clusters benefit from state-backed innovation tax credits. These incentive structures explain why kit procurement volumes concentrate in specific corridors rather than dispersing across the continent.
Germany
Airbus Defence and Space operations in Manching and Airbus Commercial in Hamburg anchor kit demand for military transport and narrow-body programs. The German government allocates aerospace R&D tax credits through the LuFo program, subsidizing next-generation material qualification. Bavaria's aerospace corridor around Augsburg and Munich hosts tier-one suppliers synchronizing kit delivery to A320neo family takt times.
France
Safran and Airbus operations in Toulouse and Nantes drive specification for pressurized cabin and engine nacelle kits. ANSM oversees chemical safety assessments for resin components used in French aerospace manufacturing. The Occitanie region's Aerospace Valley cluster coordinates supplier qualification pools that compress kit approval timelines for new material introductions.
United Kingdom
BAE Systems in Broughton and Leonardo Helicopters in Yeovil demand just-in-time kitting services for rotorcraft and military fast-jet programs. The UK Civil Aviation Authority enforces EASA-aligned Part 21 production organization standards for kit suppliers. Southwest England's aerospace cluster around Bristol and Somerset specializes in satellite and defense material sets with extended qualification documentation.
Italy
Leonardo's helicopter division in Cascina Costa and superyacht builders in Viareggio generate core material kit demand for marine sandwich construction. The Italian Ministry of Economic Development funds composite research through the MISE National Recovery and Resilience Plan allocations. The Lombardy-Veneto corridor around Milan and Venice hosts distributors serving fragmented marine customers across Mediterranean ports.
Poland
Lockheed Martin F-16 sustainment operations in Łódź and potential future assembly programs create emerging kit supply relationships outside established networks. The Polish Investment and Trade Agency offers special economic zone incentives for aerospace suppliers locating near Rzeszów and Mielec. These zones attract kit cutting centers seeking proximity to expanding Eastern European manufacturing footprints.
Europe Composite Process Material Kits Market Competitive Landscape
Top-tier vendors anchor aerospace-qualified supply relationships, while mid-tier specialists compete on regional responsiveness and niche material formulations. The European market structures around three distinct tiers: integrated material-formulation-kitting conglomerates, regional cutting-and-logistics specialists, and distributor-intermediaries serving fragmented marine and construction demand. Two dominant competitive moves define current positioning: backward integration into resin formulation to capture margin pools, and geographic expansion via dedicated kitting centers near major OEM assembly lines.
Within the integrated-material tier, Solvay and Airtech Advanced Materials Group occupy positions exemplifying formulation-to-kit control. Solvay represents the specialty chemical archetype with captive resin technology feeding qualified kit specifications. Airtech anchors the vacuum-bagging-film specialist archetype with European cutting infrastructure synchronized to Airbus tier-one demand. Velocity Composites plc sits within the pure-kitting-services archetype, demonstrating how UK-based specialists capture value through just-in-time logistics rather than material manufacturing.
| Leading Market Players |
|---|
| Airtech Advanced Materials Group |
| Aerovac Composites One |
| Diatex SAS |
| Velocity Composites plc |
| GEFiM |
| InCom Group |
| Metyx Composites |
| Pro-Vac Vacuum Consumables |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EASA-qualified aerospace kits and unmarked industrial consumables manifests in both margin structures and supplier qualification timelines across European procurement channels. Premium-tier kit assemblers command pricing power through captive resin formulations and OEM-approved material lists, while commodity-grade distributors compete on spot availability for marine and construction segments with minimal technical support bundling.
Pricing Analysis
Short lead-time premiums of 15-25% apply to just-in-time kitting services delivered within 48-hour windows to Airbus tier-one suppliers in Hamburg and Toulouse. Aerospace procurement operates on long-term contract-based offtake agreements with price escalation clauses tied to naphtha cracking margins, while spot market transactions serve fragmented marine builders. Price differentiation rests on REACH registration status and EASA Part 21 approval tier. Cost compression in standard-grade adhesive kits is intensifying because German automotive OEMs are consolidating supplier panels. Tier-two rotorcraft manufacturers exhibit highest price sensitivity due to program budget volatility; defense prime contractors show least sensitivity given specification-locked procurement.
Supply Chain Analysis
Dual-sourcing requirements mandated by Airbus and Safran procurement policies force kit assemblers to qualify secondary resin compounders and film extruders across Germany, France, and the UK. Raw material dependencies center on epoxy resin feedstocks from petrochemical complexes in Rotterdam and Antwerp, carbon fiber tow from SGL Carbon facilities in Germany, and polyamide films from European extrusion plants. Single-source vulnerability concentrates in specialty hardener formulations subject to ECHA substance evaluation. Distribution runs through direct sales agreements for aerospace volumes above contract thresholds, with regional distributors serving Mediterranean marine ports and North Sea shipyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Composite Process Material Kits Market sits in a technology-transition phase as out-of-autoclave curing methods displace energy-intensive autoclave processes across wing and fuselage programs.
For Market Incumbents: To counter REACH-driven resin reformulation costs, Solvay and Airtech should deepen backward integration into bio-based hardener development and expand cutting-center capacity in Poland's Rzeszów special economic zone. Captive supply of qualified resin formulations preserves margin pools as ECHA restrictions tighten. For New Entrants and Emerging Players: The mid-tier pricing gap between premium aerospace-qualified kits and commodity marine consumables offers entry space for regional specialists targeting Italian superyacht builders in Viareggio. Poland's emerging aerospace corridor presents the most penetrable geography given Lockheed Martin F-16 sustainment operations. A go-to-market angle anchored on CSRD-compliant carbon accounting differentiates against established German-French suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with pure-kitting logistics specialists given CSRD supply chain disclosure requirements accelerating OEM consolidation toward traceable material streams. Long-term viability over a 5-10 year window favors targets with RFID-enabled consumption tracking and closed-loop film recovery partnerships. The signal to watch is Airbus specification lock-in for bio-epoxy alternatives in A320neo family programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resin Formulation | Captures margin pools as ECHA restrictions force hardener pivots across German compounders. |
| RFID-Enabled Kitting Center Expansion | Enables predictive replenishment for BAE Systems rotorcraft lines in Yeovil and Broughton. |
| Closed-Loop Vacuum Film Recovery Partnership | Aligns with EU Green Deal mandates and Airbus Hamburg pilot programs for consumable reduction. |
| CSRD Carbon Accounting Certification | Qualifies suppliers for mandatory Scope 3 emissions reporting across Safran and Airbus procurement. |
| Poland Special Economic Zone Manufacturing Footprint | Positions kit cutting centers near Lockheed Martin operations in Łódź and emerging Eastern European demand. |
Research Methodology
Independent corroboration across primary interviews with kit procurement managers at Airbus tier-one suppliers, resin formulation technical directors, and EASA Part 145 maintenance station operators underwrites the qualitative findings. Secondary validation drew from ECHA substance evaluation databases, EU Green Deal implementation reports, and aerospace OEM supplier qualification documentation. Bottom-up demand modeling across fiber kit, adhesive kit, and core material kit segments was triangulated against top-down European composite consumption estimates from trade association filings.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in aerospace versus automotive end-use segments. The analytical framework models product type, end user industry, application stage, and distribution channel dimensions alongside regional production cluster concentration. CAGRs were derived from segment-level growth trajectories weighted by base-year value shares. Forecast inputs incorporate REACH registration timelines for novel bio-based hardeners and out-of-autoclave curing adoption curves in wing production programs.
Inputs from ECHA substance evaluation proceedings and OEM supplier qualification portals were available through the study window; gaps in real-time inventory positioning data at tier-two kit assemblers introduce uncertainty bands around short-term demand elasticity assumptions. Deviation in Airbus A320neo family production rates or ECHA bisphenol restriction implementation timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Thermoset Composites Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Stone Plastic Composite Flooring Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Short Fiber Thermoplastic Composites Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Composite Quartz Stone Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
FRP Grating Market
Composite Materials
FRP Reactor Market
Composite Materials
Transportation Composites Market
Composite Materials
Europe Composites Market
Composite Materials
Global Coupling Agents Market