
 Green Composites Market | 2026-2036
Green Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Green Composites Market Outlook
China's Yangtze River Delta is rewriting regional supply dynamics for plant-derived reinforcement materials. Toray Advanced Composites dominates high-performance aerospace prepregs through captive supply of thermoplastic bio-fiber intermediates. Bcomp leverages its European manufacturing base to sustain premium positioning in motorsport and luxury automotive interiors. Hexcel Corporation anchors North American demand through specialized production of bio-epoxy systems for commercial aviation primary structures.
Green composites are engineered materials combining natural fibers such as flax, hemp, or jute with bio-based or recycled polymer matrices, typically processed through compression molding or resin transfer molding to achieve specific strength-to-weight ratios exceeding 150 MPa per g/cm³ for structural applications. The automotive application segment leads current volume consumption as OEMs substitute glass fiber in non-structural components to meet fleet emissions targets. Natural fibers command the fastest growth trajectory among material types, driven by mechanical property improvements in bast fiber processing and compatibility with existing thermoforming equipment. Bio-composites occupy the highest margin tier due to certification complexity and limited qualified supplier bases serving medical device and premium consumer goods channels.
The European Chemicals Agency enforces REACH registration requirements for bio-based resin precursors, while the US EPA administers TSCA oversight on novel natural fiber surface treatments entering commercial distribution. China's Ministry of Ecology and Environment applies dual carbon goals to industrial park permitting, directly constraining conventional composite expansion and redirecting capacity investment toward certified green alternatives. Stakeholders must monitor evolving biodegradability certification standards from ISO and national bodies, as harmonization gaps between jurisdictions increasingly determine cross-border product qualification and procurement eligibility.
Market Dynamics
EU REACH restrictions on petrochemical feedstocks are forcing automotive OEMs to requalify interior panel supply chains around bast fiber reinforcements, compressing substitution timelines from five years to eighteen months.
Growth Catalysts
- REACH compliance deadlines:European OEMs face mandatory phase-out timelines for synthetic fiber interiors, accelerating flax and hemp procurement contracts.
- China's dual carbon goals:MEE permitting constraints redirect state-backed infrastructure investment toward certified bio-composite fiberboard for construction applications.
- Compression molding compatibility:Equipment retrofits at tier-one automotive suppliers now process natural fiber preforms without dedicated capital expenditure cycles.
Market Restraints
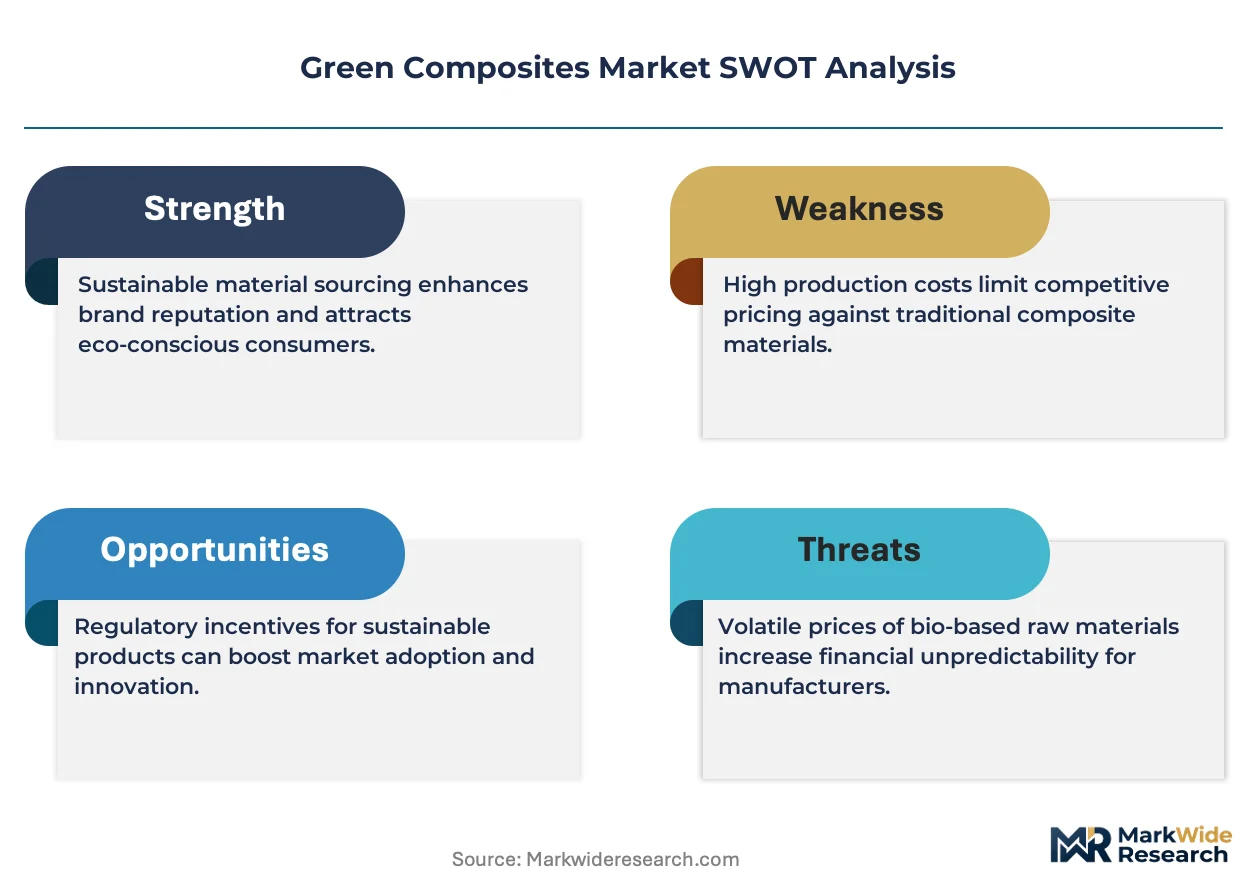
- Resin precursor volatility:Bio-epoxy feedstock costs fluctuate with agricultural commodity markets, exposing margin structures to weather-driven supply shocks.
- Yangtze River Delta concentration:Pilot-scale bio-resin capacity clusters in a single Chinese industrial corridor, creating geographic single-point vulnerability.
- Surface treatment limitations:Natural fiber moisture absorption rates exceed glass fiber benchmarks, restricting deployment in exterior automotive applications.
Strategic Opportunities
- Medical device certification:Bio-composite margins expand fastest in implantable and surgical instrument channels where ISO 10993 compliance creates supplier scarcity.
- Aerospace thermoplastic prepregs:Toray's captive bio-fiber intermediate technology converges with automated fiber placement systems to unlock primary structure applications.
- India PLI scheme alignment:Domestic bio-composite production incentives under the automotive component manufacturing program attract capacity relocation from European suppliers.
Industry Challenges
- Biodegradability certification fragmentation:ISO 14855 harmonization gaps between EU, US, and Chinese testing protocols delay cross-border product launches by 12-18 months.
- Natural fiber supply seasonality:Bast crop harvesting windows constrain year-round production scheduling at compression molding facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Composites Market |
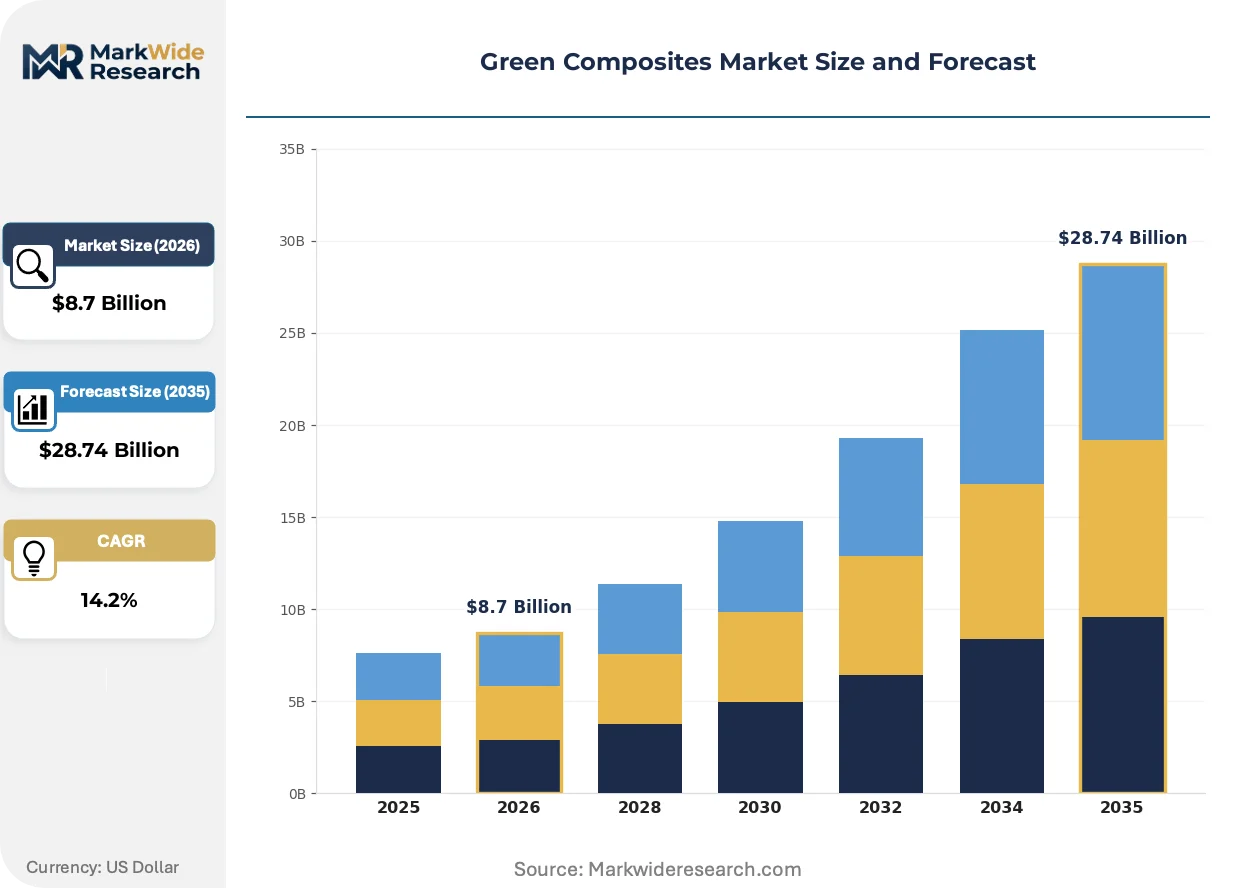
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Natural Fibers, Bio-resins, Recycled Plastics, Bio-composites Application: Aerospace, Automotive, Construction, Consumer Goods End User: OEMs, Tier-1 Suppliers, Manufacturers, Contractors Distribution Channel: Direct Sales, Online Retail, Distributors, B2B Supply |
| Companies Covered | Mitsubishi Chemical Advanced Materials, Bcomp, Hexcel Corporation, Teijin Limited, INCA Renewable Technologies, Toray Advanced Composites, SGL Carbon, Gurit Holding AG, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Composites Market Strategic Shifts
Processing technology convergence is collapsing the historical performance gap between natural and synthetic fiber composites, enabling structural load-bearing applications that were previously reserved for carbon fiber.
Automated fiber placement is digitizing natural fiber preform manufacturing, eliminating manual layup variability that previously limited aerospace qualification. Tier-one suppliers in Germany and Japan are adopting these systems for non-structural interior series production. The technology is digitizing quality assurance workflows, compressing first-article inspection timelines from weeks to hours.
REACH registration requirements for bio-based resin precursors now mandate full toxicological dossiers for novel natural fiber surface treatments entering European distribution. ECHA enforcement has blocked three Asian supplier entries since 2023. Commercial aviation bio-epoxy systems face the steepest compliance burden, with Hexcel and Toray maintaining dedicated regulatory affairs teams in Brussels.
Fleet emissions targets are compressing automotive OEM qualification cycles for interior component substitutions. Procurement teams now run parallel material validation tracks rather than sequential glass-to-natural fiber transitions. German and Japanese OEMs lead this behavioral shift, with tier-one suppliers reporting 40% faster approval velocities versus 2020 benchmarks.
Green Composites Market Segmentation
Green composites serve radically different performance requirements across mobility, infrastructure, and consumer sectors. Segmentation reveals how material selection, application engineering, and channel economics diverge by end-use intensity and regulatory exposure.
Material Type:
Use-case spectrum spans structural load-bearing to disposable packaging, with fiber-matrix combinations calibrated to durability, biodegradability, and processing compatibility.
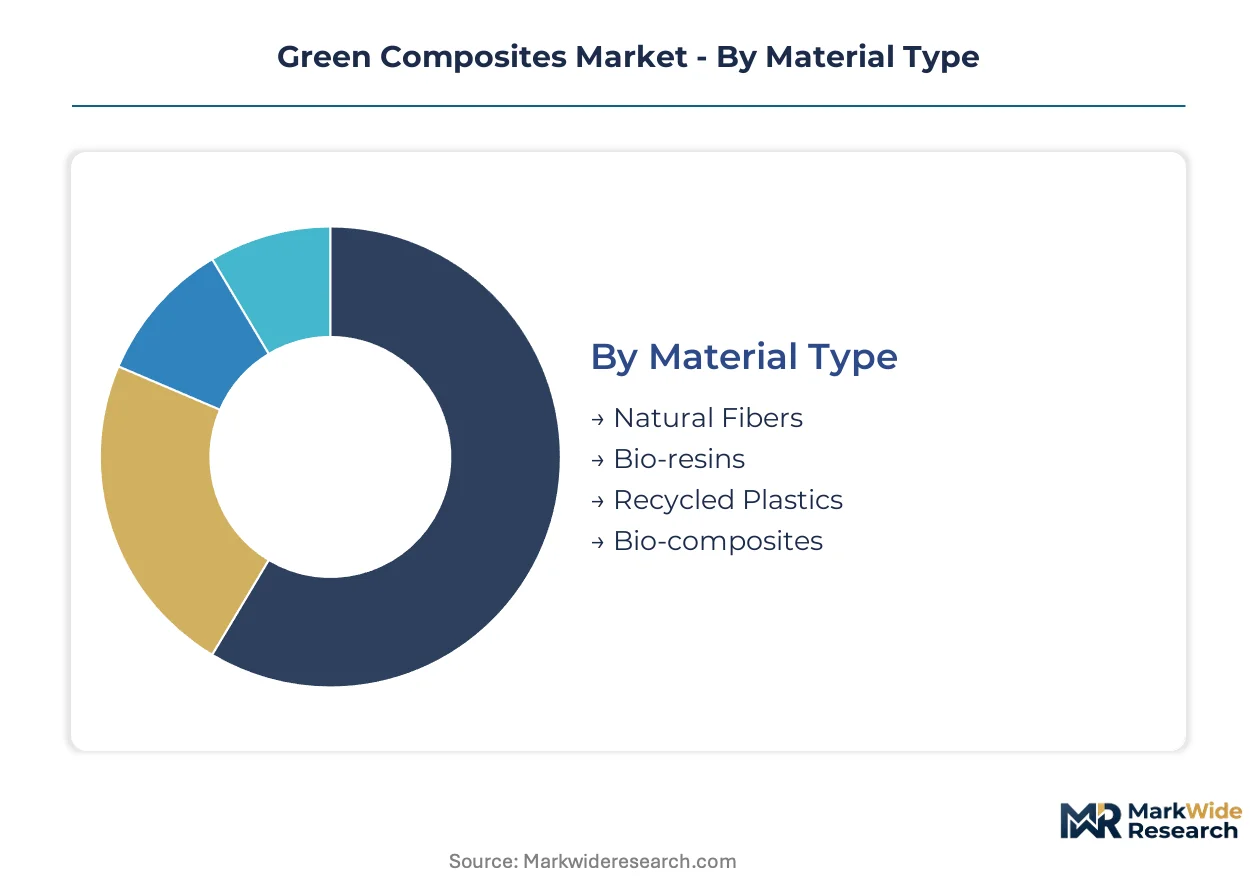
- Natural Fibers:Bast fibers such as flax and hemp deliver tensile strength exceeding 600 MPa when aligned, with density 40% below glass fiber equivalents. Automotive interior panels in Germany and Japan now specify these reinforcements to meet EU REACH synthetic phase-out deadlines. Moisture absorption remains the primary constraint for exterior deployment.
- Bio-composites:Certified fiber-matrix systems command premium positioning in medical device and aerospace channels where ISO 10993 and FAA qualification create supplier scarcity. Toray and Hexcel maintain dedicated regulatory affairs teams to secure these margins. Limited qualified production bases restrict volume scaling despite price premiums.
- Bio-resins:Epoxy and thermoplastic precursors derived from lignin or plant oils enable partial petrochemical substitution in existing compression molding equipment. Agricultural commodity price volatility exposes margin structures to weather-driven supply shocks.
- Recycled Plastics:Post-consumer polymer streams blended with natural fiber fillers target cost-sensitive construction fiberboard in China's Yangtze River Delta state-backed infrastructure projects.
The dominant share belongs to Natural Fibers, while Bio-composites is closing the gap fastest.
Application:
Performance thresholds and certification burdens create four distinct commercial environments with diverging procurement cycles and margin structures.
- Automotive:Non-structural interior components—door panels, headliners, seat backs—drive current volume as OEMs substitute glass fiber to meet fleet emissions targets. German and Japanese manufacturers have compressed qualification timelines from five years to eighteen months under REACH pressure.
- Aerospace:Commercial aviation primary structures require bio-epoxy systems with full toxicological dossiers for ECHA registration. Hexcel anchors North American demand through specialized production lines.
- Construction:China's Ministry of Ecology and Environment applies dual carbon goals to industrial park permitting, redirecting capacity investment toward certified green fiberboard for state-backed contractors.
- Consumer Goods:Premium positioning in surgical instruments and implantable devices exploits ISO compliance scarcity, though volumes remain constrained by medical-grade certification timelines.
Automotive captures the largest volume position, with Aerospace expanding most quickly as automated fiber placement unlocks structural qualification.
End User:
Procurement authority and technical specification control determine channel economics and supplier relationship intensity.
- OEMs:German and Japanese automotive manufacturers now run parallel material validation tracks rather than sequential substitutions, accelerating contract velocity 40% versus 2020 benchmarks.
- Tier-1 Suppliers:Equipment retrofits at compression molding facilities now process natural fiber preforms without dedicated capital expenditure cycles, enabling rapid scale-up.
- Manufacturers:Medical device producers face ISO 14855 harmonization gaps between EU, US, and Chinese testing protocols that delay cross-border launches.
- Contractors:Yangtze River Delta infrastructure contractors source construction-grade fiberboard from local bio-resin pilot plants under state procurement mandates.
OEMs retain specification authority, while Tier-1 Suppliers are gaining procurement autonomy fastest as processing technology standardizes.
Distribution Channel:
Product complexity and certification documentation requirements fragment channel structures by customer scale and application risk.
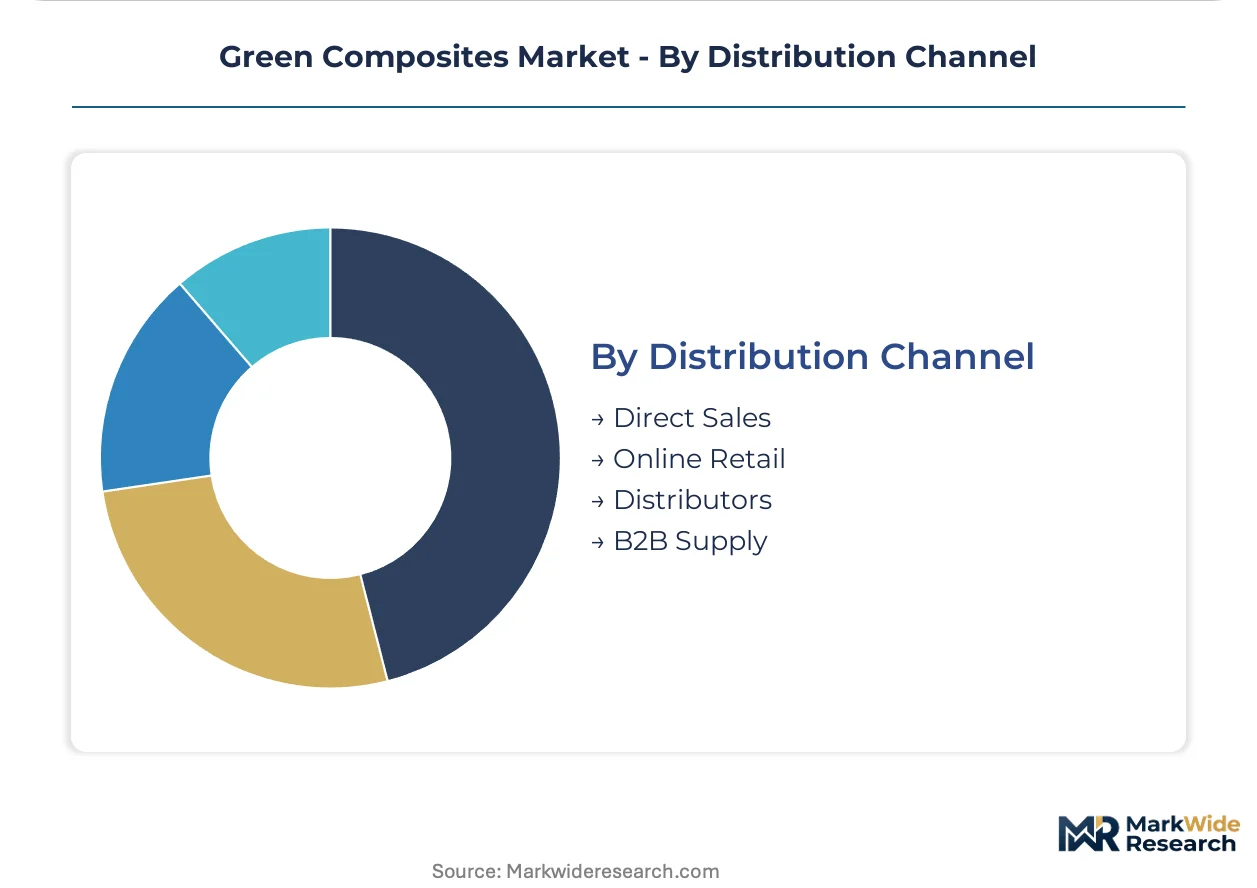
- Direct Sales:Aerospace bio-epoxy systems and medical-grade bio-composites move through manufacturer-direct relationships requiring dedicated technical service and regulatory dossier management.
- Distributors:Construction fiberboard and automotive interior materials flow through regional distributors serving China's Yangtze River Delta industrial corridor.
- B2B Supply:Long-term procurement contracts with tier-one automotive suppliers specify volume commitments and quality assurance protocols for natural fiber preform delivery.
- Online Retail:Limited to standardized recycled plastic compounds and small-volume bio-resin samples for R&D evaluation.
Direct Sales commands the highest margin tier, with B2B Supply expanding fastest as automotive procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilot-scale bio-resin capacity clusters heavily in China's Yangtze River Delta, while automotive qualification cycles compress fastest in Germany and Japan. Regulatory enforcement in Brussels and Beijing is redirecting investment flows toward certified green alternatives.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg now run parallel material validation tracks for flax-reinforced interior panels. ECHA REACH enforcement mandates toxicological dossiers for all bio-based resin precursors entering European distribution. Stuttgart's tier-one supplier corridor retrofits compression molding equipment to process natural fiber preforms without dedicated capital cycles.
China
State-backed infrastructure contractors in the Yangtze River Delta source construction-grade fiberboard from local bio-resin pilot plants. MEE dual carbon goals constrain conventional composite expansion in industrial park permitting. Shanghai's supplier cluster faces geographic single-point vulnerability as pilot-scale capacity concentrates in this corridor alone.
Japan
Automotive manufacturers accelerate procurement contracts for bast fiber reinforcements to meet compressed qualification timelines. METI industrial policy supports processing technology convergence for automated fiber placement systems. Nagoya's automotive supplier base digitizes natural fiber preform manufacturing for series production.
United States
Commercial aviation demand anchors North American bio-epoxy consumption for primary structure applications. EPA TSCA oversight applies to novel natural fiber surface treatments entering commercial distribution. Hexcel maintains specialized production lines and dedicated regulatory affairs capacity to secure aerospace qualification.
India
Domestic bio-composite production incentives under the automotive component PLI scheme attract capacity relocation from European suppliers. BIS standards development lags behind EU and US certification protocols, delaying market entry. Gujarat and Maharashtra industrial corridors host emerging compression molding facilities for tier-one automotive contracts.
Green Composites Market Competitive Environment
Diversified chemical conglomerates and specialized composite fabricators split the market along certification complexity lines. Supplier scarcity in medical-grade and aerospace channels sustains premium margin tiers despite volume constraints. Three archetypes dominate: integrated resin-fiber producers, tier-one automotive system suppliers, and regulatory-affairs-heavy aerospace specialists. Competitive dynamics center on backward integration into bio-fiber intermediates and dedicated Brussels-based compliance teams.
Within the diversified chemical tier, Mitsubishi Chemical Advanced Materials and Solvay exemplify scale-driven positioning across multiple end-use verticals. Specialized fabricators include Bcomp, which occupies a premium position in motorsport and luxury automotive interiors through its European manufacturing base. Toray Advanced Composites anchors the aerospace-specialist archetype with captive supply of thermoplastic bio-fiber intermediates. Hexcel Corporation represents North American regulatory-heavy production for commercial aviation primary structures.
| Leading Market Players |
|---|
| Mitsubishi Chemical Advanced Materials |
| Bcomp |
| Hexcel Corporation |
| Teijin Limited |
| INCA Renewable Technologies |
| Toray Advanced Composites |
| SGL Carbon |
| Gurit Holding AG |
| Solvay |
| Others |
Value Chain & Pricing Dynamics
Pilot-scale bio-resin capacity in China's Yangtze River Delta funnels margin pools toward medical-grade bio-composite channels where ISO 10993 certification creates supplier scarcity. Agricultural commodity volatility in bio-epoxy feedstocks compresses margins at the construction fiberboard tier while aerospace qualification premiums sustain pricing power for Brussels-compliant producers.
Pricing Analysis
EU REACH registration requirements dictate the pricing tier structure across European distribution, separating certified bio-composites from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ECHA dossier completeness, volume scale, and after-sales technical service bundling. Cost compression in construction-grade fiberboard is intensifying because agricultural commodity price swings expose bio-resin producers to margin erosion. Tier-one automotive suppliers exhibit highest price sensitivity due to compressed OEM qualification timelines, while medical device manufacturers accept premium positioning for ISO-compliant supply security.
Supply Chain Analysis
Geographic single-point vulnerability in the Yangtze River Delta dominates supply chain risk assessment for construction fiberboard procurement. China, Germany, and Japan anchor upstream bast fiber processing and downstream compression molding equipment retrofits. Raw material dependencies center on flax and hemp harvests, lignin-derived epoxy precursors, and thermoplastic bio-fiber intermediates. Tariff exposure between EU and Asian bio-resin suppliers threatens cross-border qualification timelines. Distribution runs through direct sales for aerospace bio-epoxy systems and regional distributors serving China's state-backed infrastructure contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated fiber placement interoperability is collapsing the historical performance gap between natural and synthetic fiber composites, creating platform-economics dynamics where processing technology convergence determines competitive access.
For Market Incumbents: Pre-empt emerging Asian bio-resin entrants by securing captive supply of thermoplastic bio-fiber intermediates and expanding Brussels-based regulatory affairs capacity. ECHA enforcement blocking three Asian supplier entries since 2023 signals window for qualification-based moat construction. Backward integration into bast fiber processing insulates margin structures from agricultural commodity volatility. For New Entrants and Emerging Players: Build out India PLI scheme-aligned production capacity in Gujarat and Maharashtra industrial corridors, targeting tier-one automotive contracts relocating from European suppliers. BIS standards development lag creates penetrable white space for early ISO 14855 harmonization investment. Go-to-market angle centers on compressed qualification timelines for OEMs facing REACH compliance deadlines. For Investors and Strategic Acquirers: Capital is best deployed toward regulatory-affairs-heavy aerospace specialists with dedicated Brussels teams and captive bio-fiber intermediate technology. Long-term viability hinges on biodegradability certification harmonization across EU, US, and Chinese protocols. Signal to watch: ISO 14855 testing protocol alignment as inflection indicator for cross-border product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Fiber Intermediates | Toray's captive thermoplastic supply secures aerospace qualification timelines against resin precursor volatility. |
| Brussels Regulatory Affairs Capacity Expansion | Hexcel's dedicated ECHA team maintains bio-epoxy registration dossiers for commercial aviation primary structures. |
| Automated Fiber Placement Technology Adoption | Nagoya's tier-one suppliers digitize natural fiber preform manufacturing for compressed first-article inspection. |
| India PLI Scheme Manufacturing Relocation | Gujarat compression molding facilities attract capacity from European suppliers facing REACH compliance cost pressure. |
| ISO 14855 Harmonization Investment | Medical device producers bridge EU-US-China testing protocol gaps to accelerate cross-border launch timelines. |
Study Parameters
Initial hypotheses were tested against primary input from automotive OEM procurement directors, tier-one supplier plant managers, bio-resin R&D directors, and ECHA regulatory affairs specialists and refined through secondary validation. Sources included customs trade data for bast fiber imports, SEC 10-K filings from composite manufacturers, REACH registration dossiers, and Yangtze River Delta industrial park permitting records. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed material type, application intensity, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Industry-specific inputs included automotive fleet emissions target trajectories and MEE dual carbon goal enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese bio-resin producers or accelerated REACH phase-out timelines would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Composite Preforms Market
Composite Materials
Composite Rollers Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
China Marine Composites Market
Composite Materials
Structural Composites Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
Global Geocomposites Market
Composite Materials
Transportation Composites Market
Composite Materials
Global Composite Resin Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Marine Composites Market
Composite Materials
Aluminum Composite Materials Market