
 Global Carbon Capture and Storage Market | 2026-2036
Global Carbon Capture and Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Capture and Storage Market Foresight
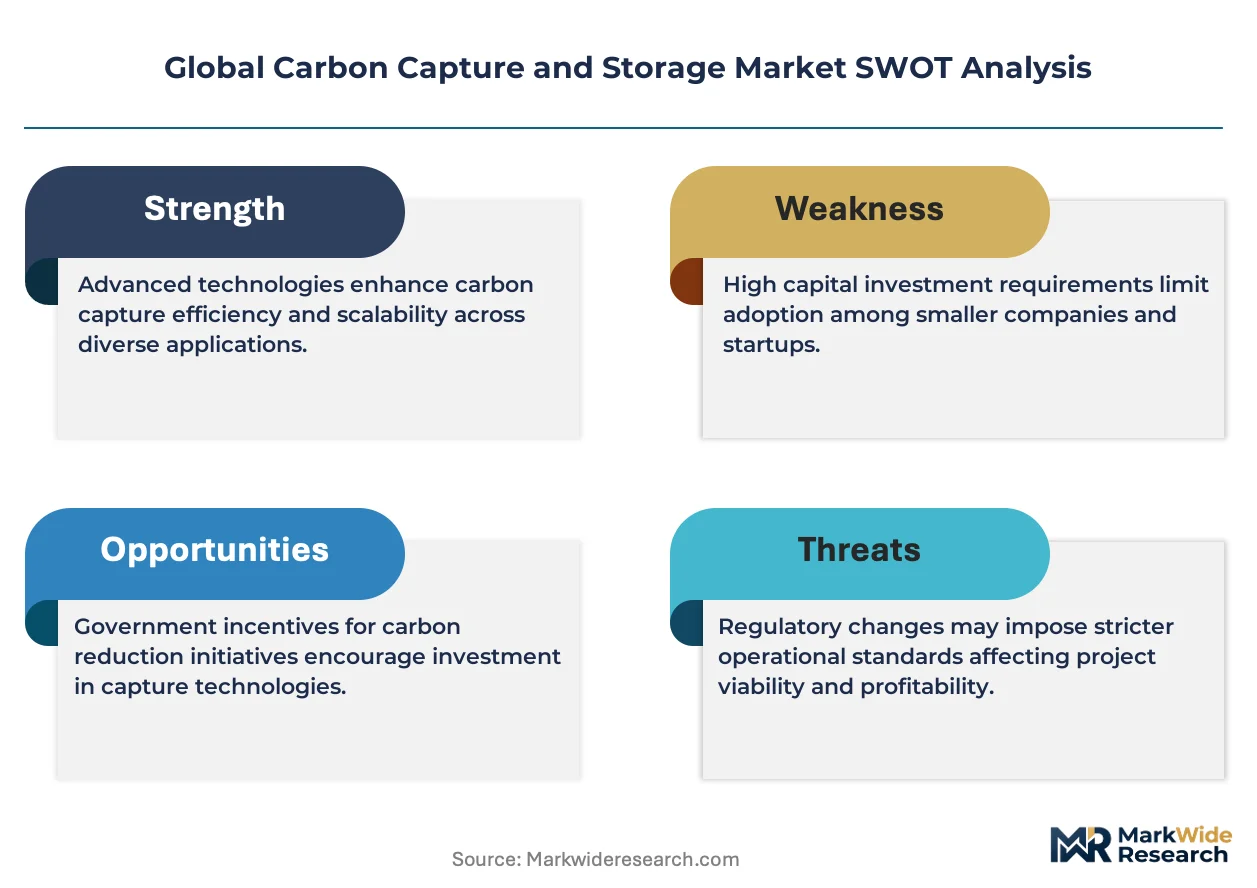
Buyer concentration among energy producers is hardening as utilities and oil majors consolidate offtake agreements for large-scale storage hubs. ExxonMobil Corporation leverages its Gulf Coast pipeline network to anchor saline aquifer projects across Texas and Louisiana. Equinor ASA dominates the North Sea storage corridor with operational experience at Sleipner and Northern Lights. Shell plc competes through integrated carbon management offerings spanning capture engineering to permanent sequestration.
Carbon capture and storage encompasses the separation, transport, and geological sequestration of carbon dioxide from industrial flue streams or fuel processing, typically achieving capture rates above 90 percent through amine scrubbing, membrane separation, or cryogenic distillation systems. Post-combustion capture leads deployment because it retrofits existing power and cement plants without requiring fundamental process redesign, while saline aquifers represent the fastest-growing storage medium due to their vast capacity and lower competition with hydrocarbon recovery. Heavy manufacturing anchors current demand as steel and cement producers face binding emissions obligations, though waste-to-energy applications are expanding as municipal operators seek landfill diversion credits.
The EPA's Underground Injection Control program governs Class VI well permitting in the United States, creating multi-year approval timelines that constrain project velocity, while the EU Green Deal's Carbon Border Adjustment Mechanism and ETS price floors directly shape European investment timelines. China's MEE implements dual carbon goals through provincial emissions caps that force coal-to-chemicals operators toward capture retrofits. Stakeholders must monitor regulatory harmonization between national storage liability frameworks and cross-border CO2 transport treaties to assess long-term asset viability.
Market Dynamics
Saline aquifer storage economics are compressing project timelines as Class VI permitting bottlenecks force developers toward pre-certified geological formations with established containment data. The competitive landscape splits between pipeline-integrated majors with captive transport networks and modular capture specialists competing on retrofit speed.
Growth Catalysts
- EU ETS price floors:Binding emissions obligations under the EU Green Deal's Carbon Border Adjustment Mechanation are accelerating cement and steel retrofit commitments across Germany, Poland, and the Netherlands.
- Post-combustion amine systems:Mature scrubbing technology enables 90-plus percent capture rates without fundamental process redesign, preserving capital-intensive plant infrastructure.
- China:Provincial emissions caps enforced by the MEE are compelling coal-to-chemicals operators toward capture retrofits in Shandong and Inner Mongolia.
Market Restraints
- Class VI permitting timelines:The EPA's Underground Injection Control program imposes multi-year approval cycles that constrain project velocity and tie up capital without revenue generation.
- Transport infrastructure gaps:Dense CO2 pipeline networks concentrate in the US Gulf Coast, leaving Rocky Mountain and Midwest projects dependent on costly truck or rail alternatives.
- Direct air capture competition:Emerging DAC technologies threaten to divert policy subsidies and offtake commitments from point-source capture investments.
Strategic Opportunities
- Waste-to-energy expansion:Municipal operators in Sweden, Denmark, and the Netherlands are pursuing landfill diversion credits through flue gas capture retrofits on incineration facilities.
- Blue hydrogen integration:Steam methane reforming with CCS is capturing policy support under the US Inflation Reduction Act's clean hydrogen production credits.
- Membrane-cryogenic hybrid systems:Converging separation technologies are opening efficiency gains for natural gas processing and bioethanol facilities with variable CO2 concentrations.
Industry Challenges
- Geological containment certification:Demonstrating plume migration control and long-term liability transfer requires specialized reservoir engineering talent that remains concentrated among a handful of consultancies.
- Cross-border transport treaties:The London Protocol's amendment on CO2 sequestration lacks full ratification, complicating North Sea basin projects that would move captured volumes between Norway, Denmark, and the Netherlands.
- Legacy plant integration:Retrofitting post-combustion systems onto aging cement kilns and refineries demands custom engineering that stretches project timelines and erodes returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Capture and Storage Market |
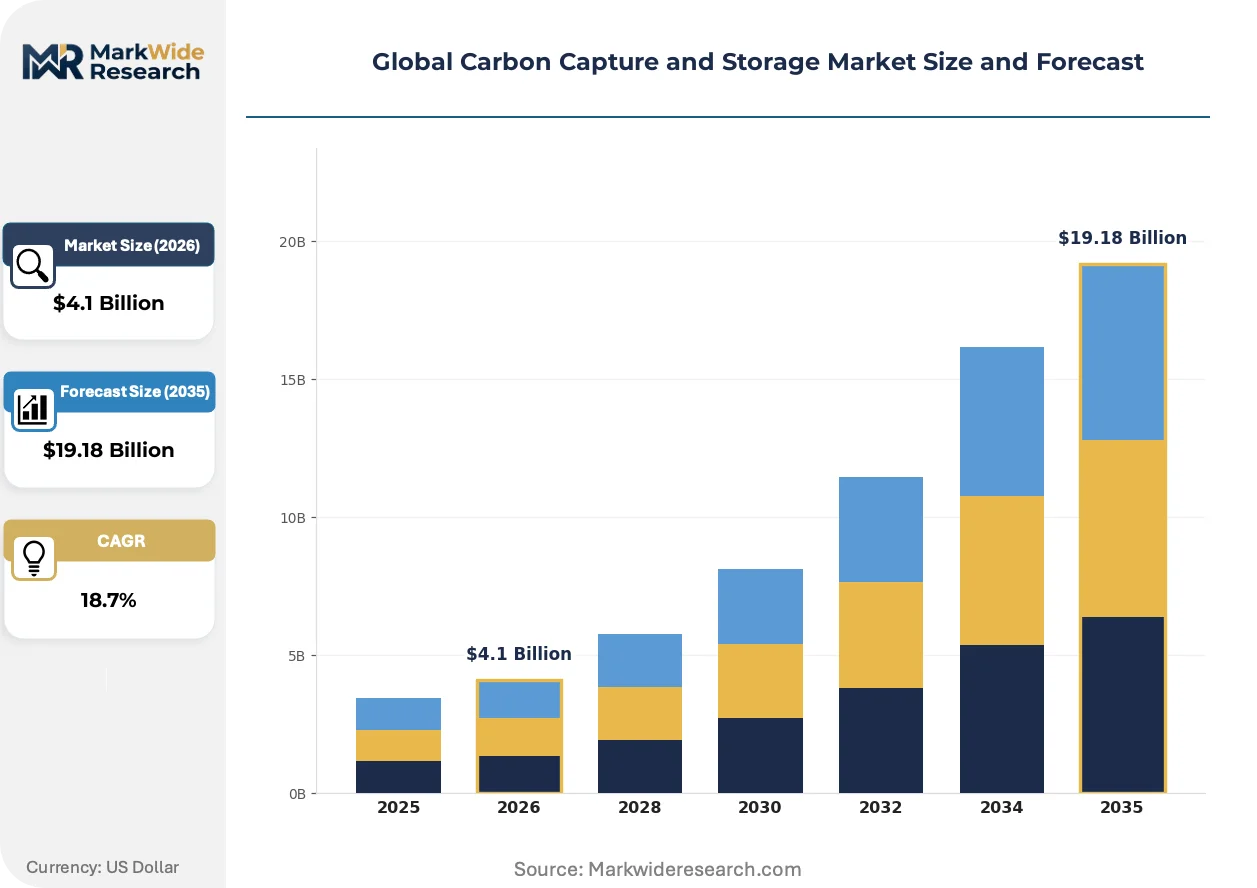
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $19.18 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pre-Combustion Capture, Post-Combustion Capture, Oxy-Fuel Combustion, Chemical Looping Application: Power Generation, Cement Production, Steel Manufacturing, Refinery Operations, Waste-to-Energy Storage Medium: Saline Aquifers, Depleted Oil Reservoirs, Depleted Natural Gas Reservoirs, Unmineable Coal Seams End User: Energy Producers, Heavy Manufacturing, Petrochemical Companies, Waste Management Firms |
| Companies Covered | ExxonMobil Corporation, Shell plc, Equinor ASA, TotalEnergies SE, Linde plc, Fluor Corporation, Schlumberger Limited, Aker Solutions, Mitsubishi Heavy Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Capture and Storage Market Shifts & Advancements
Modular capture skid designs are compressing deployment cycles from years to months. Equipment manufacturers are standardizing containerized amine units that slot between existing flue stacks and power blocks without civil works.
Solid sorbent direct air capture is rewriting the economics of distributed carbon removal. Climeworks and Carbon Engineering competitors are deploying kiloton-scale units in Iceland and Texas that strip atmospheric CO2 using temperature-swing adsorption. Data center operators and aviation majors are signing offtake agreements for delivered carbon credits. The technology is enabling voluntary offset markets to scale beyond industrial point-source constraints.
The EU's Carbon Border Adjustment Mechanism is reshaping import competitiveness for carbon-intensive goods. Steel and cement imports into the European Union now face embedded emissions tariffs that mirror domestic ETS prices. Turkish, Ukrainian, and Indian exporters are accelerating capture retrofits to preserve market access. The mechanism is forcing non-EU producers to internalize carbon costs previously externalized through regulatory arbitrage.
Buyer concentration among utilities and oil majors is consolidating offtake negotiation power. Large-scale storage hub developers now face procurement teams that demand take-or-pay structures with price caps indexed to carbon credit futures. Engineering firms are responding with build-own-operate models that retain operational risk in exchange for long-term revenue certainty. The shift is most visible in the US Gulf Coast, where ExxonMobil and Occidental compete for industrial emitter commitments.
Global Carbon Capture and Storage Market Segmentation
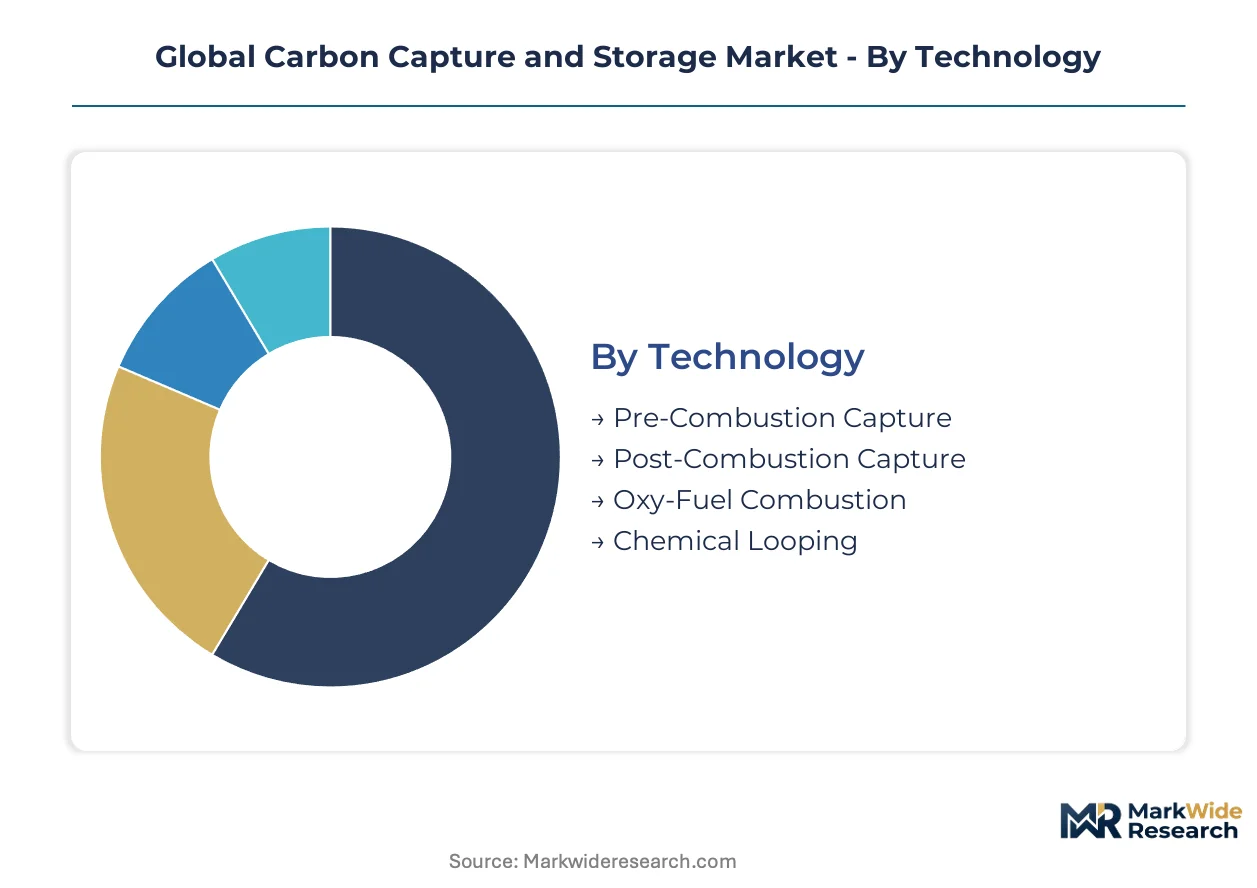
Technology selection determines retrofit feasibility and capital intensity across industrial sites. Application segmentation reveals which emissions sources face binding regulatory deadlines. Storage medium choice locks in containment geology and liability frameworks for decades.
Technology:
Upgrade cycles favor retrofittable systems over greenfield process redesigns, compressing deployment timelines for existing plant infrastructure.
- Post-Combustion Capture:Amine scrubbing systems strip CO2 from flue gases after fuel combustion, achieving capture rates above 90 percent. Cement producers in Germany and Poland deploy these retrofits under EU ETS compliance deadlines without rebuilding kiln infrastructure.
- Pre-Combustion Capture:Fuel gasification combined with water-gas shift reactions extracts carbon before combustion occurs. Integrated gasification combined cycle plants in the United States leverage this approach for blue hydrogen production under Inflation Reduction Act incentives.
- Oxy-Fuel Combustion:Pure oxygen combustion generates concentrated CO2 streams requiring minimal post-processing.
- Chemical Looping:Metal oxide carriers transport oxygen to fuel without direct air contact, eliminating nitrogen dilution.
Volume placements concentrate in Post-Combustion Capture; the faster expansion belongs to Pre-Combustion Capture.
Application:
Cost tier segmentation separates capital-intensive continuous process industries from intermittent waste streams with divergent payback requirements.
- Cement Production:Rotary kiln emissions exceed 500 kilograms CO2 per ton of clinker, making capture essential for EU market access. Turkish and Ukrainian exporters accelerate retrofits to avoid Carbon Border Adjustment Mechanism tariffs.
- Steel Manufacturing:Blast furnace off-gases contain concentrated CO2 suitable for capture integration. Chinese provincial caps enforced by MEE push Shandong and Inner Mongolia operators toward retrofit commitments.
- Power Generation:Coal and gas turbine flue streams offer scale economies for centralized capture hubs.
- Refinery Operations:Hydrogen production units and fluid catalytic crackers generate process-specific CO2 streams.
- Waste-to-Energy:Municipal incineration facilities in Sweden and Denmark pursue landfill diversion credits through flue gas capture.
Volume placements concentrate in Cement Production; the steepest expansion trajectory belongs to Waste-to-Energy.
Storage Medium:
Application context dictates geology selection, with capacity depth and containment certification driving site viability assessments.
- Saline Aquifers:Deep sedimentary formations hold vast pore volumes with no hydrocarbon recovery value. Texas and Louisiana host the densest cluster of Class VI permitted projects, leveraging Gulf Coast pipeline networks for CO2 delivery.
- Depleted Oil Reservoirs:Mature fields offer proven caprock integrity and existing well infrastructure. Enhanced oil recovery operations in the Permian Basin integrate capture with residual production.
- Depleted Natural Gas Reservoirs:High-permeability sandstone and carbonate formations provide established containment demonstration.
- Unmineable Coal Seams:Deep or thin coal beds adsorb CO2 through chemisorption mechanisms, though capacity constraints limit scalability.
Volume placements concentrate in Saline Aquifers; the fastest capacity additions belong to Depleted Oil Reservoirs.
End User:
Customer type segmentation reflects divergent procurement power, with consolidated energy majors negotiating take-or-pay structures against fragmented municipal operators.
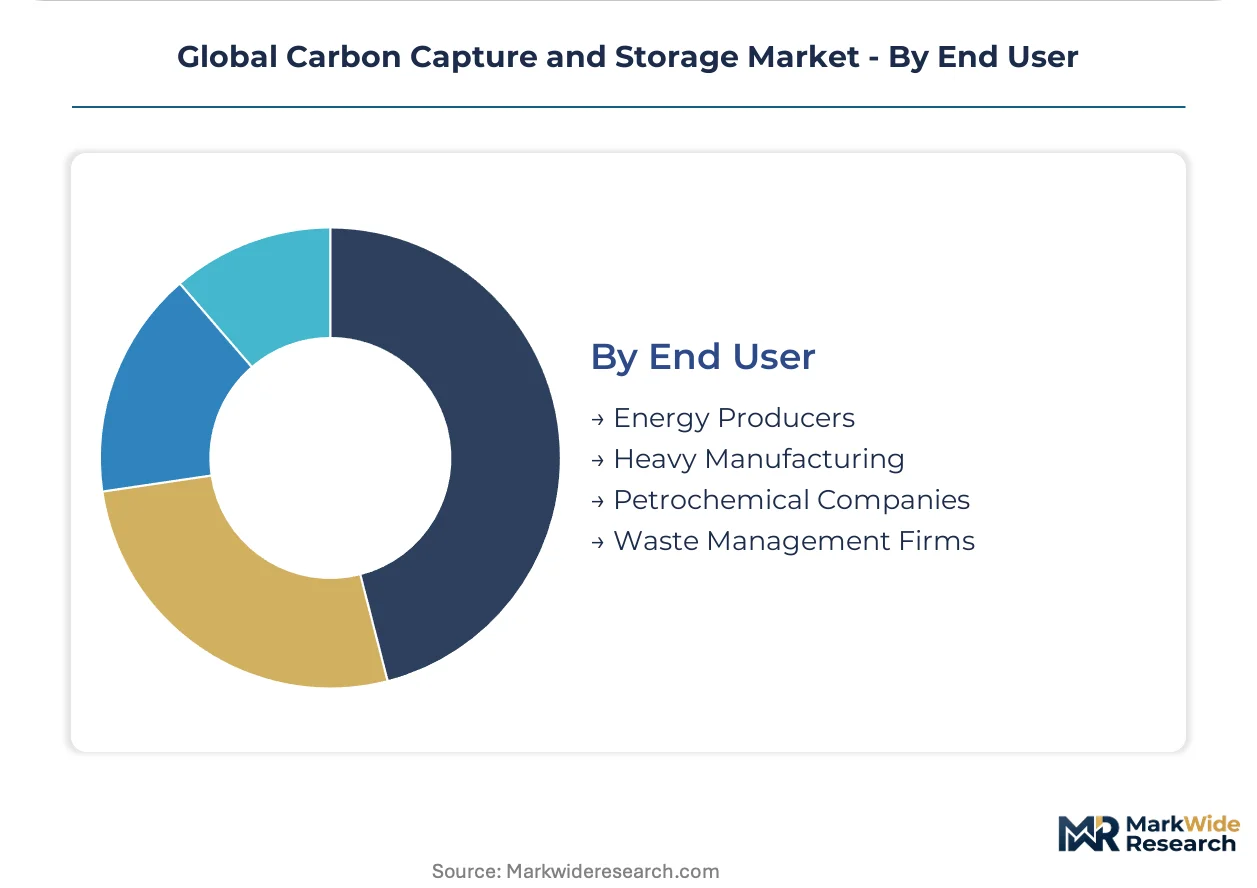
- Energy Producers:Utilities and independent power producers face decarbonization mandates across multiple jurisdictions. Integrated operators in the United States anchor large-scale hub developments with captive transport networks.
- Heavy Manufacturing:Steel and cement producers confront binding emissions caps with limited abatement alternatives outside capture retrofits.
- Petrochemical Companies:Steam crackers and aromatics complexes generate process emissions requiring point-source solutions.
- Waste Management Firms:Municipal and industrial waste operators seek compliance pathways for incineration emissions.
Volume placements concentrate in Energy Producers; the fastest contract expansion belongs to Heavy Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saline aquifer geology in Texas and Louisiana anchors North American storage capacity. North Sea formations drive European project clustering. Chinese provincial emissions caps reshape Asian deployment timelines.
United States
Texas and Louisiana host the densest cluster of Class VI permitted saline aquifer projects, leveraging Gulf Coast pipeline networks for CO2 delivery. The EPA's Underground Injection Control program governs well permitting, creating multi-year approval timelines that constrain project velocity. Houston anchors hub development as ExxonMobil and Occidental compete for industrial emitter commitments across the petrochemical corridor.
Norway
Equinor dominates the North Sea storage corridor with operational experience at Sleipner and Northern Lights. The country's dual carbon goals align with EU Green Deal emissions trading tightening. Stavanger anchors continental shelf project development as developers pursue cross-border transport treaties with Denmark and the Netherlands.
China
Provincial emissions caps enforced by the MEE compel coal-to-chemicals operators toward capture retrofits in Shandong and Inner Mongolia. The country's dual carbon goals reshape investment timelines for heavy manufacturing. Shandong Peninsula anchors regional deployment as cement and steel producers face binding abatement obligations.
Germany
Cement producers deploy post-combustion amine retrofits under EU ETS compliance deadlines without rebuilding kiln infrastructure. The EU Green Deal's Carbon Border Adjustment Mechanism accelerates import competitiveness pressures. The Ruhr region anchors industrial cluster development as steel and cement exporters seek to preserve market access.
United Kingdom
Steel manufacturing and power generation drive demand for integrated carbon management offerings spanning capture engineering to permanent sequestration. The EU-UK Trade and Cooperation Agreement shapes cross-border CO2 transport liability frameworks. Teesside anchors hub development as operators pursue saline aquifer storage in the southern North Sea.
Global Carbon Capture and Storage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular capture speed and retrofit specialization. The market splits between pipeline-integrated majors with captive transport networks and engineering specialists competing on deployment velocity. Three archetypes dominate: Gulf Coast hub developers with saline aquifer access, North Sea corridor operators with containment certification, and modular skid manufacturers compressing installation cycles. Competitive moves center on build-own-operate contracting and pre-certified geological formation partnerships.
Within the integrated majors tier, ExxonMobil Corporation anchors Gulf Coast hub development through pipeline network control, while Equinor ASA exemplifies North Sea corridor dominance through operational storage experience. Shell plc occupies a position spanning capture engineering to permanent sequestration. These three represent distinct geographic anchoring strategies: US Gulf saline aquifer concentration, Norwegian continental shelf expertise, and integrated carbon management portfolio breadth.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Equinor ASA |
| TotalEnergies SE |
| Linde plc |
| Fluor Corporation |
| Schlumberger Limited |
| Aker Solutions |
| Mitsubishi Heavy Industries, Ltd. |
| Others |
Supply & Pricing Matrix
Backward integration into saline aquifer ownership anchors both supply security and pricing power for Gulf Coast hub developers, locking in transport cost advantages that modular capture specialists cannot replicate without pipeline network control. This structural position allows integrated majors to bundle long-term offtake with containment certification, while independent engineering firms compete on deployment speed without geological asset backing.
Pricing Analysis
Warranty and long-term liability bundling separates premium project developers from unbundled equipment vendors, with containment guarantees and post-injection monitoring packaged into take-or-pay contracts. Price differentiation rests on certification depth—EPA Class VI permit status and reservoir engineering pedigree—versus modular skid speed with limited geological backing. Cost compression in the mid-market intensifies as pre-certified formation partnerships reduce due diligence overhead for buyers. Municipal waste-to-energy operators exhibit highest price sensitivity due to constrained capital budgets, while oil majors negotiating hub-scale commitments prioritize liability transfer over unit economics.
Supply Chain Analysis
Specialized reservoir engineering talent concentrates in Norway, the United Kingdom, and the United States, constraining containment certification capacity and stretching project timelines for formations lacking established plume migration data. Manufacturing draws from South Korean and Japanese fabrication yards for amine scrubbing vessels, German engineering consultancies for process design, and domestic US steel for pipeline infrastructure. Single-source vulnerability runs through Class VI permitting consultancy capacity, where EPA-approved assessors remain limited. Distribution runs through captive CO2 pipeline networks on the US Gulf Coast, with rail and truck alternatives penalizing Rocky Mountain and Midwest project economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained geological certification capacity props pricing for pre-qualified storage formations, as Class VI permitting bottlenecks and reservoir engineering talent scarcity limit viable project velocity regardless of capture technology cost curves.
For Market Incumbents: Anchor hub economics through exclusive saline aquifer lease arrangements in Texas and Louisiana, preempting competitor access to formations with established containment data. Deepen backward integration into CO2 transport pipeline ownership to lock in offtake pricing power against modular capture entrants lacking delivery infrastructure. Prioritize build-own-operate contracting models that internalize long-term liability, differentiating from equipment vendors exposed to warranty duration compression. For New Entrants and Emerging Players: The price-point gap between integrated hub developers and modular retrofit specialists opens white-space in municipal waste-to-energy applications, where landfill diversion credit values support premium capture economics without pipeline network dependence. Target Swedish, Danish, and Dutch incineration facilities facing binding emissions obligations under EU Green Deal tightening. Pursue membrane-cryogenic hybrid system specialization for natural gas processing and bioethanol facilities with variable CO2 concentrations, where incumbent amine scrubbing expertise transfers poorly. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by pipeline-integrated majors seeking geological certification assets, with valuation premia attaching to Class VI permit progress and reservoir engineering team depth. Long-term viability hinges on regulatory harmonization between national storage liability frameworks and cross-border CO2 transport treaty ratification. Monitor London Protocol amendment status as inflection indicator for North Sea basin project scalability and Norwegian-Dutch-Danish corridor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Saline Aquifer Lease Consolidation | Exclusive formation access under EPA Class VI framework locks in competitor exclusion and pricing power. |
| Modular Capture Skid Standardization | Containerized amine unit deployment compresses installation cycles from years to months for cement retrofit deadlines. |
| Cross-Border Transport Treaty Advocacy | London Protocol ratification progress unlocks North Sea basin volume flows between Norway, Denmark, and Netherlands. |
| Reservoir Engineering Talent Acquisition | Containment certification capacity scarcity concentrates among Sleipner-experienced consultancies in Stavanger and Oslo. |
| Waste-to-Energy Flue Gas Capture Expansion | Swedish and Danish municipal operators seek landfill diversion credits through incineration retrofit commitments. |
Research Methodology
Multi-period observation of EPA Class VI permit issuance timelines, EU ETS price floor trajectories, and MEE provincial cap enforcement anchored the trend analysis, supplemented by interviews with carbon capture engineering directors, saline aquifer geologists, utility procurement officers, and EPC contractors. Secondary validation drew from EPA Underground Injection Control databases, EU emissions trading registry disclosures, IEA carbon capture project tracking, and FERC pipeline infrastructure filings. Bottom-up project pipeline enumeration triangulated against top-down market sizing across technology, application, storage medium, and end user segmentation dimensions.
Segment-weighting approaches distributed value and volume estimates across post-combustion, pre-combustion, and oxy-fuel capture technologies; cement, steel, power, refinery, and waste-to-energy applications; saline aquifer, depleted oil reservoir, and depleted gas reservoir storage media; and energy producer, heavy manufacturing, petrochemical, and waste management end user categories. CAGRs were derived from fitted growth curves applied to announced project capacities and regulatory deadline impacts, incorporating Inflation Reduction Act credit value, EU Carbon Border Adjustment Mechanism tariff exposure, and China dual carbon goal enforcement as industry-specific demand drivers.
Inputs from EPA, EEA, and MEE regulatory filings were available through the study window; gaps in proprietary reservoir containment data and pre-commercial membrane-cryogenic hybrid performance introduce uncertainty bands around cost curve assumptions. Forecasts reflect documented permitting timeline assumptions, carbon credit price trajectories, and technology deployment schedules. Material deviation in Class VI approval velocity, London Protocol ratification progress, or EU ETS price floor adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Wheeled Bins Market
Environment & Sustainability
Quality Monitoring Sensor for Water Market
Environment & Sustainability
Water Trading Market
Environment & Sustainability
UAE Industrial Waste Management Market
Environment & Sustainability
Zero Liquid Discharge Market
Environment & Sustainability
Shower Water Filters Market
Environment & Sustainability
Rare Earth Recycling Market
Environment & Sustainability
Smart Water Network Market
Environment & Sustainability
Extended Producer Responsibility (EPR) Advisory Services Market
Environment & Sustainability
North America Trash Bags Market
Environment & Sustainability
Smart Waste Management Market
Environment & Sustainability
India Bio-Medical Waste Management Market
Environment & Sustainability
Medical Waste Management Equipment Market
Environment & Sustainability
Closed-Loop Recycling Programs for Automotive Hoses Market
Environment & Sustainability
Solar Frames Market
Environment & Sustainability
Hazardous Waste Management Market