
 Medical Waste Management Equipment Market | 2026-2036
Medical Waste Management Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Waste Management Equipment Market Outlook
The shift from outsourced collection to in-house on-site sterilization is broadening equipment procurement across mid-sized hospital networks. Stericycle leverages its national service footprint to compete for integrated contracts. Daniels Health differentiates through reusable container systems that reduce disposable plastic volumes. Republic Services anchors its position with large-scale incineration and autoclave infrastructure serving metropolitan health systems.
Medical waste management equipment encompasses mechanical, thermal, and chemical systems engineered to neutralize biohazardous materials through steam sterilization, combustion, or enzymatic degradation to achieve log-6 pathogen reduction. Autoclaves dominate installed capacity due to proven efficacy against bacterial spores and lower operational emissions versus incinerators. Chemical treatment systems represent the fastest-growing product category as laboratories and clinics seek compact, low-energy alternatives to thermal processing. Small-scale and medium-scale capacity segments capture expanding margin pools as point-of-care facilities prioritize decentralized waste reduction over centralized haulage.
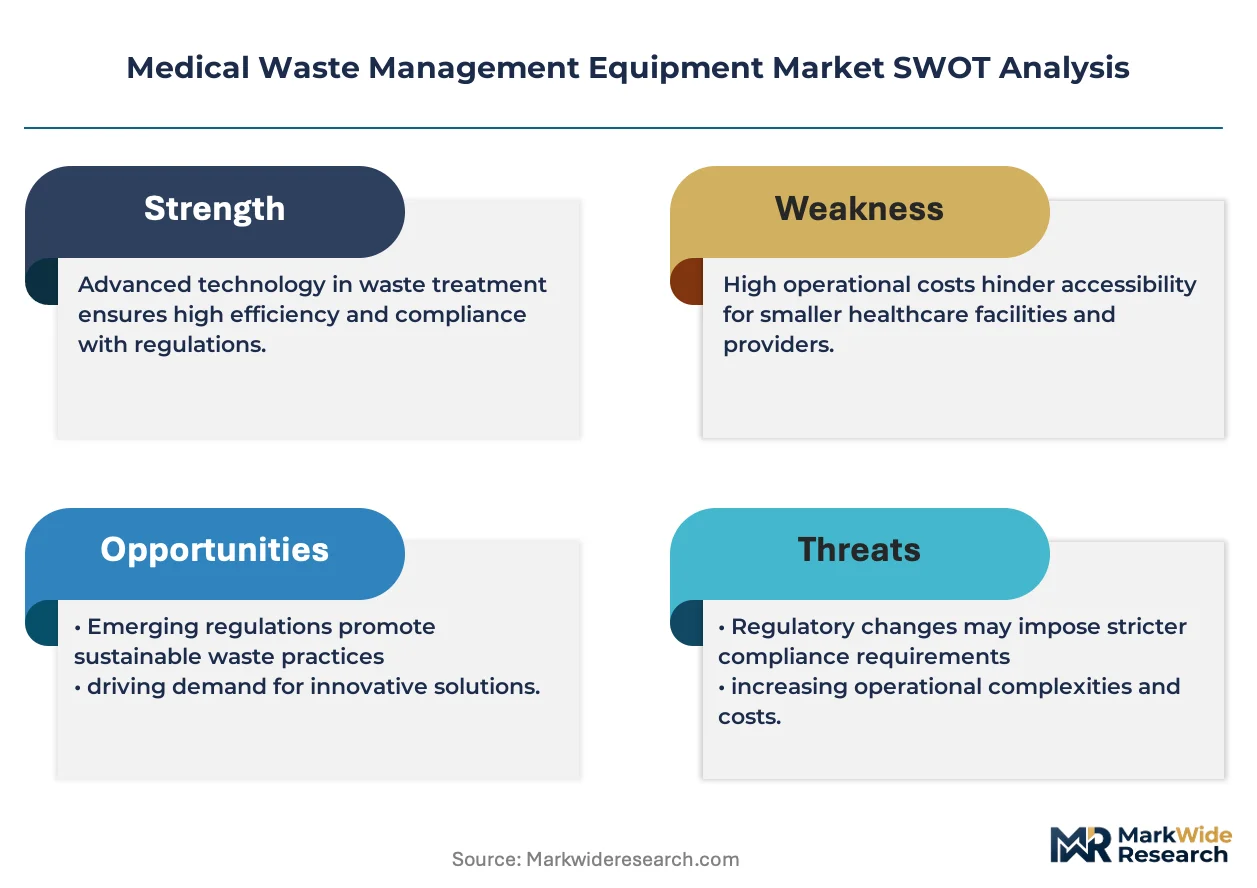
EPA emissions standards and OSHA bloodborne pathogen regulations mandate treatment verification and worker exposure limits, directly shaping autoclave validation protocols and chemical system dosing precision. EU MDR traceability requirements and REACH chemical safety frameworks extend compliance burdens to equipment material selection and disinfection byproduct documentation. Stakeholders must monitor evolving state-level pharmaceutical waste rules and carbon accounting disclosures that could reclassify preferred treatment technologies.
Market Dynamics
Hospital procurement departments are accelerating capital equipment replacement cycles to satisfy EPA emissions verification and OSHA bloodborne pathogen documentation mandates, compressing vendor sales timelines and expanding validation service attach rates.
Growth Catalysts
- EPA emissions mandates:Federal standards for dioxin and mercury output from incinerators force healthcare facilities toward steam sterilization and chemical treatment platforms with certified emission controls.
- Point-of-care expansion:Ambulatory surgical centers and dialysis clinics are installing compact autoclaves to eliminate third-party haulage costs and reduce liability exposure from transport-related spills.
- EU MDR traceability:European medical device regulation waste documentation requirements drive demand for treatment systems with integrated data logging and barcode tracking capabilities.
Market Restraints
- Stainless steel input volatility:Pressure vessel fabrication depends on nickel and chromium supply concentrated in Indonesian and South African mining operations, creating margin pressure for autoclave manufacturers.
- Incinerator permitting friction:Local air quality districts in California, Texas, and New York impose multi-year approval timelines for new thermal treatment capacity, constraining fleet expansion.
- Chemical treatment residue limits:EPA RCRA hazardous waste classifications for spent disinfectant solutions create downstream disposal costs that offset capital savings from low-temperature systems.
Strategic Opportunities
- Japan's aging healthcare infrastructure:METI hospital modernization subsidies support replacement of 1980s-era incinerators with automated autoclave systems featuring remote monitoring.
- Enzymatic-chemical hybrid platforms:Convergence of biological catalysts with precision dosing electronics enables log-6 reduction at ambient temperatures for pharmaceutical manufacturing waste streams.
- India's Ayushman Bharat expansion:Government health insurance scale-up creates demand for decentralized treatment units at tier-2 and tier-3 city hospitals lacking centralized waste infrastructure.
Industry Challenges
- Validation engineering scarcity:FDA 510(k) and EPA emission certification documentation requires specialized biostatisticians and mechanical engineers in short supply across Midwest manufacturing regions.
- Legacy system integration:Hospital IT departments struggle to embed new treatment equipment data streams into existing electronic health record and supply chain management platforms without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Waste Management Equipment Market |
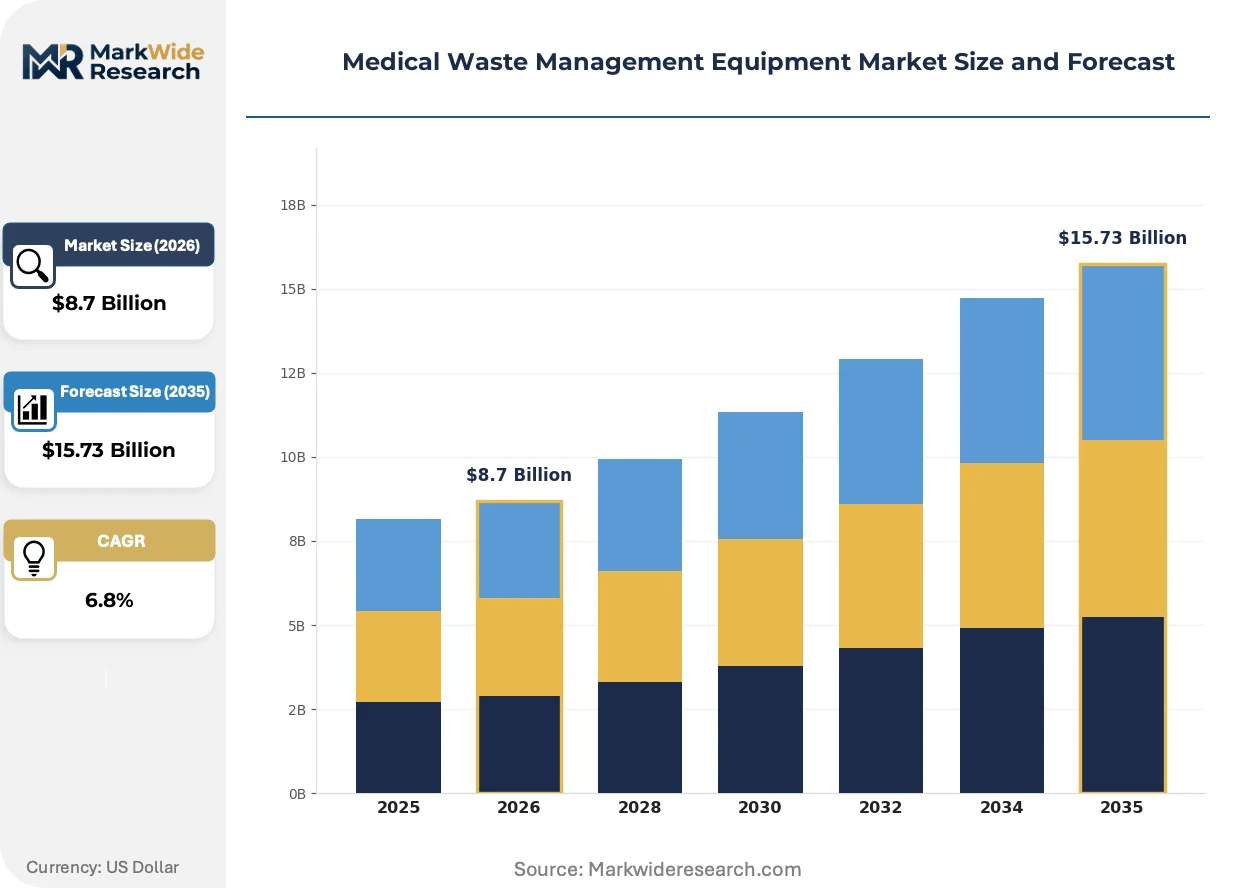
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autoclaves, Shredders, Incinerators, Chemical Treatment Systems End User: Hospitals, Clinics, Laboratories, Industrial Waste Generators Technology: Steam Sterilization, Microwave Treatment, Mechanical Processing, Chemical Disinfection Capacity: Small Scale, Medium Scale, Large Scale, On-Demand Solutions |
| Companies Covered | Republic Services, SUEZ, Stericycle, Daniels Health, REMONDIS SE & Co. KGaA, Clean Harbors, Waste Management, Sharps Compliance, Veolia Environmental Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Waste Management Equipment Market Strategic Shifts
Equipment manufacturers are embedding sensor arrays and cloud connectivity into treatment systems to transform capital sales into recurring revenue through predictive maintenance and compliance-as-a-service offerings.
Radio-frequency identification waste tracking is consolidating material flow visibility across hospital networks. RFID-tagged containers transmit fill levels, location, and treatment status to centralized dashboards. Large integrated delivery networks in Germany and the United States are mandating RFID compatibility in procurement specifications. This technology is consolidating vendor selection criteria around data interoperability rather than standalone mechanical performance.
REACH chemical safety frameworks in Europe are restricting persistent organic pollutants in disinfection byproducts. ECHA substance evaluation programs now require equipment manufacturers to document degradation pathway completeness for enzymatic and oxidative treatment chemistries. Laboratory and research facility segments in the Netherlands and Sweden are responding by specifying third-party-certified chemical systems with full material safety data sheet transparency.
Subscription-based equipment access is displacing outright purchase for mid-sized hospital networks. Under this model, manufacturers retain asset ownership and charge per-treated-kilogram fees bundled with maintenance and compliance documentation. Financially constrained health systems in Spain and Italy are adopting this structure to preserve capital for clinical technology investments while meeting EU MDR waste traceability obligations.
Medical Waste Management Equipment Market Segmentation
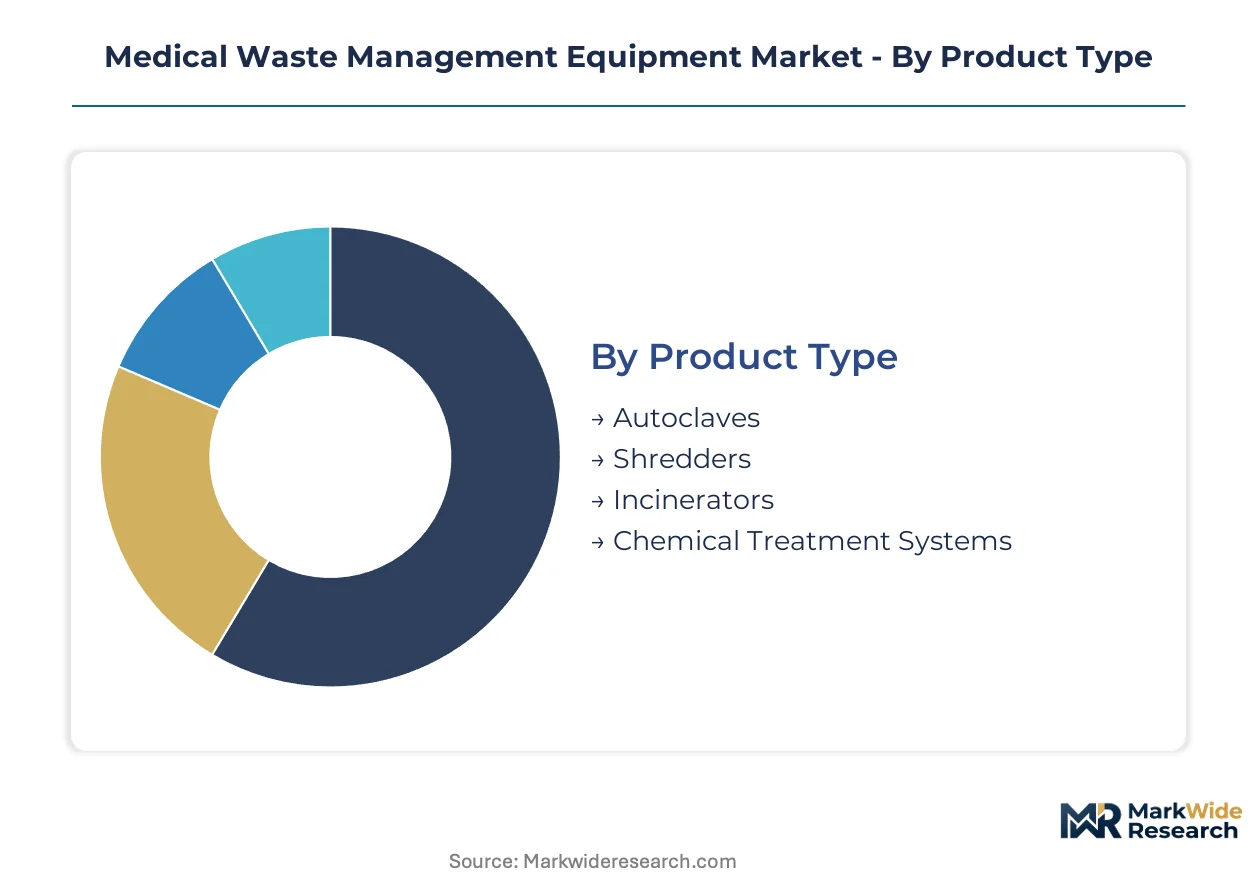
Equipment segmentation in medical waste management reflects divergent capital constraints, regulatory exposure, and treatment throughput requirements across healthcare settings. Technology selection varies sharply between centralized hospital systems and distributed point-of-care facilities.
Product Type:
Steam pressure vessel engineering defines the core specification axis for pathogen neutralization equipment.
- Autoclaves:Saturated steam systems operating at 121-134°C achieve log-6 spore reduction through pressure vessel exposure cycles. Demand concentrates in United States hospital networks replacing aging incinerators under EPA dioxin emission limits.
- Shredders:Mechanical size-reduction units with sealed containment pre-process sharps and anatomical waste prior to sterilization. German and Japanese procurement specifications now mandate integrated shredder-autoclave configurations for volume reduction efficiency.
- Incinerators:Thermal oxidation units with secondary combustion chambers for complete organic destruction. California and New York air quality districts impose multi-year permitting timelines that constrain new installations.
- Chemical Treatment Systems:Low-temperature oxidative or enzymatic platforms using peracetic acid or proprietary catalysts for heat-sensitive pharmaceutical residues.
Mature deployment sits with autoclaves. Newer deployment is concentrated in chemical treatment systems.
End User:
Facility scale determines throughput requirements and capital allocation priorities for waste neutralization infrastructure.
- Hospitals:Acute care institutions with 200+ beds operate centralized sterilization departments processing 500-2000 kg daily. United States integrated delivery networks are standardizing on RFID-tracked container systems with cloud-connected autoclave validation.
- Clinics:Ambulatory and primary care facilities under 50 beds deploy compact countertop units. India's tier-2 and tier-3 city expansion under Ayushman Bharat is driving procurement of small-scale steam sterilizers.
- Laboratories:Research and diagnostic facilities generate mixed chemical-biological waste streams requiring specialized neutralization protocols.
- Industrial Waste Generators:Pharmaceutical manufacturing and biotechnology production facilities produce high-volume concentrated biohazard streams.
Revenue concentration follows hospital procurement. Volume expansion is climbing the fastest in clinic installations.
Technology:
Energy input mechanism and thermal profile separate treatment platforms by operational cost structure and emission profile.
- Steam Sterilization:Conventional autoclave technology using saturated steam heat transfer with gravity or vacuum-assisted air removal. EPA and OSHA validation protocols in the United States mandate biological indicator testing and cycle documentation.
- Microwave Treatment:Electromagnetic radiation systems generating internal molecular friction for rapid uniform heating. EU MDR traceability requirements in Germany and Netherlands are accelerating adoption for rapid turnaround applications.
- Mechanical Processing:Physical size reduction and encapsulation without thermal or chemical pathogen kill.
- Chemical Disinfection:Oxidative or alkylating agent exposure at ambient temperature for heat-labile materials.
Steam sterilization retains installed base dominance. Microwave treatment is gaining share fastest in European laboratory segments.
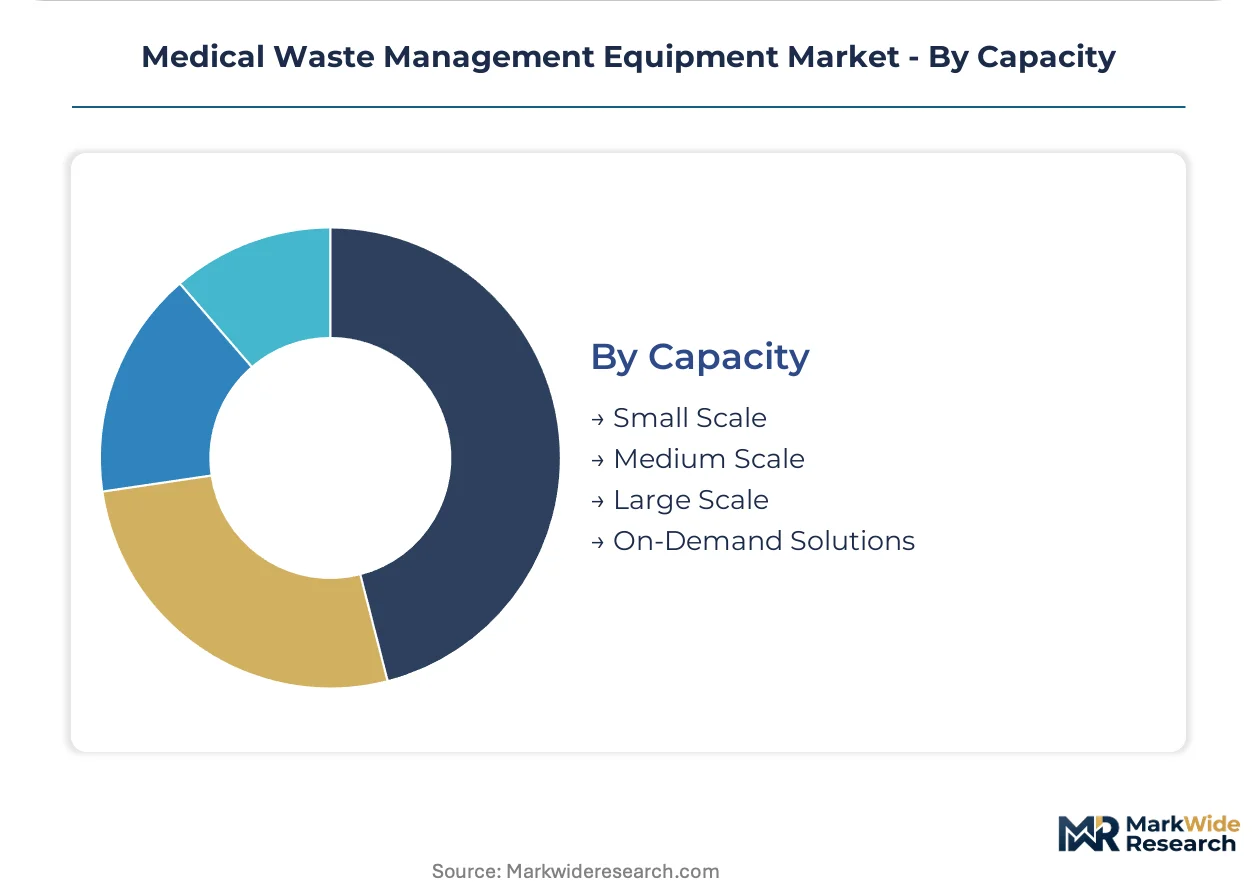
Capacity:
Throughput specification aligns with waste generation volume and centralized versus distributed processing economics.
- Small Scale:Units processing under 50 kg per cycle serve individual departments or standalone clinics. Japan's METI hospital modernization subsidies are replacing 1980s-era small incinerators with automated compact autoclaves.
- Medium Scale:50-200 kg capacity systems anchor mid-sized hospital central supply departments. United States regional health systems are consolidating procurement around standardized medium-scale platforms for fleet maintenance efficiency.
- Large Scale:Continuous-feed or batch systems exceeding 200 kg capacity serve metropolitan waste processing facilities.
- On-Demand Solutions:Modular containerized units for temporary or surge capacity deployment.
Capital deployment concentrates in medium scale. Margin expansion is steepest in small scale point-of-care installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel and chromium mining in Indonesia and South Africa anchors autoclave manufacturing costs, while stainless steel fabrication clusters in Germany and Japan supply pressure vessel components to healthcare systems worldwide.
United States
Integrated delivery networks in Texas and California are consolidating procurement around RFID-tracked container systems. EPA emissions verification and OSHA bloodborne pathogen documentation compress vendor sales timelines. The Southeast hospital corridor from Atlanta to Charlotte drives replacement demand for aging incinerators.
Germany
EU MDR traceability requirements accelerate adoption of microwave treatment systems in Frankfurt and Munich laboratory clusters. REACH chemical safety frameworks restrict persistent organic pollutants in disinfection byproducts. The Ruhr industrial basin hosts specialized validation engineering services for autoclave certification.
Japan
METI hospital modernization subsidies support replacement of 1980s-era incinerators with automated autoclave systems. Kanto region healthcare networks prioritize compact units with remote monitoring capabilities. Osaka pharmaceutical manufacturing corridors demand enzymatic-chemical hybrid platforms for heat-sensitive residues.
India
Ayushman Bharat expansion creates procurement pull for small-scale steam sterilizers in tier-2 and tier-3 cities. Maharashtra and Karnataka hospital networks lack centralized waste infrastructure. Delhi-NCR clinics deploy countertop autoclaves to eliminate third-party haulage costs and transport liability.
Medical Waste Management Equipment Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers respond to compressed replacement cycles in United States hospital networks. The vendor base organizes around three archetypes: national service integrators with hauling infrastructure, equipment specialists focused on reusable container systems, and waste management conglomerates with incineration scale. Strategic partnerships and technology licensing represent the dominant competitive vectors as mid-sized networks seek bundled compliance-as-a-service offerings.
Among North American service providers, Stericycle and Republic Services exemplify the scale-driven archetype, while Daniels Health occupies a position within the reusable container specialization tier. SUEZ and Veolia Environmental Services anchor the European environmental services segment. REMONDIS SE & Co. KGaA represents German engineering-intensive positioning. Clean Harbors and Waste Management sit within the diversified hazardous waste management tier. Sharps Compliance exemplifies the compliance-focused specialist model.
| Leading Market Players |
|---|
| Republic Services |
| SUEZ |
| Stericycle |
| Daniels Health |
| REMONDIS SE & Co. KGaA |
| Clean Harbors |
| Waste Management |
| Sharps Compliance |
| Veolia Environmental Services |
| Others |
Value Chain & Pricing Dynamics
Nickel and chromium price indices from the London Metal Exchange cascade through stainless steel pressure vessel fabrication costs, compressing margins for autoclave manufacturers and forcing tiered pricing stratification across premium-certified and standard-grade equipment lines.
Pricing Analysis
Extended warranty and validation-service bundling separates premium autoclave offerings from unbundled economy-tier chemical treatment systems. Price differentiation rests on EPA emission certification tier and RFID-traceability integration, with premium units commanding substantial service-attach premiums. Pricing pressure stems from nickel supply volatility concentrated in Indonesian mining operations. Mid-sized hospital networks exhibit highest price sensitivity, while large integrated delivery networks prioritize compliance-documentation reliability over capital cost.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and Japan's METI hospital modernization subsidies are reshaping sourcing patterns for pressure vessel components. Stainless steel fabrication draws from German and Japanese engineering clusters, with nickel and chromium supply anchored in Indonesian and South African mining operations. Single-source vulnerability in specialty valve and sensor procurement creates supply chain risk. Distribution runs through regional medical equipment distributors with service-technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical waste management equipment represents a consolidation play as EPA validation-engineering scarcity and compressed replacement cycles force sub-scale manufacturers toward strategic exits.
For Market Incumbents: Anchor market position through backward integration into stainless steel pressure vessel fabrication and captive validation-engineering capacity. Stericycle and Republic Services demonstrate scale advantages in bundled compliance-as-a-service offerings. Defensive moves should emphasize RFID-tracked container fleet control and cloud-connected predictive maintenance platforms to lock in integrated delivery network contracts. For New Entrants and Emerging Players: The price-point gap between premium autoclave systems and economy chemical-treatment units creates white-space opportunity in India's tier-2 and tier-3 city hospital networks under Ayushman Bharat expansion. Target small-scale steam sterilizer deployment with subscription-based per-treated-kilogram pricing to bypass capital-constrained procurement committees. Partner with regional distributors possessing existing biomedical engineering service footprints. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale autoclave specialists with EPA 510(k) certification pipelines in the United States Southeast hospital corridor. Long-term viability over the coming decade hinges on software-enabled recurring revenue transformation. Monitor state-level pharmaceutical waste rule evolution as inflection indicator for chemical-treatment system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Engineering Capacity Buildout | EPA 510(k) and emission certification documentation requires scarce biostatisticians and mechanical engineers. |
| RFID-Integrated Container Fleet Expansion | German and United States integrated delivery networks mandate RFID compatibility in procurement specifications. |
| Subscription-Based Equipment Access Model | Spanish and Italian health systems adopt per-treated-kilogram fees to preserve capital for clinical technology. |
| Enzymatic-Chemical Hybrid Platform Development | Osaka pharmaceutical corridors demand ambient-temperature log-6 reduction for heat-sensitive manufacturing residues. |
| Remote Monitoring Capability Integration | Japan's Kanto region healthcare networks prioritize compact autoclaves with cloud-connected predictive maintenance. |
Study Parameters
Independent corroboration across hospital procurement managers, biomedical engineering directors, GPO contracts managers, and autoclave validation specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from EPA emission certification databases, OSHA bloodborne pathogen regulatory filings, hospital procurement databases, and EU MDR traceability documentation. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure triangulation anchored market sizing.
Rate-of-change decomposition across product type, end-user facility scale, treatment technology, and capacity tier informed the analytical framework. Segmentation modeling incorporated autoclave versus chemical-treatment technology substitution patterns, point-of-care facility expansion trajectories, and regulatory compliance timeline acceleration. CAGRs derived from weighted average of historical replacement cycle compression and projected EPA enforcement intensity across the analysis window.
Inputs from EPA certification databases and EU MDR implementation timelines were available through the study window; gaps in real-time hospital capital expenditure tracking introduce uncertainty bands around near-term equipment procurement forecasts. Forecasts reflect documented assumptions regarding nickel price volatility and state-level pharmaceutical waste rule evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Nutrient Recycling Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Solid Waste Management Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Recycled Waste Management Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market