
 Wheeled Bins Market | 2026-2036
Wheeled Bins Market Size, Share, and Industry Trends Forecast 2026-2036
Wheeled Bins Market Analytics
Residential waste collection is decoupling from traditional manual handling methods as municipalities automate curbside pickup systems. SSI Schaefer leverages its European manufacturing footprint to supply standardized bin dimensions compatible with mechanical lift arms. Craemer Holding GmbH anchors its position through proprietary HDPE rotomolding expertise that extends product lifespan in harsh climates. Rehrig Pacific Company competes on channel control, maintaining direct distribution relationships with North American municipal procurement offices.
Wheeled bins are mobile waste containers mounted on castors, typically manufactured through rotational molding or injection molding of high-density polyethylene with wall thicknesses ranging from 3 to 8 millimeters to withstand mechanical lifting stresses. Their primary commercial purpose centers on standardized waste segregation at the point of generation, enabling efficient collection logistics and compliance with diversion mandates. Plastic material formulations dominate volume production due to corrosion resistance and weight advantages, though metal construction persists in industrial settings where fire safety codes restrict polymer use. Medium-capacity units lead residential adoption, while extra-large formats capture margin pools in construction debris applications where rental models generate recurring revenue.
EPA landfill diversion targets in the United States shape municipal procurement specifications, requiring bins with color-coded lids matching single-stream recycling protocols. EU REACH regulations restrict certain stabilizer additives in virgin and recycled plastics, compelling compound reformulation across European supply chains. The EU Green Deal's circular economy action plan further tightens material traceability requirements. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to localize production within regulated jurisdictions or absorb cross-border compliance costs.
Market Dynamics
Municipal automation programs are forcing bin standardization across collection fleets, locking suppliers into dimensional specifications that favor manufacturing scale over product differentiation.
Growth Catalysts
- Automated lift-arm compatibility:European sanitation departments are retrofitting mechanical collection vehicles with standardized grab mechanisms. This creates pull for uniform bin geometries.
- REACH additive restrictions:ECHA regulations on plastic stabilizers are accelerating reformulation toward post-consumer resin blends that meet durability thresholds without legacy compounds.
- Construction debris rental models:Contractors in Germany and France are adopting subscription-based container services for temporary waste streams, expanding addressable volume beyond municipal procurement.
Market Restraints
- HDPE resin volatility:Feedstock costs for high-density polyethylene fluctuate with naphtha and natural gas pricing, compressing margin predictability for rotomolders.
- Chinese mold fabrication dominance:Tooling for large-scale rotational molds concentrates in Zhejiang and Guangdong provinces, creating single-source vulnerability for European and North American producers.
- Metal substitution in industrial fire zones:Steel containers retain mandated presence in petrochemical and solvent-handling facilities where polymer ignition risk triggers code restrictions.
Strategic Opportunities
- Sensor-embedded smart bins:IoT fill-level monitors are converging with mechanical containers, enabling dynamic routing algorithms that cut collection fleet fuel consumption.
- India's Swachh Bharat infrastructure gaps:Secondary cities lack standardized container networks, creating first-mover advantage for suppliers establishing local molding partnerships.
- EU Green Deal circular procurement:Public tender scoring now weights recycled content percentage, rewarding compounders with verified post-consumer resin supply chains.
Industry Challenges
- Rotational molding skill scarcity:Experienced oven operators and mold technicians are aging out of European and North American workforces faster than apprenticeship programs replace them.
- Legacy fleet interoperability:Municipalities with mixed-age collection vehicles require backward-compatible bin interfaces, forcing suppliers to maintain multiple dimensional SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheeled Bins Market |
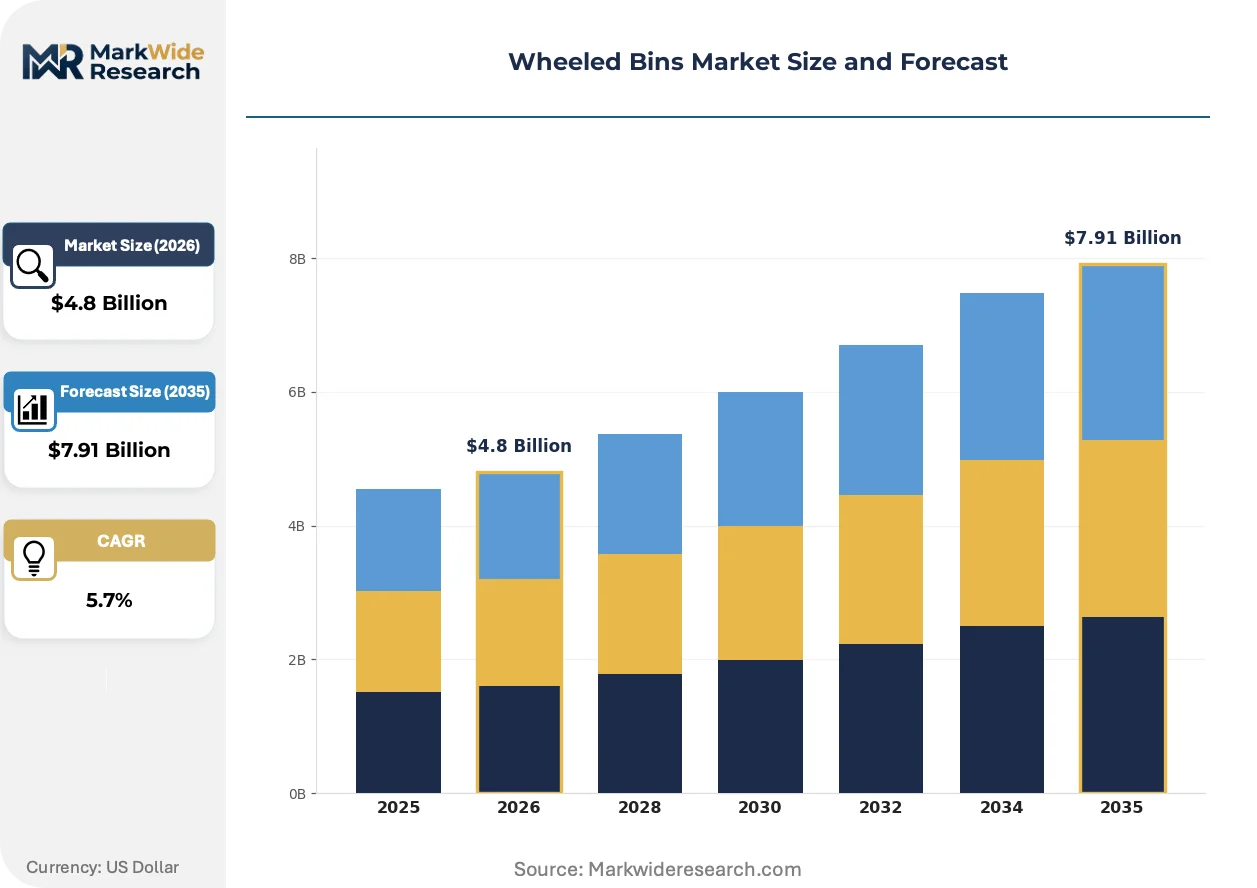
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
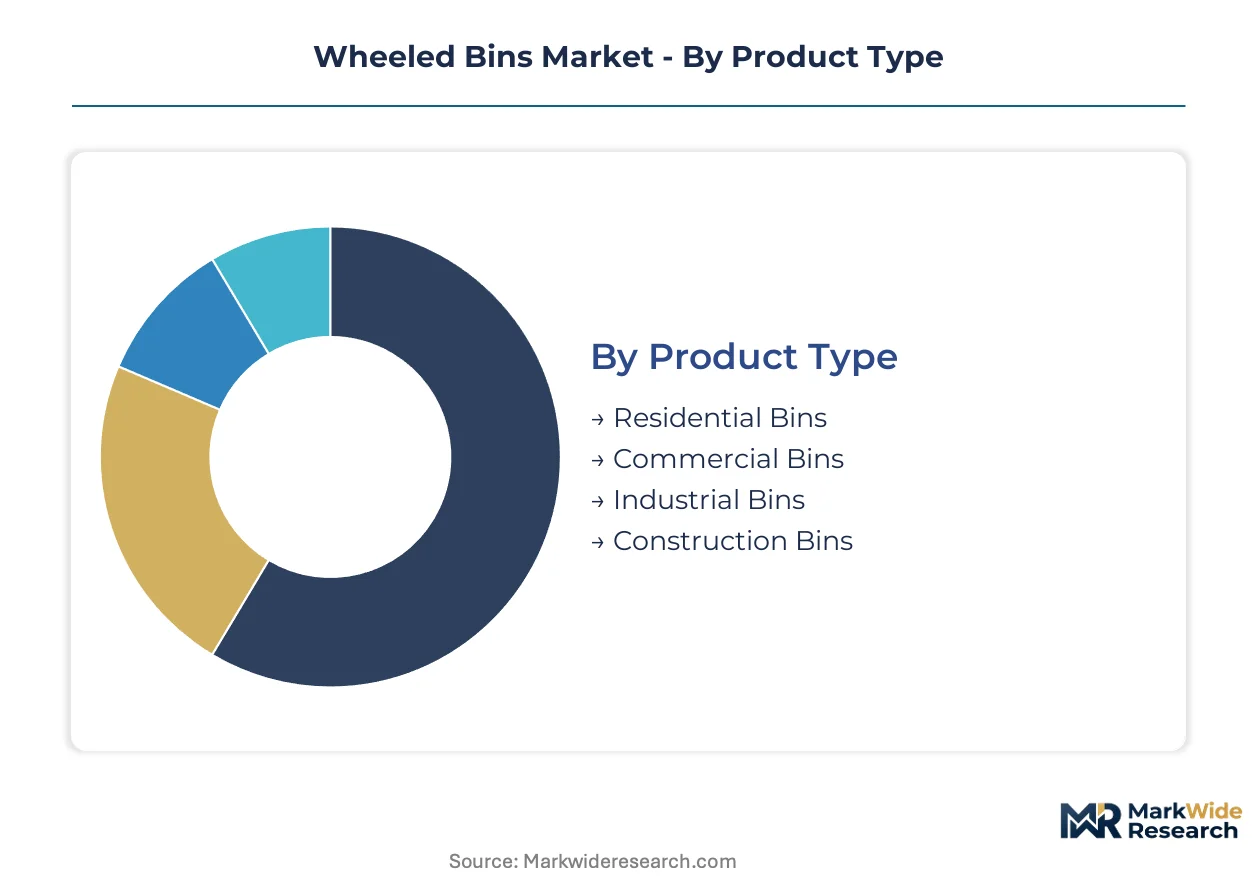
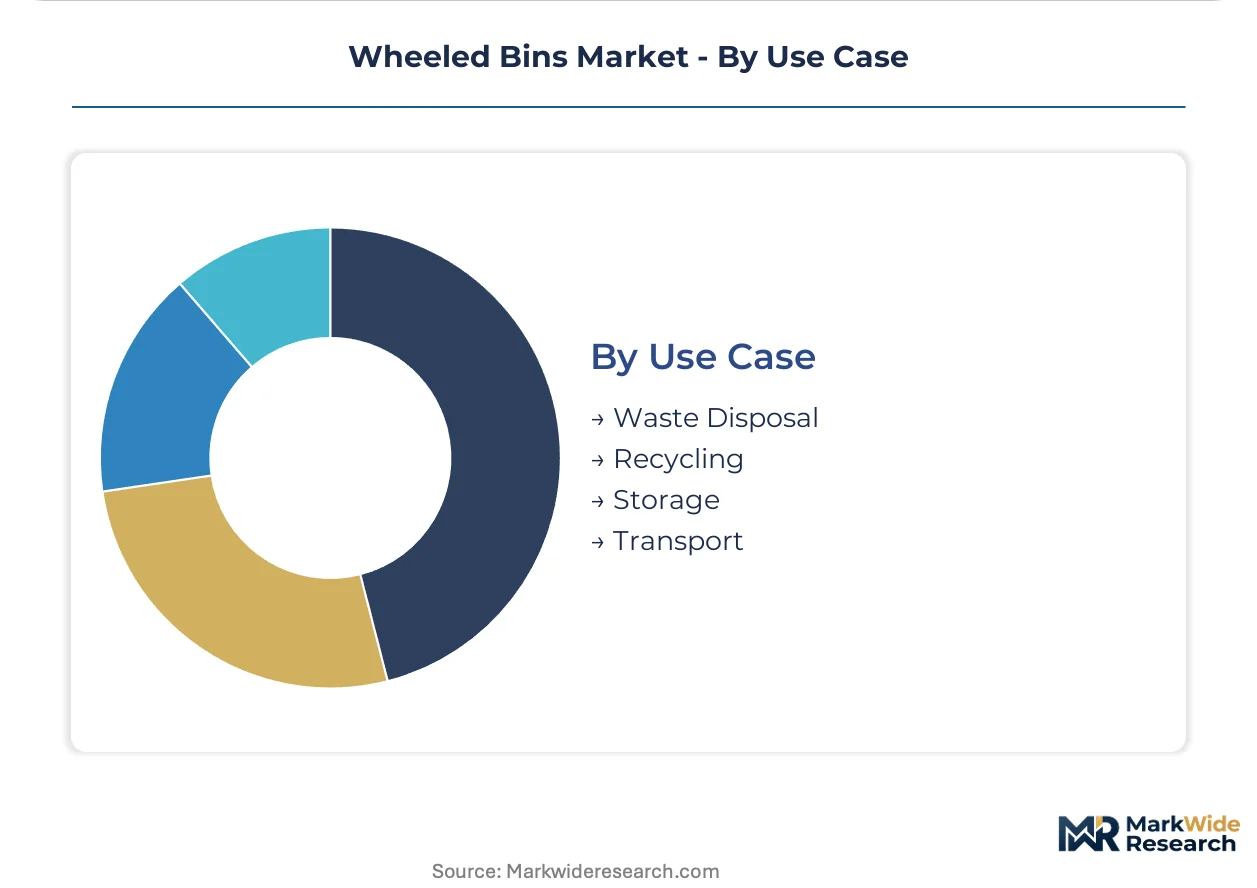
| Segmentation | Product Type: Residential Bins, Commercial Bins, Industrial Bins, Construction Bins Material: Plastic, Metal, Wood, Composite Capacity: Small, Medium, Large, Extra-Large Use Case: Waste Disposal, Recycling, Storage, Transport |
| Companies Covered | Toter LLC, Craemer Holding GmbH, SSI Schaefer, Otto Environmental Systems, IPL Plastics, SULO Global, Rubbermaid Commercial Products, Rehrig Pacific Company, ESE World B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheeled Bins Market Evolving Landscape
Material traceability systems and digital logistics integration are redefining how bin suppliers demonstrate compliance and capture value beyond commodity container sales.
RFID tagging and blockchain-based provenance tracking are decentralizing accountability for recycled content claims. German and French waste authorities are mandating chip-embedded bins to verify diversion metrics. This technology is decentralizing the audit function from centralized laboratories to distributed collection points, compressing certification timelines.
REACH Annex XVII restrictions on cadmium and lead stabilizers are forcing compounders toward calcium-zinc alternatives. ECHA enforcement actions against non-compliant imports are tightening border surveillance. Rotomolders serving Nordic markets are responding fastest, driven by national chemical agencies with aggressive substitution timelines.
Municipal procurement offices are consolidating vendor panels and unbundling maintenance contracts from initial supply agreements. French and Dutch regional authorities now separate container purchase from 10-year service provision. This pattern is most visible in Benelux markets where inter-municipal purchasing cooperatives aggregate bargaining power across dozens of jurisdictions.
Wheeled Bins Market Segmentation
Wheeled bin procurement specifications diverge sharply across end-use contexts, with certification burdens ranging from municipal interoperability standards to industrial fire safety codes. Suppliers must align material formulations and dimensional tolerances to distinct regulatory gateways rather than pursuing universal product platforms.
Product Type:
Residential bins carry CE marking obligations for mechanical lift-arm compatibility under EU machinery directives, while industrial variants face ATEX zone classifications and OSHA combustible dust standards in US manufacturing corridors.
- Residential Bins:HDPE rotomolded shells with reinforced wheel housings withstand automated collection cycles. German municipalities specify DIN 30700 geometries, locking suppliers into standardized lid hinge and grab-rail placements. Demand concentrates in European extended producer responsibility jurisdictions where uniform container specifications streamline sorting infrastructure.
- Commercial Bins:Front-load configurations with castor-mounted bases serve retail and food service waste streams. French commercial property codes mandate fire-resistant lid materials for enclosed loading docks, bifurcating procurement between polymer and metal variants.
- Industrial Bins:Steel construction dominates petrochemical facilities where NFPA 30 flammable liquid codes restrict polymer ignition risk.
- Construction Bins:Roll-off hook-lift frames with reinforced sidewalls capture debris rental revenue in German and French infrastructure projects.
Leading the category by volume: Residential Bins. Expanding most quickly: Construction Bins.
Material:
Raw material selection determines regulatory exposure across REACH additive restrictions and recycled content verification mandates.
- Plastic:Post-consumer HDPE formulations now face ECHA scrutiny on legacy stabilizer residues. Nordic national chemical agencies enforce fastest substitution timelines toward calcium-zinc alternatives.
- Metal:Galvanized steel retains mandated presence in solvent-handling zones where polymer ignition triggers code violations.
- Wood:Treated lumber variants satisfy organic waste diversion programs seeking biodegradable container options.
- Composite:Fiber-reinforced polymer blends bridge weight and durability requirements for specialty transport applications.
Plastic holds the dominant share. Composite materials are gaining share fastest in transport logistics.
Capacity:
Volume specifications map directly to collection fleet economics and storage footprint constraints.
- Medium:120-240 liter formats anchor European household waste streams, matching automated side-loader arm geometries. German cities specify 120-liter standard bins for residual waste and 240-liter for recyclables, creating paired procurement patterns.
- Extra-Large:1100-liter four-wheeled containers serve construction debris rental models in France and Germany. Subscription pricing for temporary waste streams generates recurring revenue beyond municipal procurement cycles.
- Small:Under-desk and countertop units capture office recycling protocols.
- Large:360-660 liter formats bridge commercial food service and light industrial demand.
Medium capacity generates the highest unit volume. Extra-Large formats command the steepest expansion trajectory in construction services.
Use Case:
Functional application determines interface requirements with downstream sorting and processing infrastructure.
- Waste Disposal:Residual waste streams require odor-sealing lid mechanisms and rodent-resistant rim profiles. EPA landfill diversion targets in US municipalities shape color-coded procurement for single-stream separation.
- Recycling:Color-matched lids to material streams—blue for paper, yellow for plastics, green for organics—enable source-segregated collection. EU Green Deal circular procurement scoring weights recycled content percentage in tender evaluations.
- Storage:Static containment without mobility features serves warehouse and retail backroom applications.
- Transport:Nestable designs with forklift pockets optimize reverse logistics for empty container repositioning.
Waste Disposal remains the volume anchor. Recycling applications show the fastest policy-driven expansion under diversion mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility zones in Germany and France concentrate procurement standardization, while India's Swachh Bharat Mission creates infrastructure gaps for container networks. Municipal automation programs and circular economy regulations are reshaping competitive positioning across distinct national frameworks.
Germany
DIN 30700 geometry mandates lock suppliers into standardized lid hinge and grab-rail placements for automated collection compatibility. The Packaging Act strengthens extended producer responsibility enforcement, requiring uniform container specifications for household waste streams. North Rhine-Westphalia hosts the densest concentration of rotomolding facilities serving municipal procurement cooperatives.
France
Regional inter-municipal purchasing cooperatives aggregate bargaining power across dozens of jurisdictions, unbundling maintenance from supply contracts. The country's national chemical regulator enforces aggressive substitution timelines for calcium-zinc stabilizer alternatives under REACH implementation. The Grand Est region anchors construction debris rental subscription models for infrastructure projects.
United States
EPA landfill diversion targets shape color-coded procurement matching single-stream recycling protocols across metropolitan sanitation departments. OSHA combustible dust standards restrict polymer use in petrochemical corridors, preserving steel container mandates. The Southeast manufacturing belt concentrates rotational molding capacity serving municipal retrofit programs.
India
Secondary cities lack standardized container networks, creating first-mover advantage for suppliers establishing local molding partnerships under Swachh Bharat infrastructure gaps. The Bureau of Indian Standards issues evolving specifications for waste segregation equipment. Maharashtra's urban agglomerations pilot smart bin deployments with fill-level monitoring for dynamic routing.
Netherlands
Benelux inter-municipal purchasing cooperatives drive vendor panel consolidation and 10-year service provision unbundling from initial container supply. EU Green Deal circular procurement scoring weights recycled content percentage in tender evaluations. The Randstad logistics cluster optimizes reverse logistics for nestable container repositioning systems.
Wheeled Bins Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with municipal procurement favoring established suppliers possessing verified resin supply chains while construction rental markets tolerate newer entrants. The vendor base organizes around three strategic archetypes: European rotomolding specialists with DIN-certified geometries, North American channel controllers maintaining direct municipal relationships, and Asian mold fabricators capturing tooling economics. Competitive moves concentrate on backward integration into post-consumer resin compounding and geographic licensing partnerships for localized production.
Among German fabricators, Craemer Holding GmbH and Otto Environmental Systems exemplify the rotomolding specialist archetype with proprietary HDPE expertise. SSI Schaefer occupies a position representing European manufacturing footprint scale for standardized bin dimensions. Rehrig Pacific Company anchors the North American channel control model through direct distribution relationships with municipal procurement offices.
| Leading Market Players |
|---|
| Toter LLC |
| Craemer Holding GmbH |
| SSI Schaefer |
| Otto Environmental Systems |
| IPL Plastics |
| SULO Global |
| Rubbermaid Commercial Products |
| Rehrig Pacific Company |
| ESE World B.V. |
| Others |
Value Network & Pricing Analysis
Naphtha-linked HDPE resin indices cascade through rotational molding supply chains into three distinct pricing tiers: premium DIN-certified geometries for German municipal fleets, mid-tier standardized bins for inter-municipal cooperatives, and economy-grade spot inventory for construction rental markets. Buyers absorbing feedstock volatility face compressed margins unless they lock long-term resin offtake or localize compounding operations.
Pricing Analysis
Lead-time premiums attach to short-cycle municipal retrofit orders where automated collection fleet deadlines compress procurement windows. Three-tier pricing structure separates premium DIN 30700-certified bins with verified post-consumer resin content from standard CE-marked units and economy-grade spot inventory for temporary construction deployments. Price differentiation hinges on certification grade and geographic delivery radius, with Nordic markets commanding premiums for fastest calcium-zinc stabilizer compliance. Cost compression in the economy tier is intensifying because Chinese mold fabrication concentrates tooling leverage with Zhejiang fabricators. Municipal procurement offices show lowest price sensitivity due to decade-long service bundling, while independent construction contractors negotiate aggressively on rental rates.
Supply Chain Analysis
Dual-sourcing requirements now dominate municipal procurement specifications, forcing buyers to qualify redundant rotomolding capacity across Germany and France before contract award. HDPE resin draws from naphtha crackers in Belgium, the Netherlands, and Saudi Arabia, while large-scale rotational mold tooling concentrates in Zhejiang and Guangdong provinces. Single-source vulnerability in Chinese mold fabrication creates tooling bottleneck risk for European and North American producers scaling standardized geometries. Distribution runs through inter-municipal purchasing cooperatives in Benelux and France, with direct distribution relationships anchoring North American municipal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as compounders pursue captive post-consumer resin supply to meet EU Green Deal circular procurement scoring and ECHA additive restrictions.
For Market Incumbents: Anticipate margin compression from REACH Annex XVII enforcement actions against non-compliant imports by securing verified calcium-zinc stabilizer supply chains and backward integration into post-consumer resin compounding. Defend municipal panel positions through 10-year service provision bundling that locks out spot-market competitors. Prioritize DIN 30700 geometry certification maintenance as automated fleet standardization hardens interface specifications. For New Entrants and Emerging Players: Enter via India's Swachh Bharat infrastructure gaps in secondary cities lacking standardized container networks, establishing local molding partnerships before incumbent European suppliers localize production. Target construction debris rental subscription models in French infrastructure corridors where temporary waste stream services generate recurring revenue beyond municipal procurement cycles. Lead with sensor-embedded smart bin offerings that enable dynamic routing algorithms for fuel-conscious fleet operators. For Investors and Strategic Acquirers: Distressed-cycle entries favor European rotomolding specialists with DIN-certified geometries and verified resin supply chains during periods of HDPE feedstock volatility. Long-term viability over the next decade hinges on circular economy compliance infrastructure and post-consumer resin traceability systems. Watch ECHA enforcement action intensity against cadmium and lead stabilizer residues as the inflection indicator for compounder consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Resin Compounding | Captive HDPE supply secures EU Green Deal tender scoring against REACH additive scrutiny. |
| Sensor-Embedded Smart Bin Development | IoT fill-level monitors enable dynamic routing algorithms that cut collection fleet fuel consumption. |
| Geographic Licensing Partnerships for Localized Production | India Swachh Bharat gaps reward first-movers establishing domestic molding capacity. |
| 10-Year Service Provision Unbundling | Benelux and French cooperatives now separate container purchase from long-term maintenance contracts. |
| Calcium-Zinc Stabilizer Formulation Transition | Nordic chemical agencies enforce fastest substitution timelines under REACH Annex XVII restrictions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with municipal procurement officers, rotomolding plant managers, resin compounder technical directors, and waste authority diversion specialists. ECHA enforcement databases, DIN standards documentation, EU Green Deal circular procurement guidelines, and national chemical agency substitution timelines provided triangulation points against bottom-up capacity surveys and top-down demand modeling.
Data-stream reconciliation across the analysis window weighted municipal automation program announcements, extended producer responsibility enforcement trajectories, and construction rental subscription adoption curves. Segmentation dimensions spanned product type, material formulation, capacity tier, and use case, with regional regulatory clusters capturing DIN 30700 mandates, REACH implementation variance, and EPA landfill diversion targets. CAGRs derived from resin price elasticity modeling and fleet replacement cycle analysis, incorporating mechanical lift-arm compatibility standards and post-consumer resin availability constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH additive bans or naphtha price spikes. Deviation in ECHA enforcement intensity or Chinese mold fabrication capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
Polyfluoroalkyl Substances (PFAS) Waste Management Market
Waste Management & Pollution Control
Municipal Solid Waste Incineration Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Metal Recycling Equipment Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
South American Waste Management Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Medical Waste Management Equipment Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
ASEAN Waste Management Market