
 Smart Waste Management Market | 2026-2036
Smart Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Waste Management Market Intelligence
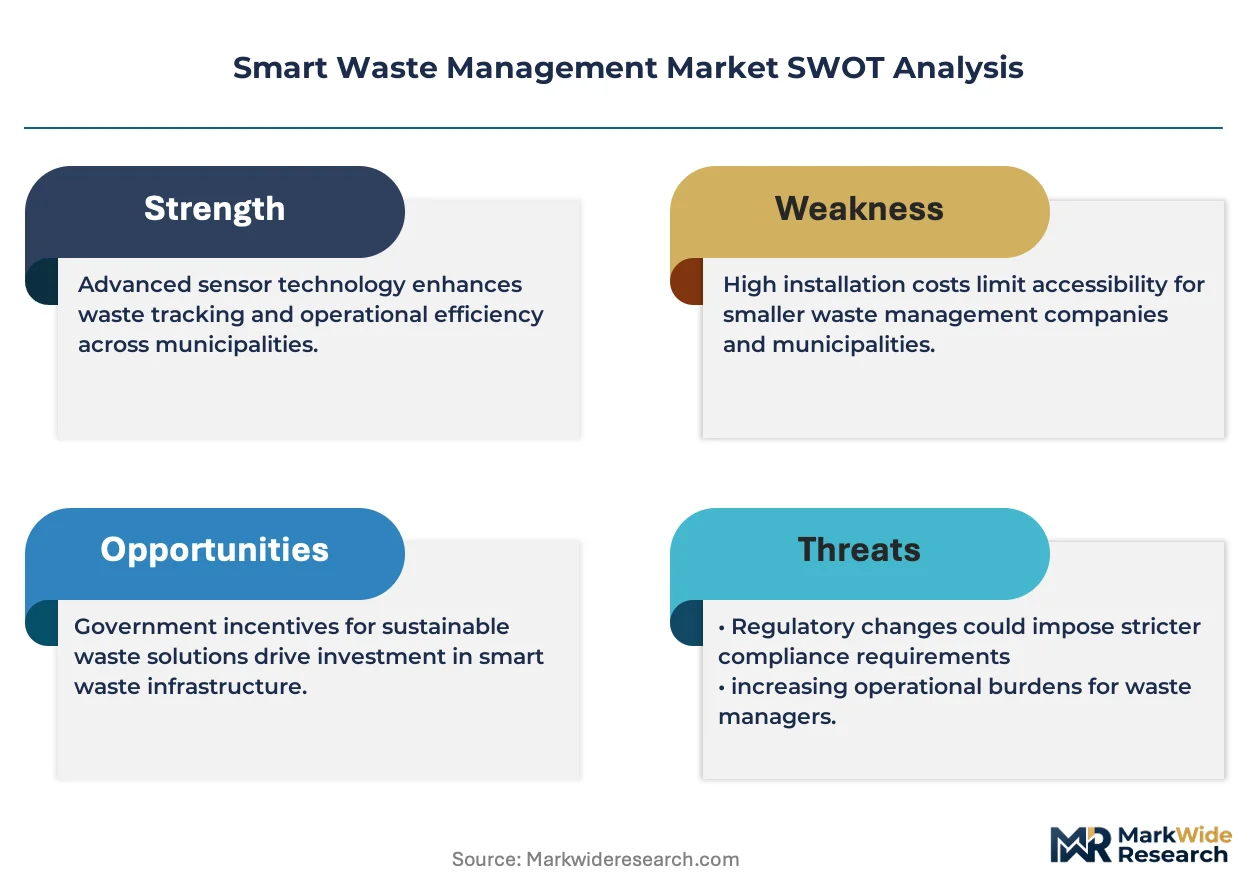
Subscription-based route optimization software is hardening into the core revenue layer for smart waste vendors, shifting municipal contracts from capital expenditure to recurring service models. Ecube Labs Co., Ltd. anchors its position through vertically integrated bin manufacturing and cloud platform delivery. Sensoneo, s.r.o. competes on RFID-enabled fill-level accuracy across European deployments. Cisco Systems, Inc. leverages networking infrastructure to dominate backhaul connectivity for sensor networks in North American cities.
Smart waste management deploys IoT sensors, embedded telemetry hardware, and cloud-native analytics to monitor container fill levels, composition, and location in real time, enabling dynamic dispatch of collection fleets rather than fixed-route scheduling. The hardware layer encompasses ultrasonic and weight-based sensors with IP67-rated enclosures operating on low-power wide-area networks. Sensor-based monitoring and route optimization software capture disproportionate R&D investment as municipalities prioritize measurable fuel savings and labor efficiency over standalone smart bin deployments. Data analytics platforms remain nascent in revenue contribution but concentrate margin pools through annual software licensing.
The EPA enforces landfill methane reporting thresholds that compel municipalities to quantify waste streams, while the EU Green Deal and F-Gas Regulation extend producer responsibility frameworks that require granular tracking of industrial byproducts and electronic scrap. ISO 14040 life-cycle assessment standards shape procurement specifications for recycling facilities seeking certified environmental claims. Stakeholders must weigh interoperability standards against vendor lock-in as procurement shifts toward integrated platform contracts spanning hardware, connectivity, and analytics.
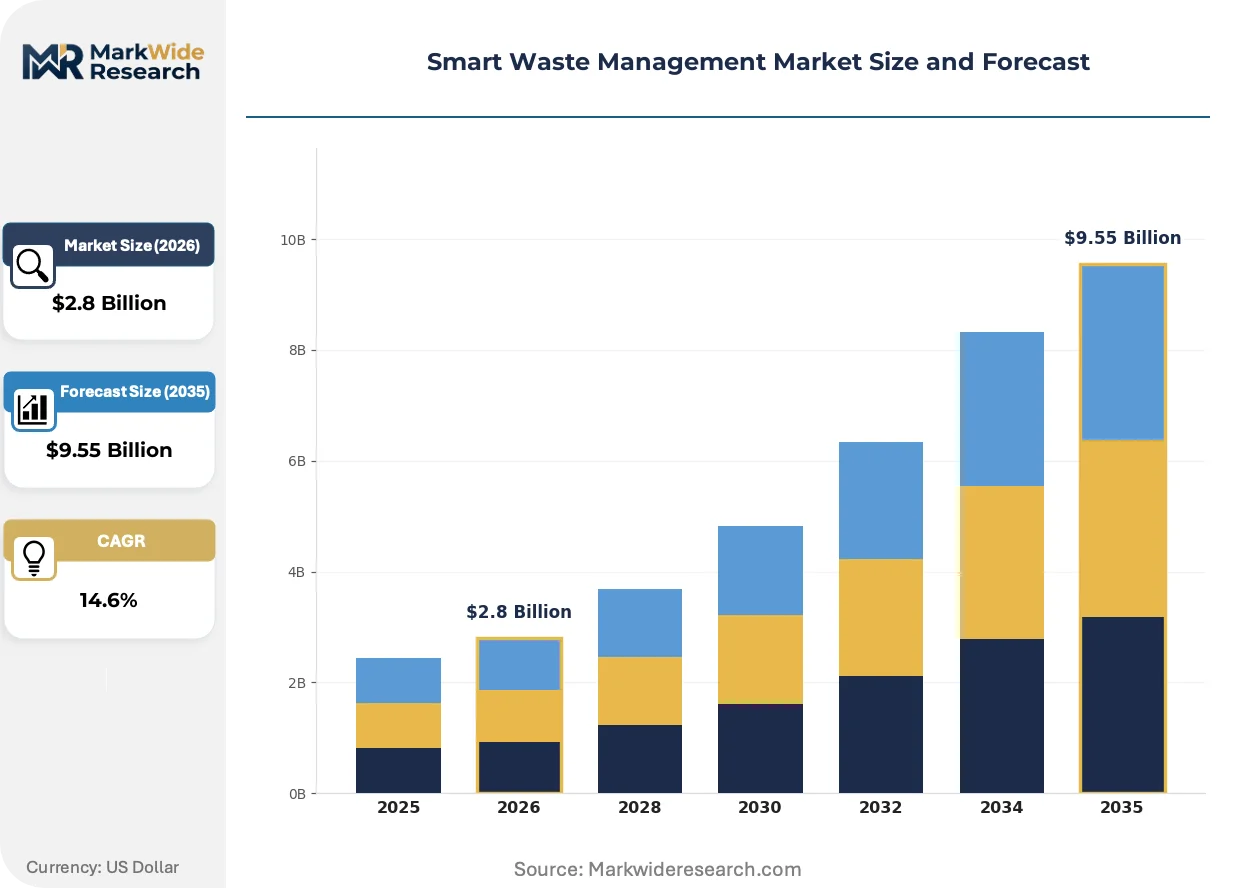
Market Dynamics
Municipal procurement departments are forcing a structural shift from capital equipment purchases to recurring SaaS contracts for route optimization, compressing vendor margins while extending customer lifetime value.
Growth Catalysts
- Landfill Diversion Mandates:The EPA's methane reporting thresholds compel US cities to deploy sensor networks that quantify waste streams in real time, creating procurement urgency for telemetry-enabled collection systems.
- LPWAN Infrastructure Rollouts:Germany's nationwide Narrowband-IoT coverage enables ultrasonic fill-level sensors to transmit data without proprietary gateway investments, lowering deployment barriers for mid-sized municipalities.
- Carbon Accounting Integration:ISO 14040 life-cycle assessment standards now require granular waste composition data, driving recycling facilities to specify smart bin deployments with embedded spectroscopy hardware.
Market Restraints
- Sensor Hardware Cost Concentration:IP67-rated ultrasonic modules rely on concentrated semiconductor foundry capacity in East Asia, exposing municipal budgets to input volatility and extended lead times.
- Interoperability Friction:The absence of unified data protocols between bin manufacturers and fleet management platforms forces cities into single-vendor lock-in, limiting competitive tendering.
- Cellular Backhaul Dependency:Smart waste networks require continuous connectivity; coverage gaps in rural Japan and mountainous German regions delay deployment outside urban cores.
Strategic Opportunities
- India's Smart Cities Mission:The PLI scheme for IoT hardware manufacturing creates localized production incentives, enabling vendors to bypass import duties on sensor assemblies for municipal tenders.
- Predictive Maintenance Convergence:Machine learning models applied to compaction motor vibration data are converging with existing fill-level monitoring, opening upsell revenue streams on installed hardware bases.
- Extended Producer Responsibility Expansion:The EU Green Deal's packaging waste directives mandate brand-level tracking of post-consumer materials, creating demand for smart bin networks at retail collection points.
Industry Challenges
- Data Science Talent Scarcity:Municipal waste departments lack personnel capable of interpreting route optimization analytics, forcing vendors to embed managed services that erode software margins.
- Legacy Fleet Integration:Diesel collection vehicles with 15-year replacement cycles require aftermarket telematics retrofits, complicating real-time dispatch synchronization with cloud-native platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Waste Management Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Smart Bins, Sensor-Based Monitoring, Automated Collection, Data Analytics Platforms, Route Optimization Software Technology: IoT Sensors, RFID, GPS Tracking, Cloud Computing, Machine Learning Algorithms Application: Municipal Solid Waste, Industrial Byproducts, Construction Debris, Electronic Scrap, Organic Waste End User: Local Governments, Waste Collection Services, Recycling Facilities, Industrial Complexes, Commercial Establishments |
| Companies Covered | Bigbelly, Inc., Ecube Labs Co., Ltd., International Business Machines Corporation (IBM), Sensoneo, s.r.o., Compology, Inc., Cisco Systems, Inc., Enevo, Inc., Rubicon Technologies, LLC, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Waste Management Market Strategic Shifts & Innovations
Edge computing architectures are migrating analytics from centralized clouds to sensor gateways, reducing latency for fill-level alerts while creating new hardware margin pools for vendors with embedded processing capabilities.
Computer vision modules mounted on collection vehicles are consolidating manual waste composition audits into automated stream analysis. Recycling facilities in the Netherlands and California are adopting these systems to verify contamination rates without labor-intensive sampling. The technology is consolidating quality control functions previously outsourced to third-party auditors into in-house operations.
The EU F-Gas Regulation's phasedown of hydrofluorocarbons is compelling refrigeration-dependent waste streams—particularly food and pharmaceutical discard—to adopt temperature-monitoring telemetry. Cold chain waste generators in France and Germany now specify connected containers that log thermal excursions for compliance documentation. This regulatory pressure is accelerating sensor deployment in segments previously served by passive insulation.
Municipal buyers are unbundling long-term service contracts into discrete software, hardware, and connectivity components. German cities now tender route optimization algorithms separately from bin supply, enabling benchmarking between specialist vendors. This disaggregation is most visible in North Rhine-Westphalia, where procurement frameworks mandate modular contracting to prevent vendor lock-in.
Smart Waste Management Market Segmentation
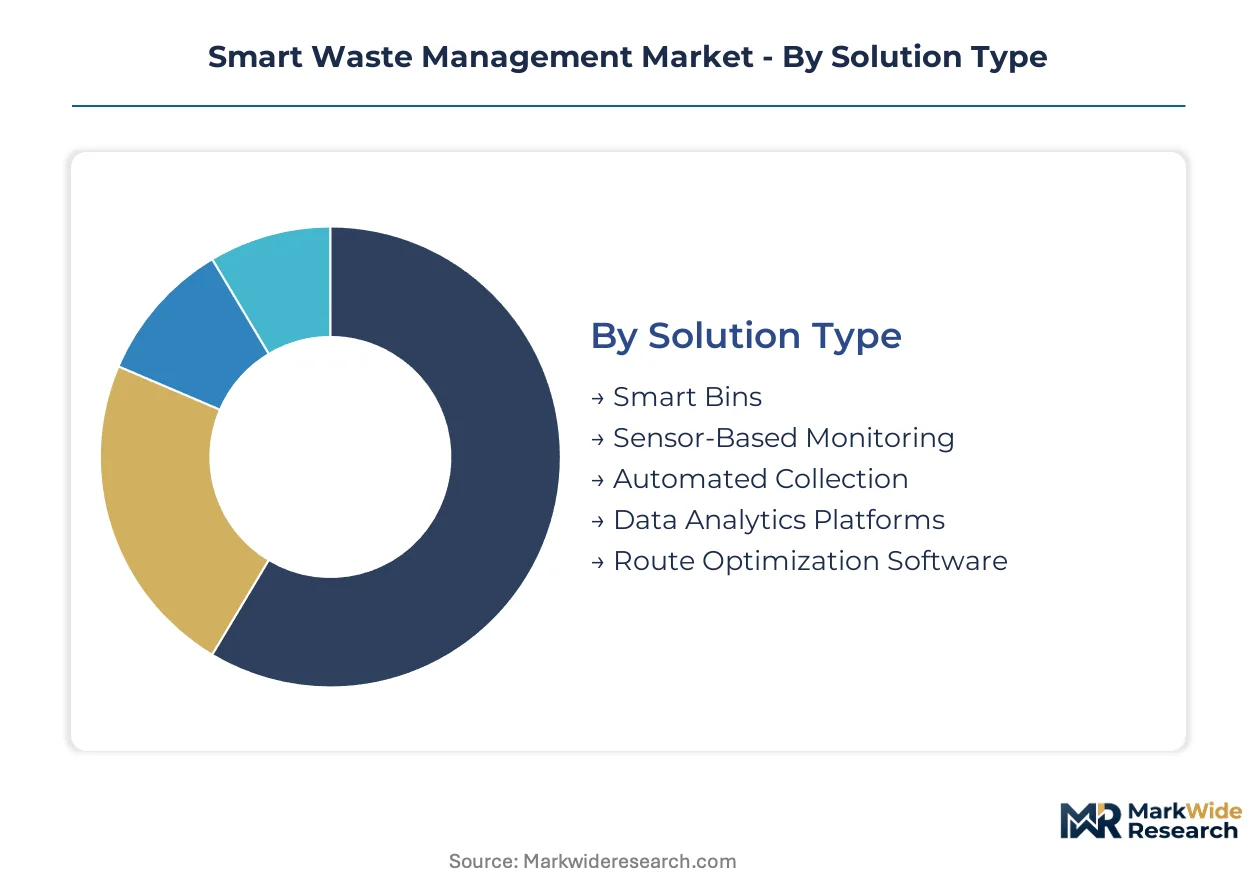
Smart waste management procurement patterns diverge sharply across solution architectures and user sophistication. Municipal buyers prioritize integrated platforms that bundle hardware with recurring analytics licenses, while industrial purchasers favor modular deployments targeting specific compliance mandates.
Solution Type:
Supply concentration in ultrasonic sensor manufacturing favors vendors with captive hardware production, compressing margins for pure-software competitors.
- Smart Bins:IP67-rated enclosures integrate compaction motors and fill-level telemetry. Demand clusters in German municipalities under landfill diversion mandates requiring real-time capacity monitoring.
- Sensor-Based Monitoring:Ultrasonic and weight-based modules transmit data over LPWAN networks. Japanese cities deploy these most aggressively where narrowband-IoT coverage enables gateway-free installations.
- Automated Collection:Side-load and front-load mechanization reduces crew requirements. Adoption lags in markets with legacy union contracts protecting manual labor roles.
- Data Analytics Platforms:Cloud-native dashboards visualize composition and routing efficiency. Recycling facilities in California specify these for ISO 14040 compliance documentation.
- Route Optimization Software:Dynamic dispatch algorithms replace static scheduling. Municipal SaaS contracts here capture the highest gross margins across the solution stack.
Today's leader: Route Optimization Software. Tomorrow's challenger: Data Analytics Platforms.
Technology:
Technology selection tracks end-user digital maturity, with cloud-native stacks penetrating municipal accounts while RFID dominates industrial traceability.
- IoT Sensors:Ultrasonic, thermal, and spectroscopic modules operate on sub-gigahertz networks. Semiconductor supply constraints from East Asian foundries extend lead times for IP67-rated units.
- RFID:Passive and active tags enable bin-level tracking without continuous power. European packaging waste directives mandate RFID for producer responsibility compliance.
- GPS Tracking:Fleet telematics synchronize vehicle location with fill-level alerts. Diesel fleet retrofits complicate real-time integration with legacy dispatch systems.
- Cloud Computing:Centralized data lakes aggregate multi-source telemetry. Edge migration is displacing pure cloud architectures for latency-sensitive compaction alerts.
- Machine Learning Algorithms:Predictive models optimize collection frequency and maintenance scheduling. Talent scarcity forces vendors to embed managed services that erode software margins.
Edge-capable IoT Sensors are climbing the fastest; pure Cloud Computing faces margin compression from infrastructure commoditization.
Application:
Application mix reflects regulatory pressure gradients, with methane-intensive streams commanding premium sensor density.
- Municipal Solid Waste:Residential and commercial mixed streams dominate procurement volume. EPA methane reporting thresholds compel US cities to quantify generation rates through sensor networks.
- Industrial Byproducts:Manufacturing slag, chemical residues, and process waste require hazardous classification. EU REACH documentation drives demand for composition-sensing containers.
- Construction Debris:Concrete, asphalt, and demolition waste streams lack standardization. Sorting facility automation lags due to material heterogeneity and abrasive wear on equipment.
- Electronic Scrap:Circuit boards, batteries, and rare earth recovery face strict chain-of-custody rules. EU WEEE directives mandate GPS-tracked collection points for audit trails.
- Organic Waste:Food scraps and agricultural residue generate methane if landfilled. France and Germany mandate temperature-logging containers for cold chain compliance under F-Gas Regulation.
Electronic Scrap commands steepest expansion trajectory; Construction Debris lags on automation economics.
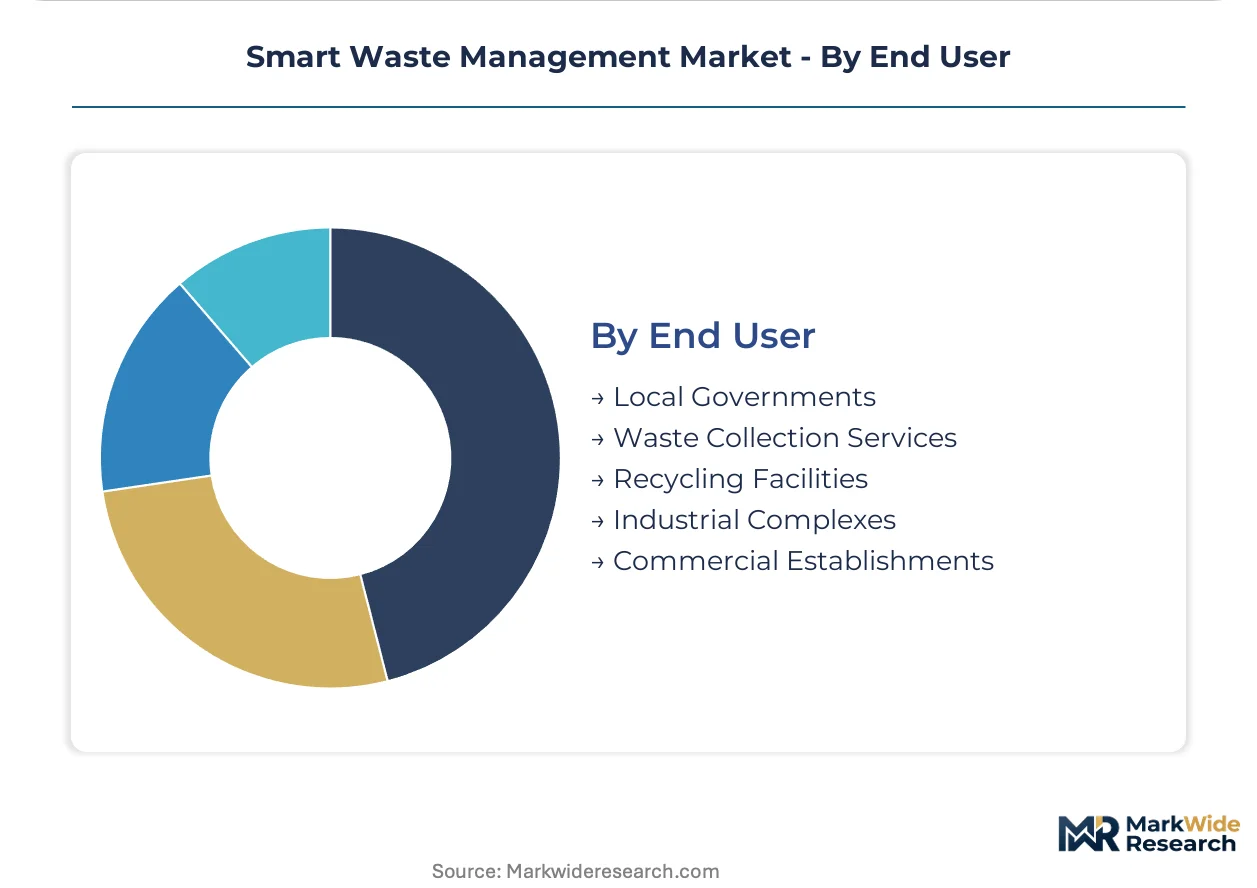
End User:
End user procurement authority determines contract structure, with government accounts favoring SaaS while industrial buyers negotiate capital purchases.
- Local Governments:Municipal waste departments control collection fleet operations. Budget constraints force multi-year amortization of sensor hardware alongside annual software licenses.
- Waste Collection Services:Private haulers compete on route efficiency and fuel costs. Dynamic optimization software separates competitive performers from static-schedule operators.
- Recycling Facilities:MRFs and composting sites prioritize contamination detection. Computer vision modules mounted on intake conveyors automate quality control previously outsourced.
- Industrial Complexes:Manufacturing campuses manage captive waste streams. Producer responsibility frameworks require granular tracking of byproduct disposition.
- Commercial Establishments:Retail and hospitality generators face packaging waste directives. Smart bin networks at collection points enable brand-level post-consumer material accounting.
Local Governments anchor current procurement volume; Commercial Establishments represent the fastest-climbing segment under extended producer responsibility expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's landfill tax regime and Narrowband-IoT coverage create faster deployment velocity than Japan, where mountainous terrain fragments cellular backhaul and delays rural sensor network rollout.
United States
EPA methane reporting thresholds compel municipal procurement of fill-level telemetry systems. The IRA's clean energy incentives extend to waste-to-energy infrastructure, accelerating sensor deployment in California and Texas metros. New York City's commercial waste zone reforms mandate route optimization software for private haulers.
Germany
EU Green Deal packaging waste directives drive RFID-enabled bin tracking across industrial districts. The F-Gas Regulation mandates temperature logging for organic waste streams, compelling sensor deployment in Bavarian food processing clusters. North Rhine-Westphalia's procurement frameworks require modular contracting to prevent vendor lock-in.
Japan
METI's digital infrastructure investments enable gateway-free LPWAN installations in dense urban cores. Narrowband-IoT coverage gaps in mountainous regions delay deployment outside Tokyo-Osaka corridors. Osaka's industrial waste generators specify spectroscopic composition sensors for hazardous classification compliance.
India
PLI scheme incentives for IoT hardware manufacturing localize sensor production for Smart Cities Mission tenders. Maharashtra's municipal corporations pilot dynamic route optimization in Mumbai and Pune. Telangana's electronics manufacturing clusters supply IP67-rated enclosures for domestic waste infrastructure.
France
ANSM cold chain regulations extend to pharmaceutical waste disposal, requiring thermal telemetry in Lyon and Paris hospital networks. Extended producer responsibility frameworks mandate brand-level tracking at retail collection points. Île-de-France's sorting facilities adopt computer vision modules for contamination detection.
Smart Waste Management Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing municipal SaaS contracts and component suppliers serving modular industrial deployments. The vendor base concentrates around three strategic archetypes: vertically integrated hardware-platform hybrids, pure-play analytics specialists, and networking infrastructure incumbents. M&A activity targets route optimization algorithms, while capacity expansion concentrates on East Asian sensor foundry partnerships.
Within the integrated-platform tier, Ecube Labs Co., Ltd. and Sensoneo, s.r.o. occupy positions defined by captive manufacturing and European deployment expertise respectively. Cisco Systems, Inc. anchors the infrastructure-provider archetype through backhaul connectivity dominance in North American municipal networks.
| Leading Market Players |
|---|
| Bigbelly, Inc. |
| Ecube Labs Co., Ltd. |
| International Business Machines Corporation (IBM) |
| Sensoneo, s.r.o. |
| Compology, Inc. |
| Cisco Systems, Inc. |
| Enevo, Inc. |
| Rubicon Technologies, LLC |
| Schneider Electric SE |
| Others |
Cost & Logistics Intelligence
Captive manufacturing of IP67-rated sensor enclosures anchors Ecube Labs' supply position and pricing power, insulating municipal contracts from semiconductor foundry volatility while compressing margins for pure-software competitors dependent on third-party hardware procurement.
Pricing Analysis
Capacity additions in Telangana's electronics manufacturing clusters are reshaping price floors for sensor assemblies, enabling Indian vendors to undercut East Asian imports in Smart Cities Mission tenders. SaaS-tiered pricing for route optimization software stratifies across premium, standard, and economy tiers based on fleet scale and analytics depth. Cost compression in hardware tiers intensifies because PLI scheme subsidies localize production, though software margins face erosion from embedded managed services. Waste collection services exhibit highest price sensitivity due to thin operating margins, while municipal governments prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Freight cost differentials between East Asian semiconductor hubs and Indian assembly plants are reordering procurement patterns for ultrasonic sensor modules. Supply concentrates in Taiwan and South Korea for MEMS fabrication, with final assembly migrating to India and Vietnam under tariff pressure. Raw material dependencies span rare earth magnets for compaction motors, lithium for battery-backed telemetry, and specialty polymers for IP67 sealing. Single-source vulnerability in East Asian foundry capacity exposes lead times to geopolitical disruption. Distribution runs through municipal procurement frameworks in Germany and the United States, with direct OEM relationships dominating industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's PLI-subsidized manufacturing and Germany's landfill-tax-driven procurement premiums creates margin capture opportunities for vendors with dual-hemisphere production footprints.
For Market Incumbents: Acquire route optimization algorithm specialists to defend SaaS recurring revenue against pure-play analytics entrants. Backward integration into LPWAN gateway manufacturing reduces cellular backhaul dependency in Japanese mountainous regions. Certification investment in ISO 14040-compliant data platforms locks in recycling facility contracts under EU Green Deal mandates. For New Entrants and Emerging Players: The premium-to-economy pricing gap in sensor hardware opens white-space targeting of mid-sized German municipalities bypassed by integrated platform vendors. India's Smart Cities Mission tenders represent the most penetrable geography given localized production incentives and limited incumbent saturation. A go-to-market angle through predictive maintenance upsells on installed compaction motor bases bypasses direct competition for initial hardware deployment. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor lock-in from proprietary data protocols limits competitive tendering in North American municipal accounts. Long-term viability hinges on platform interoperability rather than hardware margin extraction, favoring analytics-centric business models over sensor manufacturing. Acquisition target archetypes include computer vision specialists for contamination detection and edge-computing gateway providers. The signal to watch is modular contracting mandates spreading from North Rhine-Westphalia to other German states and potentially the EU procurement code.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Gateway Development | Reduces latency for fill-level alerts while creating hardware margin pools beyond sensor sales. |
| Predictive Maintenance Algorithm Licensing | Monetizes vibration data from compaction motors through upsell revenue on installed bases. |
| RFID-IoT Protocol Convergence | Addresses interoperability friction forcing single-vendor lock-in under EU packaging waste directives. |
| Computer Vision Module Integration | Automates contamination audits for Dutch and Californian recycling facilities seeking labor reduction. |
| PLI Scheme Manufacturing Localization | Bypasses import duties on sensor assemblies for Indian Smart Cities Mission municipal tenders. |
Research Approach
Direct dialogue with municipal waste department directors, fleet operations managers at private haulers, recycling facility procurement leads, and IoT platform engineers grounded qualitative findings, cross-referenced against EPA methane reporting databases, EU Green Deal implementation trackers, NB-IoT coverage maps from German and Japanese regulators, and municipal tender documentation from North Rhine-Westphalia and Maharashtra. Secondary validation drew from customs records for sensor assembly trade flows, SEC filings for publicly traded infrastructure providers, and ISO certification registries. Bottom-up and top-down triangulation reconciled vendor shipment data with municipal budget appropriations.
Bottom-up modeling aggregated sensor unit deployments by municipality tier and software license counts by fleet scale, while top-down analysis tracked landfill diversion mandate adoption curves and LPWAN infrastructure investment cycles across the projection horizon. Segmentation dimensions spanned solution architecture, connectivity technology, waste stream application, and end-user procurement authority. CAGRs were derived from logistic diffusion curves fitted to early-adopter penetration rates in Germany and the United States, adjusted for regulatory enforcement timelines and infrastructure buildout schedules. Forecast inputs incorporated semiconductor foundry capacity utilization and municipal budget elasticity to landfill tax regimes.
Caveats apply where NB-IoT coverage expansion delays in mountainous Japanese regions or PLI scheme revision in India could materially shift the outlook for hardware deployment velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Waste Management
Packaging Waste Recycling Market
E-Waste Management
Global E-Waste Recycling and Reuse Service Market
E-Waste Management
Recycling Equipment and Machinery Market
E-Waste Management
Middle East and Africa Solar Panel Recycling Market
E-Waste Management
E-Scrap Recycling Market
E-Waste Management
Release Liner Recycling Market
E-Waste Management
Electronic Scrap Recycling Market
E-Waste Management
Recycling Equipment Market
E-Waste Management
Solar Panel Recycling Market
E-Waste Management
APAC E-Waste Management Market
E-Waste Management
Electronic Waste Recycling Market
E-Waste Management
Solar Panel Recycling Management Market
E-Waste Management
Solar Trash Compactors Market
E-Waste Management
North America E-Waste Management Market
E-Waste Management
UAE E-Waste Management Market
E-Waste Management
Lithium-Ion Battery Reuse and Recycling Market