
 Rare Earth Recycling Market | 2026-2036
Rare Earth Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Earth Recycling Market Outlook
Multi-source feedstock aggregation is realigning procurement economics across the rare earth recycling value chain. Solvay leverages hydrometallurgical expertise to sustain European rare earth oxide output from industrial scrap. Energy Fuels, Inc. anchors North American capacity through in-house uranium and rare earth co-processing infrastructure. Shenghe Resources Holdings dominates magnet waste sourcing channels across Chinese manufacturing clusters.
Rare earth recycling encompasses the recovery and reprocessing of lanthanide elements from end-of-life products and manufacturing residues, typically yielding oxide purities exceeding 99.5% through solvent extraction circuits. The process addresses supply security for neodymium, dysprosium, and terbium used in high-performance permanent magnets. Hydrometallurgical routes command the deepest margin pools due to selective precipitation complexity and reagent recovery economics. Permanent magnet scrap generates the fastest-growing feedstock volume as wind turbine and electric motor retirement curves steepen.
The EU Critical Raw Materials Act imposes recycled content thresholds that redirect automotive OEM sourcing toward certified European recyclers. China's MIIT enforces rare earth utilization efficiency standards that compel domestic smelters to integrate scrap processing. EPA hazardous waste classifications in the United States shape leaching circuit design and tailings management protocols. Stakeholders must track how regulatory differentiation between primary and recycled material certification alters contract structures and offtake premiums.
Market Dynamics
Magnet-to-magnet recycling loops are compressing rare earth oxide supply chains by bypassing primary smelter intermediaries entirely. Hydrometallurgical direct reuse of sintered magnet scrap eliminates reduction steps that previously dominated cost structures.
Growth Catalysts
- EU Critical Raw Materials Act:Mandatory recycled content thresholds for permanent magnets used in wind turbines and traction motors force automotive OEMs to contract certified European recyclers.
- Electric vehicle motor retirement:End-of-life NdFeB magnets from first-generation EV drivetrains are entering waste streams in volumes sufficient to feed dedicated recycling facilities.
- China MIIT utilization standards:Domestic smelters must integrate scrap processing to maintain operating licenses, creating captive demand for magnet manufacturing residues.
Market Restraints
- Acid reagent cost volatility:Sulfuric and hydrochloric acid prices fluctuate with oil and chlorine markets, eroding hydrometallurgical margin stability.
- Chinese downstream concentration:Over 85% of global rare earth oxide separation capacity sits within Chinese borders, forcing Western recyclers to export mixed concentrates for refining.
- Pyrometallurgical yield ceilings:High-temperature reduction routes cannot recover dysprosium and terbium without oxidative slagging that destroys economic value.
Strategic Opportunities
- US Inflation Reduction Act credits:Domestic content bonuses for recycled critical minerals create offtake premiums for North American magnet recovery operations.
- Wind turbine decommissioning wave:Offshore installations reaching 20-year design life in Northern Europe offer concentrated NdFeB feedstock with predictable logistics.
- Direct reuse metallurgy:Grain boundary diffusion techniques enable remanufactured magnets to match virgin material performance without full oxide reduction.
Industry Challenges
- Rare earth chemist scarcity:Solvent extraction circuit design requires expertise in lanthanide separation factors that few university programs currently produce.
- EPA hazardous waste permitting:Leaching residues containing thorium and uranium trigger RCRA Subtitle C classification, extending facility approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Earth Recycling Market |
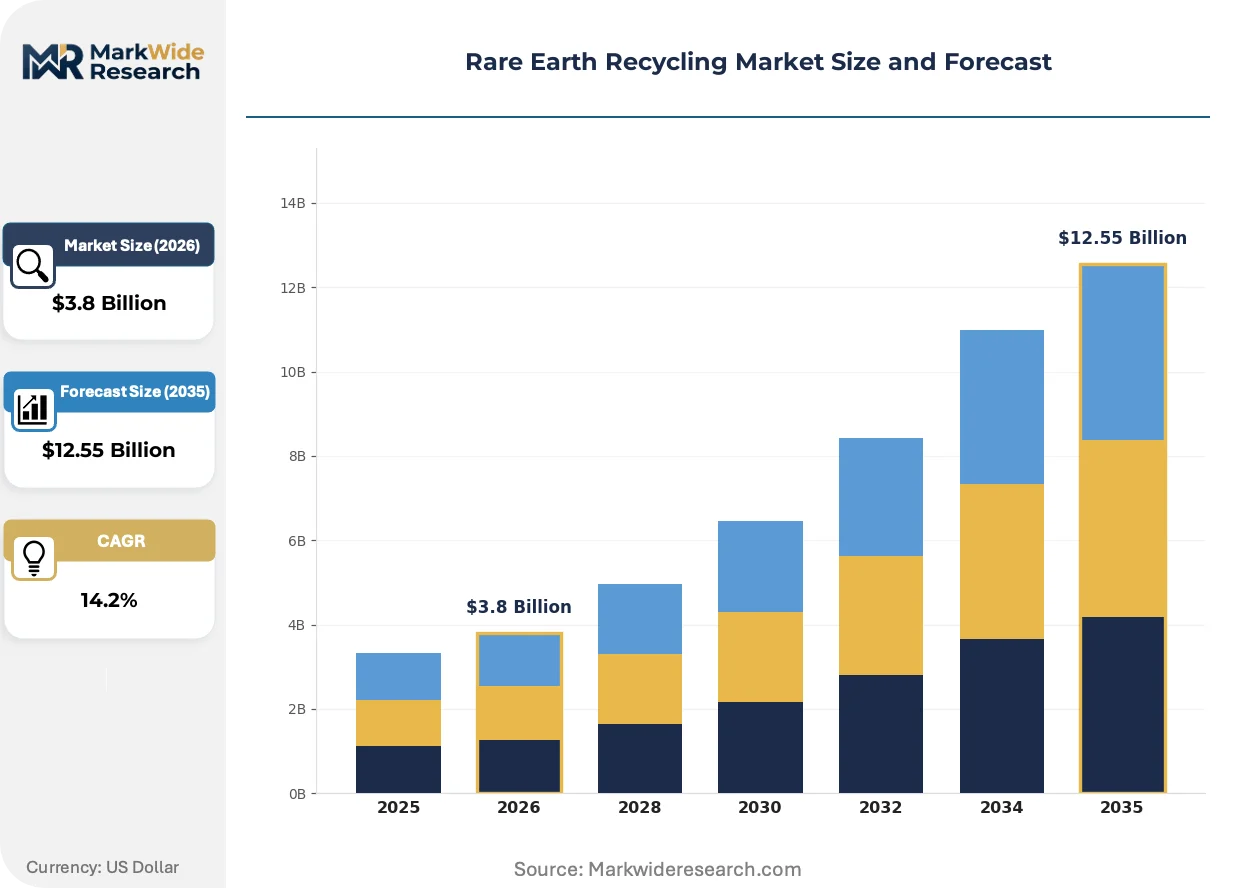
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Hydrometallurgical, Pyrometallurgical, Bioleaching, Mechanical Material Source: Scrap Electronics, Batteries, Permanent Magnets, Phosphors End User: Aerospace, Automotive, Renewable Energy, Electronics Technology: Solvent Extraction, Ion Exchange, Hydrometallurgical Processes, Recycling Innovations |
| Companies Covered | Solvay, Hitachi Metals, REEcycle, Inc., Geomega Resources, Umicore, Mitsubishi Chemical Corporation, Shenghe Resources Holdings, Energy Fuels, Inc., Arafura Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Earth Recycling Market Strategic Shifts
Selective precipitation chemistry and automated sorting systems are collapsing the cost gap between primary and recycled rare earth oxides. Process intensification through continuous flow reactors is eliminating batch inefficiencies that plagued legacy operations.
Electrochemical rare earth recovery is rewriting separation economics by replacing solvent extraction with membrane-based selective electrodeposition. European pilot facilities are commissioning 500-tonne-per-year units for magnet scrap processing. The technology compresses purification stages from seven steps to three, enabling modular plant deployment near automotive manufacturing clusters.
REACH authorization requirements for process chemicals are forcing recyclers to substitute organophosphorus extractants with biodegradable alternatives. German regulators under ECHA are accelerating substance evaluation timelines for thiocyanate-based reagents. The policy shift favors hydrometallurgical operators with in-house reagent synthesis capabilities over tolling-dependent competitors.
Automotive OEMs are consolidating magnet procurement through closed-loop contracts that specify recycled content minimums and traceable chain-of-custody documentation. Tier-1 motor suppliers in Germany and Japan are displacing spot-market oxide purchases with multi-year offtake agreements tied to specific decommissioned turbine and vehicle feedstock pools. The contracting model is most visible in Scandinavian wind energy markets where project finance requirements mandate circular material documentation.
Rare Earth Recycling Market Segmentation
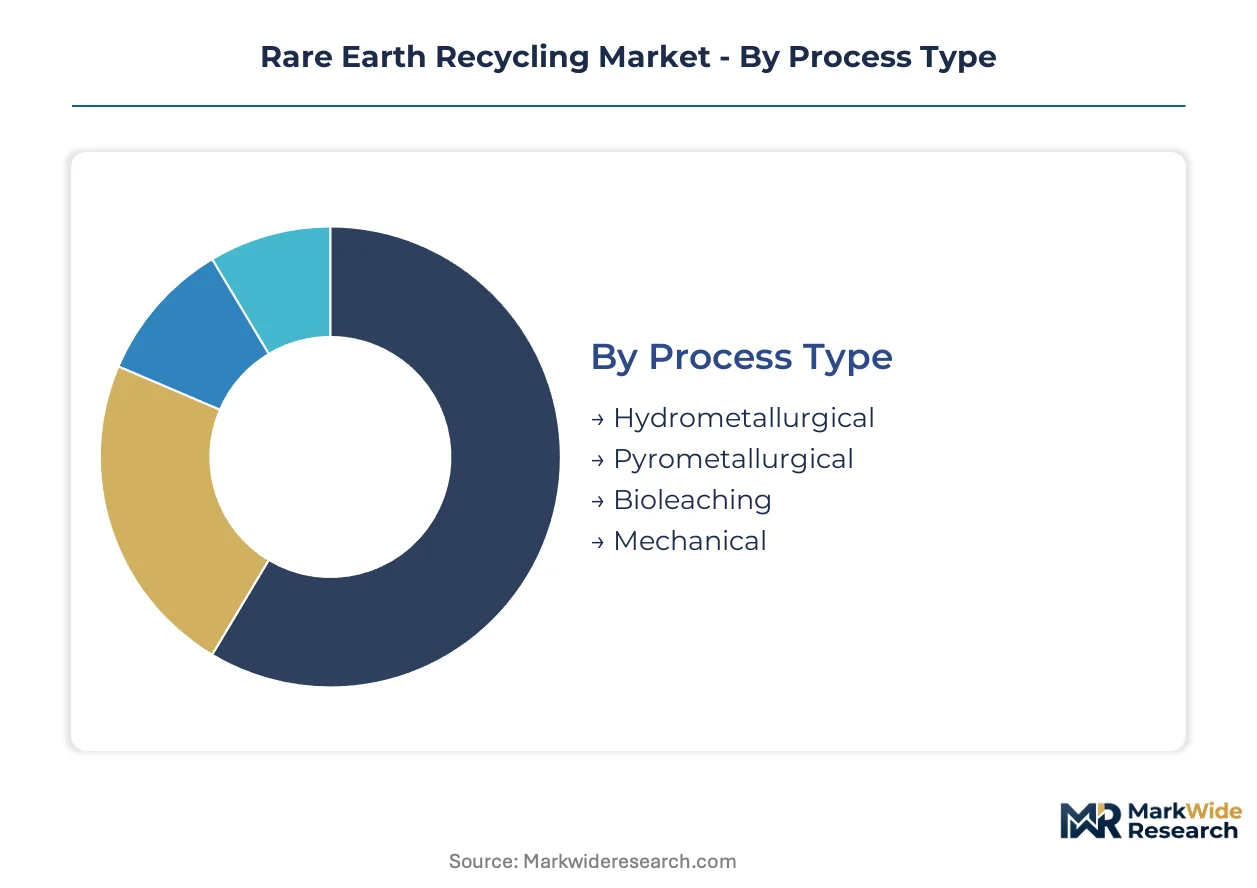
Segmentation in rare earth recycling reveals how feedstock chemistry and process economics determine facility design. Recovery yields vary dramatically across magnet scrap versus phosphor waste, while regulatory pressure on specific end-use sectors reshapes demand concentration.
Process Type:
Upgrade cycles in rare earth recycling pivot on replacing pyrometallurgical furnaces with selective hydrometallurgical circuits that preserve heavy rare earth values.
- Hydrometallurgical:Acid leaching followed by solvent extraction achieves oxide purities exceeding 99.5% for neodymium and dysprosium. German recyclers under ECHA REACH authorization requirements are expanding precipitation capacity to handle rising magnet scrap volumes from decommissioned wind turbines.
- Pyrometallurgical:High-temperature reduction routes recover cerium and lanthanum from glass polishing residues but oxidize terbium and dysprosium into unrecoverable slag. Chinese smelters under MIIT utilization standards maintain pyrometallurgical lines for light rare earth concentrates while adding hydrometallurgical modules for heavy fractions.
- Bioleaching:Microbial acid generation from Acidithiobacillus species offers reagent cost stability but requires extended residence times that constrain throughput.
- Mechanical:Crushing and magnetic separation prepares feedstock for downstream chemical processing without elemental recovery.
Hydrometallurgical sits at the top of the volume ranking, with bioleaching climbing the fastest as reagent substitution pressures mount.
Material Source:
Cost tier differentiation separates high-value magnet scrap commanding oxide-equivalent premiums from low-grade phosphor waste requiring subsidized collection.
- Permanent Magnets:NdFeB scrap from electric vehicle drivetrains and wind turbine generators carries the richest rare earth concentrations at 25-35% total rare earth oxide content. Automotive OEMs in Germany and Japan are signing closed-loop contracts that specify minimum recycled content thresholds and chain-of-custody documentation.
- Scrap Electronics:Hard disk drives and mobile speakers contain sintered magnets with predictable neodymium-to-dysprosium ratios. Collection infrastructure concentrates in Japanese urban centers where METI recycling mandates drive manufacturer-funded takeback programs.
- Batteries:Nickel-metal hydride cells from hybrid vehicles yield lanthanum-rich fractions with limited magnet-grade applicability.
- Phosphors:Fluorescent lamp waste contains europium and terbium in dilute matrices that require high reagent consumption per kilogram recovered.
Permanent magnets dominate current feedstock volumes, with scrap electronics expanding most quickly as data center decommissioning accelerates.
End User:
Application-specific purity requirements stratify the market, with aerospace demanding aerospace-grade certification that recycled material struggles to obtain.
- Automotive:Traction motor manufacturers specify grain-boundary-diffused magnets with precise dysprosium surface concentrations. The EU Critical Raw Materials Act mandates recycled content thresholds that force OEMs toward certified European recyclers.
- Renewable Energy:Wind turbine generators require 2-5 tonnes of NdFeB per megawatt installed capacity. Offshore installations reaching design life in Northern Europe offer concentrated feedstock pools with predictable logistics.
- Electronics:Miniaturized speakers and vibration motors accept lower coercivity grades that tolerate broader compositional ranges.
- Aerospace:Flight-critical actuators demand full traceability and aerospace-grade certification that current recycled oxide streams rarely achieve.
Automotive leads end-user volume, with renewable energy gaining share fastest as turbine retirement curves steepen.
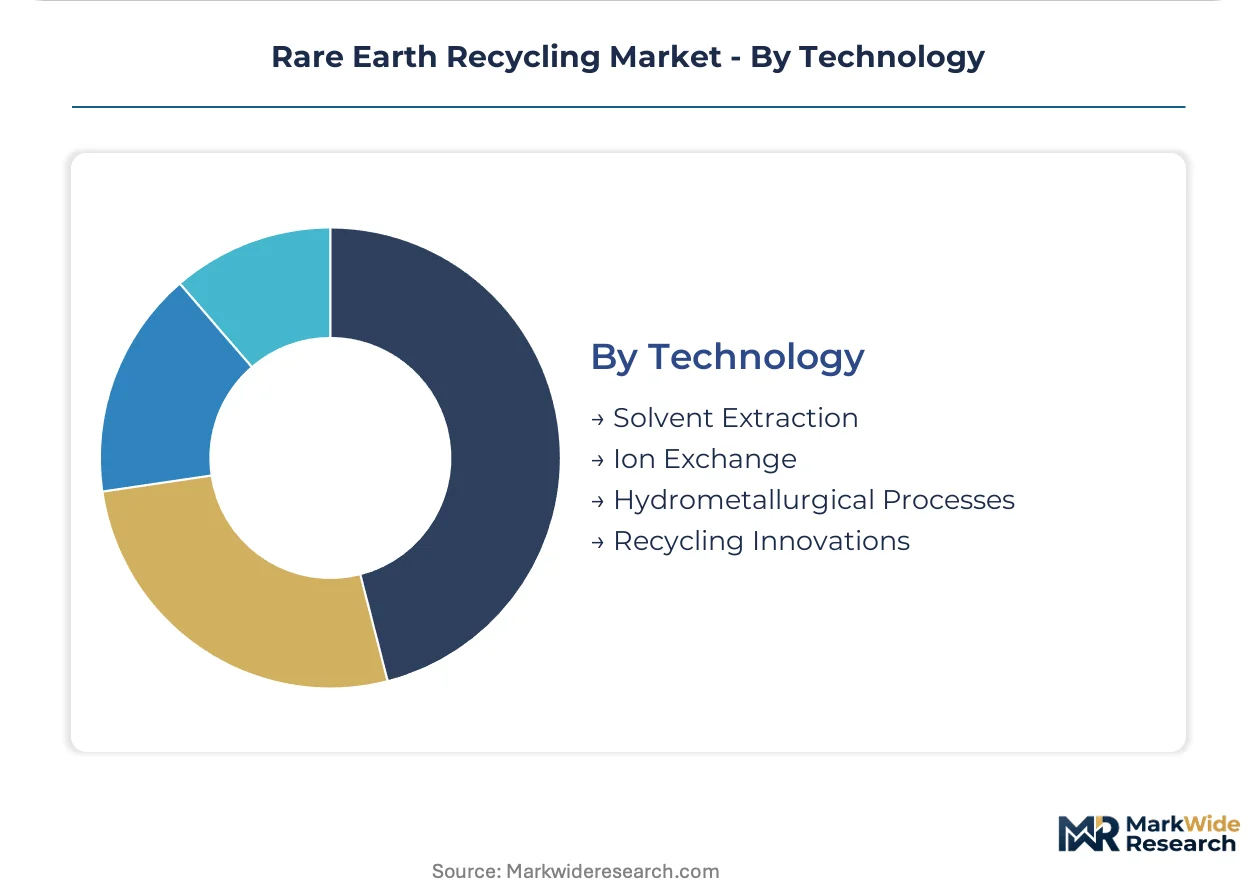
Technology:
Margin concentration favors operators with in-house solvent extraction design capability rather than tolling-dependent competitors.
- Solvent Extraction:Organophosphorus extractants separate lanthanide ions based on separation factors that require precise pH control. ECHA substance evaluation timelines for thiocyanate-based reagents are forcing substitution toward biodegradable alternatives.
- Hydrometallurgical Processes:Continuous flow reactors eliminate batch inefficiencies that plagued legacy precipitation circuits. European pilot facilities are commissioning modular units near automotive manufacturing clusters.
- Ion Exchange:Chelating resins offer selective capture of heavy rare earths from complex matrices but suffer from capacity limitations at commercial scale.
- Recycling Innovations:Electrochemical rare earth recovery through membrane-based selective electrodeposition compresses purification stages from seven steps to three.
Solvent extraction maintains the highest deployment base, with recycling innovations showing the steepest expansion trajectory as electrochemical pilots scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting rare earth recycling investment toward jurisdictions where compliance costs and permitting timelines diverge most sharply from downstream market access. European operators absorb stringent ECHA substance evaluations in exchange for EU Critical Raw Materials Act offtake guarantees, while North American projects leverage IRA domestic content credits against EPA hazardous waste classification complexity.
United States
Domestic magnet recovery facilities in Utah and Texas process uranium co-product streams through in-house rare earth oxide separation circuits. EPA RCRA Subtitle C permitting for thorium-bearing leaching residues extends facility approval timelines to 18-24 months. The White Mesa facility in Utah anchors North American hydrometallurgical capacity, exporting mixed concentrates to offshore refiners pending domestic separation scale-up.
Germany
Automotive OEMs in Stuttgart and Munich mandate closed-loop magnet contracts with recycled content thresholds exceeding EU Critical Raw Materials Act minimums. ECHA REACH authorization timelines for thiocyanate-based extractants are accelerating substitution toward biodegradable organophosphorus alternatives. The Rhine-Ruhr industrial corridor hosts pilot electrochemical recovery units processing decommissioned wind turbine feedstock from North Sea installations.
China
MIIT utilization efficiency standards compel domestic smelters in Jiangxi and Inner Mongolia to integrate scrap processing or forfeit operating licenses. Shenghe Resources Holdings dominates magnet waste sourcing channels across manufacturing clusters in Ningbo and Shenzhen. Downstream oxide separation capacity concentrates in Ganzhou, forcing Western recyclers to export mixed concentrates for refining despite geopolitical supply security concerns.
Japan
METI recycling mandates fund manufacturer-led takeback programs for hard disk drives and automotive motor scrap in Tokyo and Osaka metropolitan areas. Predictable neodymium-to-dysprosium ratios in sintered magnet waste enable streamlined solvent extraction circuit design. The Chubu region around Nagoya hosts specialized precipitation facilities serving Toyota and Honda closed-loop supply agreements.
Belgium
Solvay leverages hydrometallurgical expertise at its La Rochelle and Olen sites to sustain European rare earth oxide output from industrial phosphor and catalyst scrap. ECHA substance evaluation pressures are driving in-house reagent synthesis capabilities versus tolling-dependent competitors. The Antwerp logistics hub facilitates feedstock aggregation from decommissioned fluorescent lamp networks across Benelux and Northern France.
Rare Earth Recycling Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electrochemical and direct-reuse metallurgy niches that bypass legacy solvent extraction infrastructure. The market structures around three archetypes: diversified chemical conglomerates with hydrometallurgical heritage, resource developers integrating uranium-rare earth co-processing, and pure-play recyclers targeting magnet-to-magnet loops. Dominant competitive moves include backward integration into feedstock collection networks and technology licensing partnerships that transfer selective precipitation IP across regulatory jurisdictions.
Within the diversified chemical tier, Solvay and Umicore exemplify European operators absorbing ECHA compliance costs to secure EU Critical Raw Materials Act offtake premiums. Energy Fuels, Inc. anchors the resource-integrated archetype from its Utah base, leveraging in-house uranium processing infrastructure for rare earth co-product recovery. Shenghe Resources Holdings occupies the feedstock aggregation tier, sourcing magnet manufacturing residues across Chinese industrial clusters under MIIT utilization standards.
| Leading Market Players |
|---|
| Solvay |
| Hitachi Metals |
| REEcycle, Inc. |
| Geomega Resources |
| Umicore |
| Mitsubishi Chemical Corporation |
| Shenghe Resources Holdings |
| Energy Fuels, Inc. |
| Arafura Resources |
| Others |
Value Chain & Pricing Dynamics
Electrochemical rare earth recovery compresses purification stages from seven steps to three, collapsing cost structures while simultaneously redrawing supply concentration away from legacy solvent extraction hubs toward modular deployment near automotive manufacturing clusters. This technology shift rewards operators with in-house reagent synthesis capabilities over tolling-dependent competitors, embedding pricing power in process control rather than feedstock scale.
Pricing Analysis
Direct-to-OEM contract structures dominate high-volume magnet recovery, bypassing distributor markups that erode margin on spot-market oxide sales. Three-tier pricing structure across aerospace-grade, automotive-specification, and industrial-grade oxide purities separates certified European recyclers commanding EU Critical Raw Materials Act premiums from uncertified competitors. Cost compression in standard-grade fractions intensifies as Chinese downstream concentration forces Western recyclers to export mixed concentrates for refining. Automotive OEMs exhibit lowest price sensitivity due to regulatory compliance mandates, while industrial magnet buyers remain most responsive to spot-price fluctuations.
Supply Chain Analysis
Reverse-logistics networks for end-of-life wind turbines and electric vehicle drivetrains are consolidating feedstock aggregation around North Sea ports and Japanese urban centers. Primary supply concentrates in China, with secondary feedstock sourcing expanding across Germany, Japan, and the United States. Hydrometallurgical reagent supply draws from sulfuric acid production tethered to oil refining and chlorine markets. Single-source vulnerability in downstream oxide separation forces Western recyclers into geopolitically exposed export arrangements. Distribution runs through closed-loop contracts with Tier-1 motor suppliers rather than spot-market exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rare earth recycling market compounds steadily as regulatory mandates harden recycled content thresholds across automotive and renewable energy procurement. EU Critical Raw Materials Act enforcement ensures demand visibility that stabilizes investment returns across facility development cycles.
For Market Incumbents: Deploy selective precipitation IP licensing to capture value from tolling-dependent competitors without capital-intensive capacity expansion. Backward integration into decommissioned wind turbine collection networks in Northern Europe defends feedstock access against emerging pure-play recyclers. ECHA REACH authorization timelines for thiocyanate-based reagents threaten margin stability for operators lacking in-house reagent synthesis capabilities.
For New Entrants and Emerging Players: The US Inflation Reduction Act domestic content credits open a window for North American magnet recovery operations to capture offtake premiums from automotive OEMs seeking supply security. Electrochemical recovery pilots in the 500-tonne-per-year scale represent the most penetrable technology tier, bypassing legacy solvent extraction infrastructure requirements. Target direct reuse metallurgy partnerships with grain boundary diffusion specialists to accelerate commercial validation without full oxide reduction investment.
For Investors and Strategic Acquirers: Roll-up economics work for hydrometallurgical specialists with ECHA-compliant reagent capabilities because regulatory compliance costs create barriers that favor scaled operators over fragmented tolling competitors. Five-to-ten-year viability hinges on securing closed-loop contracts with automotive OEMs before turbine decommissioning volumes peak. Monitor EPA RCRA Subtitle C permitting timelines for thorium-bearing leaching residues as the signal for North American capacity expansion inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Secures decommissioned wind turbine volumes from North Sea installations before competitor aggregation. |
| Electrochemical Recovery Scale-Up | Compresses purification stages and enables modular deployment near Stuttgart and Munich automotive clusters. |
| In-House Reagent Synthesis Investment | Insulates margin from ECHA REACH authorization delays affecting thiocyanate-dependent competitors. |
| Closed-Loop Contract Structuring | Locks in EU Critical Raw Materials Act compliance premiums with German and Japanese OEMs. |
| Grain Boundary Diffusion Partnership | Enables remanufactured magnet performance matching virgin material without full oxide reduction. |
Study Parameters
Multiple input streams — primary interviews with rare earth chemists and solvent extraction engineers, regulatory filings from ECHA and EPA, and trade data on magnet scrap flows — were reconciled against secondary validation from SEC disclosures and industry association reports. Conversations with plant managers at hydrometallurgical facilities, procurement leads at automotive Tier-1 suppliers, and distribution channel partners in the Rhine-Ruhr corridor informed operational assumptions. Bottom-up facility capacity estimates and top-down demand projections from end-use sectors were triangulated to constrain forecast variance.
Historical capacity expansion patterns were cross-referenced against panel input from project developers and equipment suppliers to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include process type, material source, end-user application, and technology platform, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from fitted growth curves calibrated to announced facility commissioning timelines and feedstock availability curves. Forecast inputs incorporated retirement schedules for first-generation electric vehicle drivetrains and wind turbine design life assumptions.
Revisions become necessary when EPA hazardous waste permitting timelines extend beyond modeled assumptions or when Chinese MIIT utilization standards accelerate domestic scrap absorption beyond export availability. Practitioners should monitor ECHA substance evaluation timelines for organophosphorus extractants and electrochemical recovery pilot commissioning rates for early signals of technology transition velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
GCC Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Europe Bio-Medical Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Global Waste Management Equipment Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Trash Pump Market