
 Quality Monitoring Sensor for Water Market | 2026-2036
Quality Monitoring Sensor for Water Market Size, Share, and Industry Trends Forecast 2026-2036
Quality Monitoring Sensor for Water Market Insights
Sensor-as-a-service leasing and project finance arrangements for municipal water infrastructure is tilting competitive dynamics toward capital-light entrants. Xylem Inc. leverages its vertical integration across instrumentation and analytics software to sustain pricing power in North American utility contracts. Danaher Corporation anchors its position through intensive R&D spend on electrochemical sensor miniaturization. Endress+Hauser Group dominates European process industries with application-specific dissolved oxygen platforms.
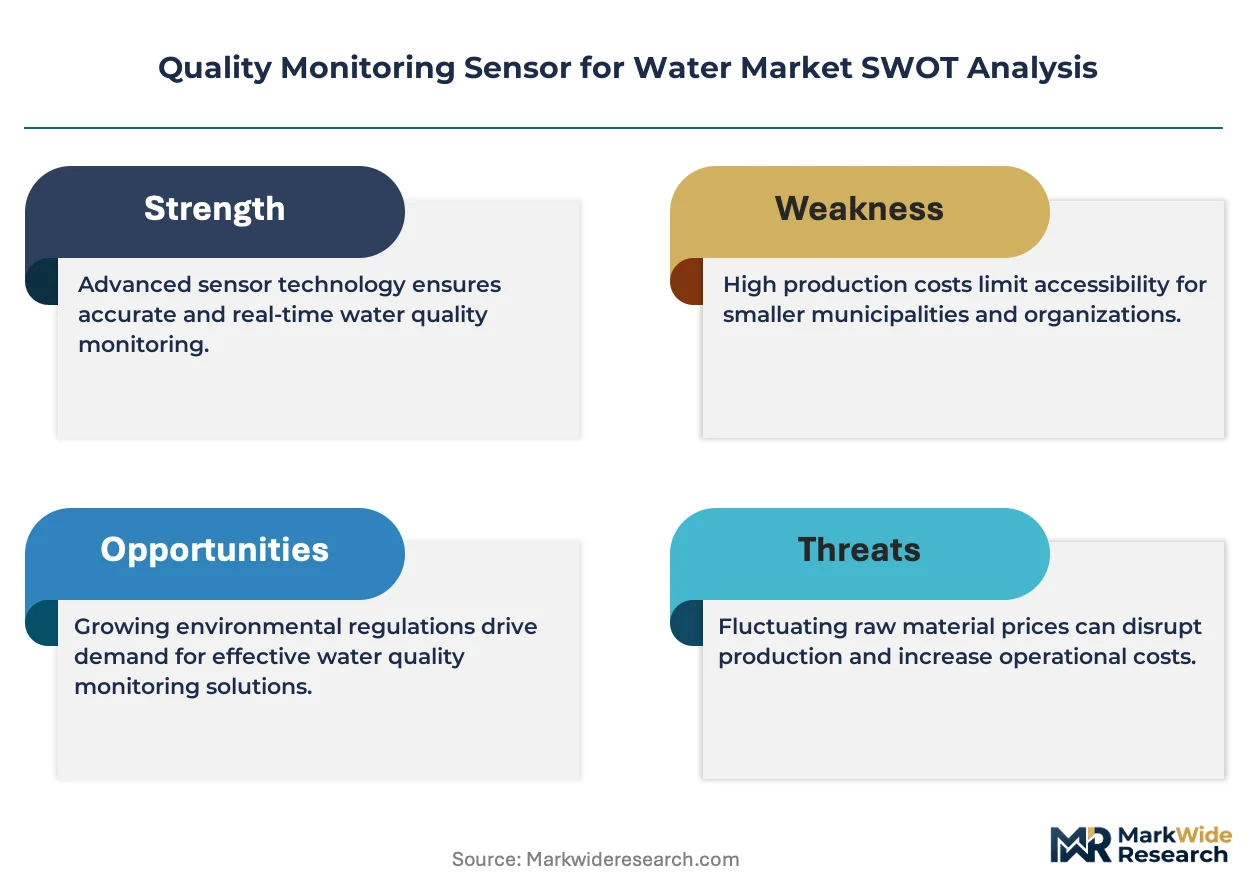
Quality monitoring sensors for water are electrochemical, optical, or ultrasonic devices that measure parameters including pH, turbidity, dissolved oxygen, and conductivity with detection ranges typically spanning parts-per-billion to saturation levels, deployed for regulatory compliance and process optimization across treatment and distribution networks. pH sensors occupy the largest installed base due to universal applicability across municipal and industrial settings, though optical turbidity platforms represent the fastest-expanding category as utilities replace manual sampling with continuous nephelometric monitoring. Electrochemical technology leads in unit volume because of lower per-node cost and established calibration protocols, while remote sensing systems command premium positioning for watershed-scale surveillance where physical access remains impractical.
The EPA enforces Clean Water Act permitting through NPDES discharge limits that mandate continuous parameter logging, while the EU Water Framework Directive and REACH chemical registration rules compel manufacturers to document aquatic toxicity profiles. China's MEE enforces real-time monitoring data transmission for key polluting enterprises through its pollution source monitoring regulations. Stakeholders must weigh calibration drift rates against total cost of ownership when selecting between optical and electrochemical architectures for multi-parameter installations.
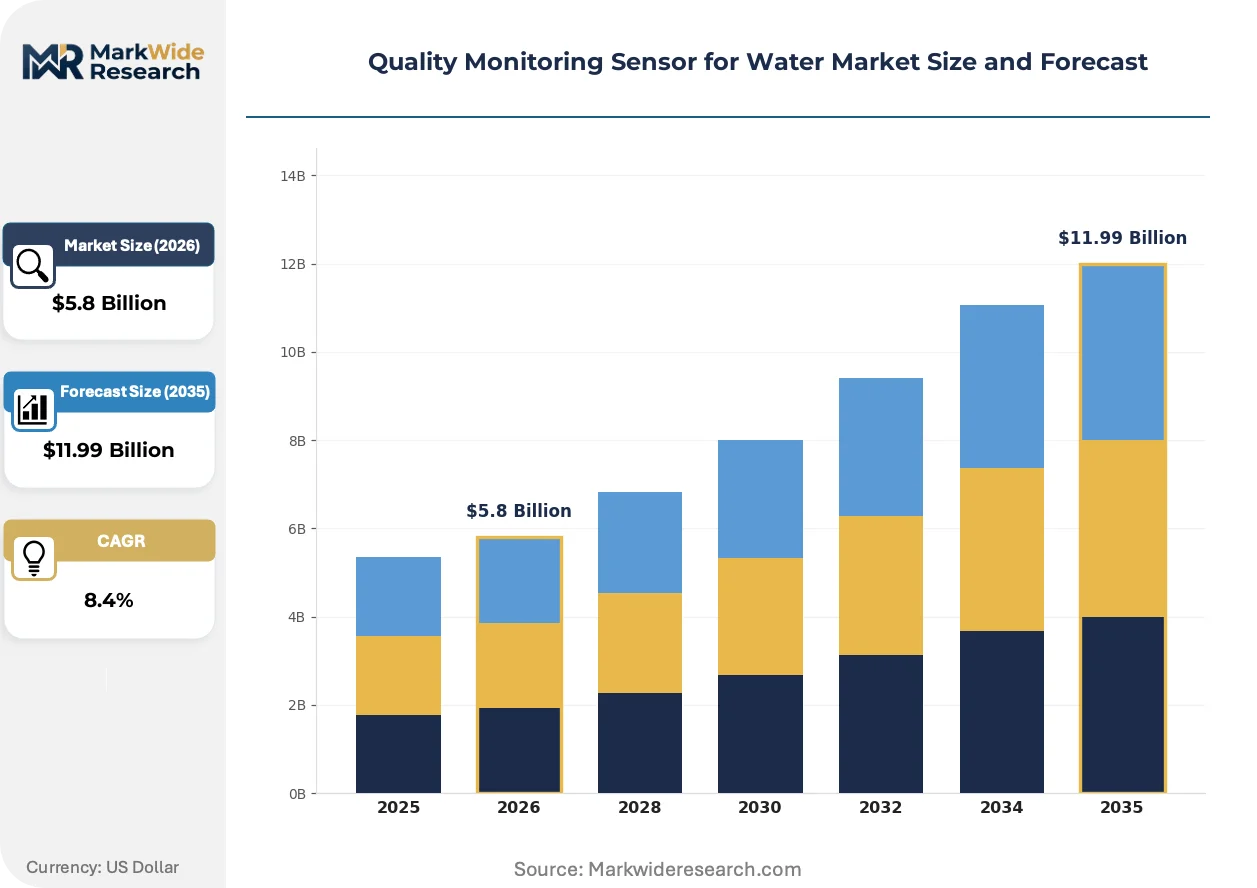
Market Dynamics
Sensor-as-a-service leasing models are restructuring capital deployment across municipal water infrastructure, tilting procurement toward operational expenditure frameworks and compressing barriers for specialized instrumentation entrants.
Growth Catalysts
- EPA NPDES Enforcement:Continuous discharge monitoring mandates under the Clean Water Act compel industrial facilities to install multi-parameter sensor arrays for real-time logging and automated reporting compliance.
- China MEE Real-Time Data Transmission:Provincial environmental bureaus in the Yangtze River Delta mandate online pollution source monitoring for chemical and electronics manufacturing plants.
- Optical Turbidity Platforms:Utilities are replacing manual nephelometric sampling with continuous optical monitoring to detect distribution network contamination events within minutes rather than days.
Market Restraints
- Electrode Consumables Cost Volatility:pH and dissolved oxygen sensors require frequent membrane and electrolyte replacement, creating recurring opex burdens that strain municipal maintenance budgets.
- Calibration Drift:Electrochemical architectures suffer from reference electrode poisoning and temperature sensitivity, necessitating labor-intensive field recalibration protocols that reduce effective uptime.
- Optical Fouling:Turbidity sensors deployed in high-solids industrial effluent face optical window coating that degrades measurement accuracy without automated cleaning systems.
Strategic Opportunities
- India Ganga Basin Municipalities:Central government funding for smart city water infrastructure creates deployment openings for dissolved oxygen and conductivity monitoring networks in secondary cities.
- EU Drinking Water Directive Revisions:Updated parametric values for emerging contaminants mandate expanded monitoring scope at treatment plant intakes and distribution endpoints.
- AI-Enabled Predictive Maintenance:Machine learning algorithms applied to sensor drift patterns enable just-in-time calibration scheduling, reducing field service costs for distributed instrumentation networks.
Industry Challenges
- Electrochemical Specialist Talent Scarcity:Field technicians capable of troubleshooting reference electrode failures and interpreting potentiometric drift signatures remain concentrated among legacy instrumentation vendors.
- Legacy SCADA Integration Friction:New optical and ultrasonic platforms must communicate through proprietary protocols of decades-old distributed control systems deployed across European process industries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quality Monitoring Sensor for Water Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Sensor, Turbidity Sensor, Dissolved Oxygen Sensor, Conductivity Sensor Application: Wastewater Treatment, Aquaculture, Drinking Water Monitoring, Industrial Process Technology: Optical Technology, Electrochemical Technology, Ultrasonic Technology, Remote Sensing End User: Municipalities, Environmental Agencies, Research Institutions, Industrial Facilities |
| Companies Covered | Xylem Inc., Thermo Fisher Scientific Inc., Danaher Corporation, Hach Company, ABB Ltd., Siemens AG, Endress+Hauser Group, Honeywell International Inc., Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quality Monitoring Sensor for Water Market Trends and Innovations
Digital sensing architectures and predictive analytics are compressing the traditional separation between field instrumentation and centralized water quality management platforms across treatment and distribution networks.
Photonic integrated circuit technology is collapsing the cost structure of multi-wavelength optical sensors. Silicon photonics platforms now embed spectrometric capability directly onto chip-scale modules, enabling simultaneous detection of turbidity, UV254 absorbance, and fluorescence signatures. German municipal utilities are piloting these devices at drinking water treatment intakes, where the technology is collapsing the price premium previously commanded by laboratory-grade analyzers for organic carbon surrogate monitoring.
REACH chemical registration requirements under the EU Water Framework Directive are expanding aquatic toxicity testing obligations for industrial discharge permit holders. Manufacturers must now document chronic and acute ecotoxicity profiles for formulated products containing priority substances. Electronics plating facilities in the Netherlands and Belgium are responding by installing continuous heavy metal sensors at process effluent points to demonstrate compliance with derived no-effect concentration limits.
Outcome-based service contracts are displacing capital purchase models for municipal sensor deployments. French and Japanese water utilities now contract for guaranteed data availability rather than equipment ownership, transferring calibration, maintenance, and replacement liability to instrumentation providers. This reconfiguration concentrates vendor risk in regions with aging distribution infrastructure where sensor failure rates exceed design specifications.
Quality Monitoring Sensor for Water Market Segmentation
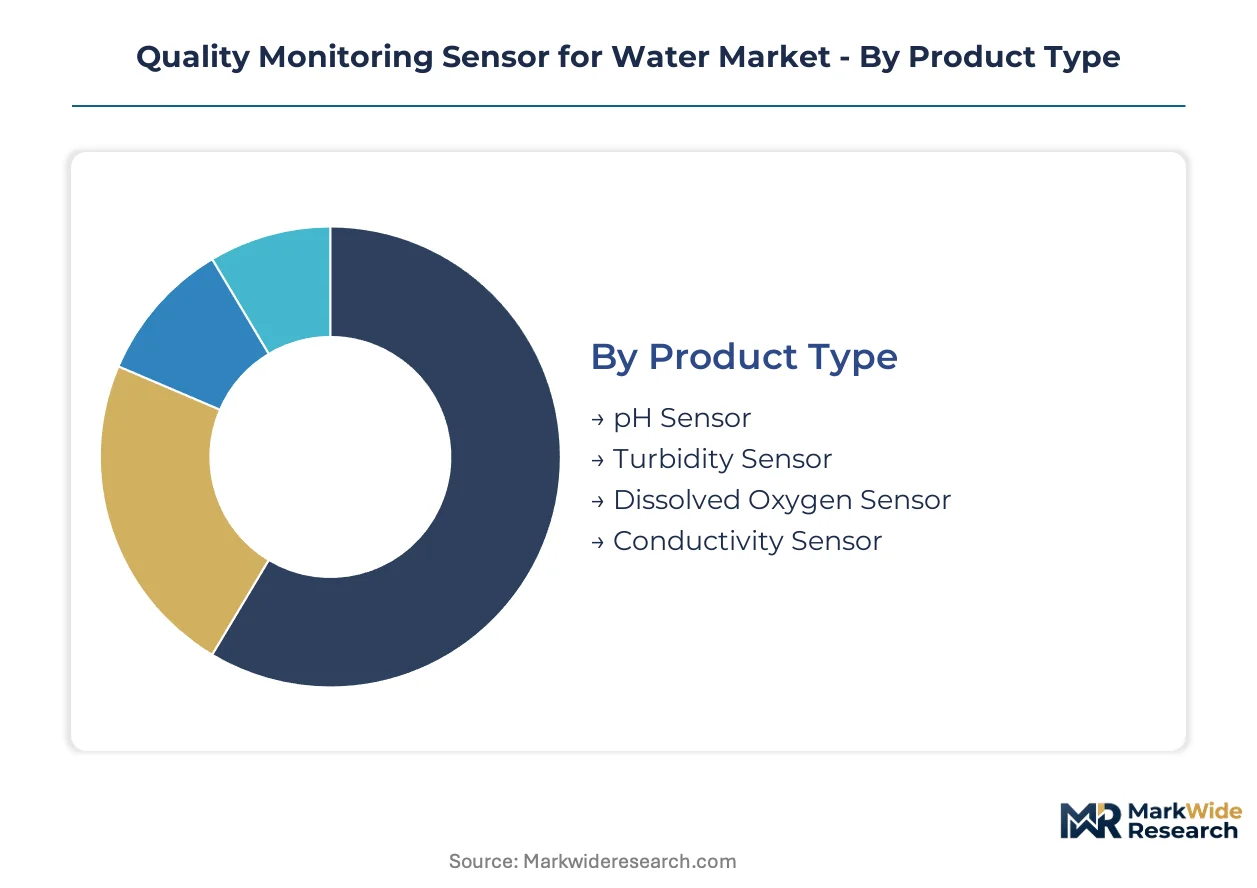
Water quality monitoring sensors fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct procurement patterns, performance requirements, and vendor competitive dynamics that shape market structure.
Product Type:
Cost tier differentiation separates commodity electrochemical probes from premium optical platforms with integrated telemetry.
- pH Sensor:Glass electrode assemblies with reference junctions measure hydrogen ion activity across 0-14 range with ±0.02 accuracy. Municipal treatment plants in Germany and Japan deploy these universally for coagulation control and corrosion management. Electrode consumables create recurring revenue streams that strain maintenance budgets.
- Turbidity Sensor:Nephelometric optical platforms detect scattered light at 90-degree angles to quantify suspended solids. Utilities across the United States are replacing manual grab sampling with continuous monitoring to detect distribution network contamination within minutes. Optical fouling in high-solids environments demands automated cleaning systems.
- Dissolved Oxygen Sensor:Membrane-covered electrochemical cells or luminescent optical patches quantify molecular oxygen for biological process control.
- Conductivity Sensor:Four-electrode or toroidal inductive designs measure ionic concentration for salinity tracking and leak detection.
pH sensors hold installed capacity. Turbidity sensors are rotating up the share rankings.
Application:
Application context dictates sensor specification, calibration frequency, and data logging requirements across regulatory and operational environments.
- Wastewater Treatment:Activated sludge basins require continuous dissolved oxygen feedback for aeration optimization. Facilities under EPA NPDES permits in the United States install multi-parameter arrays for real-time discharge compliance reporting. Biological nutrient removal processes demand redundant sensor configurations.
- Drinking Water Monitoring:Distribution network sentinel points deploy chlorine residual and turbidity sensors for regulatory compliance under the Safe Drinking Water Act. German utilities pilot photonic integrated circuit platforms at treatment intakes for organic carbon surrogate detection. Continuous monitoring replaces laboratory grab sampling for Cryptosporidium early warning.
- Aquaculture:Dissolved oxygen and pH sensors maintain optimal conditions for intensive fish farming operations.
- Industrial Process:Boiler feedwater and cooling tower applications require conductivity and silica monitoring for scaling prevention.
Wastewater treatment commands the largest equipment footprint. Drinking water monitoring is climbing the fastest.
Technology:
Technology architecture determines capital expenditure, operational maintenance burden, and measurement precision trade-offs.
- Electrochemical Technology:Potentiometric and amperometric cells dominate unit volume through lower per-node cost and established calibration protocols. pH and dissolved oxygen electrodes require frequent membrane replacement and electrolyte replenishment. Reference electrode poisoning and temperature sensitivity generate calibration drift that reduces effective uptime.
- Optical Technology:Photonic integrated circuits embed spectrometric capability onto chip-scale modules for simultaneous multi-wavelength detection. Silicon photonics platforms collapse the price premium of laboratory-grade analyzers for UV254 absorbance and fluorescence monitoring. German municipal utilities pilot these devices for organic carbon surrogate detection at drinking water intakes.
- Ultrasonic Technology:Non-contact acoustic methods measure flow-coupled parameters without fouling susceptibility.
- Remote Sensing:Satellite and aerial platforms command premium positioning for watershed-scale surveillance where physical access remains impractical.
Electrochemical technology maintains volume leadership. Optical platforms are gaining share fastest.
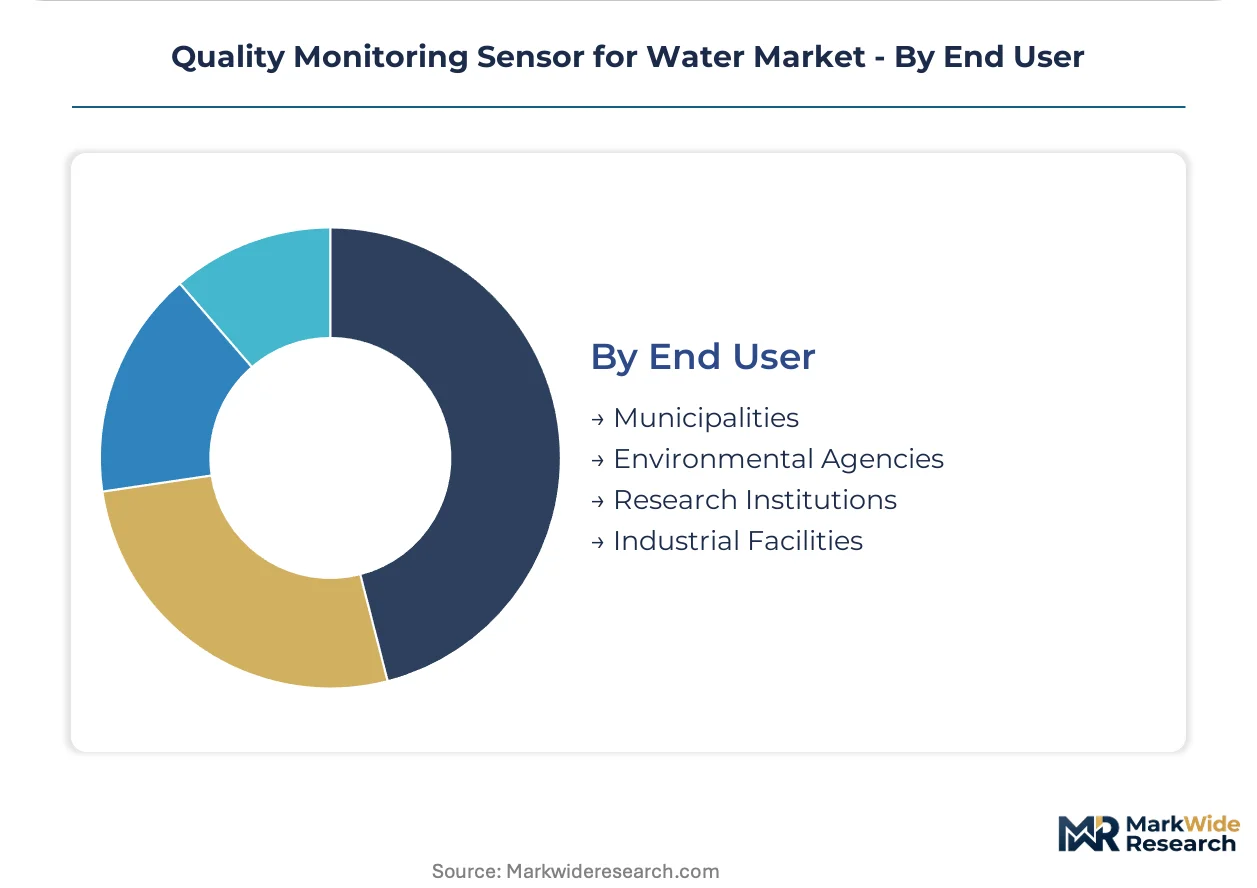
End User:
Customer type shapes procurement modality, service level expectations, and financing structure for sensor deployments.
- Municipalities:Public water utilities operate under rate-regulated capital constraints that favor sensor-as-a-service leasing over equipment ownership. French and Japanese utilities contract for guaranteed data availability, transferring calibration and replacement liability to vendors. Aging distribution infrastructure elevates sensor failure rates above design specifications.
- Industrial Facilities:Chemical and electronics plants in China's Yangtze River Delta face provincial environmental bureau mandates for continuous online discharge monitoring. REACH registration requirements under the EU Water Framework Directive compel manufacturers to document aquatic toxicity profiles through continuous heavy metal detection. Outcome-based service contracts displace capital purchase models.
- Environmental Agencies:Regulatory bodies deploy reference-grade instrumentation for enforcement monitoring and watershed assessment.
- Research Institutions:Academic and government laboratories require high-precision platforms for method development and validation studies.
Municipalities anchor equipment demand. Industrial facilities are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utilities and industrial discharge permit holders concentrate equipment procurement across Germany, Japan, the United States, China, and India. Each geography imposes distinct regulatory compliance frameworks and infrastructure investment cycles that shape sensor deployment patterns.
United States
EPA NPDES enforcement mandates continuous discharge monitoring for industrial facilities. The Clean Water Act compels real-time parameter logging and automated reporting compliance. Texas and California chemical clusters deploy multi-parameter sensor arrays at process effluent points.
Germany
Municipal utilities pilot photonic integrated circuit platforms at drinking water treatment intakes. The EU Water Framework Directive and REACH chemical registration rules expand aquatic toxicity testing obligations. Bavarian and North Rhine-Westphalian utilities contract for guaranteed data availability under outcome-based service arrangements.
China
Provincial environmental bureaus in the Yangtze River Delta mandate continuous online discharge monitoring. MEE pollution source monitoring regulations enforce real-time data transmission for key polluting enterprises. Shanghai and Suzhou electronics plating facilities install heavy metal sensors to demonstrate compliance.
Japan
Water utilities adopt sensor-as-a-service leasing models for distribution network surveillance. METI industrial standards guide instrumentation procurement for process optimization. Tokyo and Osaka metropolitan utilities deploy dissolved oxygen and turbidity sensors for real-time quality monitoring.
India
Central government funding for smart city water infrastructure creates deployment openings in secondary cities. State pollution control boards implement continuous monitoring mandates for industrial clusters. Maharashtra and Gujarat municipalities expand dissolved oxygen and conductivity monitoring networks.
Quality Monitoring Sensor for Water Market Competitive Landscape
Channel-controlling players compete with product-specialist players across municipal utility and industrial process verticals. The vendor base organizes around instrumentation conglomerates with vertical software integration, electrochemical sensor specialists with intensive R&D programs, and regional fabricators with application-specific dissolved oxygen platforms. Dominant competitive moves include backward integration into analytics software and geographic expansion through outcome-based service contracting.
Within the instrumentation conglomerate tier, Xylem Inc. and Danaher Corporation exemplify channel-control strategies through captive supply of analytics platforms. Endress+Hauser Group occupies a position among European process industry specialists with application-specific platform development. These three anchors demonstrate how competitive positioning stratifies between capital-light leasing entrants and vertically integrated incumbents.
| Leading Market Players |
|---|
| Xylem Inc. |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Hach Company |
| ABB Ltd. |
| Siemens AG |
| Endress+Hauser Group |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Others |
Pricing and Supply Chain Analysis
Electrode membrane and electrolyte supply concentration in Germany and Japan determines both tiered pricing spreads across electrochemical and optical architectures and supply chain resilience for municipal utility procurement. Single-source dependency on specialty glass formulations for pH sensor reference junctions compresses margin buffers for mid-tier vendors while concentrating pricing power among integrated incumbents.
Pricing Analysis
Cost-plus contracts with precious metal indexation dominate municipal utility procurement for dissolved oxygen and conductivity sensors. Three-tier pricing structure across premium, standard, and economy levels separates photonic integrated circuit platforms from membrane-covered electrochemical cells and commodity ultrasonic probes. Price differentiation rests on ISO 9001 certification tier and after-sales calibration service bundling. Cost compression in economy-tier electrochemical nodes is intensifying because Chinese provincial environmental bureaus mandate volume procurement for Yangtze River Delta manufacturing corridors. Industrial facilities under EPA NPDES enforcement exhibit lowest price sensitivity due to compliance penalty exposure, while secondary Indian municipalities face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for optical sensor windows draws from German specialty glass manufacturers, Japanese precision ceramic fabricators, and Chinese rare-earth coating suppliers. Silicon photonics wafers source from Taiwan foundries, luminescent optical patches from South Korea, and electrochemical membrane substrates from the United States. Single-source vulnerability concentrates in germanium-doped glass for near-infrared turbidity detection. Distribution runs through instrumentation conglomerates with captive service networks rather than independent channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EPA NPDES mandates and EU Water Framework Directive enforcement create switching cost moats around installed sensor networks. Compliance data continuity requirements lock municipal utilities into incumbent calibration and replacement protocols.
For Market Incumbents: Build switching cost moats through embedded analytics software integration that ties sensor hardware to centralized water quality management platforms. Deepen backward integration into photonic integrated circuit manufacturing to collapse optical platform cost structures and defend against silicon photonics specialists. Secure capacity expansion in India's Maharashtra and Gujarat corridors ahead of smart city infrastructure deployment waves. For New Entrants and Emerging Players: Establish a beachhead in AI-enabled predictive maintenance services for distributed electrochemical sensor networks where legacy vendors lack algorithmic competency. Target India's Ganga Basin secondary municipalities with sensor-as-a-service leasing models that bypass capital budget constraints. Pursue white-label optical turbidity platform supply to European process industry specialists seeking to bypass Endress+Hauser's application-specific dominance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors electrochemical sensor specialists with intensive R&D programs and established calibration service infrastructures. Acquisition targets should demonstrate captive relationships with German or Japanese municipal utilities under long-term outcome-based contracts. Watch for MEE enforcement intensity in China's Yangtze River Delta as the inflection indicator for industrial demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Manufacturing Scale-Up | Collapses laboratory-grade analyzer price premiums for German municipal drinking water intakes. |
| Sensor-as-a-Service Leasing Platform Launch | Transfers calibration liability to vendors in French and Japanese utility markets. |
| Predictive Maintenance Algorithm Development | Reduces field service costs for distributed instrumentation networks through drift pattern machine learning. |
| Outcome-Based Service Contract Expansion | Concentrates vendor risk in regions with aging distribution infrastructure above design specifications. |
| Backward Integration into Specialty Glass Production | Secures reference junction supply for pH sensor electrode consumables against membrane cost volatility. |
Research Methodology
Cross-validation between regulatory filing analysis and instrumentation procurement databases anchors the qualitative findings on EPA NPDES permit holder sensor deployment patterns. Primary interviews with municipal utility operations directors, industrial environmental compliance officers, electrochemical sensor R&D leads, and water treatment plant maintenance supervisors combined with secondary validation through EPA enforcement and compliance history online, EU ECHA REACH registration databases, China MEE pollution source monitoring disclosures, and SEC 10-K instrumentation segment filings. Bottom-up unit deployment estimates triangulate against top-down market value reconstruction.
Calibration against historical sensor replacement cycles and regulatory mandate implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application context, technology architecture, end user procurement modality, and regional regulatory enforcement intensity. CAGRs derived from logistic diffusion curves fitted to municipal infrastructure investment cycles and industrial discharge permit renewal patterns. Industry-specific forecast inputs incorporate electrode consumables replacement frequency distributions and optical fouling incident rates in high-solids effluent environments.
Stress conditions across precious metal price volatility, MEE enforcement intensity variation, and photonic integrated circuit yield rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory mandate adherence timelines and infrastructure depreciation schedules. Cross-checking against utility capital expenditure survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Smart Water Monitoring Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Soil Remediation Technologies Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Industrial Site Carbon Footprint Verification and Metering Test Equipment Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Environmental Test Equipment Market