
 Point of Care Blood Testing Devices Market | 2026-2036
Point of Care Blood Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Point of Care Blood Testing Devices Market Analytics
Asset-light leasing models for diagnostic equipment are rewriting competitive entry barriers in point-of-care diagnostics. Abbott leverages captive supply chains for glucose strip manufacturing to sustain margin control across retail and clinical channels. Siemens Healthineers anchors European hospital procurement through integrated analyzer-to-software platforms that dominate enterprise contracts.
Point of care blood testing devices are portable or benchtop instruments that analyze whole blood, plasma, or serum using electrochemical or optical detection methods with turnaround times under fifteen minutes, primarily enabling clinical decision-making outside centralized laboratories. Glucose meters occupy the largest installed base due to diabetes prevalence, while lateral flow infectious disease testing represents the fastest expansion corridor as antimicrobial stewardship programs push rapid pathogen identification to bedside and pharmacy settings. Coagulation monitors retain premium pricing power in anticoagulation clinics where INR precision directly guides dosing decisions.
The FDA's CLIA waiver program and the EPA's medical waste disposal standards shape device design requirements and site certification pathways for US manufacturers. In Europe, the MDR and IVDR frameworks impose stricter clinical evidence thresholds that delay market access for novel assay formats. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether to prioritize FDA 510(k) clearance speed or MDR conformity assessment depth in product development roadmaps.
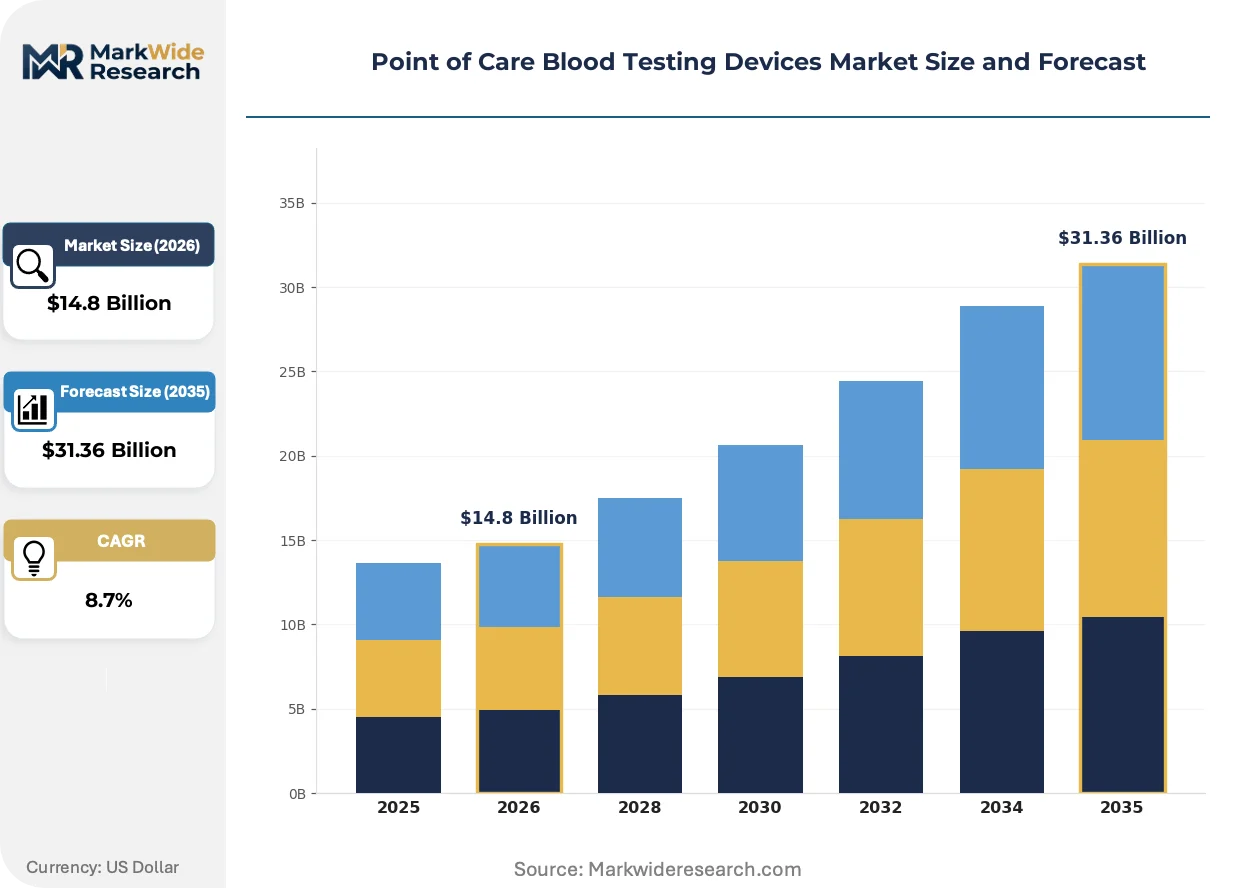
Market Dynamics
The Point of Care Blood Testing Devices Market is experiencing structural pressure from the FDA's accelerated CLIA waiver pathway, which compresses development timelines while simultaneously fragmenting competitive moats through faster non-laboratory device approvals.
Growth Catalysts
- CLIA Waiver Expansion:The FDA's streamlined moderate complexity test exemptions are unlocking pharmacy and retail clinic deployment for glucose and coagulation assays.
- Antimicrobial Stewardship Mandates:Hospital infection control protocols are embedding rapid infectious disease testing at bedside to shorten antibiotic initiation windows.
- Electrochemical Sensor Miniaturization:Advances in printed electrode fabrication are reducing analyzer footprints for home care glucose monitoring.
Market Restraints
- Precious Metal Input Volatility:Platinum and palladium price swings in electrochemical sensor electrodes compress gross margins on disposable strips.
- IVDR Conformity Assessment Bottlenecks:Europe's stricter clinical evidence requirements for novel assay formats delay market entry by 18-24 months versus FDA pathways.
- Optical Detection Substitution:Smartphone-integrated colorimetric readers threaten standalone lateral flow analyzer volumes in low-acuity settings.
Strategic Opportunities
- India's Diagnostic Infrastructure Gap:Tier-2 and Tier-3 city clinics present untapped demand for portable coagulation and infectious disease testing outside centralized lab networks.
- Remote Patient Monitoring Integration:Bluetooth-enabled glucose meters converging with telehealth platforms are creating recurring revenue streams through subscription data services.
- EPA Medical Waste Streamlining:Relaxed disposal standards for single-use lancets and test strips in non-hazardous waste categories reduce site certification costs for retail pharmacy deployment.
Industry Challenges
- CLIA Waiver Technical Validation:Demonstrating operator-independent precision across untrained user populations requires extensive usability studies that extend development timelines.
- Interoperability Architecture:Integrating point-of-care data streams with hospital EHR systems demands HL7 FHIR compliance investments that strain mid-cap device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point of Care Blood Testing Devices Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Hemoglobin A1c Testers, Coagulation Monitors, Cholesterol Test Kits End User: Clinics, Home Care, Hospitals, Emergency Services Technology: Electrochemical, Optical, Lateral Flow, Microarray Application: Diabetes Management, Cardiac Monitoring, Infectious Disease Testing, Coagulation Testing |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, BD, bioMérieux, Thermo Fisher Scientific Inc, QIAGEN, QuidelOrtho Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point of Care Blood Testing Devices Market Evolving Landscape
Microfluidic cartridge architectures and smartphone-connected biosensors are collapsing the boundary between consumer wellness and clinical-grade diagnostics, forcing traditional device manufacturers to defend against consumer electronics entrants.
Lab-on-a-chip microfluidic platforms integrating sample preparation, reaction, and detection in disposable cartridges are rendering obsolete benchtop analyzers requiring manual pipetting and wash steps. Anticoagulation clinics and emergency departments are adopting these closed-system devices to eliminate operator variability in INR and cardiac marker testing. The technology is rendering obsolete the installed base of open-platform chemistry analyzers that dominated hospital point-of-care networks for two decades.
The EU IVDR's expanded clinical performance study requirements for Class C and D devices are redirecting R&D budgets toward retrospective evidence generation rather than novel assay development. Manufacturers are prioritizing 510(k) predicate pathways in the United States to secure revenue while awaiting European notified body capacity. Cardiac marker and sepsis biomarker assays face the steepest compliance burden under these rules.
Hospital procurement committees are unbundling analyzer hardware from reagent supply contracts to negotiate separate pricing tiers. IDN consolidation in the United States is concentrating purchasing power among ten major systems that demand open-architecture connectivity and third-party assay compatibility. This contract restructuring is most visible in the Southeast and Midwest regions where Catholic health system mergers have created multi-state procurement entities.
Point of Care Blood Testing Devices Market Segmentation
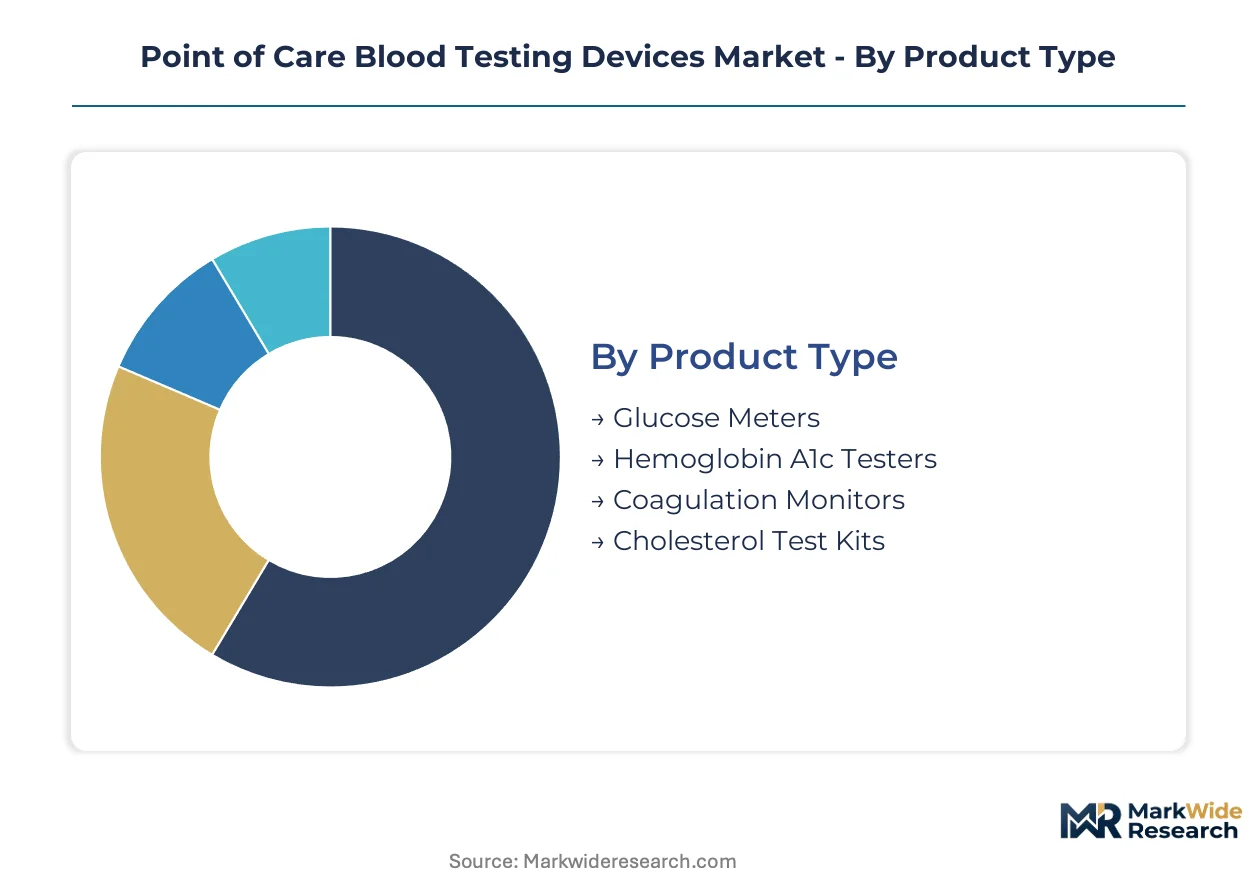
Segmentation in point of care blood testing devices reveals distinct service intensity profiles across product categories. Glucose meters demand continuous strip replenishment and calibration support, while infectious disease platforms require training-heavy deployment protocols that reshape vendor economics.
Product Type:
After-sales service intensity varies dramatically across device categories, with consumables-driven segments demanding perpetual supply chain engagement versus capital equipment requiring episodic maintenance.
- Glucose Meters:Handheld electrochemical analyzers utilizing disposable enzyme-impregnated strips for capillary whole blood glucose quantification. Home care deployment in the United States generates recurring strip revenue streams that exceed hardware margins by an order of magnitude, though platinum electrode cost volatility compresses disposable profitability.
- Coagulation Monitors:Benchtop or portable systems measuring prothrombin time and INR through amperometric detection of thrombin generation. Anticoagulation clinics in Germany and France sustain premium pricing through dosing decision dependency, with each device supporting 200-300 patient visits monthly.
- Hemoglobin A1c Testers:Boronate affinity or immunoassay-based systems for glycated hemoglobin quantification in diabetes monitoring protocols.
- Cholesterol Test Kits:Enzymatic dry chemistry strips or cuvette-based systems for lipid panel screening in pharmacy and workplace wellness settings.
By volume, glucose meters lead. By growth pace, coagulation monitors are ahead.
End User:
Procurement authority concentration determines contract structure complexity, with consolidated hospital systems extracting multi-year service bundling versus fragmented home care channels favoring retail distribution.
- Home Care:Patient-operated devices for chronic disease self-monitoring with direct-to-consumer or pharmacy-mediated acquisition. Bluetooth-enabled meters in the United States are converging with telehealth reimbursement codes that reward remote glucose data transmission, creating subscription revenue attachments.
- Hospitals:Enterprise procurement of multiplexed analyzers for emergency department and surgical unit deployment. IDN consolidation across the American Midwest has produced ten multi-state purchasing entities demanding open-architecture HL7 FHIR connectivity.
- Clinics:Physician office laboratories operating under CLIA-waived or moderate complexity certification for rapid diagnostics.
- Emergency Services:Pre-hospital and ambulance-deployed devices requiring ruggedized construction and extreme temperature operational tolerance.
By installed base, home care dominates. By contract value per seat, hospitals command premium positioning.
Technology:
Detection modality selection locks manufacturers into distinct component supply chains and regulatory validation pathways that persist across product generations.
- Electrochemical:Amperometric or potentiometric transduction utilizing screen-printed electrodes with enzyme or mediator coatings. Printed electrode fabrication advances in South Korea and Japan are reducing analyzer footprints for home glucose monitoring while palladium price hedging consumes working capital.
- Lateral Flow:Immunochromatographic capillary-driven assays with visual or reader-based quantification. Antimicrobial stewardship mandates in United Kingdom NHS trusts are embedding rapid infectious disease identification at bedside, displacing send-out microbiology workflows.
- Optical:Reflectance photometry or fluorescence detection for colorimetric reaction endpoint measurement.
- Microarray:Multiplexed nucleic acid or protein detection on solid substrates for simultaneous biomarker panel analysis.
By unit shipments, electrochemical sensors lead. By assay menu expansion potential, microarray platforms are climbing the fastest.
Application:
Clinical utility urgency shapes price elasticity, with time-critical cardiac and sepsis applications sustaining markup levels that chronic disease monitoring cannot command.
- Diabetes Management:Glucose and ketone monitoring for insulin dosing guidance across Type 1 and Type 2 populations. India's tier-2 city clinics present deployment opportunities outside centralized lab networks, though strip cold chain integrity remains problematic in ambient storage conditions.
- Infectious Disease Testing:Rapid antigen or molecular detection for respiratory, sexually transmitted, and nosocomial pathogens. CLIA waiver expansion for pharmacy-based streptococcal and influenza testing in the United States is unlocking retail clinic volume previously captured by urgent care centers.
- Cardiac Monitoring:Troponin, BNP, and D-dimer quantification for acute coronary syndrome and heart failure triage.
- Coagulation Testing:INR and aPTT monitoring for warfarin and heparin therapeutic management.
By patient touchpoints, diabetes management leads. By reimbursement rate acceleration, infectious disease testing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in point-of-care blood testing devices, exporting electrochemical sensor platforms to European and Asian markets while importing specialized microfluidic cartridges from German and Japanese suppliers. Import volumes concentrate on high-complexity coagulation analyzers not manufactured domestically.
United States
Chronic disease prevalence and Medicare reimbursement for remote patient monitoring sustain demand for home glucose meters and cardiac biomarker platforms. The FDA's CLIA waiver expansion accelerates pharmacy-based deployment of rapid infectious disease tests. Device manufacturing clusters in Massachusetts and California supply electrochemical strip production for North American distribution networks.
Germany
Anticoagulation clinic density and statutory health insurance coverage for INR self-monitoring sustain premium coagulation analyzer demand. The MDR and IVDR frameworks impose extended clinical evidence requirements that delay novel assay market entry. Industrial concentration in Baden-Württemberg hosts precision optics manufacturing for optical detection modules serving European hospital procurement.
China
Domestic diabetes prevalence and tiered hospital reform policies redirect diagnostic volumes toward primary care settings. The NMPA accelerates registration pathways for imported glucose meters while enforcing GB standards for electrochemical sensor calibration. Manufacturing agglomeration in the Yangtze River Delta produces disposable test strips for export markets across Southeast Asia.
India
Diagnostic infrastructure gaps in tier-2 and tier-3 cities create deployment opportunities for portable coagulation and infectious disease testing outside centralized lab networks. The CDSCO regulates device imports while PLI scheme incentives attract domestic manufacturing investment. Industrial activity in Maharashtra and Karnataka concentrates on reagent strip assembly for price-sensitive clinic segments.
Japan
Aging demographics and home care policy subsidies expand patient-operated glucose monitoring adoption. The PMDA maintains stringent clinical performance requirements for cardiac marker assays that limit foreign device penetration. Precision manufacturing clusters in Nagoya supply high-reliability electrodes for domestic and export analyzer OEMs.
Point of Care Blood Testing Devices Market Competitive Landscape
On the supply side, the industry is consolidating around integrated diagnostic platforms that bundle hardware, consumables, and data connectivity. Large diversified health technology conglomerates occupy the premium tier, mid-cap specialists defend niches in electrochemical sensor fabrication, and emerging entrants leverage smartphone integration to bypass traditional analyzer distribution. Competitive moves center on backward integration into precious metal electrode supply chains and strategic partnerships with telehealth platforms for remote monitoring data monetization.
Among diversified health technology conglomerates, Abbott, Siemens Healthineers AG, and Danaher Corporation exemplify the integrated platform archetype. Abbott represents captive supply chain control through in-house glucose strip manufacturing. Siemens Healthineers AG occupies a position anchoring European hospital enterprise contracts through analyzer-to-software integration. Danaher Corporation sits within the life sciences tools segment, exemplifying portfolio diversification across diagnostic consumables and analytical instrumentation. These three entities collectively illustrate the competitive imperative of spanning both clinical and home care channels while managing regulatory divergence between FDA and IVDR pathways.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| BD |
| bioMérieux |
| Thermo Fisher Scientific Inc |
| QIAGEN |
| QuidelOrtho Corp |
| Others |
Value Network & Pricing Analysis
Platinum and palladium electrode fabrication concentrates in South Korean and Japanese precision foundries, tethering downstream glucose meter profitability to precious metal commodity desks and captive hedging programs at Abbott and Roche. This upstream concentration funnels margin pools toward consumables manufacturers who control strip chemistry formulation, while hardware OEMs face persistent cost compression on analyzer units sold through retail pharmacy channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA CLIA waiver certification grade and after-sales calibration service bundling. Cost compression in economy-tier home glucose meters is intensifying because smartphone-integrated colorimetric readers displace standalone analyzers. Hospital procurement committees exhibit least price sensitivity due to dosing decision dependency, while retail pharmacy distributors face acute margin pressure.
Supply Chain Analysis
Contract manufacturing capacity for electrochemical sensor electrodes concentrates at South Korean printed electronics specialists and Japanese precision coating houses, with secondary capacity in Massachusetts and Baden-Württemberg. Raw material feeds draw from Russian and South African platinum group metal suppliers, German precision optics for optical detection modules, and Chinese plastic molding for disposable cartridge housings. Single-source vulnerability in palladium electrode supply creates exposure to commodity price volatility. Distribution runs through GPO contracts for hospital systems, retail pharmacy chains for home care, and direct-to-clinic shipments for anticoagulation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's accelerated CLIA waiver pathway constitutes a regulatory inflection that compresses development timelines and fragments competitive moats, positioning point-of-care diagnostics for sustained high-growth disruption as non-laboratory testing penetrates pharmacy and retail clinic settings.
For Market Incumbents: Insulate consumables revenue streams through backward integration into precious metal electrode supply chains and exclusive long-term service contracts with IDN procurement entities. Smartphone-integrated biosensor entrants threaten standalone analyzer volumes, demanding defensive software companion development for Bluetooth-enabled glucose meters to lock in subscription data revenue. For New Entrants and Emerging Players: Build out microfluidic cartridge platforms targeting India's tier-2 and tier-3 city clinics where diagnostic infrastructure gaps persist outside centralized lab networks. The most penetrable white space sits in portable coagulation testing for anticoagulation clinics in price-sensitive emerging markets, with go-to-market leverage through telehealth platform partnerships enabling remote INR monitoring subscriptions. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap electrochemical sensor specialists with captive printed electrode fabrication and established FDA 510(k) predicate pathways. Long-term viability over the coming decade hinges on regulatory agility across divergent FDA and IVDR frameworks. The critical signal to watch is notified body capacity expansion in Europe, which would unlock delayed revenue from novel cardiac marker and sepsis biomarker assays currently stalled in MDR conformity assessment bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Expansion | Accelerates pharmacy-based deployment of rapid infectious disease tests in United States retail clinic networks. |
| Backward Integration into Electrode Supply | Captures margin pools in platinum and palladium sensor fabrication for glucose strip manufacturers. |
| Telehealth Platform Partnership | Creates recurring subscription revenue from Bluetooth-enabled glucose meter data transmission to remote monitoring services. |
| Microfluidic Cartridge Development | Eliminates operator variability in INR and cardiac marker testing for anticoagulation clinics and emergency departments. |
| IVDR Conformity Assessment Preparation | Secures European market access for novel assay formats amid extended clinical evidence requirements under MDR frameworks. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineers at anticoagulation clinics, GPO contracts specialists, and regulatory affairs leads at device manufacturers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contract disclosures, and electrochemical sensor patent filings. Bottom-up unit shipment estimates triangulated against top-down market sizing across glucose meter, coagulation monitor, and infectious disease testing segments.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling volume and value outputs through segmentation across product type, end user, technology, and application dimensions. CAGRs derived from fitted growth curves applied to installed base expansion and consumables replenishment rates. Forecast inputs incorporated CLIA waiver approval velocity, precious metal commodity price trajectories, and IDN consolidation patterns in United States hospital procurement.
Practitioners should monitor FDA CLIA waiver expansion scope, European notified body capacity for IVDR assessments, and palladium price volatility for early signals of forecast revision. Quarterly review of pharmacy-based test deployment rates and telehealth reimbursement code expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Procalcitonin Antibody Market
Diagnostic Devices
Europe Breath Analyzer Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
Biopsy Devices Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Counterfeit Drug Detection Device Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market