
 Lung Biopsy Systems Market | 2026-2036
Lung Biopsy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lung Biopsy Systems Market Foresight
The divergence between premium navigation bronchoscopy platforms and commodity needle biopsy kits is hardening across procurement channels. Olympus Corporation leverages its integrated imaging-to-intervention portfolio to sustain premium positioning in academic medical centers. Medtronic anchors the electromagnetic navigation segment through dedicated lung access platforms, while Boston Scientific Corporation competes on disposable instrument ecosystems that reduce reprocessing overhead.
Lung biopsy systems comprise integrated instrument platforms, imaging modalities, and tissue acquisition devices designed to extract pulmonary specimens with minimal invasiveness; core specifications include navigation accuracy within 2-3 mm, working channel diameters of 2.0-2.8 mm, and compatibility with fluoroscopic or CT guidance. Needle biopsy retains the largest installed base among product types, though vacuum-assisted biopsy systems command superior reimbursement rates in outpatient settings. Oncology applications dominate procedure volume, yet infectious disease indications are expanding fastest as molecular diagnostics require larger tissue yields for pathogen identification.
FDA 510(k) clearance pathways and CMS national coverage determinations shape commercialization timelines and reimbursement eligibility for novel lung biopsy technologies. The EU MDR and FDA quality system regulation impose divergent clinical evidence requirements that fragment go-to-market strategies for multinational manufacturers. Stakeholders must weigh regulatory capital intensity against the accelerating shift toward same-day biopsy procedures in ambulatory surgical centers.
Market Dynamics
Hospital procurement committees are consolidating vendor relationships around platforms that merge navigation, imaging, and tissue acquisition into single capital contracts, compressing the addressable supplier base.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement for lung cancer screening in high-risk populations drives procedure volume through Medicare Advantage networks.
- Minimally Invasive Surgery:Patient preference for same-day discharge protocols accelerates adoption of bronchoscopic platforms over percutaneous alternatives.
- Molecular Diagnostics:Next-generation sequencing requirements for oncogene panels demand larger tissue yields, favoring vacuum-assisted and core needle systems.
Market Restraints
- Capital Equipment Concentration:Electromagnetic navigation systems require proprietary disposable instrument ecosystems, locking facilities into single-vendor supply chains.
- EU MDR Compliance Burden:Recertification timelines for Class IIa/IIb devices extend commercialization cycles by 18-24 months for European market entry.
- Radiologist Training Bottlenecks:Interventional pulmonology fellowship programs graduate fewer specialists than replacement demand requires.
Strategic Opportunities
- Ambulatory Surgical Centers:Outpatient migration of low-complexity biopsies creates demand for compact, mobile-compatible platforms with reduced footprint.
- Artificial Intelligence Integration:Real-time lesion segmentation algorithms paired with electromagnetic navigation compress procedure times and reduce sampling error rates.
- Infectious Disease Applications:Rising antimicrobial resistance surveillance programs require histopathological confirmation, expanding biopsy indications beyond oncology.
Industry Challenges
- Interventional Pulmonology Workforce:Fellowship program capacity constraints limit deployment of navigation bronchoscopy to tertiary academic centers.
- Legacy PACS Integration:Proprietary imaging formats from navigation platforms create interoperability friction with hospital radiology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lung Biopsy Systems Market |
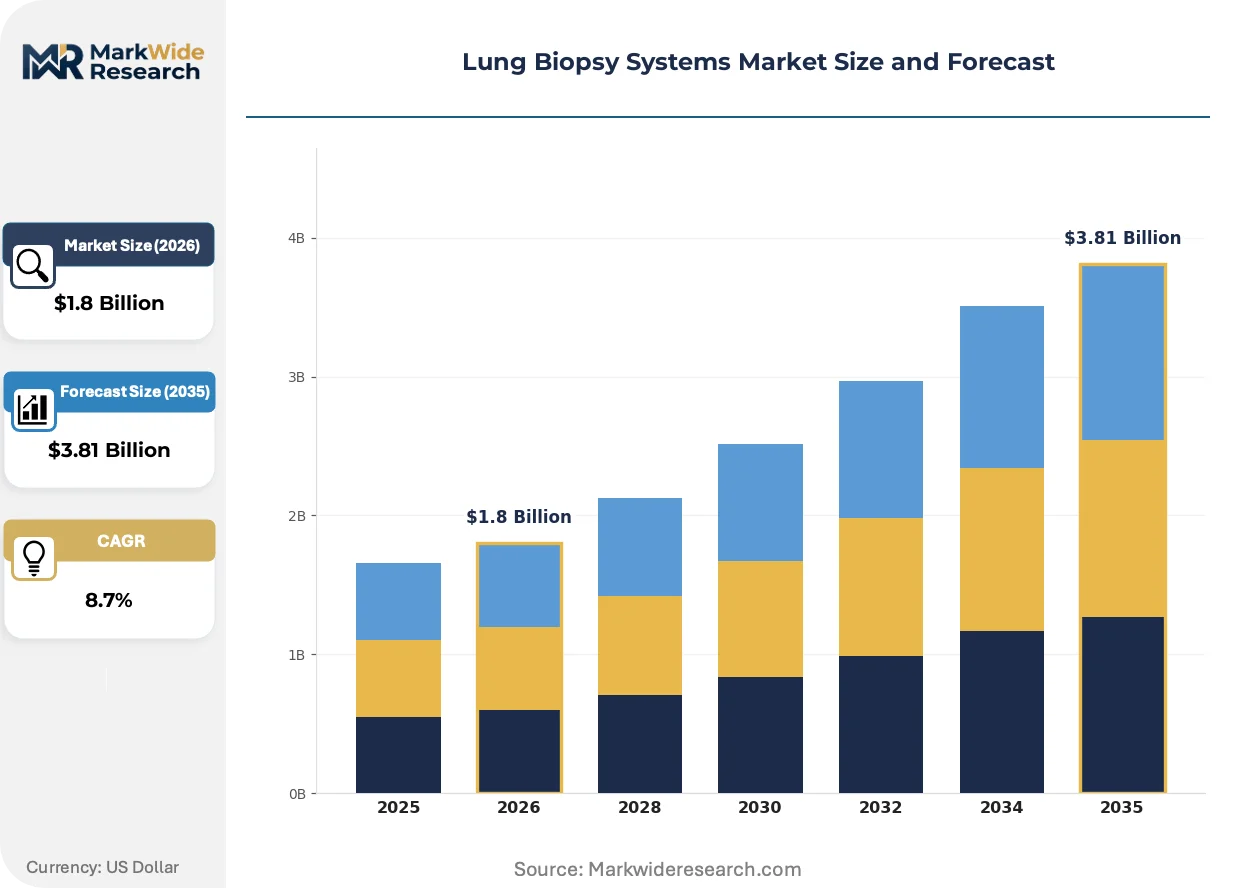
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Biopsy, Surgical Biopsy, Endobronchial Ultrasound, Vacuum-assisted Biopsy Application: Oncology, Infectious Diseases, Inflammatory Disorders, Pulmonary Fibrosis End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Clinics Delivery Mode: Online, Direct Sales, Distributors, Others |
| Companies Covered | Medtronic, Boston Scientific Corporation, Becton Dickinson and Company, Olympus Corporation, Argon Medical Devices, Hologic Inc., Cook Medical, Cardinal Health, Fujifilm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lung Biopsy Systems Market Shifts & Advancements
Convergence between robotic-assisted platforms and disposable instrument miniaturization is compressing the traditional trade-off between capital intensity and per-procedure economics.
Robotic bronchoscopy platforms are unifying navigation, visualization, and instrument control into single-operator workflows. Academic medical centers in the United States are piloting these systems for peripheral lesion access. The technology is unifying previously separate capital purchases into integrated platform contracts that reduce vendor fragmentation.
EU MDR clinical evidence requirements are forcing manufacturers to generate prospective registry data for predicate device equivalency claims. European notified bodies now demand follow-up studies for electromagnetic navigation systems previously cleared under the Medical Device Directive. German and French procurement authorities are extending tender evaluation periods to accommodate technical documentation review.
Integrated delivery networks are bundling biopsy procedures with downstream molecular pathology services under single episode-of-care contracts. Hospital systems are displacing standalone instrument vendors in favor of platform suppliers offering companion diagnostic partnerships. This consolidation is most visible in United States multi-hospital systems with captive pathology laboratories.
Lung Biopsy Systems Market Segmentation
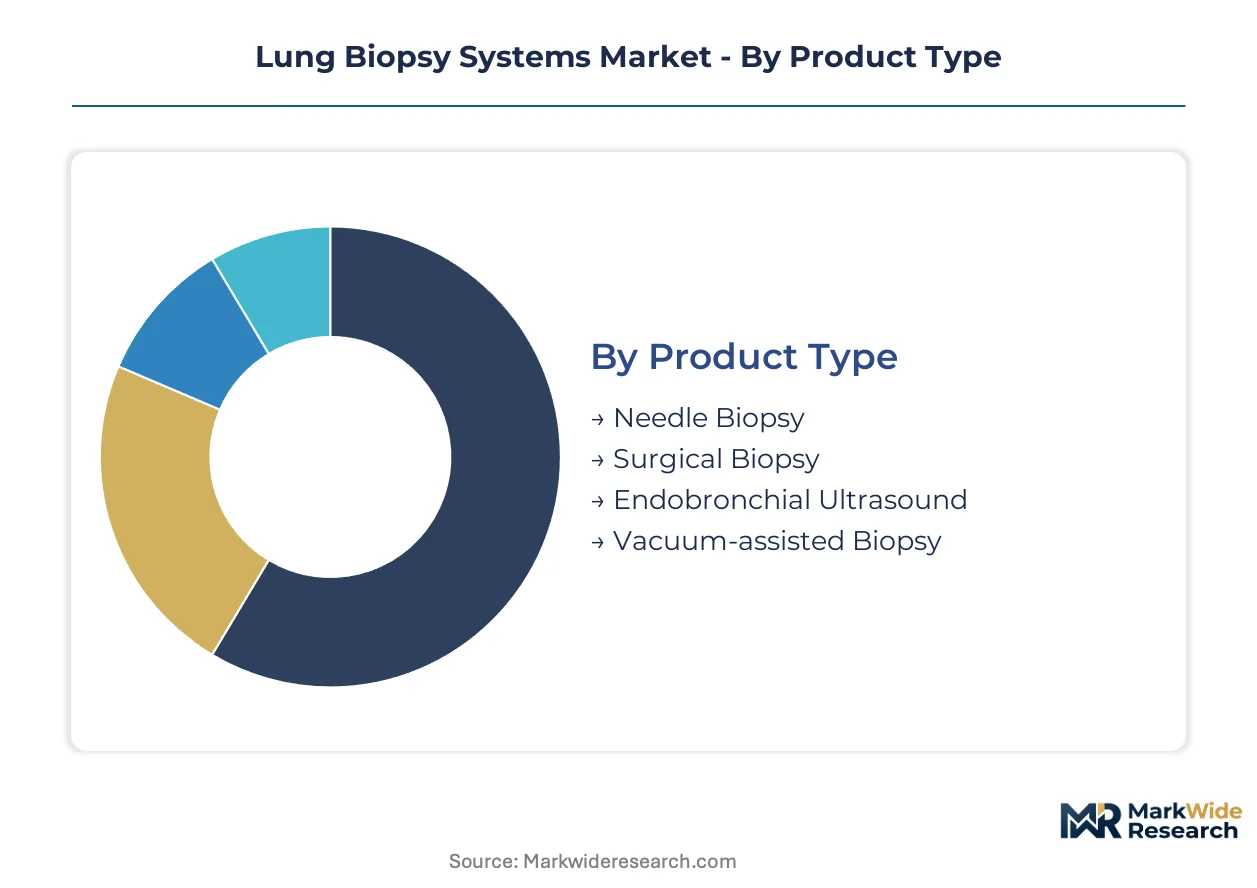
Segmentation in lung biopsy systems reveals how regulatory pathways, reimbursement tiers, and clinical workflows fragment procurement decisions across healthcare settings. Each dimension carries distinct certification burdens and capital intensity profiles that reshape vendor competitive boundaries.
Product Type:
FDA 510(k) clearance dominates needle and vacuum-assisted systems, while electromagnetic navigation platforms trigger de novo pathways; EU MDR Class IIa/IIb distinctions impose heavier clinical evidence loads on surgical and EBUS categories.
- Needle Biopsy:Percutaneous tissue acquisition via coaxial or cutting needles remains the workhorse modality, with 14-20 gauge specifications matching lesion depth and vascular proximity. United States community hospitals concentrate procurement here, constrained by interventional radiologist availability and CT suite scheduling bottlenecks.
- Vacuum-assisted Biopsy:Continuous suction mechanisms extract larger core specimens through single needle insertion, enabling molecular profiling workflows. Outpatient surgical centers in Texas and Florida favor these systems for same-day discharge protocols, though capital costs exceed standard needle kits threefold.
- Surgical Biopsy:Video-assisted thoracoscopic and open wedge resections target non-diagnostic percutaneous failures.
- Endobronchial Ultrasound:Convex-probe bronchoscopy with real-time nodal sampling requires dedicated bronchoscopy suites.
Needle biopsy sits at the top of the volume ranking, with vacuum-assisted biopsy climbing the fastest.
Application:
Oncology commands premium reimbursement rates through Medicare NCDs, while infectious disease applications face patchy coverage determination timelines that compress addressable margins.
- Oncology:Lung cancer staging drives procedure volume, with EGFR/ALK/PD-L1 testing requirements mandating adequate tissue yields. Academic medical centers in Massachusetts and California prioritize platforms supporting comprehensive genomic profiling panels.
- Infectious Diseases:Mycobacterial and fungal pathogen identification demands histopathological plus microbiological correlation. India and South Africa exhibit steepest expansion trajectory as antimicrobial resistance surveillance programs mandate tissue confirmation before targeted therapy initiation.
- Inflammatory Disorders:Sarcoidosis and granulomatosis with polyangiitis require exclusionary biopsy protocols.
- Pulmonary Fibrosis:Usual interstitial pneumonia pattern confirmation carries surgical lung biopsy risks.
Oncology maintains the revenue concentration apex, though infectious disease applications expand most rapidly in emerging markets.
End User:
Hospital capital committees negotiate bundled platform contracts spanning navigation, imaging, and pathology, while outpatient clinics face disposable instrument minimums that lock in vendor relationships.
- Hospitals:Integrated delivery networks consolidate procurement around electromagnetic navigation systems with captive pathology partnerships. Cleveland Clinic and Mayo Clinic anchor United States demand for robotic bronchoscopy platforms with same-day molecular turnaround.
- Diagnostic Centers:Independent imaging facilities concentrate on CT-guided percutaneous biopsy with outsourced pathology. Germany's outpatient radiology chains leverage MDR transition delays to negotiate favorable equipment leasing terms.
- Research Laboratories:Prospective registry generation for EU MDR predicate equivalence claims drives academic center procurement.
- Outpatient Clinics:Ambulatory surgical center migration favors compact, mobile-compatible platforms with reduced fluoroscopy footprint.
Hospitals dominate capital expenditure flows, with diagnostic centers capturing margin expansion through procedure volume aggregation.
Delivery Mode:
Direct sales organizations sustain premium positioning for navigation platforms, while distributor networks handle commodity needle kit fulfillment with compressed working capital cycles.
- Direct Sales:Electromagnetic navigation and robotic platform vendors maintain field clinical specialists for procedural training and troubleshooting. United States integrated delivery networks demand dedicated account executives for multi-hospital contract negotiation.
- Distributors:Regional medical device distributors manage inventory and logistics for disposable biopsy needles and vacuum-assisted consumables. Brazil and Mexico procurement flows concentrate through specialized interventional pulmonology distributors with regulatory registration expertise.
- Online:E-procurement portals standardize commodity instrument purchasing for cost-conscious outpatient settings.
- Others:Group purchasing organizations aggregate hospital system demand for negotiated tier pricing.
Direct sales channels anchor high-value platform penetration, with distributor networks scaling fastest in Latin American and Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional pulmonology fellowship programs in the United States graduate more specialists annually than any other country, anchoring global demand for navigation bronchoscopy platforms. Germany and Japan follow with concentrated academic medical center networks. China and India exhibit steepest procedure volume expansion as lung cancer screening programs scale.
United States
Integrated delivery networks in Massachusetts and California consolidate procurement around robotic bronchoscopy platforms with same-day molecular pathology turnaround. FDA 510(k) clearance pathways and CMS national coverage determinations accelerate commercialization timelines for electromagnetic navigation systems. The Cleveland Clinic and Mayo Clinic anchor demand for platforms merging navigation, imaging, and tissue acquisition into single capital contracts.
Germany
Outpatient radiology chains leverage EU MDR transition delays to negotiate favorable equipment leasing terms for CT-guided percutaneous biopsy systems. The country's national medical device regulator imposes heavier clinical evidence loads on Class IIa/IIb surgical and EBUS categories through prospective registry requirements. Berlin and Munich academic centers drive adoption of convex-probe bronchoscopy with real-time nodal sampling capabilities.
Japan
Metropolitan Tokyo hospitals prioritize compact, mobile-compatible platforms with reduced fluoroscopy footprint for aging population access. The Pharmaceuticals and Medical Devices Agency maintains stringent quality system regulations that fragment go-to-market strategies for multinational manufacturers. Osaka-based medical centers concentrate demand for vacuum-assisted biopsy systems enabling comprehensive genomic profiling panels.
China
Antimicrobial resistance surveillance programs in Beijing and Shanghai mandate histopathological confirmation before targeted therapy initiation, expanding biopsy indications beyond oncology. The National Medical Products Administration accelerates review timelines for domestically manufactured navigation platforms. Yangtze River Delta hospital systems pilot artificial intelligence integration for real-time lesion segmentation paired with electromagnetic navigation.
India
Mycobacterial and fungal pathogen identification demands drive steepest expansion trajectory for infectious disease biopsy applications. The Central Drugs Standard Control Organization regulates import and domestic manufacture of interventional pulmonology devices through licensing requirements. Maharashtra and Karnataka tertiary centers concentrate procurement of needle biopsy systems as community hospital constraints limit navigation bronchoscopy deployment.
Lung Biopsy Systems Market Competitive Landscape
Top-tier vendors anchor integrated platform contracts, while mid-tier disposable instrument suppliers compete on reprocessing overhead reduction. The supplier base compresses as hospital procurement committees consolidate vendor relationships around single capital purchases spanning navigation, imaging, and tissue acquisition. Two strategic archetypes dominate: diversified medical technology conglomerates with imaging-to-intervention portfolios, and interventional pulmonology specialists with electromagnetic navigation expertise. M&A activity targets complementary pathology partnerships, and capacity expansion concentrates on ambulatory surgical center-compatible platform miniaturization.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation occupy positions anchoring the electromagnetic navigation and disposable instrument ecosystem segments respectively. Olympus Corporation exemplifies the integrated imaging-to-intervention archetype through its academic medical center premium positioning. These three entities represent the competitive concentration around platform-level contracts that reduce vendor fragmentation in United States integrated delivery networks.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Becton Dickinson and Company |
| Olympus Corporation |
| Argon Medical Devices |
| Hologic Inc. |
| Cook Medical |
| Cardinal Health |
| Fujifilm Corporation |
| Others |
Supply & Pricing Matrix
Interventional pulmonologist concentration in the United States Northeast and Germany drives labor-cost differentials that separate premium navigation platform pricing from commodified needle biopsy tiers across procurement channels.
Pricing Analysis
Bundled platform contracts versus unbundled disposable instrument purchasing splits pricing structures across hospital procurement tiers. Three-tier pricing stratifies across robotic navigation systems with pathology partnerships, electromagnetic platforms with dedicated disposables, and standard needle kits for community hospitals. Price differentiation hinges on FDA 510(k) versus de novo clearance pathways and after-sales training commitments. Cost compression in the commodity needle segment is intensifying as group purchasing organizations aggregate outpatient clinic demand. Community hospitals in India and Brazil exhibit highest price sensitivity; academic medical centers in Massachusetts and California show lowest sensitivity due to captive reimbursement rates.
Supply Chain Analysis
Freight cost escalation for temperature-sensitive imaging components and sterile instrument payloads shapes regional sourcing strategies for multinational manufacturers. Electromagnetic navigation system assembly concentrates in Japan, Germany, and the United States; disposable needle fabrication clusters in China, Mexico, and India. Component sourcing draws from rare-earth magnet suppliers in China, precision optical manufacturers in Japan, and medical-grade polymer producers in Germany. Single-source vulnerability in convex-probe bronchoscope sensor supply creates chokepoint exposure. Distribution runs through direct sales organizations for capital platforms and regional medical device distributors for consumable kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance timelines extend 18-24 months versus FDA 510(k) pathways, creating first-mover cost advantages for United States-focused suppliers.
For Market Incumbents: Hedge against disposable commoditization by deepening pathology laboratory partnerships that lock hospital systems into episode-of-care contracts. Anchor electromagnetic navigation platform refresh cycles to CMS national coverage determination expansions. Prioritize captive supply of convex-probe sensors to reduce single-source exposure in bronchoscope manufacturing.
For New Entrants and Emerging Players: Ambulatory surgical centers seeking compact, mobile-compatible platforms represent the most penetrable buyer archetype currently underserved by robotic system vendors. Target infectious disease biopsy applications in India and South Africa where antimicrobial resistance surveillance programs mandate tissue confirmation. Pursue software companion development for AI lesion segmentation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Integrated delivery networks with captive pathology assets are the most active acquirer in this space, consolidating vendor relationships around single capital contracts. Long-term viability centers on platform-level bundling that displaces standalone instrument suppliers. Watch for FDA de novo clearance acceleration for robotic bronchoscopy systems as the inflection signal indicating consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic anchor demand for robotic platforms with same-day molecular pathology turnaround. |
| Reimbursement Strategy | CMS national coverage determinations for lung cancer screening accelerate electromagnetic navigation system commercialization timelines. |
| Software Companion Development | AI lesion segmentation algorithms paired with electromagnetic navigation compress procedure times and reduce sampling error rates. |
| CE Marking Pathway | EU MDR prospective registry requirements for Class IIa/IIb devices extend European commercialization cycles for navigation platforms. |
| FDA Submission | De novo pathways for robotic bronchoscopy systems trigger longer review timelines than 510(k) clearances for needle biopsy kits. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with interventional pulmonologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers were validated against secondary sources including FDA 510(k) filings, CMS national coverage determination databases, hospital procurement records, and EU MDR notified body technical documentation. Triangulation across these channels ensures segment-level precision without reliance on single-source manufacturer disclosures.
Input-output matrices map procedure volume projections to capital equipment replacement cycles and disposable instrument consumption rates across the analysis window. Segmentation dimensions include product type, application, end user, and delivery mode, with regional regulatory cluster as an additional modeled variable. CAGRs derive from weighted average procedure growth assumptions and pricing trajectory modeling. Forecast inputs incorporate CMS reimbursement expansion scenarios and EU MDR recertification timeline delays.
Underlying measurement precision varies by segment; needle biopsy and vacuum-assisted systems carry tighter precision than emerging robotic bronchoscopy categories due to established reporting channels. Forecasts reflect documented assumptions regarding screening program expansion rates and fellowship program graduation capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Global Breath Analyzer Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Breathalyzers Market
Diagnostic Devices
MRI Compatible Biopsy Devices Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Hearing Screening Diagnostic Devices Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Coronary Heart Disease Diagnostic Imaging Devices Market
Diagnostic Devices
Pulmonary Function Testing Devices Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Global Real Time Polymerase Chain Reaction Systems Market
Diagnostic Devices
Europe Point of Care Diagnostics Market
Diagnostic Devices
Hemoglobin Testing Devices Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market