
 Thrombus Precursor Protein Market | 2026-2036
Thrombus Precursor Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Thrombus Precursor Protein Market Outlook
Synthetic recombinant protein expression is shifting toward mammalian cell culture systems, displacing older bacterial fermentation platforms that yield lower post-translational modification fidelity. F. Hoffmann-La Roche Ltd leverages its deep diagnostics heritage to anchor high-throughput thrombus marker portfolios across European reference laboratories. Randox Laboratories Ltd specializes in multiplex biochip arrays that compete on assay density for coagulation panels. bioMérieux SA sustains its position through integrated instrument-reagent workflows that dominate hospital microbiology and hematology suites.
Thrombus precursor proteins comprise soluble fibrin monomers, fibrinopeptide A, and prothrombin fragment 1+2, biomarkers generated during the coagulation cascade before insoluble clot formation; recombinant variants manufactured in CHO or HEK293 cells require gamma-carboxylation for functional activity in calcium-dependent binding assays. Diagnostic kits command the largest revenue share among product types due to recurring consumable demand tied to installed analyzer bases, while monoclonal antibodies represent the fastest-expanding category as sandwich immunoassay developers seek clone specificity against neo-epitopes exposed during thrombin-mediated fibrinogen cleavage. Hospitals absorb the majority of end-user volume through emergency department D-dimer and thrombus precursor triage protocols, though research laboratories concentrate margin pools through custom assay development for translational cardiovascular studies.
FDA 510(k) clearance pathways and EMA's In Vitro Diagnostic Regulation collectively elevate analytical validation burdens for novel thrombus biomarker claims, compressing timelines for smaller developers lacking clinical evidence infrastructure. ISO 13485 quality management systems and CLSI EP guideline adherence function as de facto market access prerequisites for contract manufacturers serving branded assay suppliers. Stakeholders must monitor evolving payer coverage determinations for precision coagulation testing as health technology assessment bodies scrutinize cost-per-quality-adjusted-life-year thresholds for thrombosis risk stratification protocols.
Market Dynamics
Recombinant protein expression platforms are consolidating around mammalian cell culture systems, displacing legacy bacterial fermentation due to stringent post-translational modification requirements for functional thrombus biomarker assays. This technological pivot is compressing supplier margins while elevating analytical validation standards across diagnostic value chains.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Harmonized biomarker validation frameworks across EU member states reduce redundant clinical studies, accelerating kit registration timelines for manufacturers with ISO 13485 certification.
- Emergency department triage protocols:Hospital-based coagulation diagnostics in the United States and Western Europe integrate thrombus precursor panels with D-dimer workflows, creating recurring consumable demand tied to installed analyzer bases.
- CHO cell expression systems:Gamma-carboxylation fidelity in Chinese hamster ovary platforms enables calcium-dependent binding assays essential for prothrombin fragment detection, differentiating high-performance reagent suppliers.
Market Restraints
- Fetal bovine serum price volatility:Mammalian cell culture media depend on serum inputs concentrated in South American and Australian supply chains, exposing manufacturers to input cost swings exceeding 20% annually.
- FDA 510(k) evidentiary burdens:Novel thrombus biomarker claims require analytical and clinical validation studies that compress development timelines for developers lacking dedicated regulatory affairs infrastructure.
- Substitute biomarker competition:High-sensitivity D-dimer assays and rotational thromboelastometry displace thrombus precursor protein demand in perioperative monitoring applications.
Strategic Opportunities
- Translational cardiovascular research:Academic medical centers in Germany and the Netherlands fund custom assay development for thrombosis risk stratification protocols, concentrating margin pools outside commoditized hospital diagnostics.
- Multiplex biochip convergence:Integration of thrombus markers with inflammatory cytokine panels creates assay density advantages for reference laboratories seeking consolidated testing menus.
- Health technology assessment alignment:Payer coverage determinations for precision coagulation testing in the United Kingdom reward cost-per-quality-adjusted-life-year documentation, favoring suppliers with health economics capabilities.
Industry Challenges
- CLSI EP guideline implementation:Contract manufacturers must demonstrate adherence to analytical performance standards for precision, bias, and detection limits, extending quality system certification timelines.
- Neo-epitope clone specificity:Sandwich immunoassay developers face technical barriers in isolating monoclonal antibodies against thrombin-mediated fibrinogen cleavage sites, requiring extended hybridoma screening cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrombus Precursor Protein Market |
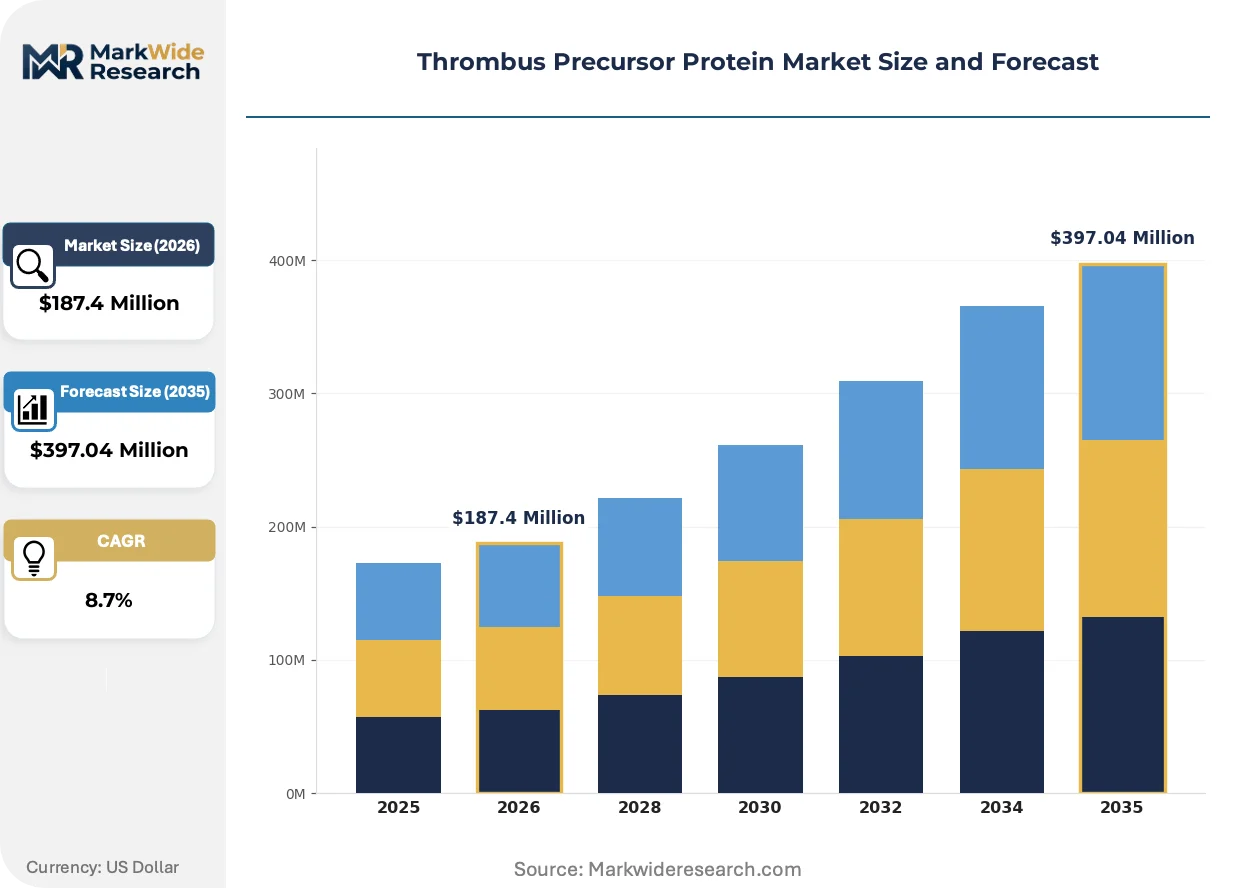
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Proteins, Natural Proteins, Monoclonal Antibodies, Diagnostic Kits End User: Hospitals, Research Laboratories, Diagnostic Centers, Academic Institutions Application: Cardiovascular Research, Hematology, Cancer Therapy, Blood Clotting Disorders Delivery Mode: Injection, Oral, Infusion, Topical |
| Companies Covered | F. Hoffmann-La Roche Ltd, Randox Laboratories Ltd, bioMérieux SA, Beckman Coulter, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Becton, Dickinson and Company, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrombus Precursor Protein Market Strategic Shifts
Instrument-reagent integration is consolidating competitive positioning around closed-system workflows, while regulatory convergence and procurement centralization reshape how diagnostic value migrates across supply chains.
Multiplex immunoassay platforms are unifying thrombus precursor detection with coagulation factor profiling, enabling simultaneous quantification of soluble fibrin monomers, fibrinopeptide A, and prothrombin fragment 1+2 in single analytical runs. Reference laboratories in Belgium and Switzerland adopt these systems to reduce sample aliquoting and improve turnaround consistency. The technology is unifying previously fragmented biomarker testing into consolidated panels that compress per-test costs while elevating data richness for cardiovascular risk algorithms.
REACH chemical registration requirements and EU MDR device classification rules now govern reagent stability claims and packaging material disclosures for thrombus diagnostic kits marketed in European Economic Area jurisdictions. Manufacturers reformulate buffer systems and replace phthalate-containing plastics to maintain market access. Assay developers with dedicated regulatory toxicology functions capture registration timelines 8-12 months shorter than competitors relying on external consultants.
Hospital procurement consortia in France and Italy now bundle thrombus precursor reagents with hematology analyzer service contracts, displacing standalone kit purchasing. Integrated instrument-reagent workflows from dominant microbiology suite suppliers capture multi-year exclusive supply agreements. Academic medical centers in Scandinavia resist this consolidation through tender specifications favoring open-platform reagent compatibility, preserving niche opportunities for specialized biochip array suppliers.
Thrombus Precursor Protein Market Segmentation
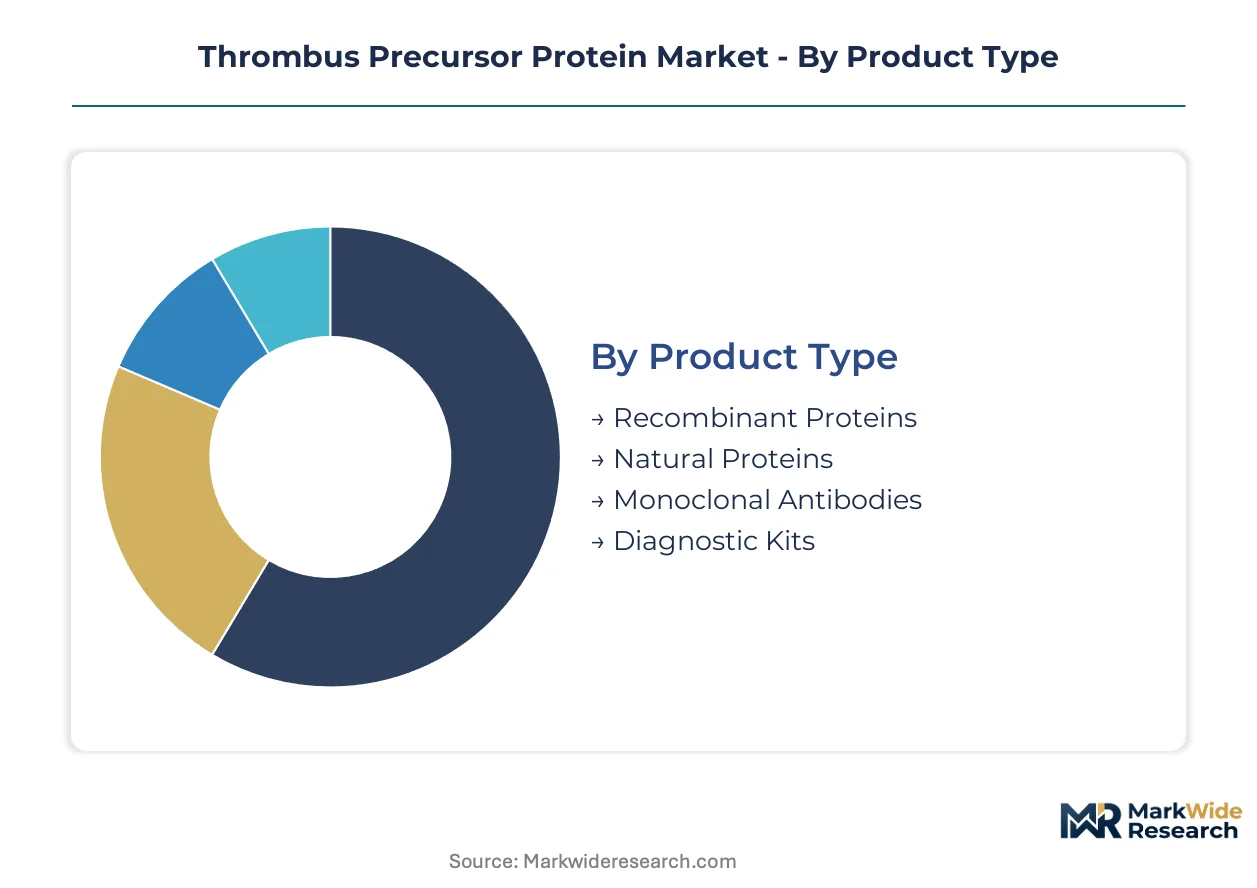
Segmentation in the thrombus precursor protein market reveals how analytical workflows, regulatory pathways, and procurement models allocate value across supply chains. Understanding these divisions exposes where margin pools concentrate and where technical differentiation creates defensible positioning.
Product Type:
Volume concentrates in recurring consumables, while premium capture shifts toward biological specificity and regulatory validation depth.
- Recombinant Proteins:Manufactured in CHO or HEK293 expression systems with gamma-carboxylation for functional calcium-dependent binding. Demand clusters in European reference laboratories requiring batch-to-batch consistency for thrombin-mediated fibrinogen cleavage assays. Fetal bovine serum price volatility compresses margins for manufacturers lacking serum-free media formulations.
- Diagnostic Kits:Encompass ELISA and chemiluminescence platforms with pre-coated capture antibodies against soluble fibrin monomers and prothrombin fragment 1+2. Hospital procurement consortia in France and Italy absorb the majority of volume through bundled analyzer service contracts, creating recurring revenue tied to installed instrument bases.
- Monoclonal Antibodies:Sandwich immunoassay developers seek clone specificity against neo-epitopes exposed during coagulation cascade activation. Extended hybridoma screening cycles elevate development costs.
- Natural Proteins:Plasma-derived fibrinogen and thrombin preparations retain niche demand in specialized hemostasis research applications with limited recombinant alternatives.
Today's leader: Diagnostic Kits. Tomorrow's challenger: Monoclonal Antibodies.
End User:
Procurement authority separates high-throughput routine testing from custom assay development with divergent margin structures.
- Hospitals:Emergency department triage protocols integrate thrombus precursor panels with D-dimer workflows in the United States and Western Europe. Integrated instrument-reagent systems from dominant microbiology suite suppliers capture multi-year exclusive supply agreements through procurement centralization.
- Research Laboratories:Academic medical centers in Germany and the Netherlands fund custom assay development for translational cardiovascular studies, concentrating margin pools outside commoditized hospital diagnostics through precision coagulation testing protocols.
- Diagnostic Centers:Independent reference laboratories in Belgium and Switzerland adopt multiplex biochip platforms to consolidate previously fragmented biomarker testing into unified panels.
- Academic Institutions:Scandinavian tender specifications favor open-platform reagent compatibility, preserving niche opportunities for specialized suppliers outside closed-system consolidation.
Hospitals command volume. Research laboratories command margin.
Application:
Clinical validation depth and payer coverage determinations stratify commercial opportunity across therapeutic domains.
- Cardiovascular Research:Thrombosis risk stratification protocols in academic medical centers drive demand for high-sensitivity prothrombin fragment 1+2 quantification. Health technology assessment bodies in the United Kingdom scrutinize cost-per-quality-adjusted-life-year thresholds, favoring suppliers with documented health economics capabilities.
- Hematology:Coagulation factor profiling and perioperative monitoring applications face displacement pressure from high-sensitivity D-dimer assays and rotational thromboelastometry in routine clinical use.
- Cancer Therapy:Oncology-associated thrombosis monitoring creates specialized demand for soluble fibrin monomer detection in immuno-oncology treatment centers.
- Blood Clotting Disorders:Inherited thrombophilia screening programs in national health systems generate steady demand for fibrinopeptide A quantification in specialized coagulation reference centers.
Cardiovascular Research leads validation investment. Hematology faces substitution pressure.
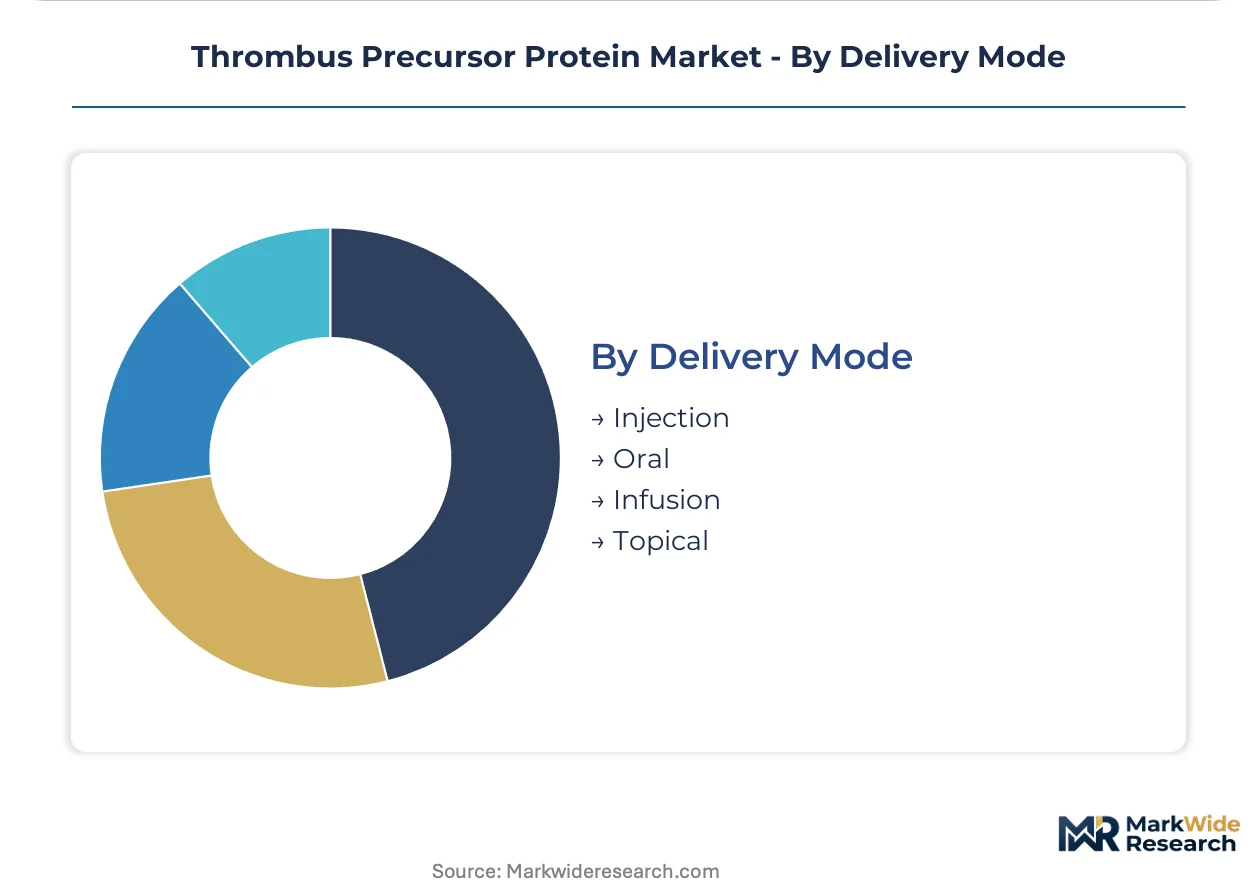
Delivery Mode:
Route of administration determines manufacturing complexity, stability requirements, and regulatory classification across jurisdictions.
- Injection:Intravenous and subcutaneous formulations dominate therapeutic protein delivery, requiring sterile fill-finish capabilities and cold chain distribution infrastructure validated under ISO 13485 quality management systems.
- Oral:Limited bioavailability of large protein molecules restricts application to small-molecule anticoagulant adjuvants rather than direct thrombus precursor protein delivery.
- Infusion:Continuous delivery systems for perioperative hemostasis management in cardiac surgery centers require pump-compatible formulation stability.
- Topical:Fibrin sealant applications in surgical hemostasis utilize thrombin and fibrinogen combinations with localized delivery bypassing systemic circulation.
Injection anchors clinical utility. Topical offers surgical niche expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Basel-Rotterdam corridor anchors diagnostic reagent manufacturing for thrombus precursor protein assays, with integrated bioprocessing clusters supplying CHO cell-derived recombinant proteins to European reference laboratories.
United States
Emergency department triage protocols at academic medical centers in Boston and Cleveland integrate thrombus precursor panels with D-dimer workflows. FDA 510(k) clearance pathways compress development timelines for novel biomarker claims. The Research Triangle Park concentration in North Carolina hosts contract manufacturers serving branded assay suppliers with ISO 13485-certified production.
Germany
Translational cardiovascular research at Heidelberg and Munich academic centers drives custom assay development for thrombosis risk stratification. EMA's In Vitro Diagnostic Regulation harmonizes biomarker validation frameworks across EU member states. The Munich biotech cluster concentrates gamma-carboxylated recombinant protein production for calcium-dependent binding assays.
France
Hospital procurement consortia in Paris and Lyon bundle thrombus precursor reagents with hematology analyzer service contracts. ANSM oversight of clinical laboratory quality standards elevates analytical validation requirements. The Lyon biocluster specializes in multiplex biochip array manufacturing for consolidated coagulation testing menus.
Switzerland
Reference laboratories in Basel and Geneva adopt multiplex immunoassay platforms unifying thrombus marker detection with inflammatory cytokine panels. Swissmedic device classification rules govern reagent stability claims for kits marketed across European Economic Area jurisdictions. The Basel pharmaceutical corridor dominates instrument-reagent integration for closed-system workflows.
Netherlands
Academic medical centers in Amsterdam and Rotterdam fund precision coagulation testing protocols with documented health economics capabilities. Health technology assessment bodies scrutinize cost-per-quality-adjusted-life-year thresholds for thrombosis risk stratification. The Leiden bioScience cluster advances monoclonal antibody development against neo-epitopes exposed during thrombin-mediated fibrinogen cleavage.
Thrombus Precursor Protein Market Competitive Environment
Global majors compete with regional champions across diagnostic platform integration, with consolidated instrument-reagent workflows dominating hospital procurement while specialized biochip suppliers capture niche reference laboratory segments. The vendor base stratifies into three tiers: diversified diagnostics conglomerates with installed analyzer bases, mid-scale reagent specialists with ISO 13485 contract manufacturing capabilities, and boutique antibody developers serving translational research. Dominant competitive moves include exclusive multi-year supply agreements with hospital consortia and backward integration into mammalian cell expression systems.
Within the diversified diagnostics tier, F. Hoffmann-La Roche Ltd and bioMérieux SA exemplify archetypes of instrument-reagent integration, with the former representing Swiss-German heritage in high-throughput marker portfolios and the latter occupying a position in hospital microbiology and hematology suite dominance. Randox Laboratories Ltd sits within the specialized array segment, exemplifying the Northern Irish model of multiplex biochip density competition against closed-system consolidation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Randox Laboratories Ltd |
| bioMérieux SA |
| Beckman Coulter |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| Sysmex Corporation |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consortia in France and Italy bundling thrombus precursor reagents with hematology analyzer service contracts are forcing contract manufacturers to absorb serum cost volatility while maintaining ISO 13485-certified batch consistency for gamma-carboxylated recombinant proteins.
Pricing Analysis
Fetal bovine serum price swings exceeding twenty percent annually pass through to recombinant protein pricing, with CHO cell-derived thrombus biomarkers commanding premium tiers against bacterial fermentation alternatives. Price differentiation hinges on gamma-carboxylation fidelity and CLSI EP guideline compliance, with research laboratories least sensitive and hospital procurement consortia most aggressive on per-test economics. Cost compression in standard-grade diagnostic kits is intensifying as bundled analyzer contracts displace standalone purchasing.
Supply Chain Analysis
ISO 13485 certification and FDA 510(k) evidentiary requirements gate supplier qualification, concentrating gamma-carboxylated recombinant protein production in Germany, Switzerland, and the Netherlands. Mammalian cell culture media draws from South American and Australian serum supply chains, creating single-source vulnerability for fetal bovine serum inputs. Distribution runs through hospital procurement consortia and reference laboratory networks rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
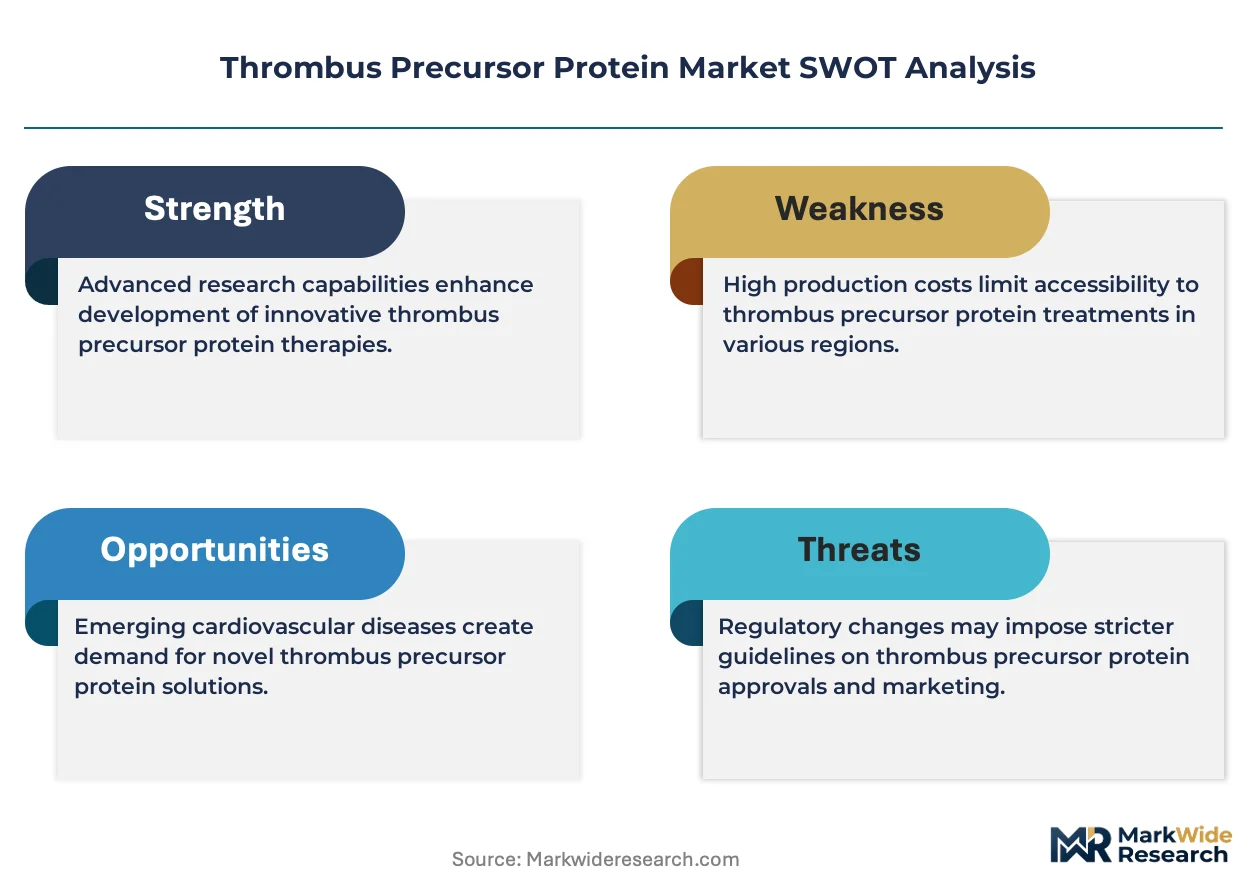
This market functions as a geographic-arbitrage play between EMA harmonized validation frameworks reducing redundant clinical studies and FDA 510(k) evidentiary burdens compressing timelines for developers lacking regulatory infrastructure.
For Market Incumbents: To counter displacement pressure from high-sensitivity D-dimer assays and rotational thromboelastometry in perioperative monitoring, anchor position through backward integration into serum-free CHO cell expression systems and exclusive multi-year supply agreements with hospital consortia in France and Italy. For New Entrants and Emerging Players: Multiplex biochip convergence with inflammatory cytokine panels offers the most penetrable wedge, targeting reference laboratories in Belgium and Switzerland seeking consolidated testing menus outside closed-system consolidation from dominant microbiology suite suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with boutique monoclonal antibody developers possessing neo-epitope clone specificity against thrombin-mediated fibrinogen cleavage sites, particularly those serving academic medical centers in Germany and the Netherlands with documented health economics capabilities. Watch for EMA In Vitro Diagnostic Regulation implementation creating tiered supplier qualification timelines as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Serum-Free Media Formulation | Eliminates fetal bovine serum cost volatility exposure for CHO cell manufacturers. |
| CE Marking Pathway | Unlocks European Economic Area market access under EMA harmonized validation frameworks. |
| Multiplex Biochip Development | Creates assay density advantages for reference laboratories in Belgium and Switzerland. |
| Health Economics Documentation | Satisfies United Kingdom HTA scrutiny of cost-per-quality-adjusted-life-year thresholds. |
| Neo-Epitope Hybridoma Screening | Isolates clone specificity for sandwich immunoassay developers against thrombin cleavage sites. |
Study Parameters
Direct dialogue with regulatory affairs leads at diagnostic kit manufacturers, reference laboratory directors in Germany and the Netherlands, hospital procurement managers in French and Italian consortia, and contract manufacturing executives anchored qualitative grounding. Secondary validation drew from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, hospital GPO contract databases, and ISO 13485 certification registries. Bottom-up assay demand modeling and top-down cardiovascular research funding allocation triangulated market sizing.
Segmented outputs across product type, end user, application, and delivery mode dimensions combined with CHO cell expression capacity assessments and procurement pattern analysis across the projection horizon. CAGRs derived from installed analyzer base expansion rates, biomarker validation timeline compression, and payer coverage determination trajectories for precision coagulation testing protocols.
The model holds under stable EMA regulatory implementation and serum supply continuity; deviation in FDA evidentiary burden escalation or fetal bovine serum export restrictions would shift recombinant protein availability and pricing trajectories. A model refresh is warranted upon material change in health technology assessment body reimbursement determinations for thrombosis risk stratification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Global Dermatology Diagnostic Devices Market
Diagnostic Devices
Global Dental Caries Detectors Market
Diagnostic Devices
Navigated Biopsy Needles Market
Diagnostic Devices
Point of Care Diagnostics Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
Global DNA Test Kit Market
Diagnostic Devices
AI Portable Chest X-ray Triage Device Market
Diagnostic Devices
Skin Moisture Detectors Market
Diagnostic Devices
Pelvic Floor Diagnostics Market
Diagnostic Devices
Ophthalmic Diagnostic Equipment Market
Diagnostic Devices
Digital Diagnostic Audiometer Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Ocular Allergy Diagnostic System Market
Diagnostic Devices
Biopsy Guidance System Market
Diagnostic Devices
Calprotectin Serum Immunoassay Market