
 Global Real Time Polymerase Chain Reaction Systems Market | 2026-2036
Global Real Time Polymerase Chain Reaction Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Real Time Polymerase Chain Reaction Systems Market Foresight
Aftermarket service revenue is rewriting profitability expectations across the installed base. Thermo Fisher Scientific leverages its global field service network to capture recurring calibration and maintenance contracts. QIAGEN anchors its position through proprietary assay chemistry paired with instrument lock-in strategies. Bio-Rad Laboratories competes on open-platform flexibility that reduces customer switching costs.
Real time polymerase chain reaction systems amplify and quantify targeted DNA or RNA sequences through fluorescence-based monitoring during thermal cycling, typically operating across 35-45 cycles with temperature ramp rates of 2-5°C per second for rapid diagnostic turnaround. These instruments serve as the analytical backbone for molecular diagnostics, genomics research, and pathogen surveillance programs. Digital PCR systems command premium positioning due to absolute quantification capabilities that bypass standard curve dependencies. Infectious disease diagnostics represents the largest application volume, while agricultural biotechnology registers the fastest expansion as gene-editing validation workflows multiply. Fluorescence detection technology dominates the technology landscape, though droplet digital PCR is displacing legacy methods in liquid biopsy and rare mutation detection contexts.
FDA clearance pathways for in vitro diagnostics shape product development timelines and clinical claim substantiation requirements for US market access. EMA's In Vitro Diagnostic Regulation and China's NMPA technical review standards collectively elevate the documentation burden for multi-region product registrations. ISO 13485 quality management certification functions as a baseline qualifier for supplier qualification by large hospital networks and reference laboratories. Stakeholders must weigh the capital allocation trade-off between expanding high-throughput PCR machine placements and defending margin integrity in the installed base service layer.
Market Dynamics
Installed base monetization is restructuring competitive economics as manufacturers pivot from instrument placement to recurring assay and service revenue streams. Field service density and reagent lock-in now determine profitability more than initial hardware margins.
Growth Catalysts
- MDR implementation deadlines:European Union medical device regulation is accelerating laboratory instrument replacement cycles as facilities upgrade to compliant platforms ahead of certification deadlines.
- China's biotech corridor expansion:Domestic pharmaceutical captive genomics capabilities are driving sustained instrument demand across Shanghai, Suzhou, and Beijing clusters.
- Multiplexing chemistry advances:Simultaneous detection of multiple pathogen targets per reaction is compressing cost-per-test economics for high-volume infectious disease screening.
Market Restraints
- Fluorophore supply concentration:Specialized optical dye manufacturing concentrates in German and Japanese chemical suppliers, exposing reagent producers to input volatility.
- Capital intensity barriers:Reference laboratory instrument purchases require 18-24 month capital budgeting cycles, elongating sales pipelines.
- Digital PCR substitution pressure:Absolute quantification capabilities in liquid biopsy applications are fragmenting addressable market growth for traditional real-time platforms.
Strategic Opportunities
- India's diagnostic infrastructure buildout:Central government health mission funding is opening molecular testing access in tier-2 and tier-3 cities previously served by referral networks.
- Agricultural biotechnology validation:Gene-editing regulatory compliance workflows are creating instrument demand from seed and crop science laboratories.
- ISO 13485 certification arbitrage:Quality management standardization is enabling mid-tier manufacturers to qualify for hospital network procurement previously reserved for established suppliers.
Industry Challenges
- Field service engineer scarcity:Cross-trained technicians capable of optical calibration, thermal cycler maintenance, and software diagnostics command premium compensation in tight labor markets.
- IVD compliance documentation burden:FDA 510(k) and EMA technical file preparation timelines extend 14-22 months, consuming regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Real Time Polymerase Chain Reaction Systems Market |
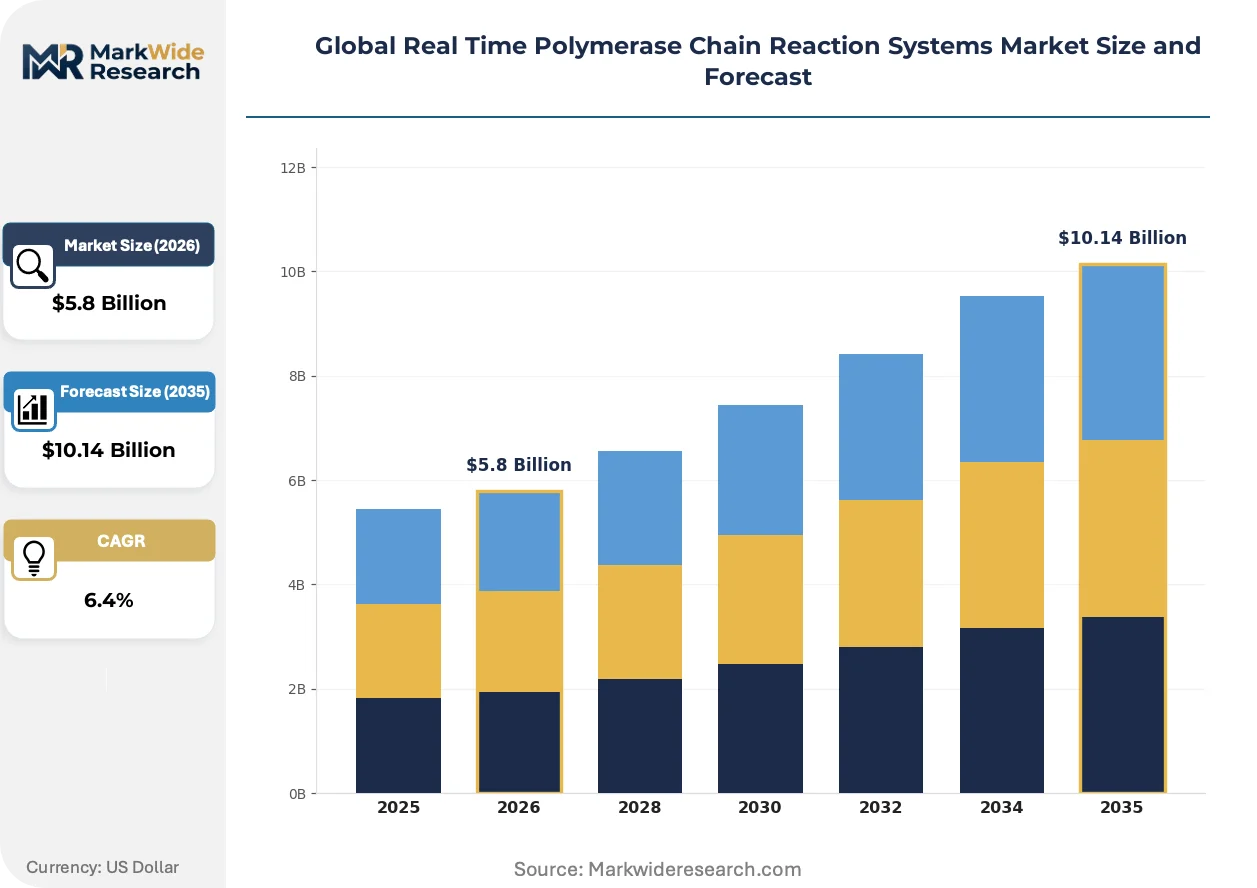
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multiplex PCR Devices, Digital PCR Systems, Droplet Digital PCR, High-Throughput PCR Machines, Standalone PCR Instruments Technology: Fluorescence Detection, SYBR Green, TaqMan Probes, Molecular Beacons, Scorpions, EvaGreen Application: Genetic Mutation Analysis, Infectious Disease Diagnostics, Forensics, Agricultural Biotechnology, Food Safety Analysis End User: Academic Research, Clinical Laboratories, Pharmaceutical Companies, Biotechnology Startups, Food Testing Labs |
| Companies Covered | Thermo Fisher Scientific, QIAGEN, Bio-Rad Laboratories, F. Hoffmann-La Roche Ltd, Abbott, Agilent Technologies, Danaher Corporation, GE Healthcare, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Real Time Polymerase Chain Reaction Systems Market Shifts & Advancements
Platform architecture is converging around modular designs that separate thermal cycling hardware from detection optics, enabling field-upgradable configurations. This flexibility is reshaping capital deployment strategies across laboratory networks.
Droplet digital PCR technology is hybridizing with real-time fluorescence monitoring to create hybrid platforms that preserve the workflow familiarity of quantitative PCR while delivering absolute quantification. Agricultural biotechnology laboratories in the United States and Netherlands are adopting these systems for gene copy number validation in edited crop lines. The convergence is compressing the addressable market for standalone digital PCR systems by delivering comparable analytical performance through familiar thermal cycling interfaces.
EMA's In Vitro Diagnostic Regulation is mandating clinical evidence standards that exceed legacy IVD Directive requirements, forcing manufacturers to generate prospective performance data for new submissions. This documentation burden extends product development timelines and elevates barriers to entry for novel assay developers. European reference laboratories are responding by consolidating vendor relationships to reduce qualification overhead.
Reagent rental and instrument leasing models are displacing outright purchase arrangements in hospital network procurement, transferring capital risk to manufacturers while securing long-term consumable commitments. This shift is most visible in United States integrated delivery networks where centralized laboratory services negotiate enterprise-wide agreements. The model compresses customer switching flexibility and intensifies field service quality as a competitive differentiator.
Global Real Time Polymerase Chain Reaction Systems Market Segmentation
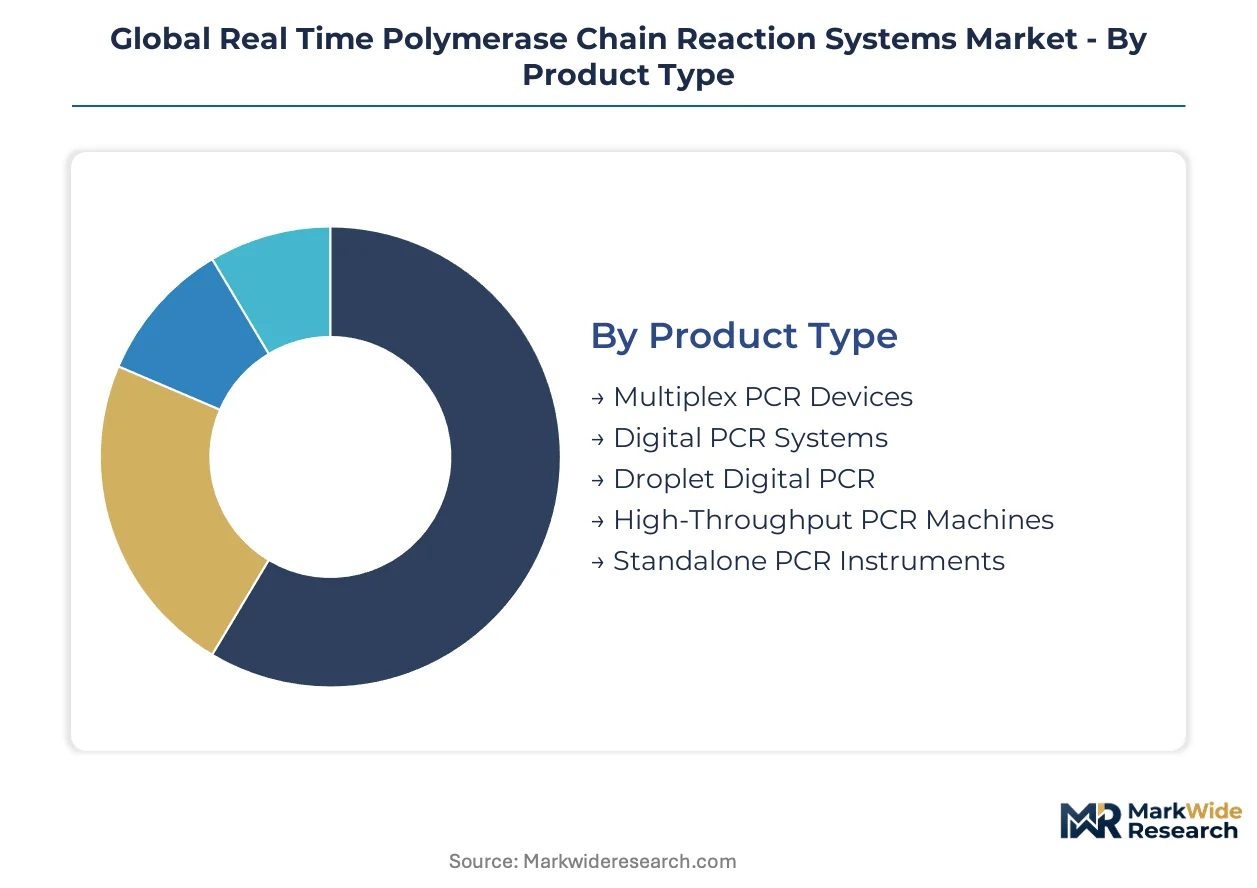
Segmentation in real-time PCR systems reveals how purchasing logic splits across technical sophistication, throughput requirements, and regulatory exposure. Each dimension carries distinct margin profiles and service attachment rates that reshape manufacturer resource allocation.
Product Type:
Cost tier differentiation separates entry-level placements from premium absolute-quantification platforms.
- Multiplex PCR Devices:Simultaneous amplification of multiple genetic targets reduces reagent consumption per diagnostic panel. Clinical laboratories in the United States deploy these for respiratory pathogen screening where reimbursement pressures demand cost compression.
- Digital PCR Systems:Partitioning reactions into thousands of micro-reactions enables absolute copy number quantification without standard curves. Pharmaceutical companies in China's Suzhou biotech cluster adopt these for gene therapy potency assays where regulatory submissions require traceable metrology.
- Droplet Digital PCR:Oil-emulsion microfluidics deliver single-molecule sensitivity for liquid biopsy applications.
- High-Throughput PCR Machines:384-well and 1,536-well formats serve reference laboratories with population-scale screening mandates.
- Standalone PCR Instruments:Entry-level thermal cyclers dominate academic grant-funded purchases with limited service contract attachment.
Standalone PCR instruments command the established base. The steepest expansion runs through droplet digital PCR as oncology laboratories validate cell-free DNA workflows.
Technology:
Detection chemistry maturity determines reagent cost structures and assay development timelines.
- Fluorescence Detection:Broad-spectrum optical systems accommodate multiple fluorophore combinations for multiplexed pathogen detection. Hospital networks in Germany standardize on these platforms to simplify procurement and training across distributed laboratory sites.
- SYBR Green:Intercalating dye chemistry offers low-cost entry for research applications lacking probe design resources. Academic laboratories in India leverage SYBR-based protocols for infectious disease surveillance where budget constraints limit probe-based alternatives.
- TaqMan Probes:Hydrolysis probe chemistry delivers specificity for clinical diagnostic claims requiring FDA clearance.
- Molecular Beacons:Stem-loop probe architecture enables real-time genotyping with single-nucleotide discrimination.
- Scorpions:Unimolecular probe-primer constructs accelerate assay development for biotech startups.
- EvaGreen:Next-generation intercalating dye reduces PCR inhibition compared to SYBR formulations.
TaqMan probe-based detection anchors clinical revenue. EvaGreen dye chemistry is climbing the fastest as agricultural biotechnology laboratories validate copy number assays for gene-edited crops.
Application:
End-use regulatory intensity creates divergent qualification requirements and pricing power.
- Genetic Mutation Analysis:Oncology companion diagnostic workflows demand validated analytical sensitivity for rare allele detection. Reference laboratories in the Netherlands deploy these capabilities for hereditary cancer screening programs.
- Infectious Disease Diagnostics:Respiratory, bloodstream, and sexually transmitted pathogen panels represent the highest test volume segment. China's NMPA clearance requirements for SARS-CoV-2 assays accelerated domestic instrument placement during the pandemic response.
- Forensics:CODIS-compliant short tandem repeat analysis requires stringent contamination controls and chain-of-custody documentation.
- Agricultural Biotechnology:Gene copy number validation supports regulatory submissions for gene-edited seed varieties.
- Food Safety Analysis:Pathogen detection in supply chains faces commodity pricing pressure from rapid culture-based alternatives.
Infectious disease diagnostics holds the volume base. Agricultural biotechnology validation workflows are gaining share fastest as seed companies build in-house genomics capabilities.
End User:
Customer type shapes contract structure, from capital purchase to reagent rental and full service outsourcing.
- Clinical Laboratories:Hospital-based and independent reference laboratories drive recurring reagent revenue through high daily test volumes. Integrated delivery networks in the United States negotiate enterprise pricing that compresses per-test margins while locking in multi-year consumable commitments.
- Pharmaceutical Companies:Captive genomics facilities prioritize assay transferability and regulatory documentation for IND-enabling studies. Domestic Chinese pharmaceutical firms in Beijing and Shanghai clusters are expanding instrument fleets to reduce dependence on contract research organizations.
- Academic Research:Grant-funded purchases concentrate in flagship universities with limited service contract penetration.
- Biotechnology Startups:Venture-backed companies favor leasing models to preserve capital for therapeutic development.
- Food Testing Labs:Commercial and government laboratories face pricing pressure from rapid alternative methods.
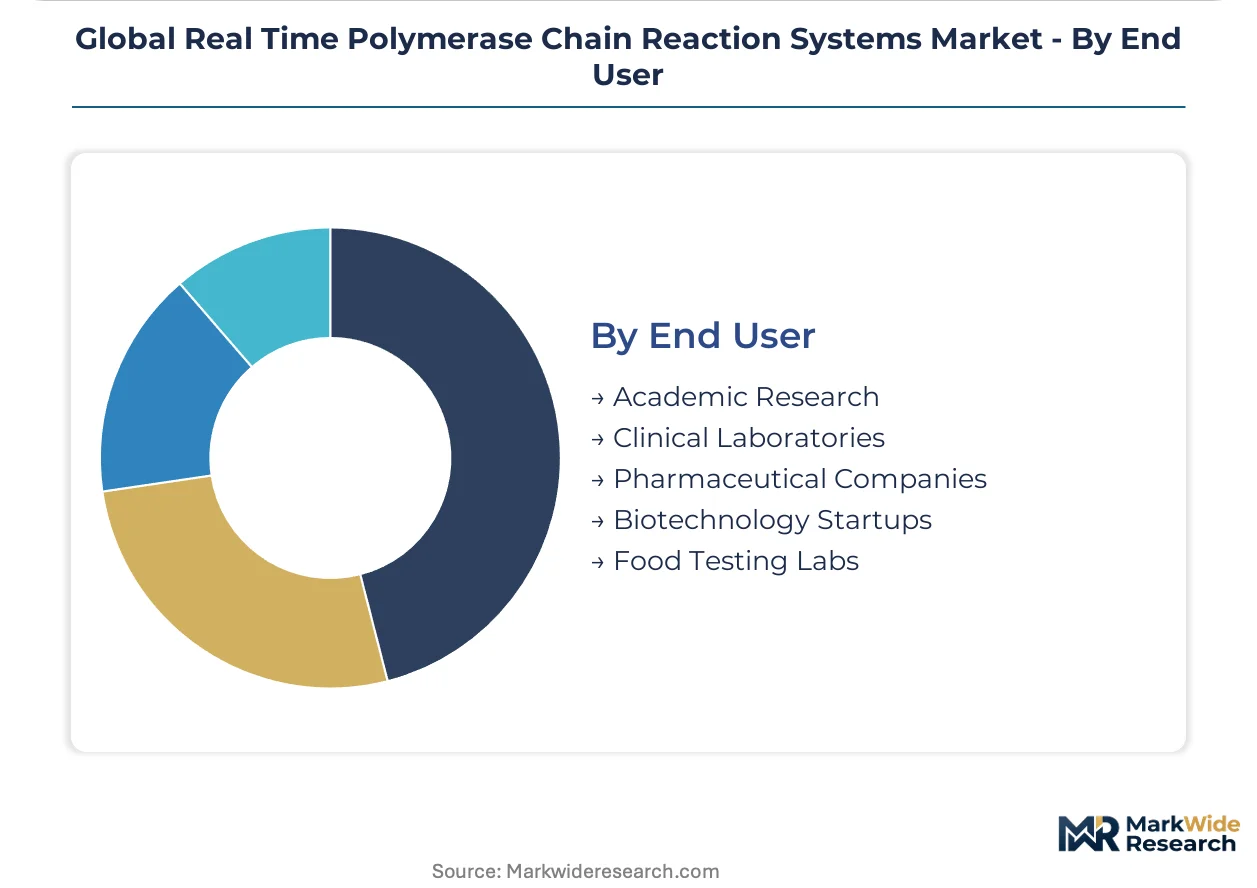
Clinical laboratories anchor installed base monetization. Biotechnology startups are expanding most quickly as venture financing supports captive diagnostic development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital networks negotiate aggressively on reagent rental terms while Chinese biotech clusters absorb premium instrument pricing with minimal price elasticity. Germany's reference laboratories prioritize regulatory documentation over cost compression. India's tier-2 cities represent the most price-sensitive demand frontier.
United States
Integrated delivery networks consolidate laboratory procurement through enterprise-wide reagent rental agreements that transfer capital risk to manufacturers. FDA's evolving 510(k) clearance pathways for in vitro diagnostics extend product development timelines to 14-22 months. Boston and San Diego biotech clusters drive demand for absolute-quantification platforms in gene therapy development workflows.
China
Domestic pharmaceutical companies in Beijing and Shanghai build captive genomics capabilities to reduce contract research organization dependence. NMPA technical review standards for molecular diagnostic instruments elevate documentation burdens comparable to FDA requirements. Suzhou biotech corridor instrument placements accelerate as gene therapy developers establish in-house potency assay laboratories.
Germany
Hospital networks standardize fluorescence detection platforms across distributed laboratory sites to simplify procurement and training protocols. EMA's In Vitro Diagnostic Regulation mandates clinical evidence standards exceeding legacy IVD Directive requirements. Munich and Heidelberg molecular diagnostic hubs consolidate vendor relationships to reduce qualification overhead from stricter documentation demands.
India
Central government health mission funding opens molecular testing access in tier-2 and tier-3 cities previously dependent on metropolitan referral networks. CDSCO regulatory frameworks for medical devices gradually align with international quality management standards. Hyderabad and Bangalore diagnostic laboratory clusters expand instrument fleets to serve newly accessible patient populations.
Netherlands
Reference laboratories deploy digital PCR capabilities for hereditary cancer screening programs requiring validated analytical sensitivity. CE marking requirements under MDR implementation accelerate replacement cycles for non-compliant legacy platforms. Wageningen agricultural biotechnology laboratories adopt hybrid platforms for gene copy number validation in edited crop lines.
Global Real Time Polymerase Chain Reaction Systems Market Competitive Landscape
Capability concentration sits with specialized optics and thermal engineering firms; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: full-stack platform providers, reagent-focused specialists, and open-platform instrument suppliers. Strategic archetypes include instrument-lock-in strategists, assay-chemistry anchors, and field-service density builders. Dominant competitive moves encompass reagent rental model expansion and modular platform architecture development.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies the field-service density archetype through global calibration and maintenance network leverage. QIAGEN occupies a position representing proprietary assay chemistry paired with instrument ecosystem lock-in. Bio-Rad Laboratories anchors the open-platform flexibility tier that reduces customer switching costs and preserves academic research market access.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| QIAGEN |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Agilent Technologies |
| Danaher Corporation |
| GE Healthcare |
| bioMérieux |
| Others |
Supply & Pricing Matrix
Air freight corridors linking German optical dye manufacturers to Chinese reagent producers concentrate cost volatility in fluorescence detection chemistry. Thermo Fisher Scientific and QIAGEN absorb these logistics premiums through field service density investments that lock in multi-year consumable commitments from hospital networks.
Pricing Analysis
Aftermarket service contracts and reagent rental tiers generate lifetime value exceeding initial hardware margins by substantial multiples. Three-tier pricing structure across premium digital PCR, standard multiplex platforms, and economy standalone instruments separates absolute quantification capabilities from basic thermal cycling. Cost compression in infectious disease diagnostics intensifies as integrated delivery networks negotiate enterprise-wide per-test pricing. Academic research laboratories in India exhibit highest price sensitivity; pharmaceutical captive genomics facilities in China's Suzhou corridor show minimal elasticity for validated potency assay platforms.
Supply Chain Analysis
Tariff exposure between German chemical suppliers and Japanese optical component manufacturers dominates supply chain risk planning for fluorescence detection systems. Manufacturing concentrates in Germany, Japan, and the United States for specialized fluorophores, thermal cycling hardware, and optical detection modules. Component sourcing draws from precision optics foundries, semiconductor-grade Peltier elements, and synthetic oligonucleotide synthesis facilities. Single-source vulnerability in intercalating dye chemistry creates qualification bottlenecks for alternative suppliers. Distribution runs through direct field sales organizations for hospital networks and authorized distributors for academic and agricultural biotechnology segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-trained field service engineers capable of optical calibration, thermal maintenance, and software diagnostics represent the critical capability gap constraining manufacturer expansion. Laboratories now select vendors based on technician response time rather than instrument specifications alone.
For Market Incumbents: Build field service density moats through captive training academies and regional spare parts depots. Thermo Fisher Scientific's calibration network exemplifies this approach. Defend against digital PCR substitution by hybridizing real-time platforms with absolute quantification modules. Pursue ISO 13485 certification arbitrage to qualify for hospital procurement previously reserved for established suppliers. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 diagnostic infrastructure buildout where price sensitivity exceeds brand loyalty. Agricultural biotechnology validation workflows offer second entry point with lower regulatory documentation burdens than clinical diagnostics. Leasing models with reagent bundling reduce capital barriers for biotechnology startups seeking captive assay development capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core instrument divisions. Long-term viability hinges on recurring revenue attachment rates rather than hardware placement velocity. Watch NMPA technical review standardization in China as signal for domestic manufacturer consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Architecture Development | Field-upgradable thermal cycling and detection optics preserve customer capital investment across EMA MDR implementation cycles. |
| Reagent Rental Model Expansion | Integrated delivery networks in the United States transfer capital risk to manufacturers while locking multi-year consumable commitments. |
| ISO 13485 Certification Investment | Quality management standardization enables mid-tier manufacturers to qualify for hospital network procurement previously reserved for established suppliers. |
| Hybrid Platform Convergence | Droplet digital PCR integration with real-time fluorescence monitoring compresses addressable market for standalone digital systems. |
| Field Service Network Density Buildout | Cross-trained technician availability determines competitive positioning as laboratories prioritize response time over instrument specifications. |
Research Methodology
Initial hypotheses were tested against primary input from molecular diagnostic laboratory directors, regulatory affairs specialists at instrument manufacturers, hospital GPO contracts managers, and agricultural biotechnology R&D heads and refined through secondary validation. FDA 510(k) clearance databases, EMA technical file submissions, NMPA registration records, and ISO 13485 certification registries provided structured secondary inputs. Bottom-up instrument placement tracking and top-down reagent consumption modeling were triangulated against manufacturer reported installed base figures.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, detection chemistry maturity, application regulatory intensity, and end-user contract structure. CAGRs were derived from instrument placement trajectories, reattachment rate assumptions, and assay menu expansion timelines. Forecast inputs incorporated EMA MDR implementation deadline impacts, China's biotech corridor expansion velocity, and digital PCR substitution elasticity in liquid biopsy applications.
Sensitivities concentrate around fluorophore supply disruptions, field service engineer labor market tightness, and IVD compliance documentation timeline extensions. Forecasts reflect assumptions about replacement cycle acceleration and reagent rental model penetration without guaranteeing specific outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Devices
Amniotic Fluid Detection Market
Diagnostic Devices
Blood Testing Devices Market
Diagnostic Devices
Breath Samplers Market
Diagnostic Devices
Non-Hospital-Based Point-Of-Care Diagnostic Products Market
Diagnostic Devices
Cotinine Screening Devices Market
Diagnostic Devices
Animal Pregnancy Test Kits Market
Diagnostic Devices
Contactless Vital Sign Monitoring Device Validation Test Platforms Market
Diagnostic Devices
Immunochromatography Kits Market
Diagnostic Devices
GCC Breath Analyzer Market
Diagnostic Devices
Non-Invasive Biosensors Market
Diagnostic Devices
Point-Of-Care Breathalyzer Market
Diagnostic Devices
Breast Biopsy Market
Diagnostic Devices
Europe Companion Diagnostics Market
Diagnostic Devices
Portable Diagnostic Devices Market
Diagnostic Devices
Portable Cancer Screen Devices Market
Diagnostic Devices
Global Breast Lesion Localization Methods Market