
 North America Video Surveillance Systems Market | 2026-2036
North America Video Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Video Surveillance Systems Market Analytics
NDAA Section 889 compliance is unwinding the competitive landscape for federal procurement channels, disqualifying non-compliant component suppliers from national security installations. Motorola Solutions leverages its vertically integrated manufacturing footprint to sustain federal contract eligibility, while Axis Communications AB competes through open-architecture platform specialization. Honeywell International Inc anchors its position through building-automation integration that extends video into broader security ecosystems.
Video surveillance systems encompass camera hardware, video management software, storage infrastructure, and analytics engines designed for real-time monitoring and forensic review, typically operating at frame rates of 15-30 fps with H.265 compression to minimize bandwidth consumption. IP-based technology leads installed value due to Power-over-Ethernet deployment flexibility and resolution scalability to 4K and beyond. The government end-user segment dominates absolute spending, though healthcare application demand is expanding fastest as HIPAA-aligned physical security requirements intensify around patient data access points.
The FCC governs wireless spectrum allocation for cellular-enabled cameras, while NIST cybersecurity frameworks shape product hardening standards for critical infrastructure deployments. State-level privacy statutes in California and Illinois are fragmenting compliance obligations, forcing manufacturers to maintain multiple firmware configurations. Stakeholders must monitor evolving biometric recognition restrictions, as facial detection capabilities face patchwork municipal bans that threaten feature monetization strategies.
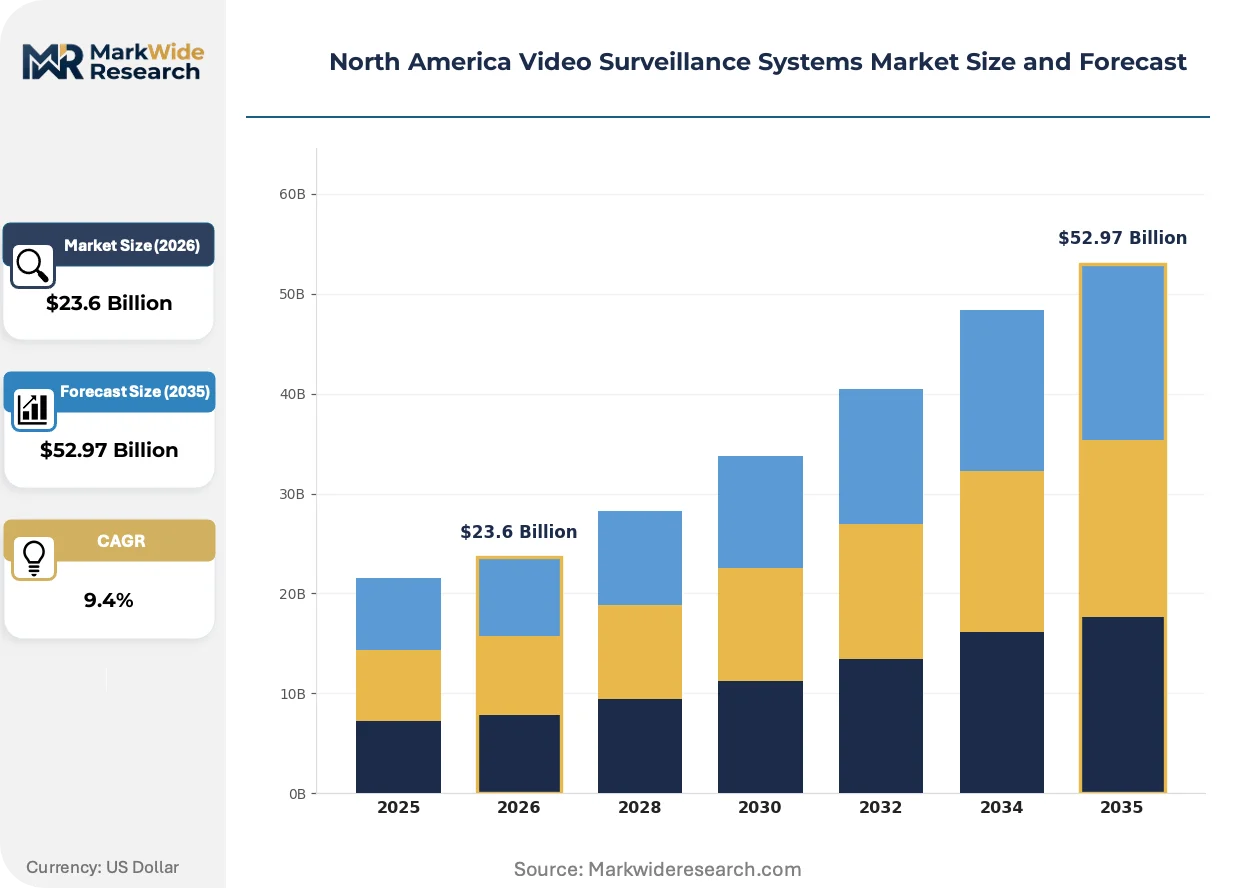
Market Dynamics
NDAA Section 889 compliance mandates are restructuring federal procurement eligibility, forcing component sourcing realignments that favor vertically integrated domestic manufacturers over foreign-dependent supply chains.
Growth Catalysts
- Smart city infrastructure:Municipal governments in Texas and California are accelerating camera deployments for traffic management and public safety coordination, compressing traditional procurement cycles.
- FCC broadband programs:Federal connectivity subsidies are enabling cloud-architecture transitions that reduce on-premise storage burdens for mid-sized municipal deployments.
- HIPAA-aligned physical security:Healthcare facilities are mandating video coverage at patient data access points, creating specification pull-through for integrated access-control systems.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication depends heavily on Taiwan and South Korean foundry capacity, exposing lead time volatility for camera OEMs.
- State privacy statute fragmentation:Illinois Biometric Information Privacy Act and California Consumer Privacy Act impose conflicting firmware configuration requirements that inflate compliance costs.
- Facial recognition substitution pressure:Municipal bans on biometric analytics in Portland, San Francisco, and other jurisdictions threaten feature monetization for AI-enabled platforms.
Strategic Opportunities
- Critical infrastructure perimeter expansion:Data center investments across Arizona and Nevada are generating demand for thermal-camera integration with video analytics.
- Cellular-enabled camera penetration:Private LTE and CBRS spectrum allocations are opening remote-site monitoring applications previously uneconomical for fiber deployment.
- Building-automation convergence:Integration with HVAC and lighting control systems is creating specification bundling opportunities in commercial real estate retrofits.
Industry Challenges
- Cybersecurity certification timelines:NIST framework compliance for critical infrastructure deployments extends product validation cycles by 6-12 months.
- Legacy analog migration complexity:Hybrid environments requiring coaxial-to-IP bridge equipment inflate integration labor costs and commissioning timelines.
- Edge-AI talent scarcity:Firmware optimization for on-camera inference engines requires specialized embedded systems expertise concentrated in Seattle and Boston metro areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Video Surveillance Systems Market |
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $52.97 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Analog, IP, Wireless, HD Application: Retail, Transportation, Banking, Healthcare End User: Commercial, Residential, Government, Education Component: Cameras, Recorders, Monitors, Accessories |
| Companies Covered | Motorola Solutions, Eagle Eye Networks Inc, Honeywell International Inc, Verkada, Inc., Avigilon Corporation, Johnson Controls International, Axis Communications AB, March Networks, Genetec Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Video Surveillance Systems Market Evolving Landscape
Edge computing architectures are redistributing processing loads from centralized servers to camera hardware, altering system design priorities and vendor competitive positioning across installation scales.
AI-on-chip inference engines are displacing server-dependent analytics for real-time object classification and anomaly detection. Large retail and logistics operators in the US Midwest are piloting these deployments for inventory tracking and perimeter monitoring. The shift is compressing data transmission requirements and enabling viable operation on constrained bandwidth links previously unsuitable for cloud-reliant architectures.
The FCC's spectrum reallocation for private 5G networks is enabling dedicated wireless video backhaul for industrial campuses and transportation corridors. Manufacturing facilities in Michigan and Ohio are deploying these networks to eliminate cabling infrastructure in hazardous environments. Equipment vendors are responding with hardened camera enclosures and integrated cellular modems certified for industrial temperature ranges.
Outcome-based service contracts are replacing capital-heavy equipment purchases among mid-sized commercial buyers. Security integrators in Florida and Georgia are bundling hardware, installation, and cloud storage into per-camera monthly fees. The model is penetrating fastest among multi-site retail chains seeking predictable operating expenditures and centralized system management across distributed locations.
North America Video Surveillance Systems Market Segmentation
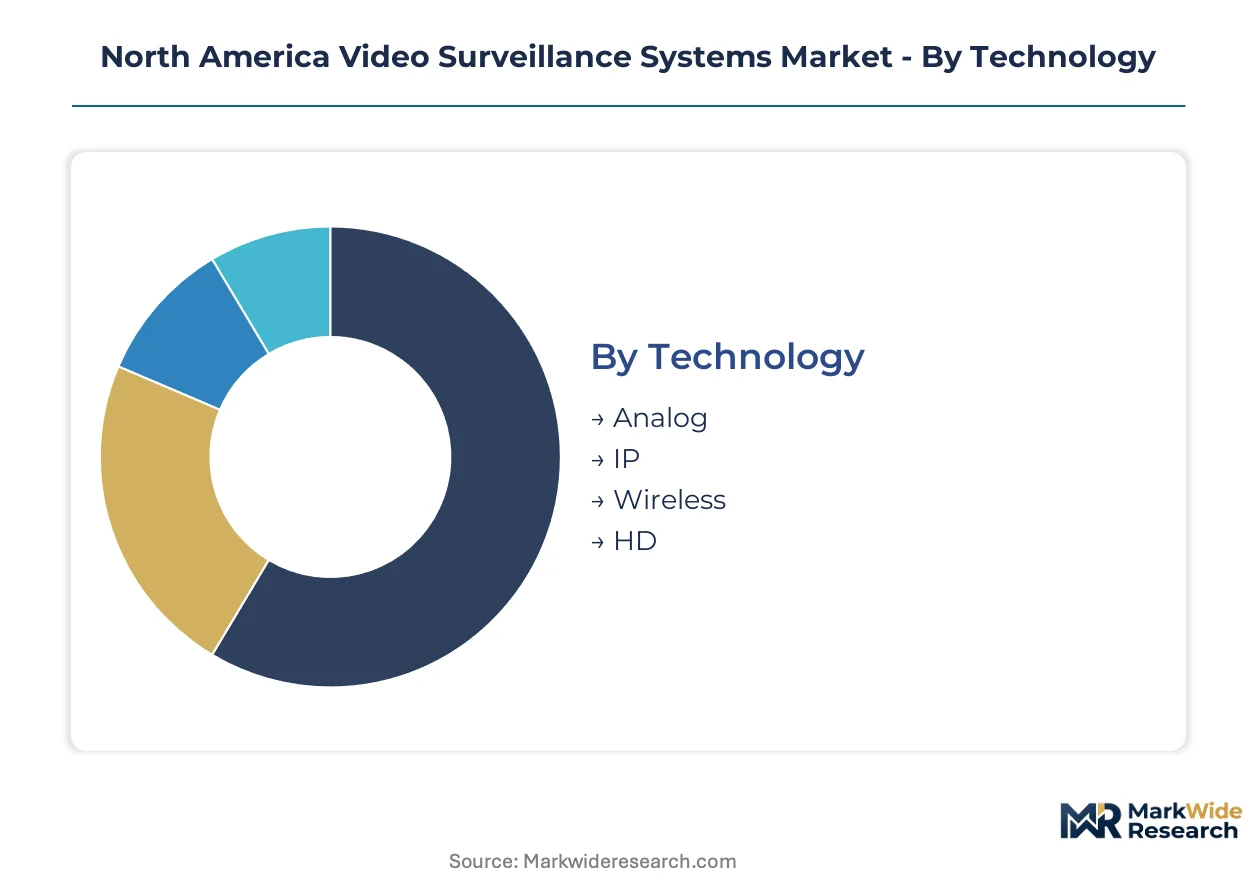
Technology choices in video surveillance dictate infrastructure requirements, recurring cost structures, and compliance pathways. Segmentation reveals where procurement budgets concentrate and which feature sets command pricing premiums across federal, commercial, and municipal deployment contexts.
Technology:
Channel mix varies sharply by technology type, with IP and wireless solutions flowing through security integrators and cloud service providers while analog persists in retrofit-heavy contractor channels.
- IP:Power-over-Ethernet architectures deliver resolution scalability to 4K and beyond with H.265 compression minimizing bandwidth consumption. Texas and California municipal governments are compressing procurement cycles for traffic management and public safety coordination, pulling IP specifications through smart city infrastructure programs.
- Wireless:Cellular-enabled cameras leveraging private LTE and CBRS spectrum allocations enable remote-site monitoring previously uneconomical for fiber deployment. Manufacturing facilities in Michigan and Ohio are eliminating cabling infrastructure in hazardous environments through hardened enclosures with integrated cellular modems.
- Analog:Coaxial infrastructure persists in legacy commercial installations where full system replacement costs are prohibitive.
- HD:High-definition over coax standards bridge analog infrastructure toward improved resolution without complete infrastructure overhaul.
IP dominates installed base. Wireless is where expansion concentrates.
Application:
Application segments stratify by compliance burden and integration complexity, with healthcare and banking commanding premium pricing due to regulatory alignment requirements.
- Healthcare:HIPAA-aligned physical security mandates video coverage at patient data access points, creating specification pull-through for integrated access-control systems. Demand concentrates in hospital networks across California and Texas where patient privacy enforcement has intensified.
- Banking:Financial institutions require forensic-grade storage retention and real-time alarm integration with vault and ATM perimeters. Critical infrastructure designations under NIST frameworks extend product validation cycles by 6-12 months for these deployments.
- Retail:Large operators in the US Midwest pilot edge-AI deployments for inventory tracking and perimeter monitoring.
- Transportation:Municipal traffic management systems in Texas and California accelerate camera deployments for public safety coordination.
Healthcare is climbing the fastest. Retail maintains the broadest installed footprint.
End User:
End user categories diverge by procurement methodology, with government segment employing formal RFP processes and commercial buyers increasingly adopting outcome-based service contracts.
- Government:Federal procurement channels face NDAA Section 889 compliance mandates that disqualify non-compliant component suppliers from national security installations. Motorola Solutions sustains contract eligibility through vertically integrated domestic manufacturing.
- Commercial:Mid-sized buyers in Florida and Georgia are bundling hardware, installation, and cloud storage into per-camera monthly fees. Multi-site retail chains seek predictable operating expenditures and centralized system management.
- Residential:Consumer-grade installations emphasize smartphone integration and DIY installation pathways.
- Education:K-12 and university campuses balance open access requirements with perimeter security and emergency response protocols.
Government commands absolute spending. Commercial is gaining share fastest.
Component:
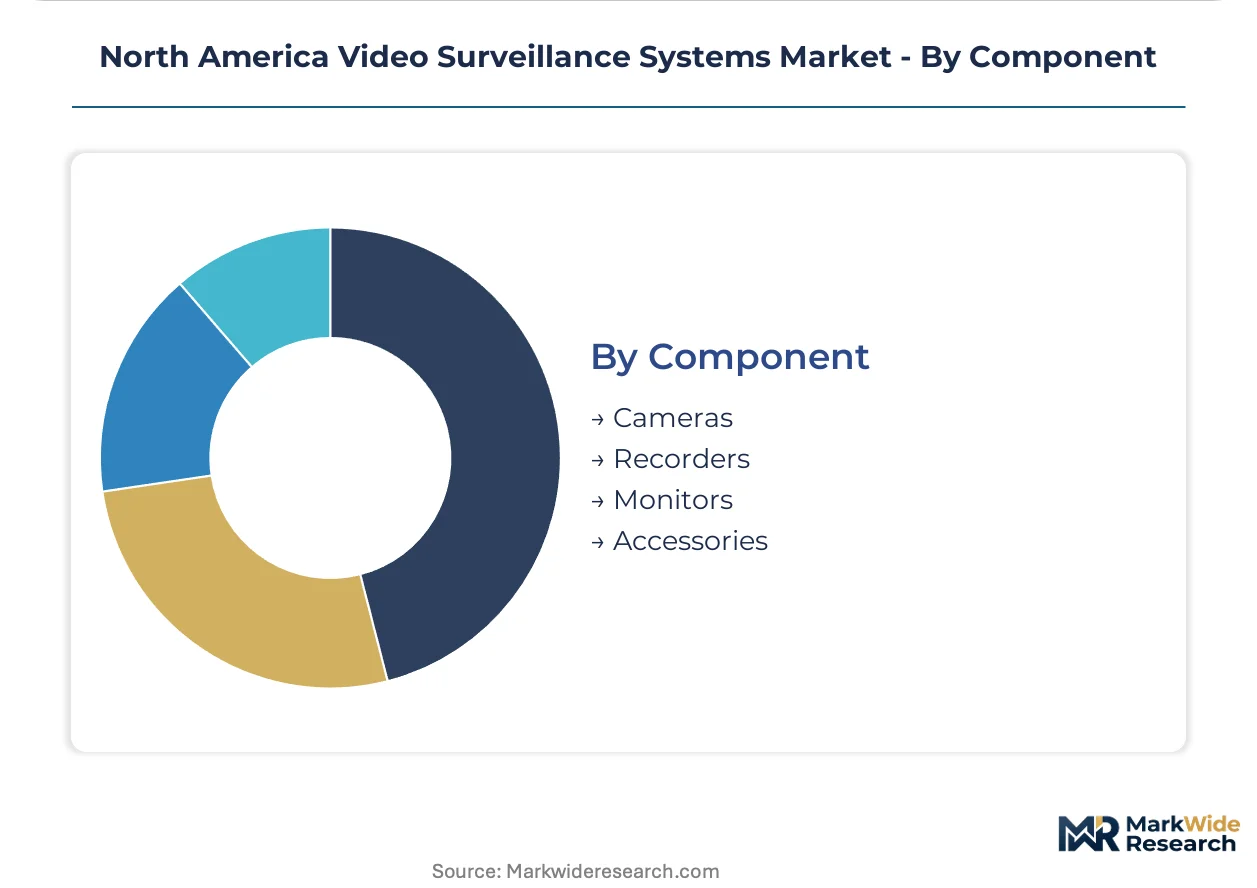
Component margins concentrate in analytics-enabled cameras and enterprise video management software, with storage hardware facing commoditization pressure.
- Cameras:Edge-AI inference engines displace server-dependent analytics for real-time object classification. Firmware optimization requires specialized embedded systems expertise concentrated in Seattle and Boston metro areas.
- Recorders:Network video recorders with integrated cybersecurity hardening face extended NIST framework validation timelines for critical infrastructure deployments.
- Monitors:Display hardware for security operations centers emphasizes 24/7 duty cycles and multi-feed visualization capabilities.
- Accessories:Power supplies, mounting hardware, and environmental housings complete installation specifications.
Cameras capture the largest revenue share. Recorders face the steepest pricing pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement concentration in Texas and California drives demand segmentation, with municipal smart city programs compressing installation timelines. Commercial buyers in Florida and Georgia shift toward subscription-based service models.
United States
Texas and California municipal governments accelerate camera deployments for traffic management and public safety coordination through smart city infrastructure programs. The FCC's broadband infrastructure subsidies enable cloud-architecture transitions for mid-sized municipal deployments. Data center investments across Arizona and Nevada generate demand for thermal-camera integration with video analytics.
Canada
Critical infrastructure operators in Ontario and British Columbia prioritize NIST-aligned cybersecurity hardening for video management systems. Health Canada regulations shape physical security requirements for healthcare facilities handling patient data. Toronto and Vancouver metropolitan areas concentrate procurement for integrated access-control systems in commercial real estate.
Mexico
Manufacturing facilities in Nuevo León and Jalisco deploy cellular-enabled cameras leveraging private LTE for hazardous environment monitoring. The country's national telecommunications regulator governs spectrum allocation for industrial wireless backhaul. Mexico City metro area drives demand for cloud-connected architectures in retail and banking applications.
North America Video Surveillance Systems Market Competitive Landscape
Player mix skews toward integrated platform specialists with federal compliance capabilities and cloud-native challengers with subscription monetization models. The vendor base separates into three tiers: vertically integrated domestic manufacturers, open-architecture platform specialists, and building-automation integrators. Dominant competitive moves include NDAA Section 889 compliance certification for federal eligibility and outcome-based service contract bundling for commercial penetration.
Among vertically integrated domestic manufacturers, Motorola Solutions occupies a position exemplifying federal contract sustainability through captive supply chains. Axis Communications AB and Honeywell International Inc represent contrasting archetypes: the former anchors open-architecture specialization, while the latter exemplifies building-automation convergence strategies. These three companies illustrate the strategic segmentation governing procurement channel access across government, healthcare, and commercial verticals.
| Leading Market Players |
|---|
| Motorola Solutions |
| Eagle Eye Networks Inc |
| Honeywell International Inc |
| Verkada, Inc. |
| Avigilon Corporation |
| Johnson Controls International |
| Axis Communications AB |
| March Networks |
| Genetec Inc |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Taiwanese image sensor foundries lock in supply access and price visibility for North American camera OEMs navigating semiconductor allocation volatility. These arrangements tether component costs to wafer pricing indices while insulating federal contractors from NDAA Section 889 compliance disruptions.
Pricing Analysis
Cost-plus contracts indexed to silicon wafer spot prices dominate component procurement for enterprise-grade camera systems. Three-tier pricing structure across NDAA-certified, cybersecurity-hardened, and standard commercial tiers separates federal-eligible hardware from municipal and retail specifications. Pricing pressure stems from foundry capacity constraints in Taiwan and South Korea that inflate image sensor input costs. Government buyers exhibit lowest price sensitivity due to compliance mandates, while mid-sized commercial adopters in Florida and Georgia gravitate toward subscription-based per-camera models that convert capital expenditure into predictable operating costs.
Supply Chain Analysis
Inbound logistics costs through the Los Angeles-Long Beach port complex and trans-Pacific container availability constraints shape landed cost structures for camera hardware imports. Image sensor fabrication concentrates in Taiwan and South Korea, with final assembly drawing from Mexico and China. CMOS sensors, SoC processors, and PoE chipset supply rests on concentrated foundry capacity. Single-source vulnerability in advanced node semiconductor production exposes lead time volatility. Distribution runs through security integrators and cloud service providers that bundle installation with ongoing managed services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America video surveillance systems market is accelerating through a regulatory inflection as NDAA Section 889 compliance restructures federal procurement eligibility and favors vertically integrated domestic manufacturers over foreign-dependent supply chains.
For Market Incumbents: Shield federal contract positions by accelerating in-house production of NDAA-compliant image sensors and SoC processors to eliminate foreign component exposure. Deepen cybersecurity certification investments under NIST frameworks to extend validation timelines that deter challenger entry. The threat of open-architecture cloud-native competitors like Verkada demands defensive bundling of hardware with outcome-based service contracts.
For New Entrants and Emerging Players: Differentiate on HIPAA-aligned physical security integration for healthcare facilities in California and Texas where patient data access point coverage mandates create specification pull-through. Target cellular-enabled camera deployments for manufacturing facilities in Michigan and Ohio eliminating cabling infrastructure in hazardous environments. A private LTE/CBRS spectrum go-to-market angle unlocks remote-site applications previously uneconomical for fiber deployment.
For Investors and Strategic Acquirers: Cloud-native platform specialists with subscription monetization models and AI-on-chip firmware optimization capabilities represent priority acquisition archetypes. Long-term viability hinges on sustained R&D differentiation as edge-AI inference engines displace server-dependent analytics. Watch for inflection signals in FCC private 5G spectrum allocation velocity and municipal facial recognition ban proliferation that reshape feature monetization strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| NDAA Section 889 Compliance Certification | Federal eligibility unlocks national security installation procurement channels worth billions annually. |
| Edge-AI Firmware Optimization Investment | On-camera inference engines reduce bandwidth costs for Midwest retail and logistics operators. |
| Private LTE/CBRS Network Deployment | Manufacturing facilities in Michigan and Ohio eliminate hazardous-environment cabling infrastructure. |
| Outcome-Based Service Contract Bundling | Florida and Georgia integrators convert capital-heavy purchases into predictable per-camera monthly fees. |
| Cybersecurity Hardening Under NIST Frameworks | Critical infrastructure designations extend product validation timelines by 6-12 months. |
Research Methodology
Cross-validation between primary interviews with security integrators, municipal procurement officers, and healthcare facility directors anchors the qualitative findings against secondary validation through FCC spectrum allocation records, NIST cybersecurity framework documentation, and SEC filings from publicly traded component suppliers. Bottom-up and top-down triangulation reconciles installation volume estimates from state-level smart city program disclosures with manufacturer shipment data.
Sensitivity analysis around foundry capacity assumptions and municipal privacy statute adoption rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application vertical, end-user category, and component class alongside geographic regulatory cluster intensity. CAGRs derive from installed base growth trajectories and replacement cycle compression in legacy analog environments. Forecast inputs incorporate FCC broadband subsidy disbursement velocity and data center investment patterns across Arizona and Nevada.
Material uncertainties — semiconductor supply concentration, biometric recognition restriction proliferation, and federal infrastructure funding continuity — sit outside the modeled envelope. Forecasts reflect documented assumptions about procurement cycle compression and cloud-architecture transition rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia Pacific Surveillance IP Camera Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Global Trade Surveillance Systems Market