
 Smart Security Camera Market | 2026-2036
Smart Security Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Security Camera Market Insights
Commercial property management is recalibrating procurement priorities toward integrated surveillance ecosystems that unify access control with video analytics. Samsung Electronics leverages its semiconductor foundry capabilities to produce image sensors in-house, reducing component dependency. Amazon.com Inc. sustains channel dominance through its Ring ecosystem, which controls the consumer smart home entry point. Hangzhou Hikvision Digital Technology anchors industrial-grade deployment through specialized thermal and low-light imaging portfolios.
A smart security camera is an embedded vision device combining optical sensors, edge processors, and network interfaces to capture, analyze, and transmit video data for real-time monitoring and forensic review. These devices typically incorporate CMOS sensors with resolutions from two to eight megapixels, on-device AI accelerators for object classification, and IP65 or higher ingress protection ratings for outdoor durability. Dome cameras lead in indoor commercial installations where vandal resistance and discreet positioning matter most. Cloud-based technology segments are expanding fastest as subscription revenue models replace upfront hardware sales. Wired PoE configurations retain margin concentration in enterprise and government tenders where cybersecurity compliance and uptime guarantees are non-negotiable.
The FCC governs wireless transmission protocols and spectrum allocation for Wi-Fi-enabled devices sold in the United States, while the EU AI Act imposes risk-classification requirements on biometric identification functions deployed in European public spaces. China's SAMR enforces cybersecurity review standards for networked cameras handling sensitive visual data, creating compliance barriers for imported equipment. Stakeholders must monitor divergence between regional algorithm transparency mandates and hardware certification timelines when allocating R&D budgets across product lines.
Market Dynamics
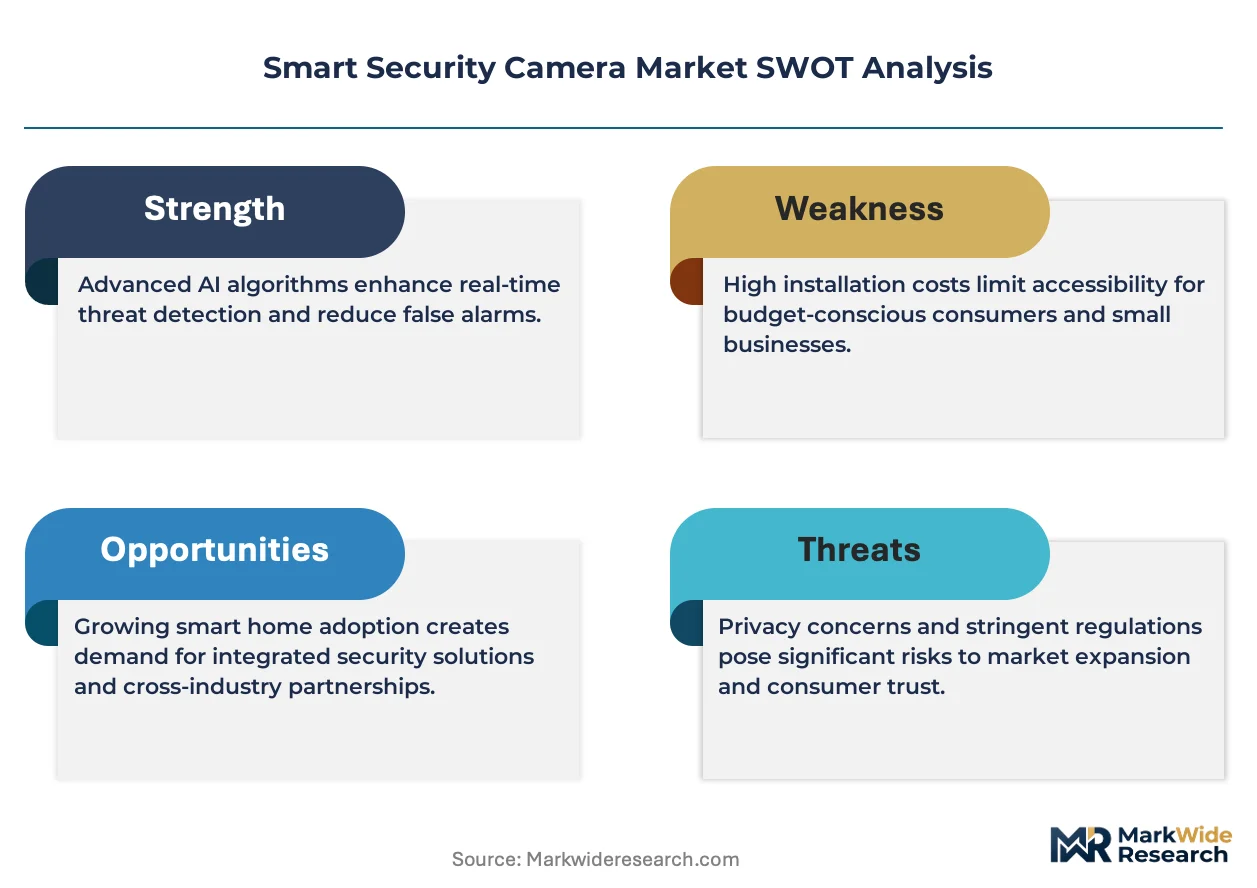
Edge AI silicon migration is compressing data transmission costs while municipal procurement cycles accelerate across transportation and public safety networks. This hardware-level intelligence shift is redistributing value capture from cloud service providers to camera OEMs with in-house semiconductor capabilities.
Growth Catalysts
- FCC spectrum allocation:Wi-Fi 6E and 7 certifications for unlicensed bands in the United States enable higher-resolution streaming without wired infrastructure, expanding residential retrofit opportunities.
- Smart city infrastructure mandates:Municipal governments in China prioritize video analytics integration across subway systems and highway corridors, creating sustained tender pipelines for multi-thousand-unit deployments.
- CMOS sensor cost curves:Sub-two-micron pixel architectures from semiconductor foundries reduce bill-of-materials for 4K entry-level units, penetrating price-sensitive commercial segments.
Market Restraints
- Image sensor supply concentration:Advanced stacked CMOS fabrication relies on a limited number of foundry nodes in East Asia, exposing procurement timelines to geopolitical friction.
- SAMR cybersecurity review:China's networked device certification requirements for visual data handling create compliance delays for imported equipment entering government tenders.
- Cloud storage substitution:Edge-local processing with SD card expansion reduces recurring subscription attach rates, compressing lifetime value per unit in consumer channels.
Strategic Opportunities
- India smart city mission:Municipal corporation tenders for intelligent traffic management systems specify thermal-visible fusion cameras, opening white space for specialized portfolio entrants.
- EU AI Act biometric classification:Risk-tiered compliance frameworks for public-space identification create premium certification tiers that vendors can monetize through audit-ready hardware.
- PoE++ convergence with access control:Unified cabling infrastructure for cameras and door controllers reduces installation labor, appealing to commercial property managers consolidating vendor relationships.
Industry Challenges
- Edge AI compiler expertise:Optimization of neural network inference for heterogeneous NPU architectures requires embedded software talent that competes with automotive and mobile sectors.
- IP65+ housing thermal management:Sealed enclosures for outdoor durability trap heat from high-TDP processors, demanding materials engineering trade-offs between ingress protection and compute headroom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Security Camera Market |
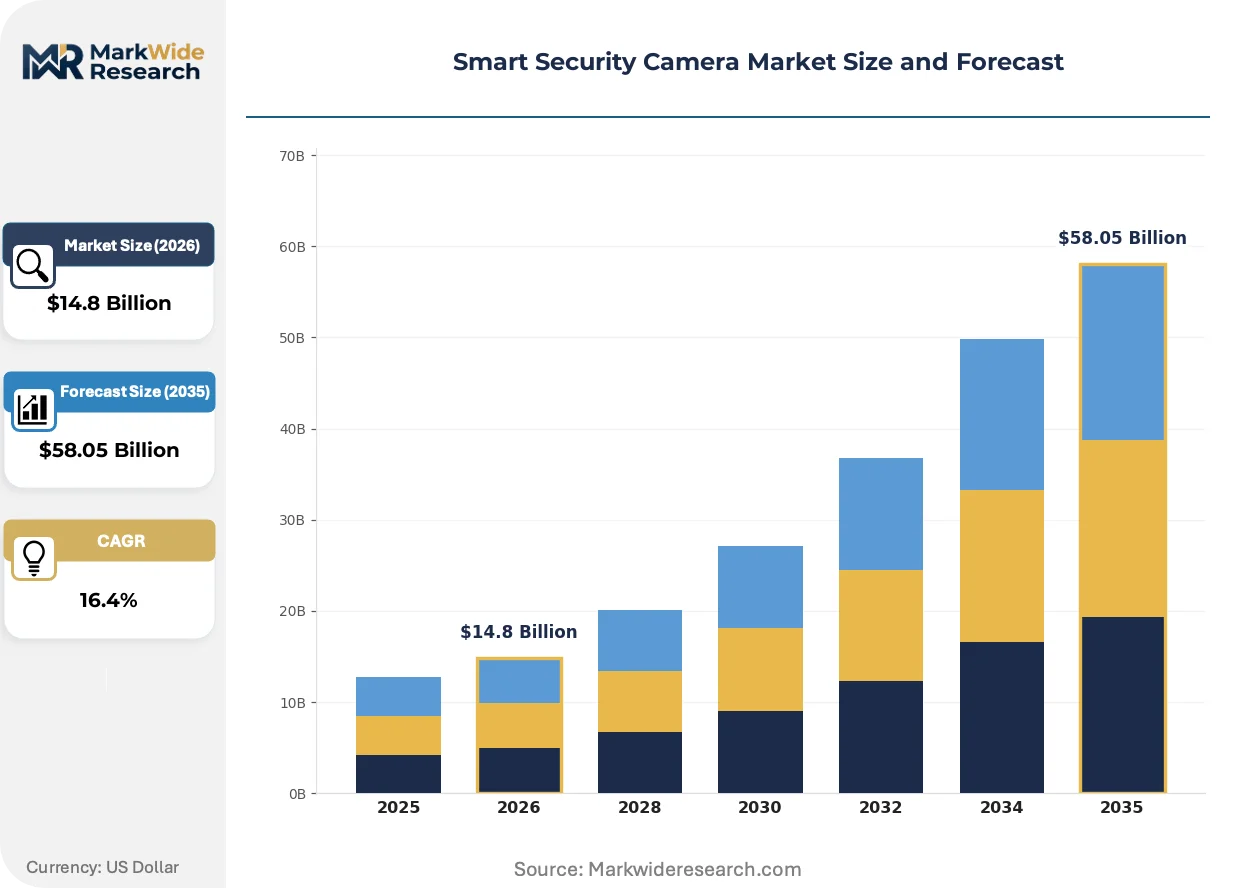
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $58.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, C-Mount Cameras Technology: Wi-Fi, Wired, PoE, Cloud-based End User: Residential, Commercial, Industrial, Government Installation Type: Indoor, Outdoor, Integrated, Standalone |
| Companies Covered | Samsung Electronics, Amazon.com Inc., Arlo Technologies Inc., Panasonic Holdings Corporation, Honeywell International Inc., Xiaomi Inc., Hangzhou Hikvision Digital Technology, ADT Inc., Anker Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Security Camera Market Trends and Innovations
Vision processor architectures are migrating inference workloads from datacenters to device endpoints, compressing latency and bandwidth requirements. This shift is redistributing competitive advantage toward OEMs with captive semiconductor design capabilities.
On-device AI accelerators is absorbing object classification and anomaly detection tasks previously routed to cloud servers. Large commercial installers in the United States specify edge-capable units to minimize recurring bandwidth costs. The technology is absorbing margin pressure from subscription-model commoditization by enabling offline functionality as a premium feature tier.
REACH substance restrictions on flame retardants in electronics housings are forcing material transitions from halogenated compounds to phosphorus-based alternatives. Camera manufacturers serving European tenders must revalidate IP ratings with new enclosure chemistries. Industrial-grade suppliers with in-house plastics molding capabilities are internalizing compliance costs faster than assembly-only competitors.
Subscription unbundling is fragmenting buyer decision criteria across hardware, software, and storage components. Small commercial property managers in Germany increasingly procure cameras without bundled cloud plans, preferring local NVR integration. This pattern concentrates in privacy-sensitive verticals where data residency requirements override convenience features.
Smart Security Camera Market Segmentation
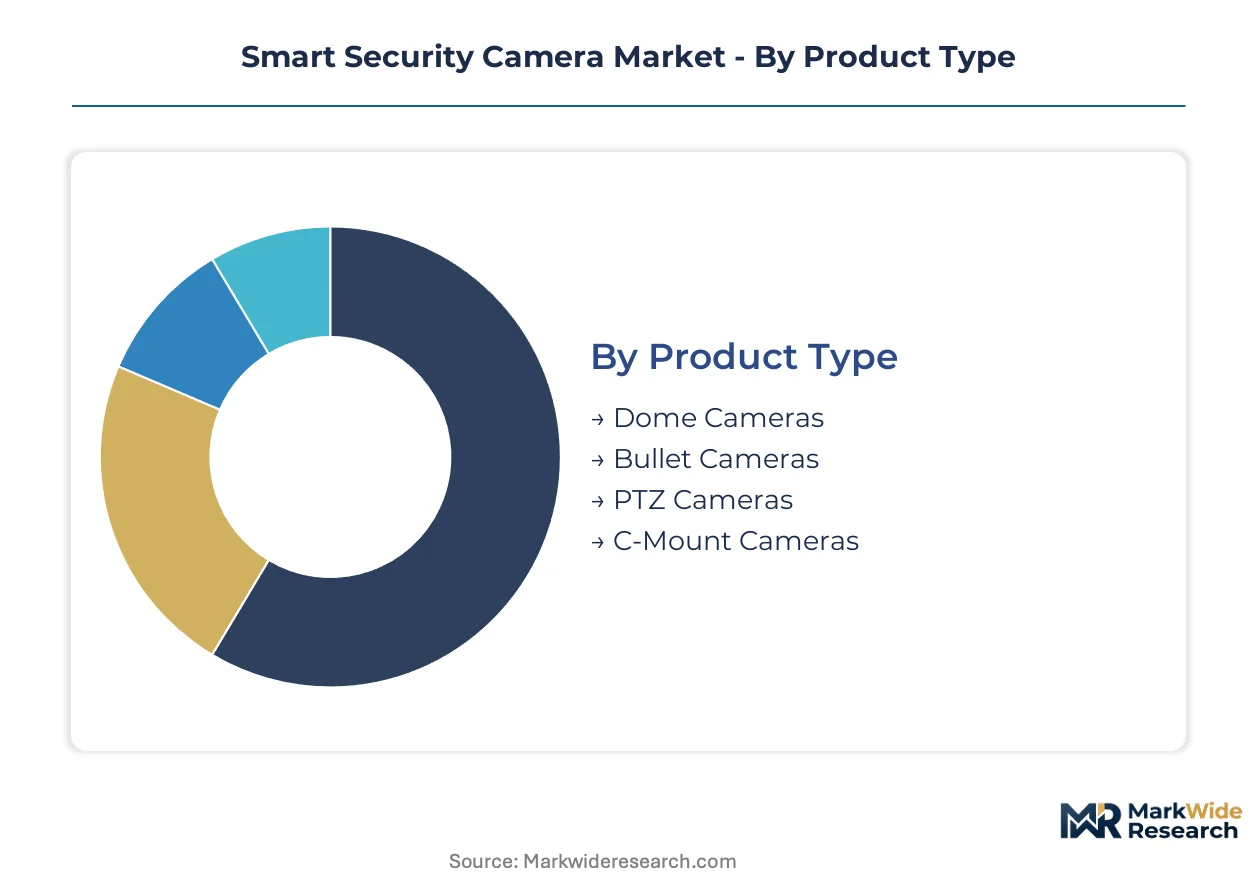
Segmentation in the Smart Security Camera Market reveals how procurement priorities diverge across certification regimes, installation environments, and buyer sophistication. Understanding these fault lines exposes where margin concentrates and which technology transitions reshape competitive positioning.
Product Type:
Dome Cameras require IP65/IP67 ingress certification for outdoor tenders and IK10 vandal resistance for transit authority specifications. Bullet Cameras face FCC Part 15 emissions testing for wireless variants and CE marking for European commercial deployment. PTZ Cameras trigger stricter cybersecurity review under China's SAMR for government contracts. C-Mount Cameras demand lens interchangeability compliance with ISO 10940 optical mounting standards.
- Dome Cameras:Compact hemispherical housings with 360-degree coverage and motorized varifocal lenses. Retail banking and hospitality verticals in Germany and France specify these for discreet ceiling mounting combined with GDPR-compliant face-blurring analytics.
- Bullet Cameras:Cylindrical weather-sealed enclosures with integrated IR illuminators for perimeter monitoring. Logistics facilities across the US Sun Belt favor these for long-throw focal lengths in unshaded yard environments where thermal cycling tests matter.
- PTZ Cameras:Pan-tilt-zoom mechanisms with preset patrol patterns and optical zoom ranges exceeding 30x. Stadium operators and port authorities require these for operator-controlled threat tracking.
- C-Mount Cameras:Modular lens-mount systems accepting CS and C-mount optics for specialized focal lengths. Machine vision integrators and laboratory security applications demand these for macro inspection capabilities.
Leading the category by volume: Dome Cameras. Growing fastest: PTZ Cameras.
Technology:
Cost tier stratification separates premium edge-AI silicon from commodity connectivity modules, with certification burdens scaling accordingly.
- Wi-Fi:Unlicensed 2.4/5/6 GHz transmission with WPA3 encryption and FCC Part 15.247 power limits. Residential retrofit channels in suburban US markets favor these for landlord-tenant installations avoiding Ethernet cable runs.
- Wired:Coaxial or Ethernet baseband transmission with galvanic isolation for industrial electromagnetic environments. Nuclear facilities and semiconductor fabs mandate these for air-gapped security zones.
- PoE:IEEE 802.3af/at/bt power delivery over twisted-pair cabling with 90W maximum draw for heater-equipped units. Commercial property managers consolidate these with access control on single cable pulls.
- Cloud-based:Encrypted tunnel architectures with SOC 2 Type II audit requirements and regional data residency options. SMB buyers in privacy-sensitive jurisdictions select these for outsourced security operations center integration.
Premium-mid-economy pricing separates PoE deployments from Wi-Fi entry points. Expanding most quickly: Cloud-based architectures.
End User:
Application maturity drives specification divergence between price-sensitive consumer channels and compliance-heavy institutional tenders.
- Residential:Self-install kits with mobile app provisioning and optional professional monitoring subscriptions. Single-family homeowners in Texas and Florida prioritize hurricane-rated outdoor units with cellular backup.
- Commercial:Multi-site management platforms with role-based access and integration APIs for building automation. Property management firms across India's smart cities specify these for centralized visibility across distributed retail portfolios.
- Industrial:Explosion-proof housings meeting ATEX/IECEx standards and vibration-resistant mounts for heavy machinery zones. Oil refineries along the US Gulf Coast and chemical complexes in Rotterdam require these for process safety monitoring.
- Government:FIPS 140-2 cryptographic modules and FedRAMP authorization for federal cloud connectivity. Correctional facilities and embassy security systems mandate these for chain-of-custody evidence handling.
Commercial verticals absorb the highest unit volumes. Government tenders command the steepest price premiums per specification tier.
Installation Type:
Geography and climate exposure determine enclosure engineering and mounting hardware requirements.
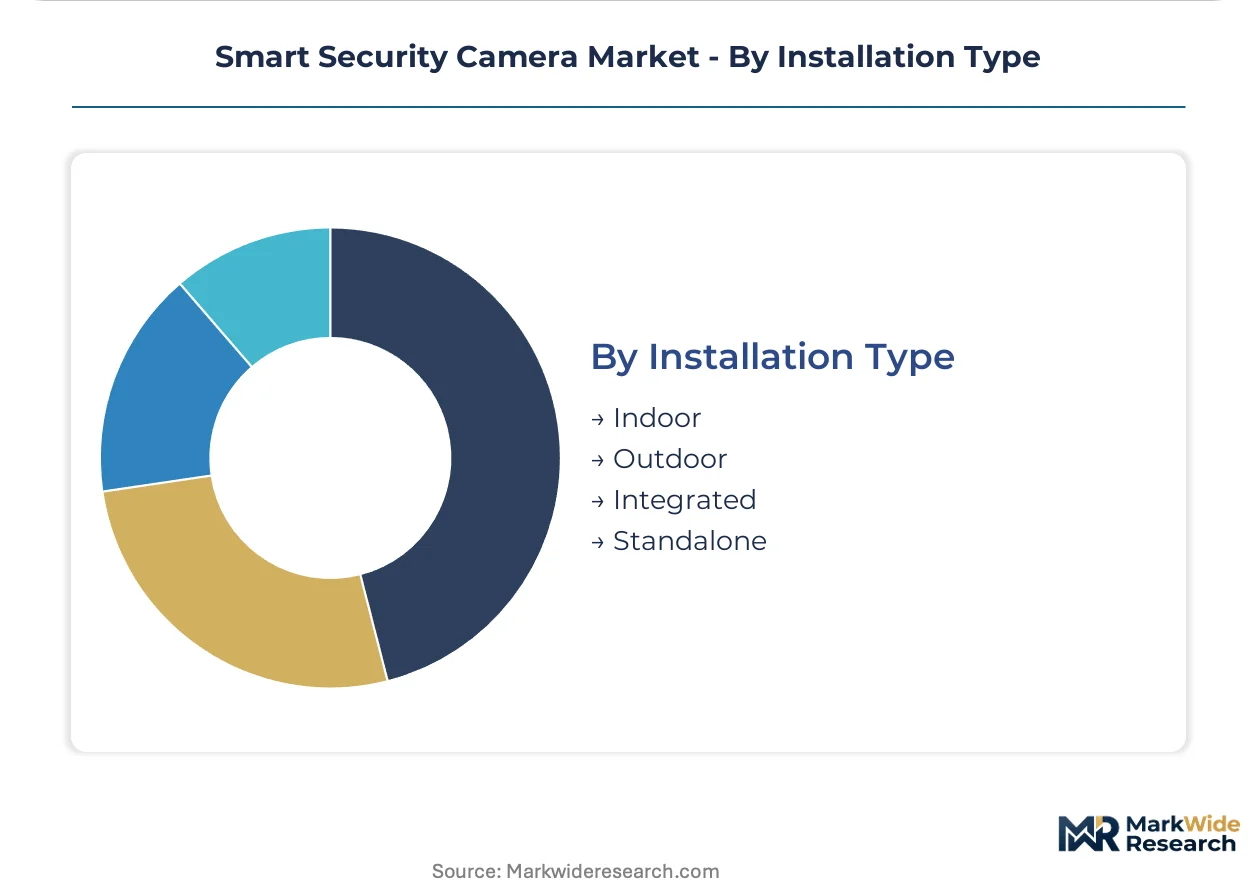
- Indoor:Recessed ceiling and wall-mount configurations with plenum-rated cabling for HVAC integration. Corporate campuses in Singapore and Sydney specify these for lobby analytics without weather sealing cost burdens.
- Outdoor:IP66/IP67 housings with integrated heaters, wipers, and sun shields for temperature extremes. Mining operations in Western Australia and cold storage facilities in Minnesota demand these for -40°C operational floors.
- Integrated:Unified platforms combining video with access control, intercom, and alarm sensor networks. Hospital systems in São Paulo and Dubai procure these for single-vendor security ecosystem consolidation.
- Standalone:Edge-recording units with local SD storage and battery backup for network-isolated operation. Remote construction sites and agricultural properties favor these for theft deterrence without infrastructure dependency.
Outdoor configurations lead installation volumes. Integrated systems gain share fastest in multi-technology consolidation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hangzhou's designation as a national-level artificial intelligence innovation pilot zone concentrates smart security camera development through tax incentives and subsidized R&D facilities. Municipal procurement programs in this cluster accelerate deployment timelines for transportation and public safety networks.
China
Domestic CMOS sensor foundries and edge-AI chip design houses cluster in the Yangtze River Delta and Pearl River Delta regions. SAMR cybersecurity review requirements for networked visual data handling create compliance barriers for imported equipment entering government tenders. Shenzhen and Hangzhou anchor volume manufacturing for both residential consumer channels and industrial-grade thermal imaging portfolios.
United States
FCC Part 15 certification for Wi-Fi 6E and Wi-Fi 7 unlicensed spectrum enables higher-resolution streaming without wired infrastructure in suburban retrofit markets. Federal procurement guidelines under FIPS 140-2 cryptographic standards restrict cloud-connected camera eligibility for correctional and embassy security systems. Dallas-Fort Worth and Atlanta metropolitan areas concentrate commercial property management demand for PoE-integrated access control ecosystems.
Germany
GDPR-compliant face-blurring analytics and data residency requirements drive specification divergence in retail banking and hospitality verticals. REACH substance restrictions on halogenated flame retardants force housing material transitions for European tender compliance. The Stuttgart and Munich industrial corridors host machine vision integrators specifying C-mount modular systems for laboratory and precision manufacturing security.
India
The Smart Cities Mission generates municipal corporation tenders for intelligent traffic management systems specifying thermal-visible fusion cameras. BIS certification requirements for electronic safety equipment create compliance timelines for imported edge-AI silicon. Bangalore and Hyderabad anchor system integrator clusters serving distributed retail portfolio management across Maharashtra and Gujarat smart city deployments.
Japan
METI funding for Society 5.0 infrastructure prioritizes edge-computing integration in aging-population monitoring applications. JIS standards for electromagnetic compatibility and environmental durability govern industrial camera specifications for semiconductor fabrication facilities. The Nagoya and Osaka manufacturing belts concentrate demand for explosion-proof and vibration-resistant housings in heavy machinery zones.
Smart Security Camera Market Competitive Landscape
Top-tier vendors anchor semiconductor-integrated portfolios, while mid-tier assemblers compete on price-sensitive commercial channels. The vendor base stratifies across captive foundry capabilities, subscription-platform ecosystems, and specialized thermal imaging portfolios. Three archetypes dominate: consumer-facing platform operators with recurring revenue models, industrial-grade specialists with in-house sensor fabrication, and system integrators bundling hardware with managed security services. Competitive moves concentrate on backward integration into CMOS design and strategic partnerships for municipal tender qualification.
Within the semiconductor-integrated tier, Samsung Electronics exemplifies captive foundry advantage through in-house image sensor production. Amazon.com Inc. occupies a position defining consumer-channel subscription economics through its Ring ecosystem. Hangzhou Hikvision Digital Technology anchors industrial-grade deployment archetypes with specialized thermal and low-light imaging portfolios. These three represent distinct competitive vectors: component independence, platform lock-in, and vertical specification depth.
| Leading Market Players |
|---|
| Samsung Electronics |
| Amazon.com Inc. |
| Arlo Technologies Inc. |
| Panasonic Holdings Corporation |
| Honeywell International Inc. |
| Xiaomi Inc. |
| Hangzhou Hikvision Digital Technology |
| ADT Inc. |
| Anker Innovations |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between FIPS 140-2 government tenders and consumer Wi-Fi channels manifests in both component sourcing strategies and margin structures. Premium-tier procurement locks in long-term foundry allocations from Taiwan and South Korea, while price-sensitive residential channels draw from spot-market CMOS inventory with compressed lead-time premiums.
Pricing Analysis
Short lead-time premiums dominate enterprise procurement, with FIPS-compliant edge-AI units commanding substantial markups against spot-market consumer inventory. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized government tenders from commercial PoE deployments and Wi-Fi retrofit kits. Cost compression in entry-level Wi-Fi segments intensifies as CMOS sensor yields improve, squeezing margins for assembly-only vendors. Government buyers exhibit lowest price sensitivity due to chain-of-custody requirements, while residential landlords prioritize total cost of ownership above performance specifications.
Supply Chain Analysis
SAMR cybersecurity qualification gates access to China's municipal tender pipeline, forcing dual-certification inventory strategies for multinational OEMs. Advanced stacked CMOS fabrication concentrates in Taiwan, South Korea, and Japan, with edge-AI silicon design anchored in the Yangtze River Delta. Bill-of-materials draws from phosphorus-based flame-retardant compounds, gallium-nitride power components, and precision-molded IP67 housings. Single-source vulnerability in advanced node foundry capacity exposes procurement timelines to geopolitical friction. Distribution runs through system integrator networks for government and industrial verticals, while consumer channels favor direct-to-retail and e-commerce fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge AI silicon migration is displacing centralized server architectures, compressing latency requirements and redistributing value capture toward camera OEMs with captive semiconductor capabilities.
For Market Incumbents: To counter subscription-model commoditization in consumer channels, deepen backward integration into CMOS sensor design and secure long-term foundry allocations from Taiwan Semiconductor Manufacturing. Prioritize FIPS 140-2 and FedRAMP certification investments to defend margin position in federal procurement segments where compliance barriers filter out mid-tier competitors. For New Entrants and Emerging Players: The price-point gap between thermal-visible fusion cameras and commodity bullet units opens white space in India's Smart Cities Mission tenders. Target municipal traffic management systems in Maharashtra and Gujarat with localized BIS certification pathways. Pursue system integrator partnerships rather than direct OEM competition to bypass entrenched channel relationships. For Investors and Strategic Acquirers: Re-rating potential sits with edge-AI chip design houses given municipal procurement acceleration across transportation networks. Long-term viability favors vendors with in-house NPU compiler expertise and thermal management IP for sealed outdoor housings. Watch for inflection in India BIS certification timelines as signal of market access normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Silicon Development | In-house NPU design reduces dependency on Qualcomm and Ambarella for inference acceleration. |
| Dual Certification Investment | Parallel FIPS 140-2 and SAMR qualification unlocks federal and Chinese municipal tender access. |
| Thermal Management IP Acquisition | Specialized heat-dissipation patents resolve IP67 sealing constraints for high-TDP processors. |
| System Integrator Partnership | Channel alliances with India-based integrators bypass direct competition with Hikvision and Xiaomi. |
| Subscription Unbundling | Hardware-only SKUs capture privacy-sensitive commercial buyers in Germany and France avoiding cloud lock-in. |
Research Methodology
Independent corroboration across semiconductor foundry executives, municipal procurement officers, and commercial property managers underwrites the qualitative findings in this study. Primary fieldwork encompassed interviews with edge-AI chip architects, IP67 housing materials engineers, and security systems integrators spanning China, the United States, Germany, and India. Secondary validation drew from FCC equipment authorization databases, SAMR cybersecurity review filings, EU AI Act implementation guidance, and BIS certification registries. Bottom-up unit economics triangulated against top-down municipal tender aggregation.
Comparable-period anchoring to historical procurement cycles across transportation, public safety, and commercial real estate verticals structured the forecast window. Segmentation dimensions modeled include product architecture, connectivity technology, installation environment, end-use vertical, and regional regulatory cluster. CAGRs derived from weighted average of volume deployment trajectories and value-per-unit escalation paths. Forecast inputs incorporated CMOS sensor cost curve projections and edge-AI accelerator penetration rates.
Inputs from foundry capacity disclosures and municipal tender databases were available through the study window; gaps in real-time inventory positioning data introduce uncertainty bands around near-term price assumptions. Forecasts reflect documented assumptions regarding regulatory timeline stability and foundry node yield progression. A model refresh is warranted upon material change in FCC spectrum allocation or SAMR cybersecurity review processing velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
AI CCTV Market