
 France Surveillance Camera Market | 2026-2036
France Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
France Surveillance Camera Market Insights
Market Context
High-definition and AI-enabled specification tiers is redrawing competitive boundaries in the France Surveillance Camera Market. Dahua Technology leverages its integrated manufacturing scale to dominate entry-level and mid-range IP camera supply. Axis Communications AB differentiates through open-platform architecture and cybersecurity-hardened firmware development. Bosch Security and Safety Systems anchors its position with German-engineered reliability standards adapted for French critical infrastructure tenders.
Technical Definition and Segment Structure
A surveillance camera is an optoelectronic device comprising image sensors, signal processors, and network interfaces that captures, encodes, and transmits video data for real-time monitoring or forensic analysis, typically operating at resolutions from 2MP to 8MP with low-light sensitivity below 0.01 lux. These systems serve commercial and institutional security managers requiring perimeter protection, crowd analytics, and incident verification across retail floors, transit platforms, and public squares. Dome and bullet product types occupy the mature volume base, while PTZ configurations capture expanding margin pools in transportation hubs demanding active tracking capabilities. IP and cloud-based technology segments are outpacing analog legacy stock, with wireless installations gaining traction in heritage building retrofits where cable routing proves prohibitive.
Regulatory Environment and Outlook
France's CNIL imposes strict purpose-limitation and data-retention rules on video surveillance operators, while the EU AI Act classifies biometric identification systems as high-risk, mandating conformity assessments before deployment. The EU Green Deal and national decarbonization targets are additionally pushing vendors toward energy-efficient PoE++ designs and lower-standby power chipsets. Stakeholders must monitor how upcoming delegated acts under the AI Act define permissible use cases for behavioral analytics in public spaces.
Market Dynamics
France's surveillance camera market faces structural pressure from the EU AI Act's biometric classification rules, which force vendors to redesign analytics pipelines for public-space deployments. This regulatory inflection is compressing product development cycles while elevating compliance costs.
Growth Catalysts
- Smart city infrastructure mandates:Lyon and Marseille are deploying networked video systems for traffic management and public safety, creating procurement pull from municipal authorities.
- CNIL framework clarity:France's data protection authority has issued detailed guidance on purpose limitation for video surveillance, reducing legal uncertainty for operators investing in cloud-connected architectures.
- PoE++ power standard adoption:Energy-efficient Power over Ethernet designs are enabling single-cable installations in heritage building retrofits where conduit access is restricted.
Market Restraints
- Image sensor supply concentration:Sony and OmniVision dominate CMOS sensor fabrication, creating input cost volatility when foundry capacity tightens.
- EU AI Act conformity assessment timelines:Biometric identification systems require third-party certification before deployment, extending sales cycles by six to twelve months.
- Cloud storage substitution pressure:Edge analytics with local SD recording are displacing full cloud architectures in budget-constrained municipal tenders.
Strategic Opportunities
- Occitanie and Hauts-de-France rail corridors:SNCF's platform modernization program is creating demand for PTZ cameras with active tracking in secondary transit hubs.
- Behavioral analytics convergence:Integration of thermal imaging with video analytics is opening crowd-density monitoring applications in stadium and event venues.
- EU Green Deal procurement incentives:Public tenders now weight energy consumption criteria, favoring vendors with low-standby-power chipset designs.
Industry Challenges
- Cybersecurity firmware engineering scarcity:Vendors struggle to recruit embedded security specialists capable of hardening Linux-based camera operating systems against evolving threat vectors.
- Legacy analog integration complexity:Hybrid deployments require protocol translation between coaxial infrastructure and IP backbones, inflating installation labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Surveillance Camera Market |
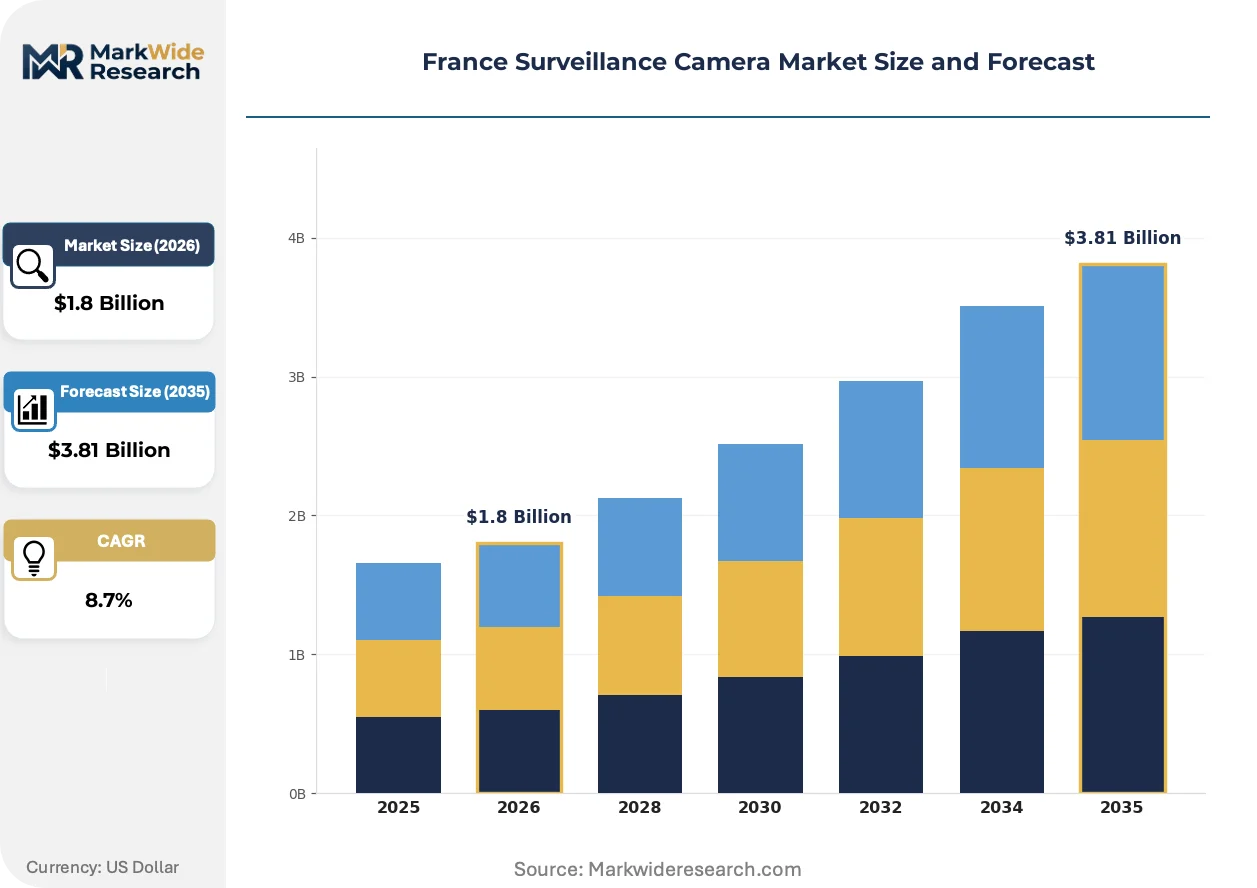
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Bullet, PTZ, Box Technology: Analog, IP, Wireless, Cloud-Based Installation: Indoor, Outdoor, Covert, Remote End User: Retail, Transportation, Residential, Government |
| Companies Covered | Dahua Technology, Lorex Corporation, Axis Communications AB, Hanwha Vision Co. Ltd, Genetec, Bosch Security and Safety Systems, Eagle Eye Networks, Mobotix, Hangzhou Hikvision Digital Technology Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Surveillance Camera Market Trends and Innovations
Edge computing architectures are redistributing processing load away from centralized servers, enabling real-time analytics without bandwidth saturation. This shift is altering how French municipalities architect their video surveillance networks.
AI inference chips embedded directly within camera housings are fragmenting the traditional server-centric analytics market. Transportation authorities in Paris and Lyon are piloting these devices for license plate recognition and abandoned-object detection. The technology is compressing margins for standalone video management software vendors.
France's CNIL has tightened consent requirements for biometric data processing in public spaces, forcing operators to document legal basis before activating facial recognition. Commercial security providers must now maintain audit trails demonstrating purpose limitation. Retail and banking end-users are responding by disabling analytics features rather than assuming compliance risk.
Subscription-based hardware provisioning is displacing outright purchase in municipal procurement. Île-de-France transit operators now lease camera fleets with bundled maintenance, shifting capital expenditure to operational budgets. This model is most visible in smart city contracts where technology obsolescence risk resides with vendors.
France Surveillance Camera Market Segmentation
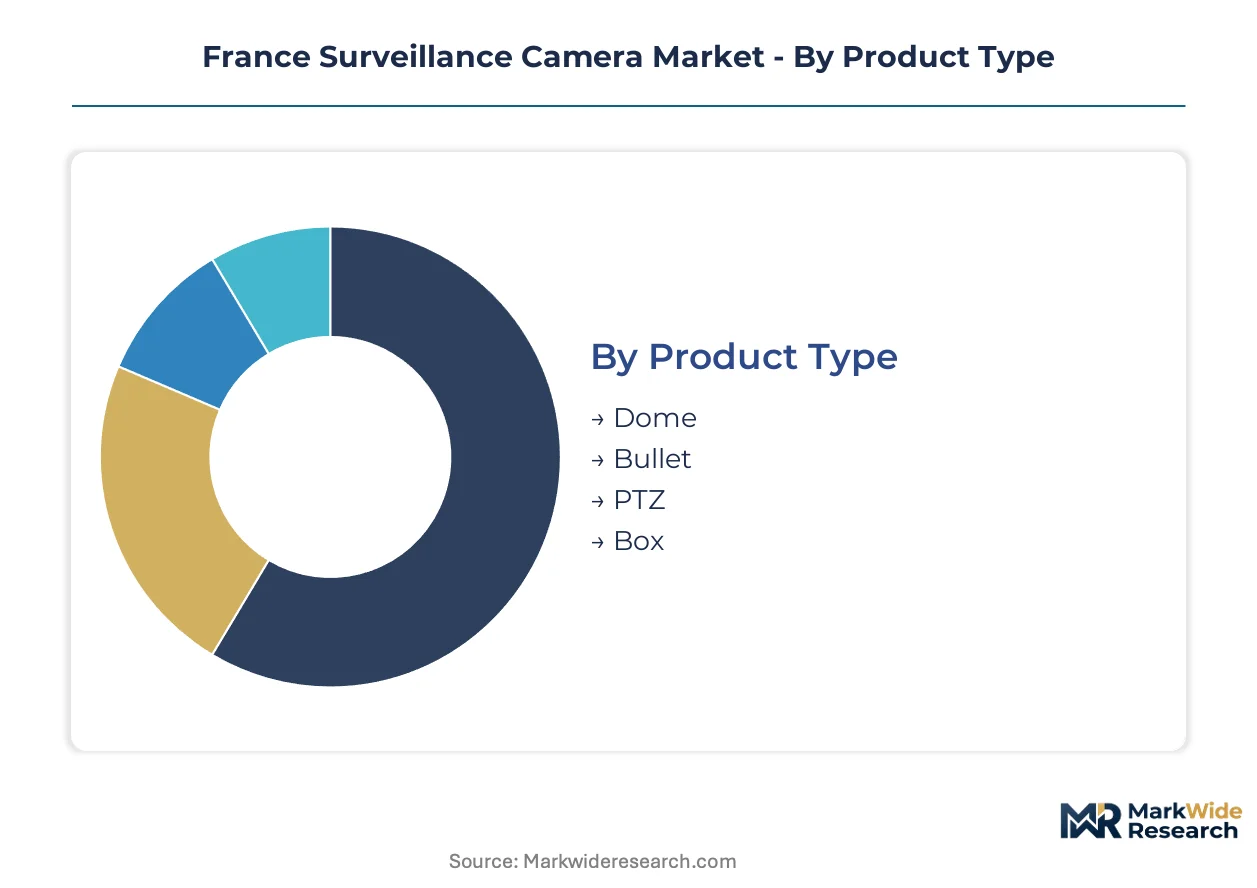
Segmentation in the France surveillance camera market reveals how procurement priorities diverge across application environments and infrastructure constraints. Each dimension carries distinct regulatory, technical, and budgetary implications that reshape vendor positioning.
Product Type:
Dome and bullet configurations anchor domestic volume, while PTZ systems concentrate in export-oriented rail and stadium projects across the EU.
- Dome:Hemispherical housings with vandal-resistant polycarbonate domes deliver 360-degree coverage from fixed positions. Demand clusters in Île-de-France retail banking branches and Marseille public housing lobbies, where discreet ceiling mounting satisfies CNIL visibility requirements. The form factor dominates new construction with integrated PoE++ compatibility.
- PTZ:Pan-tilt-zoom mechanisms with motorized optical zoom up to 30x enable active target tracking. SNCF deploys these along Lyon-Marseille TGV corridors for platform surveillance, leveraging French-made Pelco and Axis units that meet EN 50155 rail standards. The segment commands premium pricing in transportation tenders.
- Bullet:Cylindrical weather-sealed housings with integrated IR illuminators serve perimeter applications.
- Box:Modular camera bodies with interchangeable C/CS-mount lenses address specialized low-light and telephoto requirements.
Dome configurations hold the largest share; momentum sits with PTZ as transportation authorities upgrade legacy fixed installations.
Technology:
Cost tier differentiation separates budget-constrained municipal retrofits from premium smart city deployments with full analytics stacks.
- IP:Network-addressable cameras with H.265+ encoding and ONVIF Profile S/T interoperability form the replacement backbone for analog estates. French government tenders now mandate IP as baseline for new installations, with cybersecurity certification from ANSSI becoming a discriminatory criterion in critical infrastructure awards.
- Cloud-Based:Architectures with edge-to-cloud video pipelines and SaaS management platforms are gaining traction in multi-site retail chains. Decathlon and Carrefour pilot these for centralized loss prevention across hypermarket networks, though CNIL data localization rules limit full cloud adoption in sensitive zones.
- Analog:Coaxial-based CVBS/TVI systems persist in heritage building retrofits with conduit restrictions.
- Wireless:Wi-Fi 6 and 4G/LTE cellular backhaul address cable-routing impossibilities in protected monuments.
IP technology holds the largest share; cloud-based architectures are climbing the fastest as subscription procurement models displace capital purchases.
Installation:
Application environment dictates housing specifications, with outdoor and covert segments commanding specialized engineering margins.
- Outdoor:IP67/IK10-rated enclosures with integrated heaters and hydrophobic lens coatings withstand Atlantic coastal corrosion and Alpine freeze-thaw cycles. Demand concentrates in port authorities at Le Havre and Calais, where salt spray resistance determines procurement winners.
- Indoor:Standard IP54 housings with acoustic dampening serve climate-controlled environments.
- Covert:Miniaturized pinhole and smoke-detector-disguised units address law enforcement and casino surveillance requirements.
- Remote:Solar-powered cellular cameras with battery backup serve agricultural and construction site monitoring.
Outdoor installations hold the largest share; covert systems are gaining share fastest as regulatory scrutiny intensifies on visible surveillance.
End User:
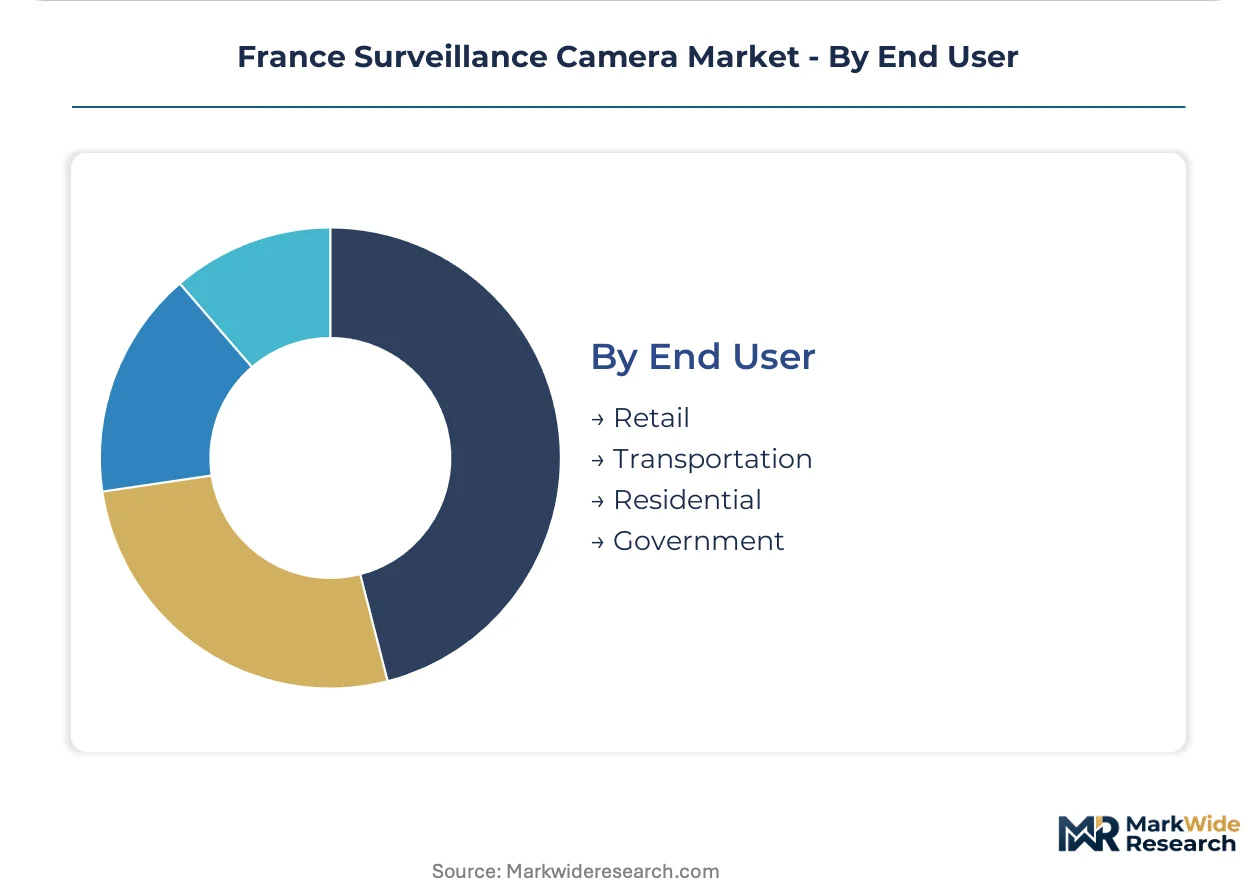
Customer type segmentation maps directly to budget cycles and compliance maturity, with government and transportation leading specification intensity.
- Government:Municipal police, prefecture security, and national monument protection drive the most stringent certification requirements. The EU AI Act high-risk system classification forces conformity assessments for biometric deployments in Paris and Lyon public spaces, extending vendor sales cycles.
- Transportation:SNCF, RATP, and airport operators under DGAC oversight demand EN 50155 and NFPA 130 compliance. The segment exhibits steepest expansion trajectory as Occitanie and Hauts-de-France rail modernization programs accelerate camera refresh cycles.
- Retail:Hypermarket and luxury boutique chains prioritize shrinkage reduction over advanced analytics.
- Residential:Gated communities and co-ownership syndicates drive consumer-grade IP camera demand.
Government end users hold the largest share; transportation is expanding most quickly as infrastructure investment programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camera manufacturing concentrates in East Asian component hubs, while French demand pulls through domestic system integrators and direct municipal procurement channels. The national market structure reflects this geographic split between upstream sensor fabrication and downstream deployment expertise.
Île-de-France
Paris Metro modernization and RATP platform security upgrades drive PTZ camera procurement. CNIL's biometric processing guidance shapes deployment protocols for facial recognition trials at Gare du Nord and Châtelet-Les Halles. The Paris-Saclay technology cluster hosts edge analytics startups supplying SNCF with embedded inference solutions.
Auvergne-Rhône-Alpes
Lyon's smart city program accelerates networked video installations for traffic flow optimization and public safety coordination. The EU AI Act conformity assessment requirements extend vendor sales cycles for biometric deployments in Place Bellecour pedestrian zones. Grenoble's semiconductor research institutes collaborate with Sony on low-light CMOS sensor optimization for Alpine surveillance conditions.
Provence-Alpes-Côte d'Azur
Marseille port authority security mandates and coastal corrosion resistance specifications dominate outdoor camera procurement. ANSSI cybersecurity certification has become a discriminatory criterion for critical infrastructure tenders at Fos-sur-Mer container terminals. The Aix-Marseille-Provence metropolis pilots solar-powered cellular cameras for remote construction site monitoring.
Hauts-de-France
SNCF's Lille-Europe station modernization and Calais port border security programs create concentrated demand. The region's Channel Tunnel access points require EN 50155-compliant rail-certified cameras with electromagnetic interference hardening. Lille's metropolitan authority deploys edge-to-cloud architectures for multi-site retail loss prevention across Euralille commercial zones.
Occitanie
Toulouse aerospace facility perimeter protection and Montpellier tram network expansion drive specialized camera demand. DGAC oversight mandates shape airport security specifications at Toulouse-Blagnac for Airbus manufacturing site protection. The region's agricultural cooperatives adopt remote solar-powered surveillance for vineyard and olive grove monitoring.
France Surveillance Camera Market Competitive Landscape
Concentration sits with integrated manufacturing conglomerates and cybersecurity-specialized European vendors. The vendor base separates into three tiers: East Asian scale producers dominating volume supply, German-engineered reliability specialists capturing critical infrastructure premiums, and North American software-centric platforms converting municipal contracts to subscription models. Competitive moves center on compliance engineering for EU AI Act biometric restrictions and energy-efficient chipset redesigns for Green Deal procurement weighting.
Among East Asian scale producers, Dahua Technology and Hangzhou Hikvision Digital Technology Co. Ltd represent the manufacturing-integrated archetype with captive sensor supply chains. Axis Communications AB exemplifies the European cybersecurity-hardened positioning required for ANSSI-certified tenders. Bosch Security and Safety Systems occupies the German-engineered reliability tier adapted for French rail and airport standards. These three archetypes illustrate how vendor positioning stratifies across compliance intensity, manufacturing scale, and firmware security specialization.
| Leading Market Players |
|---|
| Dahua Technology |
| Lorex Corporation |
| Axis Communications AB |
| Hanwha Vision Co. Ltd |
| Genetec |
| Bosch Security and Safety Systems |
| Eagle Eye Networks |
| Mobotix |
| Hangzhou Hikvision Digital Technology Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Edge-to-cloud pipeline substitution for full cloud architectures is redrawing procurement economics, compressing vendor margins while shifting supply geography toward Taiwanese chipset foundries and Korean memory fabrication. This dual migration simultaneously elevates pricing power for PoE++ power management component suppliers and erodes SaaS platform recurring revenue models.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across the France surveillance camera market, separating biometric-enabled premium systems from standard IP configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with ANSSI-cybersecurity-hardened firmware commanding substantial premiums over baseline ONVIF-compliant units. Cost compression in entry-level segments is intensifying because municipal tender boards now weight energy consumption criteria under Green Deal procurement rules. Transportation authorities exhibit lowest price sensitivity due to EN 50155 rail certification requirements, while retail loss prevention departments drive hardest bargain negotiations.
Supply Chain Analysis
TSMC foundry capacity allocation in Taiwan underwrites CMOS image sensor fabrication for Sony and OmniVision, creating chokepoint vulnerability when automotive and smartphone demand spikes compete for 28nm process nodes. Component sourcing draws from Japanese optical lens specialists, German engineered-housing suppliers, and Chinese cable and connector manufacturers. Single-source vulnerability concentrates in Sony's dominance of low-light sensor technology, where foundry allocation decisions in Hsinchu directly impact French vendor delivery schedules. Distribution runs through Paris-based system integrators and direct municipal procurement channels, with SNCF and RATP operating dedicated vendor qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with EU AI Act compliance complexity, as biometric classification rules and CNIL purpose-limitation mandates splinter demand into specialized vendor archetypes that scale players struggle to serve simultaneously.
For Market Incumbents: Consolidate firmware security engineering capabilities through acquisition of embedded Linux specialists, addressing cybersecurity talent scarcity that threatens ANSSI certification maintenance. Deepen backward integration into edge inference chip design to capture margins eroding toward standalone video management software vendors. Lock in long-term foundry allocation agreements with TSMC and UMC before automotive sensor demand intensifies. For New Entrants and Emerging Players: Post-installation compliance audit services represent underserved white space where Dahua and Hikvision volume-focused models under-serve CNIL documentation requirements. Municipalities in Occitanie and Hauts-de-France present most penetrable geography, with rail modernization programs creating greenfield PTZ demand outside incumbent transportation relationships. Pursue partnership-first go-to-market with Paris-Saclay edge analytics startups for bundled AI inference solutions. For Investors and Strategic Acquirers: The market sits at a regulatory-inflection phase that favors cybersecurity-specialized European vendors over East Asian scale producers. Long-term viability across the analysis window hinges on EU AI Act delegated acts defining permissible behavioral analytics use cases, with biometric deployment permissions serving as critical inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| ANSSI Certification Investment | Cybersecurity-hardened firmware unlocks critical infrastructure tenders at SNCF and DGAC-regulated airports. |
| PoE++ Chipset Redesign | Low-standby-power designs capture Green Deal procurement weighting in municipal smart city contracts. |
| Edge Inference Partnership | Integration with Paris-Saclay startups displaces server-centric analytics in Lyon traffic management pilots. |
| Compliance-as-a-Service Launch | CNIL audit trail automation addresses retail and banking end-users disabling analytics features. |
| Rail Corridor Specialization | EN 50155-certified PTZ development captures SNCF platform modernization in secondary transit hubs. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, SNCF infrastructure planners, CNIL compliance consultants, and system integrators; and secondary validation through ANSSI certification databases, EU AI Act delegated act tracking, and French government tender portal records. Bottom-up triangulation cross-referenced camera shipment volumes by technology segment against top-down public security budget allocations across Île-de-France, Auvergne-Rhône-Alpes, and Provence-Alpes-Côte d'Azur regional authorities.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, technology architecture, installation environment, and end-user compliance maturity. CAGRs derived from regression analysis of historical procurement cycles, overlaying regulatory inflection points from EU AI Act implementation timelines. Forecast inputs incorporated foundry capacity utilization rates for CMOS sensors and municipal debt financing conditions for infrastructure investment programs.
Forecasts assume regulatory continuity in EU AI Act biometric classification and CNIL data retention enforcement; material policy shifts would require re-modeling deployment permission scopes and sales cycle durations. Practitioners should keep alternative scenarios live as delegated acts defining behavioral analytics use cases evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Germany Surveillance IP Camera Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
India Surveillance Storage Market