
 Security Cameras (IR Illuminator) Market | 2026-2036
Security Cameras (IR Illuminator) Market Size, Share, and Industry Trends Forecast 2026-2036
Security Cameras (IR Illuminator) Market Analytics
The premium and commodity tiers of the Security Cameras (IR Illuminator) market is consolidating around divergent technology stacks, with high-end systems integrating AI-powered analytics and multi-spectral fusion while budget segments compete on LED array density and power efficiency alone. Hikvision Digital Technology Co. Ltd leverages its vertically integrated sensor manufacturing to control cost structures across both tiers. Dahua Technology sustains aggressive R&D spending on deep-learning-optimized IR illumination algorithms. Axis Communications differentiates through open-platform architecture that allows third-party analytics integration.
Security Cameras (IR Illuminator) refers to surveillance imaging systems incorporating infrared LED arrays or laser diodes emitting near-infrared wavelengths between 750 and 940 nanometers, enabling visible-spectrum image capture in zero-lux environments through CMOS or CCD sensors with removed IR-cut filters. These systems serve critical functions in perimeter defense, critical infrastructure monitoring, and law enforcement evidence collection where ambient lighting cannot be deployed or must remain covert. Dome Camera formats dominate indoor commercial installations where vandal resistance and discreet positioning matter most, while PTZ Camera configurations command the fastest growth trajectory due to expanding perimeter security requirements at logistics hubs and energy facilities. IP Surveillance technology leads value generation as network infrastructure upgrades displace legacy analog deployments across enterprise and government accounts.
FCC equipment authorization requirements govern RF emissions from wireless-enabled IR illuminator systems in the United States, while the EU AI Act imposes escalating compliance burdens on cameras deploying biometric identification in public spaces. India's BIS certification mandates and the PLI scheme for electronics manufacturing are simultaneously raising quality barriers and incentivizing domestic production capacity for export-oriented suppliers. Stakeholders must monitor how fragmented cybersecurity standards across national regulators reshape procurement specifications and aftermarket software update obligations.
Market Dynamics
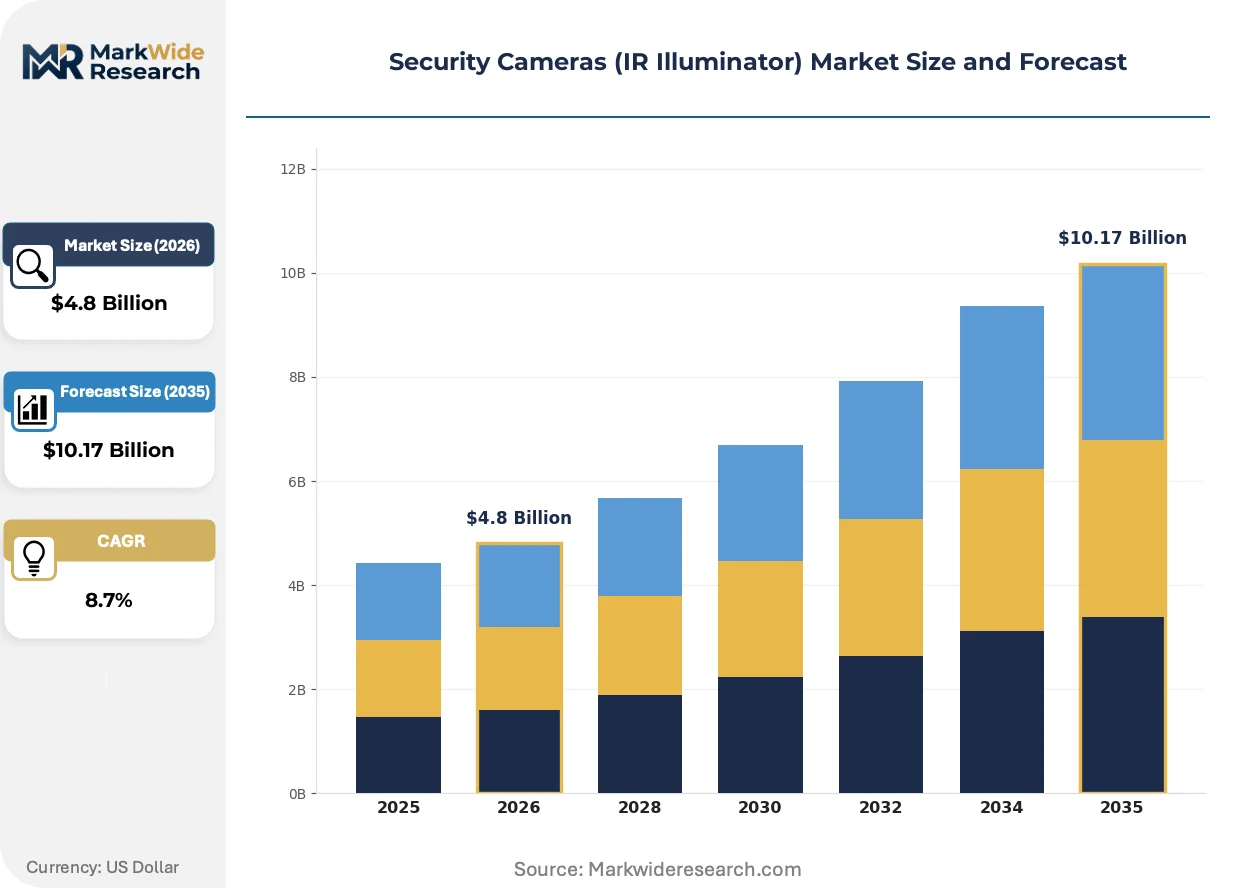
The Security Cameras (IR Illuminator) market is reshaping around the collision between AI-enabled analytics requirements and fragmented cybersecurity compliance across national borders. Municipal procurement teams now specify multi-spectral fusion capabilities alongside zero-trust network architecture, forcing hardware vendors to absorb software development costs.
Growth Catalysts
- Smart City Infrastructure Mandates:India's Safe City Mission and PLI scheme for electronics manufacturing are channeling public capital toward localized IR-enabled surveillance deployment at municipal scale.
- EU AI Act Compliance Pathways:Biometric identification restrictions in public spaces are accelerating demand for privacy-preserving infrared analytics that operate without facial recognition databases.
- Perimeter Security Modernization:Logistics hubs and energy facilities are replacing legacy analog systems with IP-based PTZ configurations featuring adaptive IR illumination algorithms.
Market Restraints
- CMOS Sensor Supply Concentration:Taiwan and South Korea dominate advanced image sensor fabrication, creating vulnerability to geopolitical disruption or export control expansion.
- FCC Equipment Authorization Complexity:Wireless-enabled IR systems face extended RF emissions testing timelines that delay product launches by 6-12 months in the United States.
- LED Array Cost Volatility:Epitaxial wafer prices for near-infrared emitters fluctuate with gallium arsenide substrate availability, compressing margins on budget-tier products.
Strategic Opportunities
- Underpenetrated Critical Infrastructure:Brazil's ANVISA-regulated pharmaceutical manufacturing corridors lack compliant night-vision surveillance for cold-chain integrity monitoring.
- Multi-Spectral Fusion Convergence:Combining thermal imaging cores with active IR illumination enables all-weather perimeter detection without visible-light signature exposure.
- Cloud-Connected Maintenance Contracts:Subscription-based firmware update and cybersecurity patch services are displacing traditional hardware-only procurement in German industrial accounts.
Industry Challenges
- Cybersecurity Firmware Engineering Shortage:Vendors struggle to recruit embedded systems specialists capable of implementing IEC 62443 industrial security standards across legacy product lines.
- CE Marking IoT Transition Friction:The European Union's updated cybersecurity requirements for connected devices are forcing redesign cycles that strain R&D budgets at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Cameras (IR Illuminator) Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Camera, Bullet Camera, PTZ Camera, Box Camera Technology: IP Surveillance, Analog, HD-SDI, Wireless End User: Retail, Banking, Residential, Government Distribution Channel: Online, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Hikvision Digital Technology Co. Ltd, Dahua Technology, Axis Communications, Bosch Security Systems, Honeywell International, Panasonic Corporation, Teledyne FLIR, Hanwha Techwin, Avigilon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Cameras (IR Illuminator) Market Evolving Landscape
Deep-learning inference at the network edge is compressing the latency between IR image capture and actionable alert generation. Hardware vendors are racing to integrate neural processing units directly into camera SoCs, eliminating dependency on cloud-based analytics for real-time threat detection.
VCSEL-based structured light arrays are consolidating as the preferred illumination source for precision biometric applications. Financial services and data center operators in Singapore and the UAE are deploying these systems for liveness detection in zero-light access control environments. The technology is consolidating supplier power around compound semiconductor foundries with vertical epitaxy capabilities.
The EU AI Act's risk-based classification system is forcing biometric-capable IR camera manufacturers to maintain separate product SKUs for European and non-European markets. Industrial buyers in France and Germany are now requiring documentation of algorithm training data provenance before contract award. Systems lacking auditable exclusion of protected demographic features face automatic disqualification from public procurement.
Equipment-as-a-service models are displacing capital purchase arrangements among North American enterprise security departments. Managed service providers bundle IR camera hardware with remote monitoring and predictive maintenance, transferring obsolescence risk from end-users to integrators. This shift concentrates most visibly in California and Texas, where property technology budgets favor operational expenditure treatment.
Security Cameras (IR Illuminator) Market Segmentation
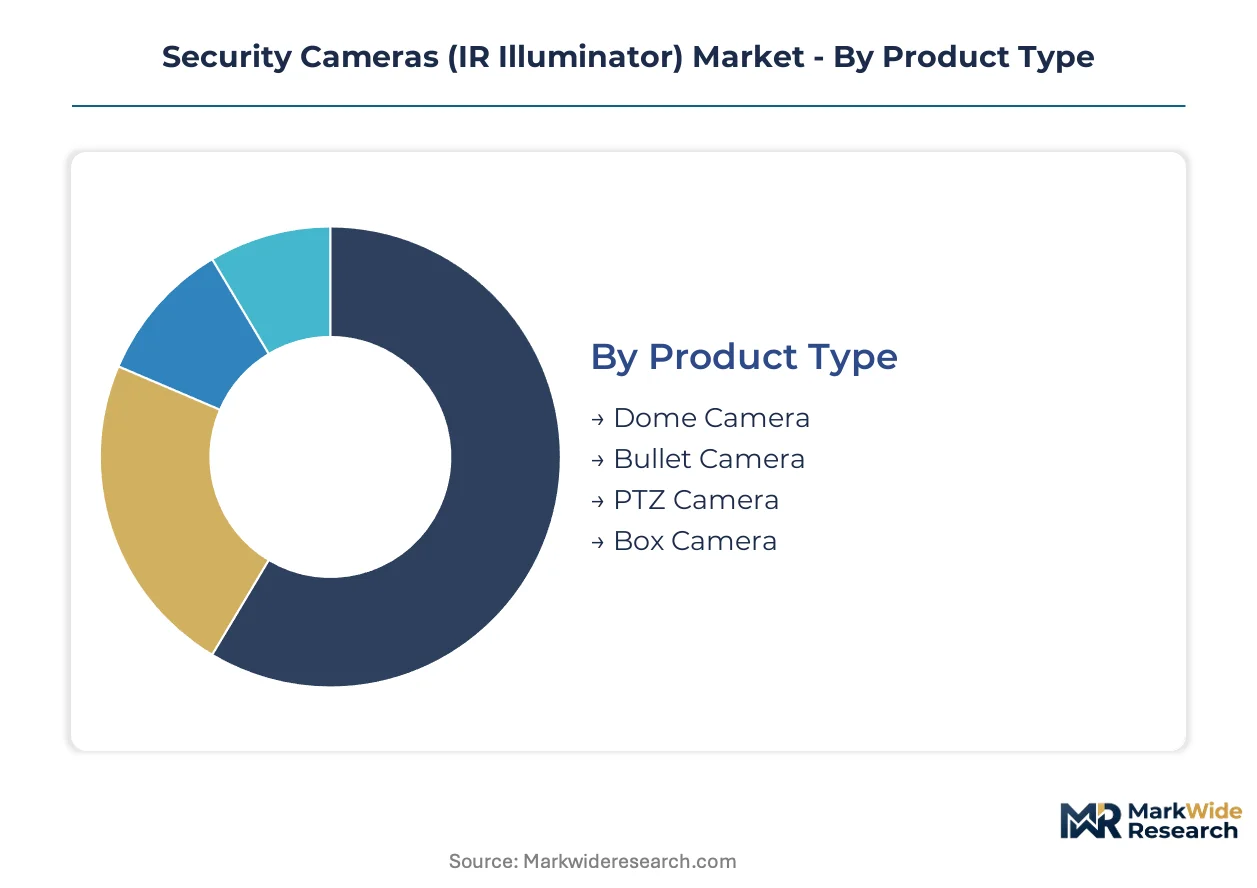
IR illuminator configurations vary sharply in certification burden, power architecture, and network integration requirements. Procurement teams specify segments based on ambient light conditions, perimeter geometry, and cybersecurity compliance mandates rather than hardware cost alone.
Product Type:
Dome Camera and Bullet Camera carry divergent FCC equipment authorization pathways for RF-integrated variants, while PTZ configurations face extended electromagnetic compatibility testing timelines in EU markets.
- Dome Camera:Vandal-resistant housings with integrated IR LED rings enable discreet indoor positioning. Banking lobbies in Frankfurt and Singapore specify these for ATM surveillance under GDPR and PDPA privacy frameworks. Demand concentrates where aesthetic constraints conflict with security requirements.
- PTZ Camera:Motorized pan-tilt-zoom mechanisms demand adaptive IR illumination algorithms that adjust beam angle and intensity in real time. Logistics hubs across India deploy these for perimeter coverage under Safe City Mission procurement guidelines. The segment climbs fastest as energy facilities replace fixed-view systems.
- Bullet Camera:Weather-sealed cylindrical housings with external IR arrays suit exposed mounting positions.
- Box Camera:Modular designs accept interchangeable lenses and illuminator modules for specialized applications.
Leading the category by volume: Dome Camera. Growing fastest: PTZ Camera.
Technology:
Cost tiers separate network-native architectures from legacy infrastructure, with IP Surveillance commanding premium positioning against declining analog maintenance contracts.
- IP Surveillance:Network-video-protocol cameras with Power-over-Ethernet IR illuminator modules enable centralized firmware management. German industrial accounts specify these for IEC 62443 cybersecurity compliance, displacing analog systems through subscription-based maintenance models.
- Analog:Coaxial-cable systems with separate IR illuminator power supplies persist in budget-constrained municipal retrofits. India's tier-2 cities maintain these under PLI scheme cost ceilings, though BIS certification mandates accelerate replacement cycles.
- HD-SDI:Uncompressed digital video over coax suits broadcast-quality surveillance with minimal latency.
- Wireless:Wi-Fi or cellular backhaul eliminates cabling but triggers extended FCC RF emissions testing.
Highest margin concentration: IP Surveillance. Steepest volume decline: Analog.
End User:
Application-driven specification splits between consumer-grade convenience and hardened infrastructure compliance, with government and banking segments imposing the strictest certification requirements.
- Government:Smart city deployments mandate multi-spectral fusion and zero-trust network architecture under EU AI Act biometric restrictions. India's Safe City Mission channels public capital toward localized IR-enabled surveillance with BIS certification and domestic assembly requirements.
- Banking:Financial services operators in Singapore and the UAE deploy VCSEL-based structured light for liveness detection in zero-light access control, demanding auditable algorithm training data under France's CNIL guidelines.
- Retail:Loss-prevention departments prioritize LED array density and power efficiency over analytics integration.
- Residential:Consumer channels favor Wi-Fi-enabled bullet cameras with cloud storage subscriptions.
Deepest compliance burden: Government. Fastest volume expansion: Banking.
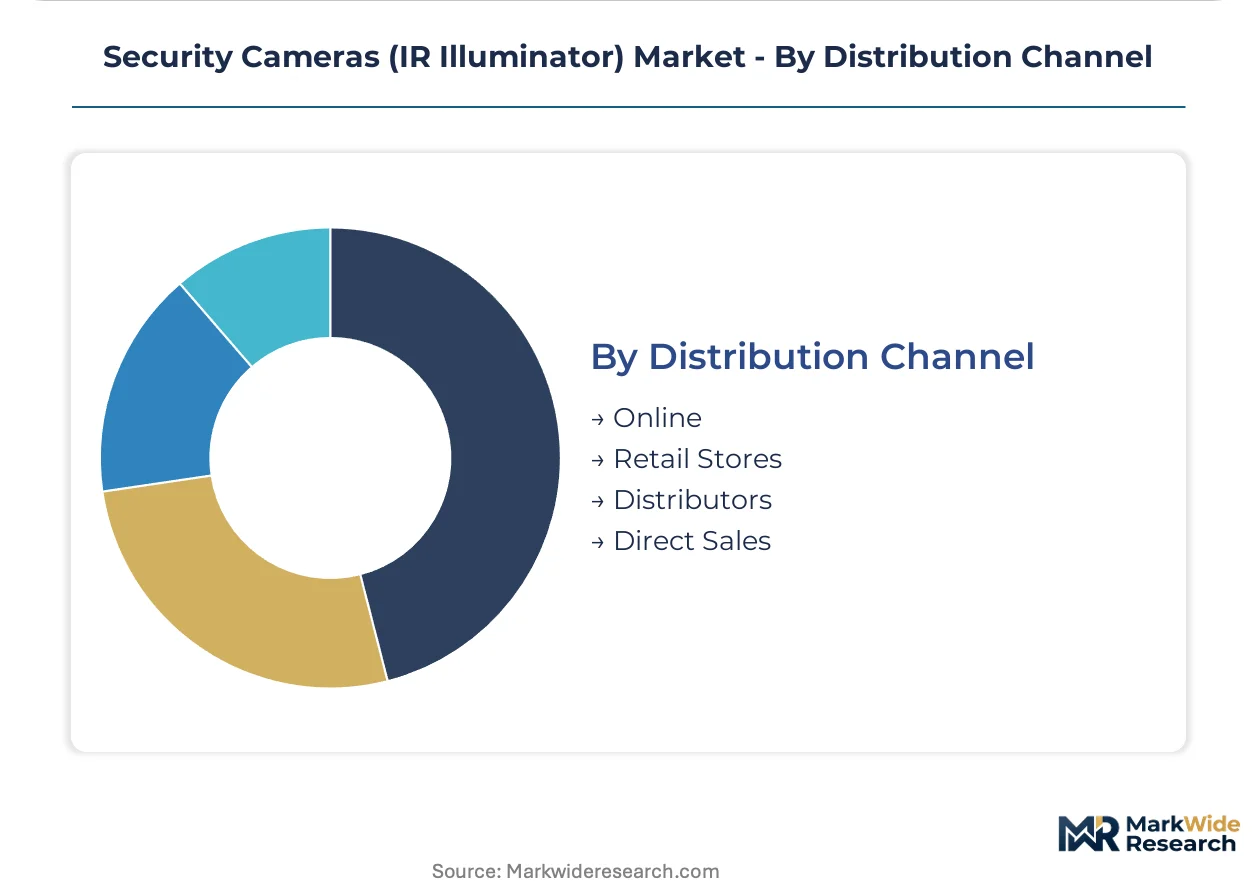
Distribution Channel:
Customer type and contract scale determine channel selection, with enterprise accounts demanding direct technical integration support unavailable through retail pathways.
- Direct Sales:Systems integrators bundle IR camera hardware with remote monitoring and predictive maintenance, transferring obsolescence risk from end-users to service providers. California and Texas property technology budgets favor this operational expenditure treatment.
- Distributors:Regional stocking points serve mid-tier installers with localized BIS certification documentation for Indian government tenders.
- Online:E-commerce platforms move consumer-grade wireless units with minimal technical support.
- Retail Stores:Big-box channels stock entry-level bullet and dome configurations for residential DIY installation.
Dominant value capture: Direct Sales. Fastest channel expansion: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors production capacity for infrared-enabled surveillance systems, while municipal procurement teams in Frankfurt, Mumbai, and Dubai drive specification divergence across compliance regimes.
United States
Logistics hubs in Texas and California are replacing legacy analog systems with IP-based PTZ configurations featuring adaptive IR illumination. FCC equipment authorization requirements for wireless-enabled systems extend product launch timelines by 6-12 months. Property technology budgets in Austin and Houston favor operational expenditure treatment through equipment-as-a-service models.
Germany
Industrial accounts in Bavaria and North Rhine-Westphalia specify IP Surveillance systems for IEC 62443 cybersecurity compliance. The EU AI Act's biometric identification restrictions accelerate demand for privacy-preserving infrared analytics without facial recognition databases. Stuttgart's automotive manufacturing corridors deploy multi-spectral fusion systems for perimeter security modernization.
India
The Safe City Mission channels public capital toward localized IR-enabled surveillance deployment across municipal governments. BIS certification mandates and the PLI scheme for electronics manufacturing raise quality barriers while incentivizing domestic production capacity. Bangalore and Hyderabad electronics clusters are scaling assembly operations for export-oriented suppliers.
Singapore
Financial services operators deploy VCSEL-based structured light arrays for liveness detection in zero-light access control environments. PDPA privacy frameworks govern ATM surveillance specifications in banking lobbies across the central business district. Data center operators in Changi and Jurong demand auditable algorithm training data provenance before contract award.
UAE
Critical infrastructure operators in Dubai and Abu Dhabi specify multi-spectral fusion capabilities alongside zero-trust network architecture for energy facility perimeter security. MOHAP regulatory frameworks intersect with financial sector procurement guidelines for biometric-capable systems. Logistics free zones are deploying PTZ configurations with real-time adaptive illumination algorithms.
Security Cameras (IR Illuminator) Market Competitive Landscape
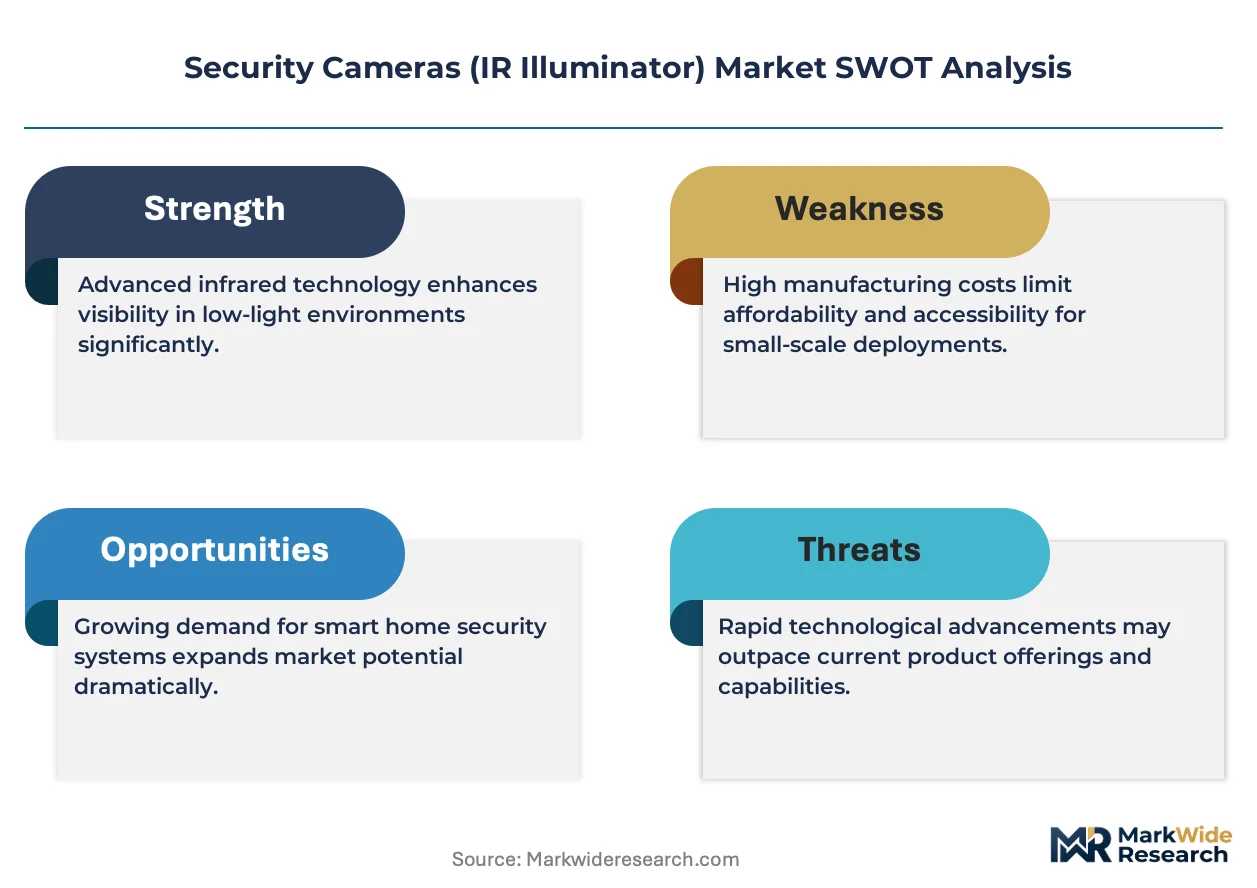
Premium-margin players sit above commodity-margin players across technology integration depth, with AI-powered analytics and multi-spectral fusion commanding pricing separation from LED array density competition alone. The vendor base organizes into three strategic archetypes: vertically integrated sensor manufacturers, open-platform architecture specialists, and deep-learning algorithm developers. Consolidation pressures concentrate most visibly around cybersecurity firmware engineering capabilities and compound semiconductor foundry access. Dominant competitive moves include backward integration into epitaxial wafer supply and geographic expansion through localized certification partnerships.
Among Chinese electronics conglomerates, Hikvision Digital Technology Co. Ltd and Dahua Technology exemplify scale-driven archetypes with captive manufacturing footprints. Axis Communications occupies a position representing open-platform specialization for third-party analytics integration. These three anchors illustrate how competitive positioning diverges across vertical integration depth versus architectural flexibility trade-offs.
| Leading Market Players |
|---|
| Hikvision Digital Technology Co. Ltd |
| Dahua Technology |
| Axis Communications |
| Bosch Security Systems |
| Honeywell International |
| Panasonic Corporation |
| Teledyne FLIR |
| Hanwha Techwin |
| Avigilon Corporation |
| Others |
Value Network & Pricing Analysis
Premium-commodity bifurcation between AI-powered analytics systems and LED-density budget units manifests in divergent margin structures and sourcing strategies. High-end configurations command value-based pricing through multi-spectral fusion capabilities while commodity tiers compete on gallium arsenide substrate costs and power efficiency metrics, with each tier feeding from distinct supplier ecosystems.
Pricing Analysis
Outcome-linked pricing for cloud-connected maintenance contracts anchors value capture in German industrial accounts and California property technology budgets. Three-tier pricing structure across premium AI-analytics, standard IP-surveillance, and economy analog levels separates vendors by certification grade and firmware update bundling. Cost compression in budget tiers intensifies as gallium arsenide epitaxial wafer prices fluctuate with substrate availability. Municipal procurement teams in India's tier-2 cities exhibit highest price sensitivity, while Singapore financial services operators prioritize liveness-detection performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced CMOS image sensor fabrication, creating exposure to export control expansion or geopolitical disruption. The supply chain draws from China's Shenzhen corridor for IR LED assembly, Japan for precision optics, and Germany for industrial-grade housing components. Gallium arsenide substrates, near-infrared epitaxial wafers, and neural processing units constitute critical input dependencies. Tariff exposure on compound semiconductor imports threatens margin stability at mid-tier manufacturers. Distribution runs through systems integrators bundling hardware with predictive maintenance services in North American enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Security Cameras (IR Illuminator) market functions as a cost-of-compliance story where the EU AI Act's biometric identification restrictions erect barrier-to-entry moats favoring vendors with auditable algorithm training data and separate European product SKUs.
For Market Incumbents:Cement market position through backward integration into compound semiconductor foundry partnerships and captive sensor manufacturing capacity. Threats from emerging cloud-native surveillance platforms demand accelerated NPU integration into camera SoCs. Certification investment for IEC 62443 industrial security standards represents the critical defensive lever against mid-tier competitors.
For New Entrants and Emerging Players:Capture white-space opportunity in Brazil's ANVISA-regulated pharmaceutical cold-chain corridors lacking compliant night-vision surveillance infrastructure. India's PLI scheme for electronics manufacturing offers the most penetrable geography through localized assembly partnerships. Equipment-as-a-service bundling with remote monitoring capabilities provides the essential go-to-market angle against capital-purchase incumbents.
For Investors and Strategic Acquirers:Re-rating potential sits with cybersecurity firmware engineering specialists given escalating CE marking IoT transition requirements and IEC 62443 implementation mandates. Long-term viability across the next decade hinges on compound semiconductor foundry access and multi-spectral fusion R&D pipelines. The signal to watch is consolidation activity around embedded systems specialists capable of industrial security standard deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Spectral Fusion Platform Launch | Combines thermal cores with active IR illumination for all-weather perimeter detection at energy facilities. |
| Compound Semiconductor Foundry Partnership | Secures captive supply of VCSEL arrays for precision biometric applications in UAE financial services. |
| Cloud-Connected Maintenance Contract Expansion | Displaces hardware-only procurement through subscription firmware updates in German industrial accounts. |
| Localized Certification Partnership Formation | Accelerates BIS compliance and PLI scheme access for Indian government tender participation. |
| Privacy-Preserving Analytics Development | Enables EU AI Act compliance without facial recognition databases for European municipal procurement. |
Research Methodology
Multi-period observation of municipal procurement specifications, foundry capacity announcements, and firmware update release cycles anchored the trend analysis, supplemented by interviews with security systems integrators, municipal procurement officers, compound semiconductor foundry managers, and industrial cybersecurity consultants. Secondary validation drew from FCC equipment authorization databases, EU AI Act implementation guidance, BIS certification registries, and customs records for gallium arsenide substrate trade flows. Bottom-up vendor revenue triangulation against top-down addressable market sizing ensured cross-check integrity.
Input-output matrix modeling connected CMOS sensor supply constraints, LED array cost structures, and subscription revenue recognition patterns across product type, technology architecture, end-user vertical, and distribution channel dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated smart city infrastructure investment pipelines, PLI scheme disbursement schedules, and cybersecurity compliance deadline clustering.
The model holds under stable geopolitical conditions for Taiwan-South Korea sensor supply and sustained EU AI Act enforcement timelines; deviation in export control expansion or biometric regulation relaxation would shift vendor competitive positioning materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
Rugged Thermal Cameras Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Video Surveillance and Vsaas Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
Japan Surveillance IP Cameras Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Video Surveillance Market