
 Night Vision Camera Market | 2026-2036
Night Vision Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision Camera Market Analysis
Defense leasing and equipment-as-a-service models is fragmenting capital requirements across the night vision camera supply chain. L3Harris Technologies leverages long-term service contracts with federal agencies to sustain recurring revenue streams. Teledyne FLIR anchors its position through in-house sensor fabrication and vertical control over thermal core production. BAE Systems competes on classified program access and sovereign security clearances in the UK and US markets.
A night vision camera captures electromagnetic radiation in near-infrared or thermal spectra, amplifying ambient photons through image intensifier tubes or detecting heat signatures via microbolometer arrays, typically operating at wavelengths from 700 nanometers to 14 micrometers for navigation and threat detection in zero-illumination environments. Thermal imaging systems command premium pricing in military surveillance due to all-weather detection capabilities and resistance to visual camouflage. Image intensification technology occupies the largest installed base across law enforcement agencies, while digital night vision represents the fastest-expanding category as CMOS sensor costs decline and software-defined image processing improves.
The US National Defense Authorization Act and ITAR export controls shape procurement eligibility and foreign market access for American manufacturers. EMA equipment standards and CE marking requirements govern commercial security deployments across European member states. Stakeholders must monitor evolving classification thresholds for thermal sensor exports and alignment between military specification cycles and commercial product development timelines.
Market Dynamics
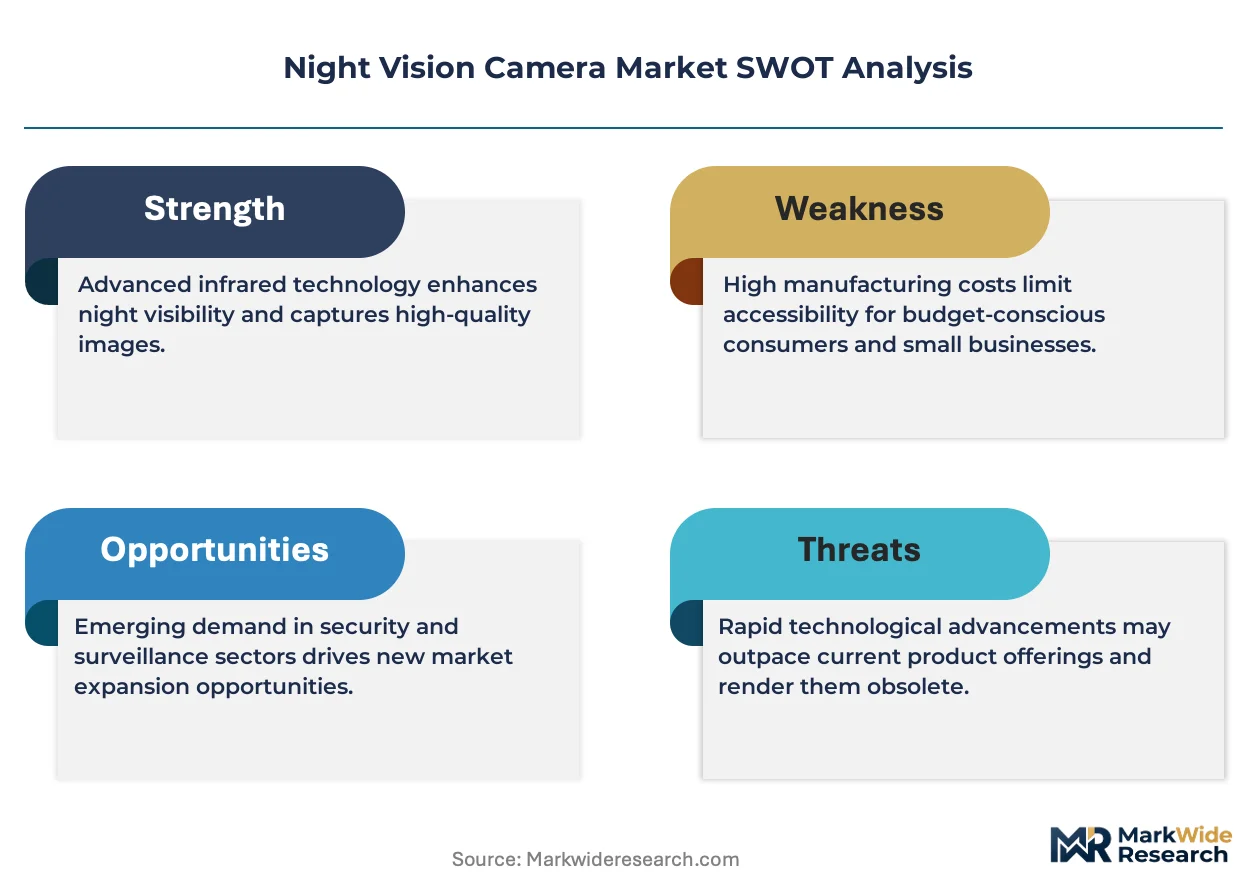
Defense procurement cycles are compressing as NATO allies accelerate thermal imaging modernization, while CMOS sensor cost curves enable law enforcement agencies to migrate from legacy image intensification tubes to digital architectures.
Growth Catalysts
- ITAR-compliant domestic sourcing mandates:The US National Defense Authorization Act requires federal agencies to prioritize domestic thermal core suppliers, creating captive demand channels for American manufacturers with security clearances.
- Microbolometer array cost reduction:Wafer-level packaging advances are collapsing thermal sensor production costs, enabling state police departments to equip patrol vehicles with previously cost-prohibitive thermal optics.
- Border security infrastructure buildouts:US Customs and Border Protection fixed-site surveillance programs sustain volume demand for long-range cooled thermal cameras across southwest and northern frontier installations.
Market Restraints
- Germanium lens supply concentration:Optical-grade germanium refining capacity clusters in China and Russia, exposing Western manufacturers to export restriction risks and price volatility for thermal objective assemblies.
- ITAR classification thresholds:US State Department export controls on thermal sensor resolution specifications block American suppliers from accessing commercial security markets in non-allied nations.
- Digital night vision lag performance:CMOS-based systems exhibit motion blur and latency gaps versus image intensifier tubes, limiting adoption for helicopter pilotage and close-quarters combat applications.
Strategic Opportunities
- India paramilitary modernization:The Central Reserve Police Force and Border Security Force are tendering for vehicle-mounted thermal imagers under the Make in India localization framework.
- Autonomous vehicle night perception:Fusion of thermal cameras with LiDAR and radar is emerging as a redundancy layer for Level 4 self-driving trucks operating in unlit rural corridors.
- Wildfire detection networks:California Department of Forestry and Fire Protection is deploying AI-enhanced thermal camera arrays for automated ignition spotting across high-risk watershed zones.
Industry Challenges
- ITAR-cleared engineering talent scarcity:Security clearance processing backlogs constrain American suppliers' ability to staff classified program teams.
- Dual-use export classification ambiguity:Thermal core manufacturers face inconsistent jurisdictional rulings between Commerce Department EAR and State Department ITAR regimes.
- Legacy system integration complexity:NATO member militaries require backward compatibility protocols for new thermal weapon sights with 1990s-era helmet mount standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision Camera Market |
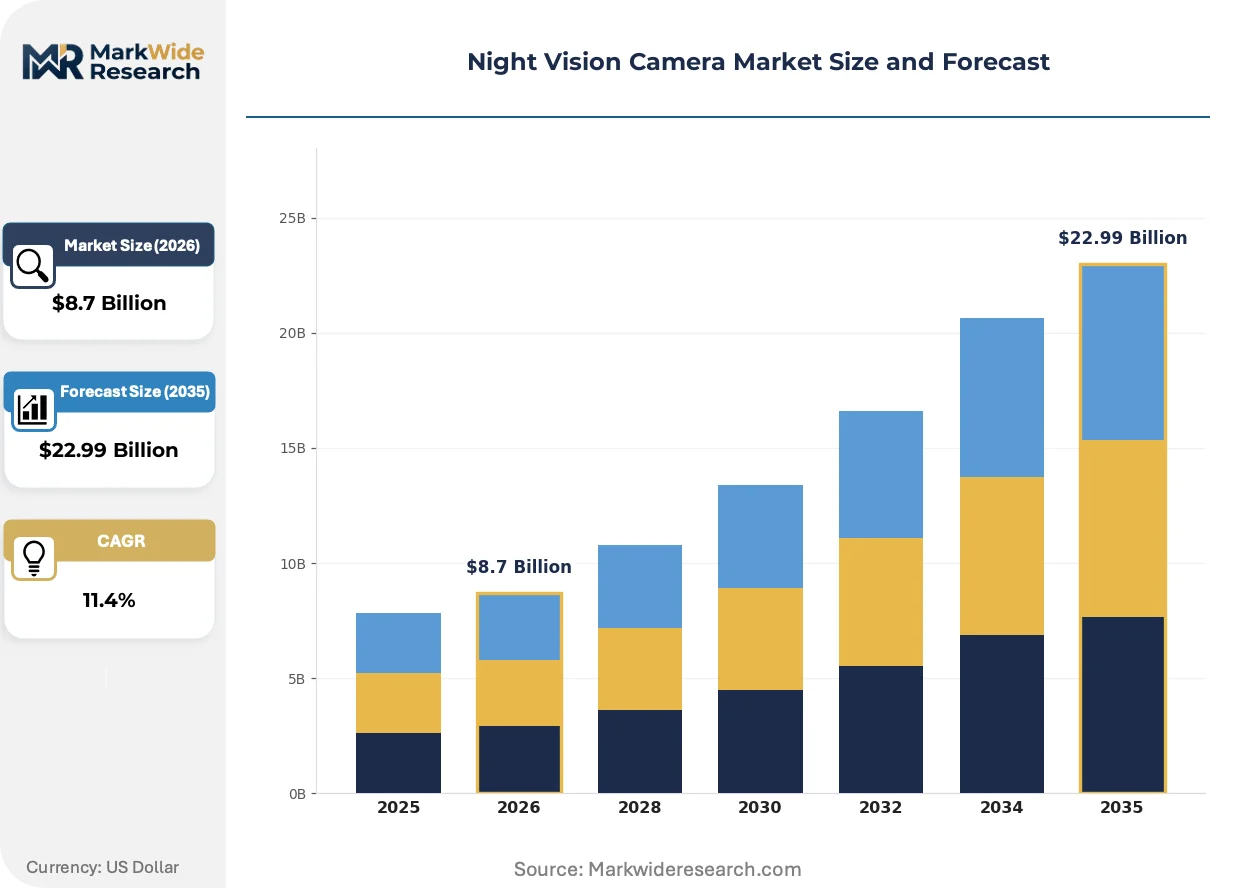
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocular, Binocular, Goggles, Camera Technology: Thermal Imaging, Image Intensification, Digital Night Vision, Low-Light End User: Military, Wildlife Observation, Security, Automotive Application: Surveillance, Search and Rescue, Hunting, Law Enforcement |
| Companies Covered | L3Harris Technologies, Teledyne FLIR, BAE Systems, Thales Group, Elbit Systems, Hikvision, Dahua Technology, Axis Communications, Bosch Sicherheitssysteme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision Camera Market Emerging Trajectories
Sensor fusion architectures and software-defined imaging are collapsing the traditional hardware segmentation between thermal and intensified night vision, enabling modular platforms that reconfigure via firmware updates.
Uncooled microbolometer arrays with 12-micron pixel pitch are digitizing thermal imaging performance previously requiring cryogenic cooling, enabling infantry squads to field pocket-sized weapon sights at under one kilogram. Marine expeditionary units are adopting these platforms for urban assault operations where battery weight constraints previously excluded thermal options. The technology is digitizing the boundary between dismounted soldier and vehicle-mounted surveillance tiers.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated threat detection in border surveillance deployments, forcing thermal camera OEMs to document training data provenance for machine-learning-enabled analytics. French and German integrators must now submit conformity assessments for AI-enhanced perimeter security systems. High-resolution thermal analytics for critical infrastructure protection face the steepest compliance timelines.
Law enforcement agencies are unbundling hardware acquisition from maintenance contracts, purchasing digital night vision devices through municipal leasing vehicles rather than federal grant programs. State procurement offices in Texas and Florida are negotiating five-year refresh cycles with technology replacement guarantees. This restructuring is most visible in sheriff's departments migrating from federal surplus equipment to commercially financed digital optics programs.
Night Vision Camera Market Segmentation
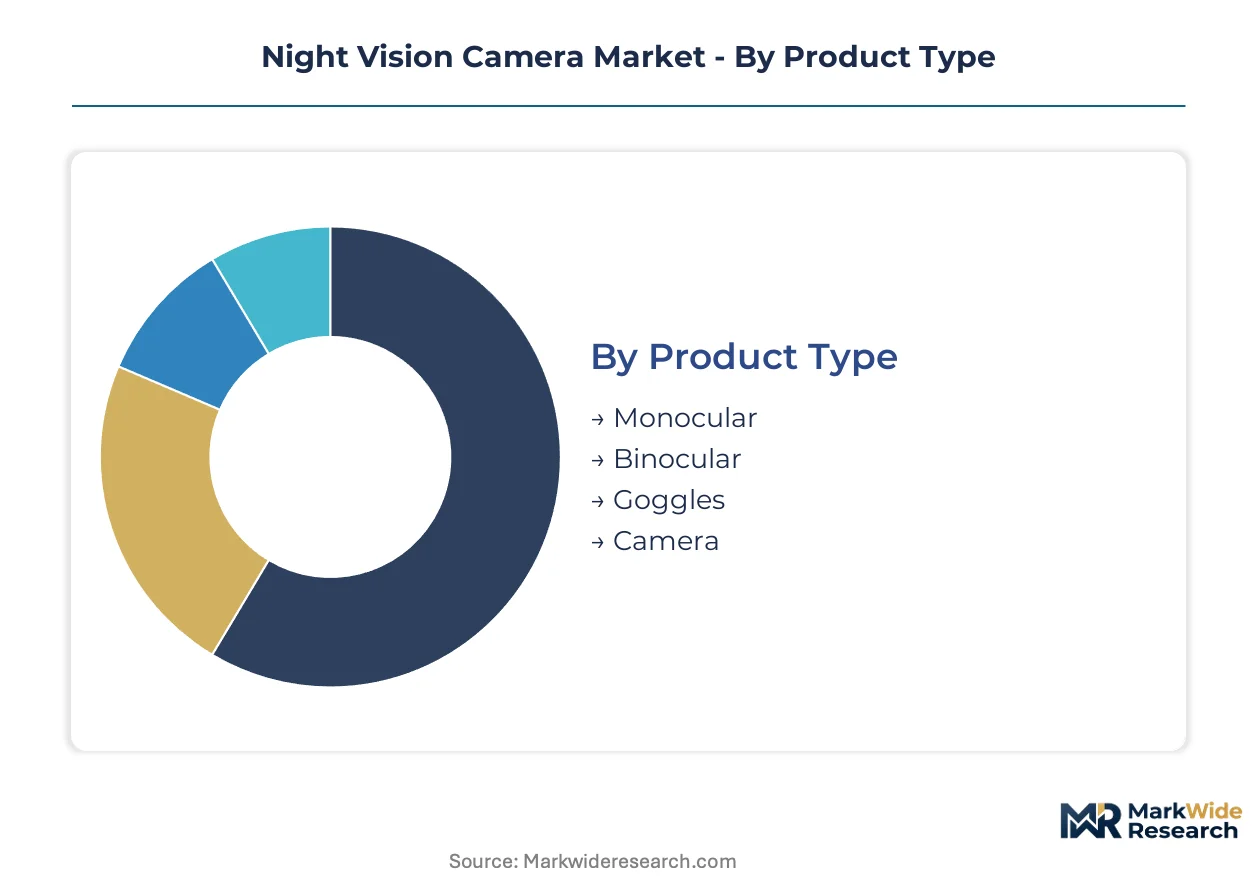
Night vision camera procurement cycles vary dramatically across form factors and sensing technologies. Military programs refresh thermal weapon sights on decade-long timelines while law enforcement agencies cycle through digital monoculars every three to five years.
Product Type:
Monocular configurations turn over fastest among tactical users seeking helmet-mounted versatility, while fixed-site camera installations persist for fifteen years or longer.
- Monocular:Single-tube designs dominate infantry helmet mounts and vehicle dashboards where weight minimization matters. US Customs and Border Protection equips field agents with monocular thermal units for roving patrol duties. Demand concentrates in federal law enforcement agencies refreshing legacy image intensification devices.
- Binocular:Dual-tube architectures deliver depth perception for long-range observation posts and maritime surveillance towers. German border security installations specify binocular thermal systems for Baltic Sea coastline monitoring. Procurement runs through multi-year framework agreements with system integrators.
- Goggles:Bi-ocular and biocular formats serve pilots and drivers requiring hands-free operation in cockpit environments.
- Camera:Fixed-mount thermal cameras anchor perimeter security networks and critical infrastructure protection systems.
Camera installations anchor the volume base while monocular configurations gain share at the steepest rate.
Technology:
Cost tiers separate cryogenically cooled thermal cores from uncooled microbolometer arrays, with digital CMOS sensors collapsing the entry price point for commercial security buyers.
- Thermal Imaging:Microbolometer arrays detect long-wave infrared radiation independent of ambient illumination, enabling all-weather threat detection through smoke and fog. US National Defense Authorization Act procurement mandates sustain demand for ITAR-compliant domestic thermal core production. Military surveillance programs specify cooled InSb sensors for extended-range identification.
- Image Intensification:Vacuum tube technology amplifies near-infrared photons through multi-channel plates, delivering sub-millisecond latency for pilotage applications. NATO helicopter fleets in Poland and Romania maintain fleet-wide inventories of Gen III intensifier tubes. Procurement cycles extend to tube life limits of roughly 4,000 operational hours.
- Digital Night Vision:CMOS sensor architectures with software-defined gain control enable recording and wireless transmission capabilities. State police departments in Texas and Florida finance digital devices through municipal leasing vehicles rather than federal grant programs.
- Low-Light:Silicon-based sensors exploit marginal ambient illumination without active amplification, serving automotive backup camera and drone navigation markets.
Image intensification anchors the volume base while digital night vision climbs the fastest.
End User:
Customer type determines specification rigor and certification requirements, with military buyers demanding MIL-STD-810G environmental testing that commercial wildlife observers rarely require.
- Military:Dismounted soldier programs and vehicle platform integrations drive thermal weapon sight and driver vision enhancer demand. US Army PEO Soldier manages procurement through indefinite-delivery contracts with security-cleared suppliers. NATO allies in Poland and Norway accelerate thermal modernization under collective defense spending commitments.
- Security:Private critical infrastructure operators and municipal police departments purchase perimeter surveillance and patrol optics. California Department of Forestry and Fire Protection deploys AI-enhanced thermal arrays for automated wildfire ignition detection.
- Wildlife Observation:Ecological researchers and hunting enthusiasts seek compact handheld units for nocturnal species monitoring.
- Automotive:Tier 1 suppliers integrate thermal cameras as redundancy layers for autonomous vehicle perception stacks operating in unlit rural corridors.
Security applications anchor the volume base while automotive integration expands most quickly.
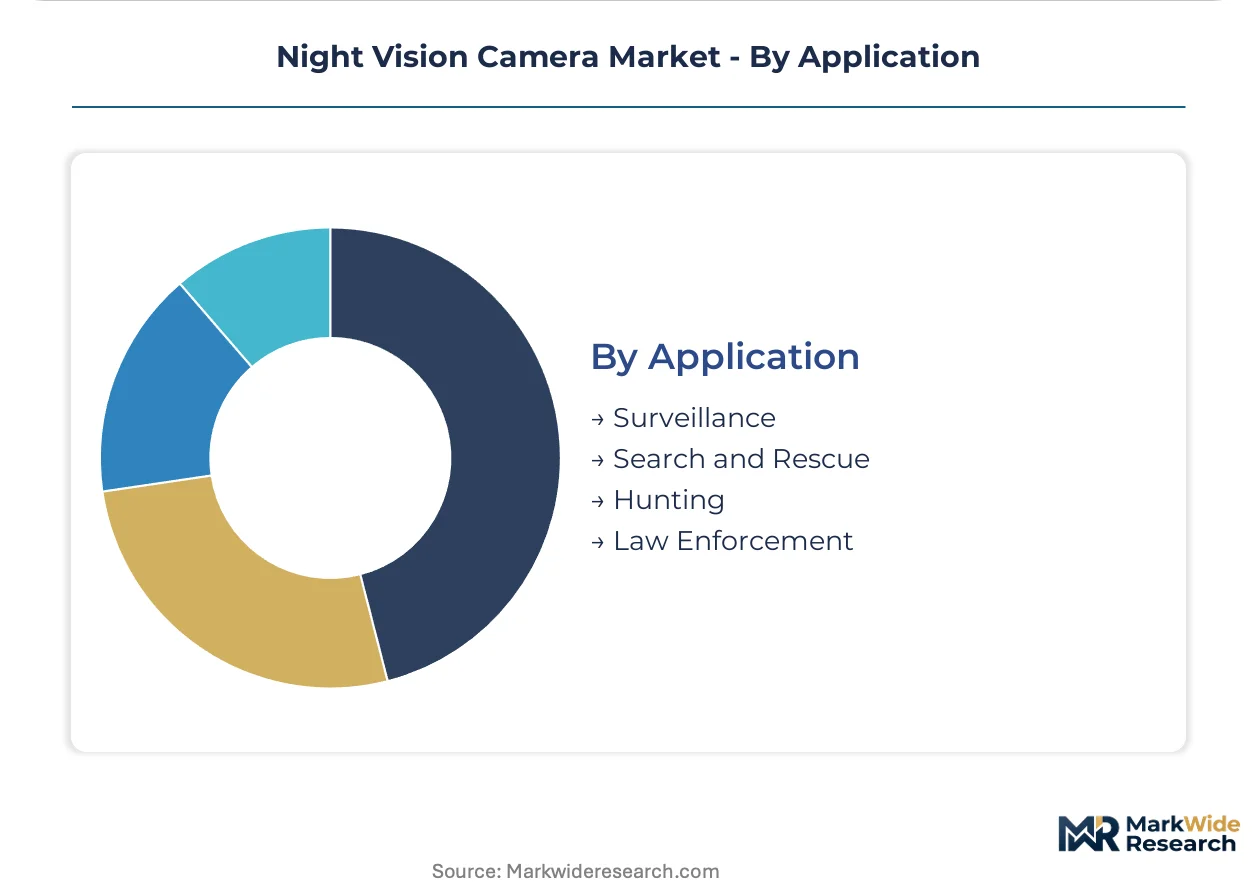
Application:
Volume concentration differs between stationary surveillance infrastructure and mobile tactical operations, with search and rescue procurement spiking episodically around disaster response funding cycles.
- Surveillance:Fixed-site thermal cameras with continuous pan-tilt-zoom operation protect borders, airports, and power generation facilities. US Customs and Border Protection sustains volume demand for long-range cooled thermal installations across southwest frontier sectors. AI-enabled analytics now automate threat detection in these deployments.
- Law Enforcement:Patrol officers and tactical teams deploy helmet-mounted and weapon-mounted night vision for warrant service and barricade situations. Sheriff's departments in Florida negotiate five-year refresh cycles with technology replacement guarantees.
- Search and Rescue:Mountain rescue services and urban disaster response teams employ thermal drones and handheld units for victim location.
- Hunting:Sportsmen utilize digital and thermal optics for feral hog population control and predator management on private land.
Surveillance anchors the volume base while law enforcement shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for thermal imaging cores tilt heavily toward surplus in the United States and deficit positions across NATO allies dependent on ITAR-cleared supply chains. Procurement mandates embedded in national defense authorization acts reshape cross-border equipment flows.
United States
The National Defense Authorization Act sustains thermal core demand through domestic sourcing mandates for federal agencies. ITAR export controls administered by the State Department block non-allied market access for American suppliers. Arizona and Texas host concentrated manufacturing clusters where security-cleared facilities produce microbolometer arrays for military programs.
Germany
Bundeswehr modernization drives cooled InSb sensor procurement for long-range surveillance applications. CE marking requirements and EU AI Act conformity assessments govern commercial security deployments. Bavaria anchors industrial activity through precision optics clusters supplying thermal objective assemblies.
France
Border security infrastructure along Mediterranean and Atlantic coastlines sustains volume demand for fixed-site thermal cameras. ANSM and CNIL oversight extends to algorithmic transparency for AI-enhanced threat detection systems. The Provence-Alpes-Côte d'Azur region concentrates system integrators serving critical infrastructure protection.
United Kingdom
Ministry of Defence helicopter fleet upgrades maintain demand for Gen III image intensifier tubes. Sovereign security clearance requirements favor domestic suppliers for classified programs. Greater Manchester and Bristol host specialized engineering clusters supporting thermal weapon sight development.
India
Central Reserve Police Force and Border Security Force tenders for vehicle-mounted thermal imagers operate under Make in India localization frameworks. BIS certification requirements shape equipment standards for paramilitary procurement. Gujarat and Maharashtra industrial corridors attract joint ventures for domestic thermal core assembly.
Night Vision Camera Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling sensor fabrication and optical subassembly supply. The vendor base separates into three functional layers: defense prime contractors managing classified program access, commercial security OEMs scaling through municipal procurement channels, and component fabricators capturing value through wafer-level packaging advances. Consolidation pressure runs highest where ITAR compliance creates captive demand channels. Dominant competitive moves include backward integration into thermal core production and long-term service contract structures that convert capital sales into recurring revenue.
Among defense-focused primes, L3Harris Technologies and Teledyne FLIR exemplify divergent strategic positions—one anchored in federal service relationships, the other in captive sensor manufacturing. BAE Systems occupies a position shaped by transatlantic security clearances. Within the commercial security tier, Hikvision and Dahua Technology represent scale-driven manufacturers serving municipal and private infrastructure markets outside ITAR jurisdiction.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Teledyne FLIR |
| BAE Systems |
| Thales Group |
| Elbit Systems |
| Hikvision |
| Dahua Technology |
| Axis Communications |
| Bosch Sicherheitssysteme |
| Others |
Supply Flow & Price Mechanics
Germanium lens supply concentration in China and Russia determines both the premium-to-economy pricing spread across thermal camera tiers and the geographic shape of Western supply chains. ITAR-compliant domestic sourcing mandates for US federal agencies create a bifurcated procurement landscape where security-cleared suppliers command pricing power while commercial buyers face cost volatility from optical-grade germanium import exposure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the night vision camera market. Price differentiation rests on ITAR certification tier and thermal sensor resolution grade, with cooled InSb sensors for military surveillance commanding substantial premiums over uncooled microbolometer arrays for commercial security. Cost compression in the law enforcement digital night vision tier is intensifying because CMOS sensor wafer costs are declining and municipal leasing vehicles are unbundling hardware from service contracts. State police departments exhibit the highest price sensitivity as they migrate from federal grant funding to commercial financing, while classified military programs demonstrate the least sensitivity due to sole-source procurement mandates.
Supply Chain Analysis
Tariff exposure between China and Western defense markets dominates supply chain risk calculus for thermal objective assemblies. Microbolometer array fabrication concentrates in the United States, China, and Taiwan, while optical-grade germanium refining draws from China and Russia. The supply chain hinges on single-source vulnerability for cryogenically cooled sensor components and germanium lens substrates. Distribution runs through defense prime contractors with security clearances for military segments, and through municipal procurement offices and system integrators for commercial security deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The night vision camera market operates as a regulatory entrenchment story where ITAR security clearances and federal procurement mandates create durable competitive moats that resist price-based disruption.
For Market Incumbents: Entrench position through backward integration into thermal core fabrication and long-term service contract structures that convert capital sales into recurring revenue streams. The threat of CMOS-based digital night vision displacement in law enforcement segments demands accelerated R&D investment in software-defined imaging platforms. Capacity addition in Arizona and Texas manufacturing clusters reinforces domestic sourcing compliance for National Defense Authorization Act procurement mandates. For New Entrants and Emerging Players: India's paramilitary modernization under Make in India localization frameworks represents the most penetrable geographic white space for vehicle-mounted thermal imager tenders. The Central Reserve Police Force and Border Security Force procurement channels favor joint venture structures with domestic assembly partners over direct export models. A go-to-market angle anchored in BIS certification compliance and local manufacturing partnerships bypasses ITAR jurisdiction barriers that block American suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component specialists with captive sensor fabrication capabilities and security-cleared engineering teams. Long-term viability over the next decade rests on alignment between military specification cycles and commercial product development timelines. The signal to monitor is ITAR classification threshold adjustments for thermal sensor exports, which would recalibrate addressable market boundaries for American manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Core Production | Captive microbolometer array fabrication insulates margins from germanium lens supply volatility and ITAR chokepoints. |
| Long-Term Service Contract Structuring | Federal agency leasing vehicles convert one-time hardware sales into recurring revenue streams with L3Harris Technologies as exemplar. |
| Make in India Joint Venture Formation | Domestic assembly partnerships satisfy BIS certification requirements for Central Reserve Police Force thermal imager tenders. |
| Software-Defined Imaging Platform Development | Firmware-upgradable architectures collapse hardware segmentation between thermal and intensified night vision categories. |
| AI-Enhanced Analytics Compliance Investment | EU AI Act conformity documentation for automated threat detection systems opens French and German border security procurement channels. |
Methodological Framework
Cross-validation between defense procurement databases and commercial security installation records anchors the qualitative findings in this study. Primary interviews with thermal core engineering directors, federal procurement officers at US Customs and Border Protection, municipal police technology managers, and system integrators serving critical infrastructure protection were combined with secondary validation from SEC 10-K filings, Defense Logistics Agency contract announcements, and EU tender documentation. Bottom-up triangulation across product type, technology tier, and end-user segment was reconciled with top-down macroeconomic drivers including defense modernization budgets and homeland security infrastructure allocations.
Calibration against historical procurement cycle patterns and announced program timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, sensing technology, end-user category, and application type, with additional granularity on ITAR compliance status and certification tier. CAGRs were derived from installed base refresh rates, program award velocities, and technology substitution curves. Forecast inputs incorporated microbolometer cost reduction trajectories, CMOS sensor performance improvements, and regulatory classification threshold evolution.
Practitioners should monitor ITAR export control revisions, germanium supply restriction announcements, and AI Act enforcement precedents for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
AI CCTV Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Global CCTV Market