
 Global Blockchain in Insurance Market | 2026-2036
Global Blockchain in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blockchain in Insurance Market Foresight
The EU Green Deal is expanding compliance obligations for European insurers, forcing upgrades to transparent and auditable data infrastructure. IBM Corporation leverages its Hyperledger expertise to anchor enterprise-grade deployments for multinational carriers. Consensys specializes in Ethereum-based smart contract architectures that automate policy execution. Guardtime dominates Baltic and Nordic markets with its quantum-resistant blockchain stack for marine and cargo insurance.
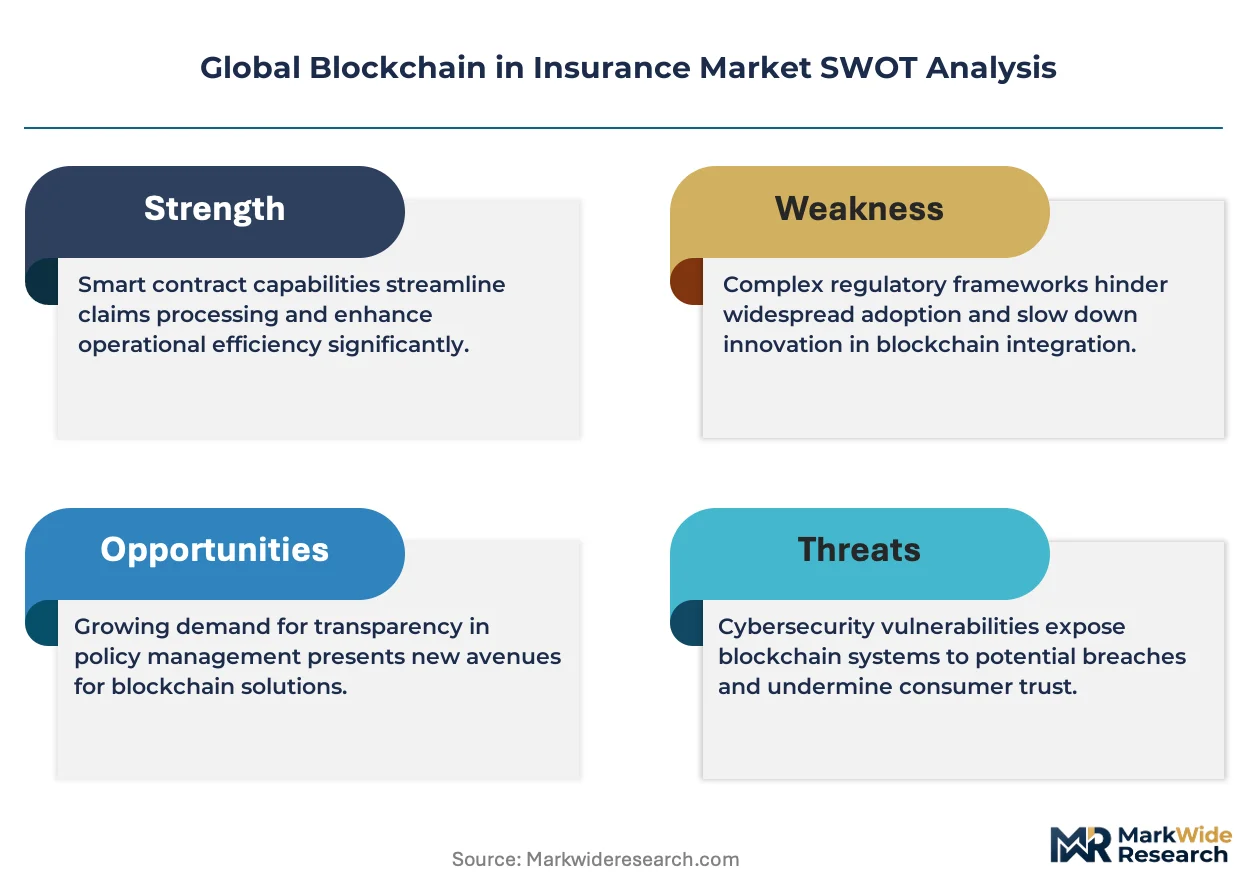
Blockchain in insurance denotes distributed ledger systems that cryptographically record policy data, premium flows, and claims events across permissioned or permissionless node networks, typically achieving settlement finality in minutes rather than weeks. These platforms eliminate reconciliation overhead between carriers, reinsurers, and brokers while creating immutable audit trails for regulatory examinations. Private blockchain solutions currently lead deployment volume among incumbent carriers prioritizing data sovereignty and counterparty confidentiality. Smart contracts within the solution layer represent the fastest-expanding segment, as programmable logic enables parametric payouts triggered by verified external data feeds. Fraud detection maintains mature adoption in health and auto lines, though margin pools are shifting toward customer identity verification as know-your-customer mandates tighten.
The National Association of Insurance Commissioners in the United States, the UK's Financial Conduct Authority, and Germany's BaFin are each developing sandbox frameworks that permit live blockchain pilots under modified licensing conditions, accelerating proof-of-concept migration to production scale. The EU's AI Act and existing GDPR requirements impose strict boundaries on automated decision-making in underwriting, shaping how carriers architect permissioned networks with embedded human override protocols. Stakeholders must monitor which regulatory jurisdiction first mandates blockchain-native reporting standards, as that precedent will cascade into contract terms across cross-border reinsurance treaties.
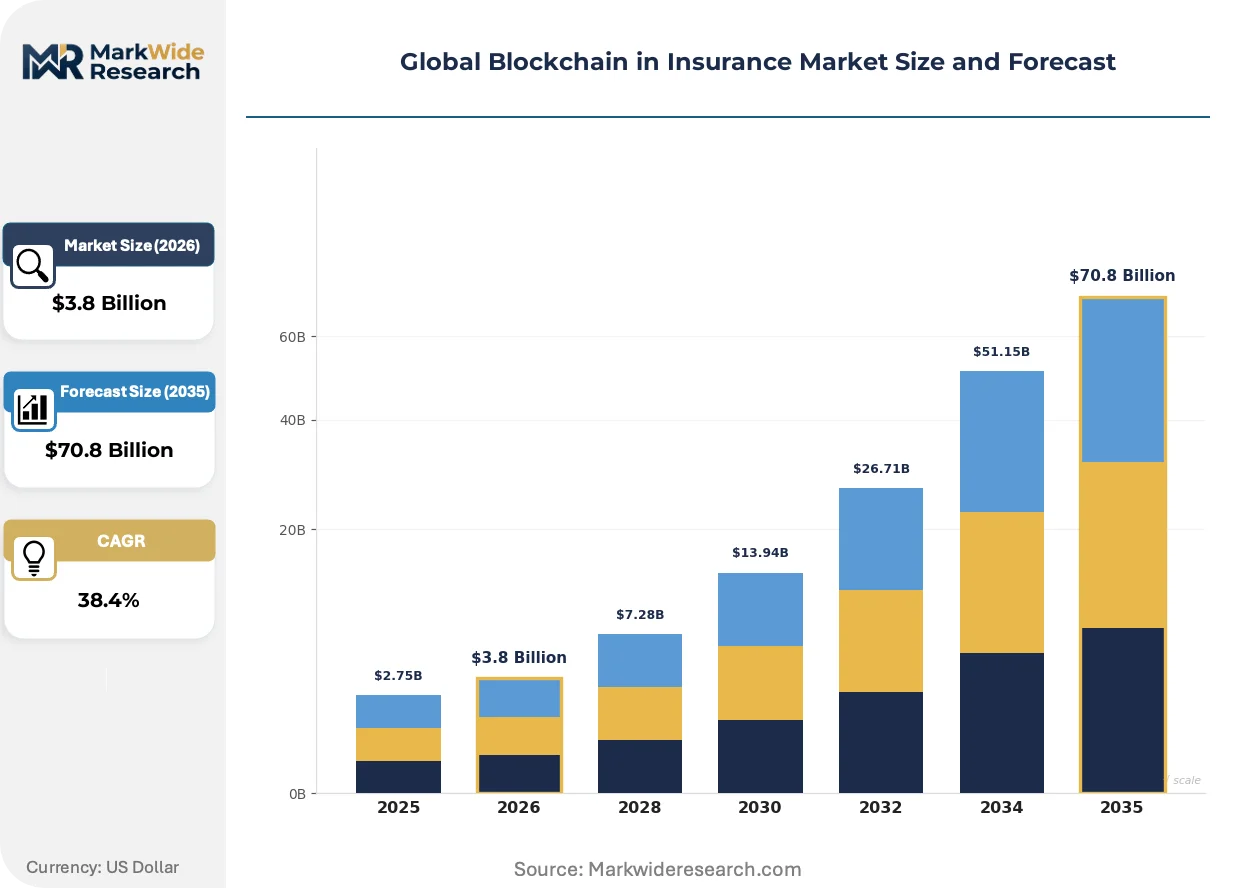
Market Dynamics
Property and casualty carriers are deploying distributed ledger platforms to compress claims settlement cycles from weeks to minutes, while the EU's Digital Operational Resilience Act pressures insurers to abandon legacy reconciliation systems. This structural shift toward cryptographic audit trails is redistributing value from intermediary brokers to automated smart contract architectures.
Growth Catalysts
- EU Digital Operational Resilience Act:European insurers must upgrade infrastructure to meet mandatory operational resilience testing, accelerating permissioned blockchain procurement for policy data immutability.
- Parametric insurance automation:Smart contracts triggered by verified external data feeds eliminate manual claims assessment in crop and catastrophe lines.
- United States state regulatory pilots:State insurance commissioners in multiple jurisdictions are approving blockchain-native rate filings, reducing compliance friction for early adopters.
Market Restraints
- Interoperability gaps:Proprietary ledger architectures from competing vendors prevent seamless data exchange between carriers and reinsurers.
- Quantum computing threat:Current cryptographic standards face obsolescence risk, forcing insurers to budget for post-quantum migration before maturity curves justify investment.
- GDPR compliance friction:The EU's right-to-erasure mandate conflicts with blockchain immutability, requiring expensive architectural workarounds for European deployments.
Strategic Opportunities
- India's uninsured agrarian base:Crop insurers can leapfrog legacy infrastructure by deploying mobile-first parametric policies on permissioned ledgers for smallholder farmers.
- Marine cargo documentation:Bills of lading tokenization on distributed networks eliminates paper-based verification delays at Singapore and Rotterdam ports.
- Know-your-customer convergence:Insurers can monetize verified identity credentials across banking and healthcare verticals by integrating self-sovereign identity standards.
Industry Challenges
- Distributed systems engineering talent:Carriers compete with fintech and cryptocurrency sectors for scarce smart contract developers and cryptographic security specialists.
- Legacy core system integration:Policy administration platforms built on 1980s mainframe architectures require expensive middleware layers to connect with blockchain nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blockchain in Insurance Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $70.8 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Solution/Offering: Fraud Detection, Claims Management, Risk Assessment, Customer Identity Verification, Smart Contracts Application: Underwriting, Policy Administration, Reinsurance, Peer-to-Peer Insurance, Regulatory Compliance End User: Insurance Carriers, Brokers, Third-party Administrators, Actuarial Firms, Legal Advisors |
| Companies Covered | IBM Corporation, Consensys, Etherisc, Guardtime, ChainThat, IntellectEU, Accenture, Microsoft Corporation, Allianz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blockchain in Insurance Market Shifts & Advancements
Programmable insurance logic is displacing manual underwriting workflows across commercial lines, while regulatory sandboxes in multiple jurisdictions accelerate production migration from proof-of-concept stages. These shifts are compressing the traditional value chain and redefining carrier-reinsurer data relationships.
Zero-knowledge proof architectures are expanding into health insurance claims processing, enabling carriers to verify policyholder eligibility without exposing sensitive medical records. Large group health underwriters in the United States are piloting these systems to satisfy HIPAA constraints while streamlining pre-authorization workflows. The structural consequence is that selective disclosure is expanding into a competitive differentiator for privacy-sensitive segments.
The EU AI Act imposes strict human oversight requirements on automated underwriting decisions, forcing carriers to architect permissioned networks with embedded override protocols. German and French regulators are interpreting these provisions most stringently, requiring documented intervention points in smart contract execution flows. Commercial auto and cyber liability lines face the steepest compliance redesign as algorithmic pricing models come under heightened scrutiny.
Corporate risk managers are consolidating vendor relationships around carriers offering API-accessible policy data and real-time claims status visibility. This procurement compression favors insurers with mature distributed ledger infrastructure over those relying on broker-mediated reporting. The shift is most visible in London's commercial specialty market, where large industrial buyers now mandate direct system-to-system integration for property and casualty programs.
Global Blockchain in Insurance Market Segmentation
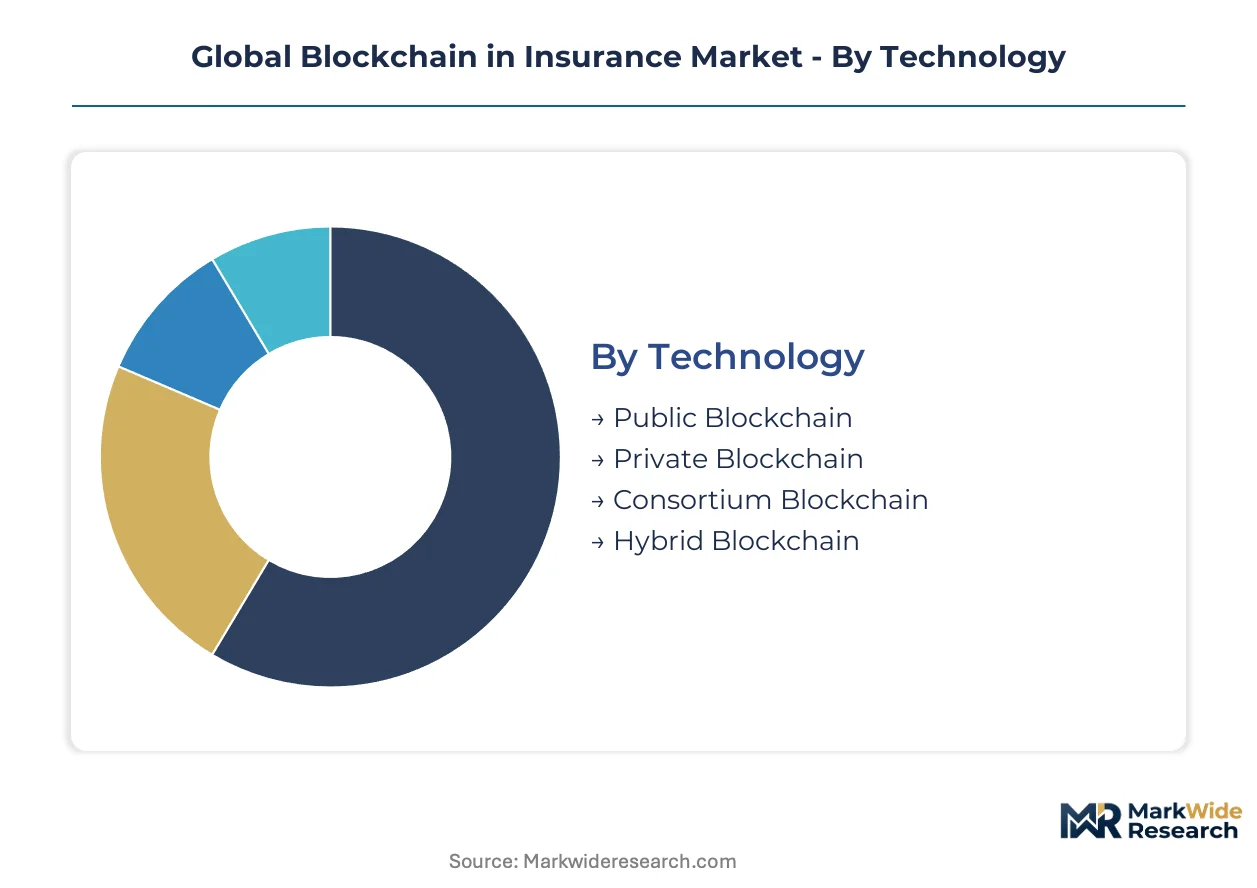
Blockchain deployment patterns diverge sharply across technical architectures and functional use cases. Carrier procurement decisions hinge on regulatory jurisdiction, counterparty confidentiality requirements, and legacy system integration complexity.
Technology:
Carrier risk appetite and data sovereignty mandates determine ledger architecture selection.
- Private Blockchain:Permissioned node networks restrict transaction visibility to vetted participants. Property and casualty carriers in Germany and France prioritize these deployments to satisfy BaFin and CNIL data localization requirements while maintaining counterparty confidentiality.
- Public Blockchain:Permissionless networks offer settlement finality without intermediary validation. Peer-to-peer insurers in Singapore and Estonia leverage Ethereum-based architectures for parametric crop policies where transparency outweighs privacy concerns.
- Consortium Blockchain:Federated governance models distribute infrastructure costs across carrier coalitions. Marine insurance consortia at Rotterdam and Singapore ports deploy these architectures for shared cargo documentation.
- Hybrid Blockchain:Dual-layer designs isolate sensitive underwriting data on private ledgers while anchoring proof-of-existence to public chains. Japanese carriers use these configurations to satisfy METI interoperability standards.
Volume sits with Private Blockchain; growth tilts toward Hybrid Blockchain.
Solution/Offering:
Procurement priorities reflect where carriers can extract immediate operational savings versus long-term strategic positioning.
- Smart Contracts:Programmable policy logic automates execution when verified data feeds confirm trigger conditions. Crop insurers in India deploy these for drought-indexed payouts to smallholder farmers, eliminating manual claims assessment.
- Claims Management:Distributed ledgers compress settlement cycles through cryptographic verification of loss events. US auto carriers integrate these platforms with telematics providers to accelerate collision liability resolution.
- Fraud Detection:Immutable transaction histories enable pattern recognition across policy lifecycles. Health insurers in the United Kingdom apply these tools to identify provider billing anomalies.
- Customer Identity Verification:Self-sovereign identity standards streamline know-your-customer workflows. European carriers under GDPR and EU AI Act mandates invest here to reduce compliance overhead.
- Risk Assessment:Decentralized data aggregation improves pricing accuracy for catastrophe models. Reinsurers in Bermuda leverage these solutions for hurricane exposure calibration.
Investment concentrates on Claims Management; expansion accelerates fastest in Customer Identity Verification.
Application:
Functional deployment varies by line of business complexity and regulatory touchpoints.
- Reinsurance:Distributed ledgers eliminate reconciliation delays between cedents and retrocessionnaires. London market carriers automate treaty administration through shared catastrophe loss databases.
- Regulatory Compliance:Immutable audit trails satisfy jurisdictional reporting mandates. US carriers facing NAIC modernization requirements pilot these for rate filing documentation.
- Underwriting:Algorithmic risk selection integrates external data feeds through oracle networks. Cyber insurers price policies using decentralized threat intelligence.
- Policy Administration:Smart contracts manage endorsement versioning and premium collection. German life insurers deploy these for unit-linked product servicing.
- Peer-to-Peer Insurance:Decentralized autonomous organizations pool member capital without traditional carrier intermediation. Platforms in Switzerland and the Netherlands target gig economy workers.
Adoption depth favors Reinsurance; regulatory pressure drives fastest uptake in Regulatory Compliance.
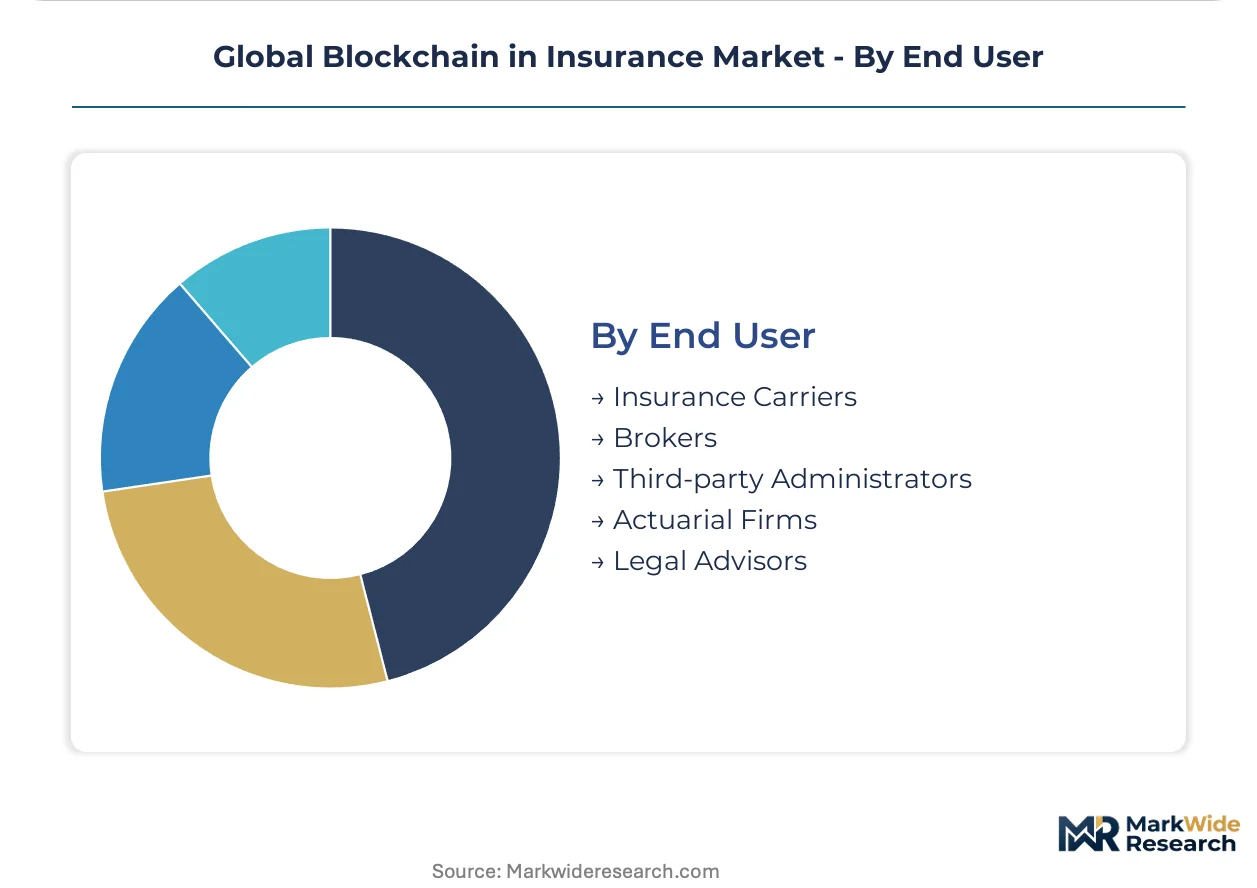
End User:
Value capture potential determines which intermediaries invest in distributed infrastructure.
- Insurance Carriers:Balance sheet entities deploy ledgers to reduce operational expense ratios. Multinational groups in the United States and United Kingdom lead capital commitment.
- Brokers:Intermediaries face disintermediation risk as smart contracts automate placement. Lloyd's coverholders invest in API integration to defend advisory relationships.
- Third-party Administrators:Claims service providers adopt ledgers to accelerate fee-based processing. US health TPAs target Medicare Advantage contract wins.
- Actuarial Firms:Consultants leverage distributed data for model calibration. Bermuda-based specialists serve catastrophe bond structuring.
- Legal Advisors:Law firms validate policy enforceability across jurisdictions. London and New York practices build smart contract litigation expertise.
Technology spending concentrates with Insurance Carriers; advisory services expand fastest among Legal Advisors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blockchain infrastructure development concentrates where regulatory clarity intersects with carrier digitalization budgets. Consumption patterns diverge between mature markets upgrading legacy systems and emerging markets deploying mobile-first architectures.
United States
State insurance commissioners in multiple jurisdictions pilot blockchain-native rate filings, reducing compliance friction for early adopters. The National Association of Insurance Commissioners develops sandbox frameworks permitting live pilots under modified licensing conditions. New York and Hartford insurance clusters drive enterprise procurement for distributed ledger policy administration platforms.
Germany
BaFin mandates operational resilience testing that accelerates permissioned blockchain procurement for policy data immutability. The EU AI Act imposes strict human oversight requirements on automated underwriting decisions, forcing architectural redesigns. Munich and Frankfurt carrier headquarters dominate continental European deployment spending for cryptographic audit trail systems.
United Kingdom
The Financial Conduct Authority permits sandboxed blockchain pilots that accelerate proof-of-concept migration to production scale. Lloyd's coverholders invest in API integration to defend advisory relationships against smart contract disintermediation. London's commercial specialty market mandates direct system-to-system integration for large industrial property and casualty programs.
Singapore
The Monetary Authority of Singapore fosters regulatory clarity for marine cargo documentation tokenization at the Port of Singapore. Peer-to-peer insurers leverage Ethereum-based architectures for parametric crop policies where transparency outweighs privacy concerns. The city-state's reinsurance hub automates treaty administration through shared catastrophe loss databases.
India
Crop insurers deploy mobile-first parametric policies on permissioned ledgers for smallholder farmers, leapfrogging legacy infrastructure. The country's national insurance regulator pilots sandbox frameworks for automated claims settlement in agrarian lines. Mumbai and Bangalore technology clusters supply smart contract development talent to domestic and multinational carriers.
Global Blockchain in Insurance Market Competitive Landscape
The competitive structure tilts toward technology conglomerates with enterprise software heritage. Market concentration reflects the dominance of incumbent IT vendors and specialized distributed ledger developers over pure-play blockchain startups. Two strategic archetypes define positioning: enterprise-grade infrastructure providers and smart contract protocol specialists. Competitive moves center on strategic partnerships with carrier consortiums and technology licensing agreements for permissioned network deployments.
Within the enterprise infrastructure tier, IBM Corporation and Microsoft Corporation occupy positions anchored by decades of carrier relationships and cloud computing scale. Consensys exemplifies the protocol specialist archetype, representing Ethereum-based smart contract architectures that automate policy execution. Guardtime anchors the regional specialist position with quantum-resistant blockchain stacks serving marine and cargo insurance markets in Northern Europe.
| Leading Market Players |
|---|
| IBM Corporation |
| Consensys |
| Etherisc |
| Guardtime |
| ChainThat |
| IntellectEU |
| Accenture |
| Microsoft Corporation |
| Allianz |
| Others |
Supply & Pricing Matrix
Smart contract developer labor costs cascade through blockchain insurance platform tiers, with scarce cryptographic engineering talent in Zurich and Singapore commanding premium rates that downstream carriers pass to enterprise buyers through outcome-based licensing structures.
Pricing Analysis
Outcome-based pricing anchored to claims-processing throughput dominates carrier procurement contracts, with IBM and Consensys structuring fees around policy volumes processed rather than fixed implementation costs. Price differentiation rests on certification grade—carriers pay premiums for SOC 2 Type II and ISO 27001 validated deployments—and geographic delivery cost, with European implementations under GDPR carrying architectural surcharges. Pricing pressure stems from open-source protocol commoditization eroding proprietary ledger margins. Tier-3 regional carriers exhibit highest price sensitivity, while multinational property and casualty groups prioritize uptime guarantees over licensing fees.
Supply Chain Analysis
Regional distribution centers for blockchain infrastructure concentrate in Ireland, Singapore, and Switzerland, where cloud hyperscalers maintain carrier-dedicated availability zones. Hardware dependencies draw from Taiwan for secure enclave processors and Netherlands for specialized networking equipment. Supply chain risk centers on single-source vulnerability for post-quantum cryptographic modules, with NIST-standardized algorithms still consolidating vendor bases. Distribution runs through carrier consortium procurement offices in London, New York, and Munich, with systems integrators managing last-mile deployment to insurer data centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as supply-constrained, with distributed systems engineering talent scarcity propping pricing power for qualified implementation partners.
For Market Incumbents: To counter smart contract protocol commoditization, IBM and Microsoft must deepen captive supply of Hyperledger and Azure Blockchain engineering talent through targeted university partnerships in Bangalore and Zurich. Channel control represents the second lever—incumbents should mandate API exclusivity clauses in carrier consortium contracts to lock out Ethereum-based competitors. For New Entrants and Emerging Players: Smallholder crop insurers in India's uninsured agrarian districts present the most penetrable buyer archetype, with parametric policy automation unmet by legacy vendor footprints. New entrants should pursue mobile-first deployment partnerships with domestic agritech platforms, bypassing carrier IT procurement cycles entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor quantum-resistant blockchain specialists in Northern Europe, where Guardtime's regional dominance offers defensive moats against NIST algorithm standardization delays. Long-term viability hinges on regulatory mandate timing—watch for the first jurisdiction mandating blockchain-native reporting standards as the inflection signal for cross-border treaty adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Contract Protocol Standardization | Ethereum-compatible tooling reduces carrier switching costs and accelerates developer talent pools. |
| Post-Quantum Cryptography Migration | NIST algorithm adoption future-proofs marine and cargo policies against quantum decryption threats. |
| Regulatory Sandbox Entry | BaFin and FCA pilot approvals de-risk production deployment for permissioned network architectures. |
| Consortium Blockchain Governance | Rotterdam and Singapore port coalitions distribute infrastructure costs across competing marine underwriters. |
| Self-Sovereign Identity Integration | GDPR-compliant KYC credentials open banking and healthcare vertical monetization for European carriers. |
Research Methodology
Multi-period observation of smart contract deployment volumes and regulatory sandbox admission rates anchored the trend analysis, supplemented by interviews with carrier CIOs, reinsurance treaty administrators, regulatory sandbox coordinators, and distributed ledger protocol engineers. Secondary validation drew from NAIC rate filing databases, EU DORA implementation guidance, SEC insurance holding company disclosures, and Lloyd's market reform documentation. Bottom-up carrier procurement tracking and top-down technology vendor revenue analysis were triangulated against consortium membership rosters.
Input-output matrices mapped smart contract transaction volumes to premium processing throughput across private, public, consortium, and hybrid ledger architectures. Segmentation dimensions modeled include technology type, solution offering, application function, and end-user category, with regional adoption patterns capturing jurisdictional regulatory divergence. CAGRs were derived from S-curve penetration modeling calibrated to historical enterprise software adoption benchmarks, with quantum computing threat timelines and GDPR compliance cost curves as industry-specific forecast inputs.
Revisions become necessary when NIST post-quantum algorithm standardization accelerates, EU AI Act enforcement tightens automated underwriting constraints, or carrier consortium governance fractures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
Global Insurance Agency Software Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
United States Insurtech Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
North America Insurtech Market
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
UK Insurtech Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Artificial Intelligence in Insurtech Market
Insurance Technology
Insurtech Market
Insurance Technology
Insurance Automation Market
Insurance Technology
Global Insurance Telematics Market
Insurance Technology
Asia-Pacific Insurtech Market
Insurance Technology
Insurance Software Market