
 Marine Insurance Market | 2026-2036
Marine Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Insurance Market Intelligence
Parametric risk-transfer products tied to voyage data and weather indices is realigning how marine coverage gets priced and delivered. Lloyd's of London leverages its syndicated capital structure to dominate complex hull and liability placements. Tokio Marine Kiln anchors Asia-Pacific cargo flows through specialized underwriting expertise in regional port risks. Progressive competes in recreational marine lines through direct digital distribution and streamlined policy administration.
Marine insurance is a specialized risk-transfer mechanism covering vessels, cargo, terminals, and transport infrastructure against physical loss, damage, and third-party liability during waterborne transit; policies incorporate nautical perils, general average clauses, and sue-and-labor provisions calibrated to international maritime law. Hull insurance commands the largest premium pool due to high vessel replacement values and concentrated exposures in major shipping lanes. Cargo insurance is recording accelerated uptake among freight forwarders managing just-in-time supply chains with narrow inventory buffers. Liability coverage, particularly pollution liability, is deepening as environmental damage claims escalate in frequency and severity across coastal jurisdictions.
The International Maritime Organization (IMO) mandates through its Marine Environment Protection Committee shape hull and machinery standards that directly affect loss ratios and premium adequacy. The EU Green Deal and associated CSRD disclosure requirements are forcing European-flagged operators to document emissions profiles, which underwriters now incorporate into risk selection and pricing models. Lloyd's of London and national regulators in Singapore and Japan maintain stringent capital reserving frameworks that determine market access for new entrants. Stakeholders must monitor how satellite-based vessel tracking and automated claims adjudication reshape the traditional broker-mediated distribution model.
Market Dynamics
Climate-induced route volatility and satellite-enabled voyage transparency are compressing traditional underwriting cycles while forcing real-time recalibration of risk pricing across hull and cargo lines.
Growth Catalysts
- IMO Decarbonization Mandates:The International Maritime Organization's carbon intensity indicators are compelling fleet operators to upgrade vessel efficiency profiles, generating fresh demand for machinery breakdown and loss-of-hire coverage.
- East Asian Port Cluster Concentration:Maritime traffic density around Singapore, Shanghai, and Busan is amplifying demand for terminal operators' liability and port infrastructure policies.
- Parametric Trigger Structures:Weather-indexed contracts tied to automated vessel tracking data are streamlining claims settlement and reducing loss-adjustment expenses for cargo underwriters.
Market Restraints
- Hull Steel Price Volatility:Fluctuations in Korean and Chinese shipyard input costs are destabilizing replacement value calculations and eroding premium adequacy on newbuild coverage.
- Reinsurance Capacity Concentration:Bermuda and London market syndicates control disproportionate catastrophe excess layers, creating bottleneck pricing for war risk and terrorism extensions.
- Legacy IT Architecture:Established carriers' core policy administration systems lack API connectivity with IoT sensor networks, delaying usage-based premium deployment.
Strategic Opportunities
- Indian Coastal Shipping Expansion:The country's Sagarmala port modernization program is unlocking demand for domestic cabotage insurance among regional fleet operators.
- EU Green Deal CSRD Alignment:Mandatory emissions disclosure requirements are creating advisory revenue streams for insurers offering carbon risk auditing alongside traditional hull coverage.
- Telematics-AI Convergence:Satellite AIS data fused with machine learning models enables dynamic premium adjustment based on real-time vessel stress indicators and route hazard scores.
Industry Challenges
- Actuarial Talent Scarcity:Shortages of professionals trained in both maritime law and data science are constraining model development for parametric product lines.
- Cross-Border Claims Jurisdiction:Conflicting interpretations of general average clauses across English, New York, and Scandinavian maritime legal traditions prolong settlement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Insurance Market |
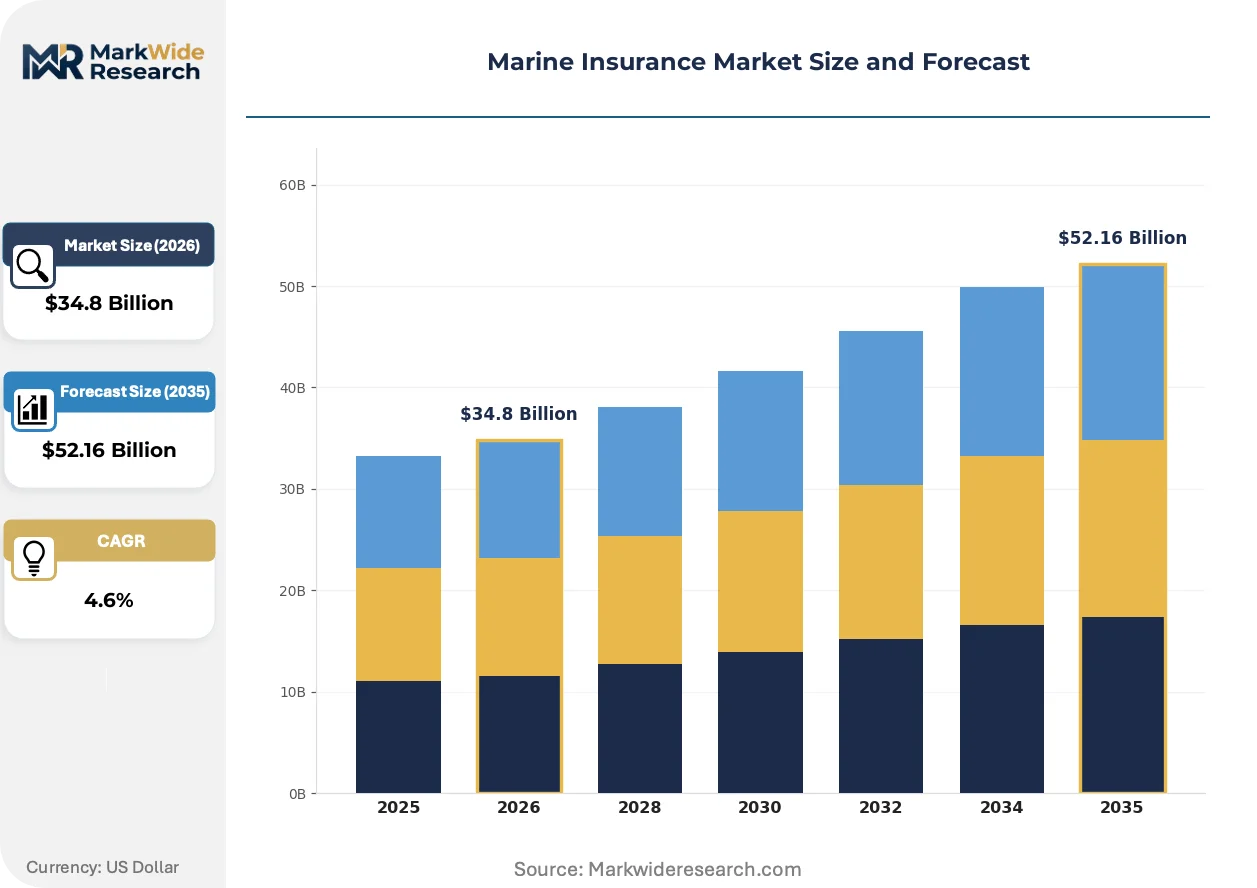
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $52.16 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Hull Insurance, Cargo Insurance, Liability Insurance, Freight Insurance End User: Shipping Companies, Freight Forwarders, Importers, Exporters Coverage Type: Physical Damage, Loss of Cargo, Marine Liability, Pollution Liability Distribution Channel: Brokerages, Direct Sales, Online Platforms, Insurance Agents |
| Companies Covered | PURE Insurance, Global Marine Insurance Agency, Progressive, Tokio Marine Kiln, Tokio Marine Highland, Geico, Ahoy! Insurance, Lloyd's of London, Nationwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Insurance Market Strategic Shifts & Innovations
Digital risk-transfer mechanisms and automated underwriting infrastructure are displacing broker-mediated placement workflows while compressing policy issuance cycles from weeks to hours.
Blockchain-enabled smart contracts are integrating distributed ledger verification with parametric trigger execution. Freight forwarders managing just-in-time inventory chains are adopting these instruments for automated cargo claim settlement. The technology is integrating irrevocable payment execution with satellite-confirmed delivery confirmation, eliminating documentary dispute resolution.
The EU Green Deal's CSRD disclosure framework is mandating emissions transparency for European-flagged operators. Underwriters now embed carbon intensity scores into risk selection algorithms and premium tiering structures. Hull and machinery coverage for vessels above specific emissions thresholds faces heightened deductibles or capacity restrictions.
Buyers are consolidating procurement through direct digital platforms that unbundle traditional broker services. Large container lines and commodity traders are accessing Lloyd's syndicated capacity through API-connected placement systems. This channel compression is most pronounced among Singapore-based commodity trading houses managing high-frequency cargo movements.
Marine Insurance Market Segmentation
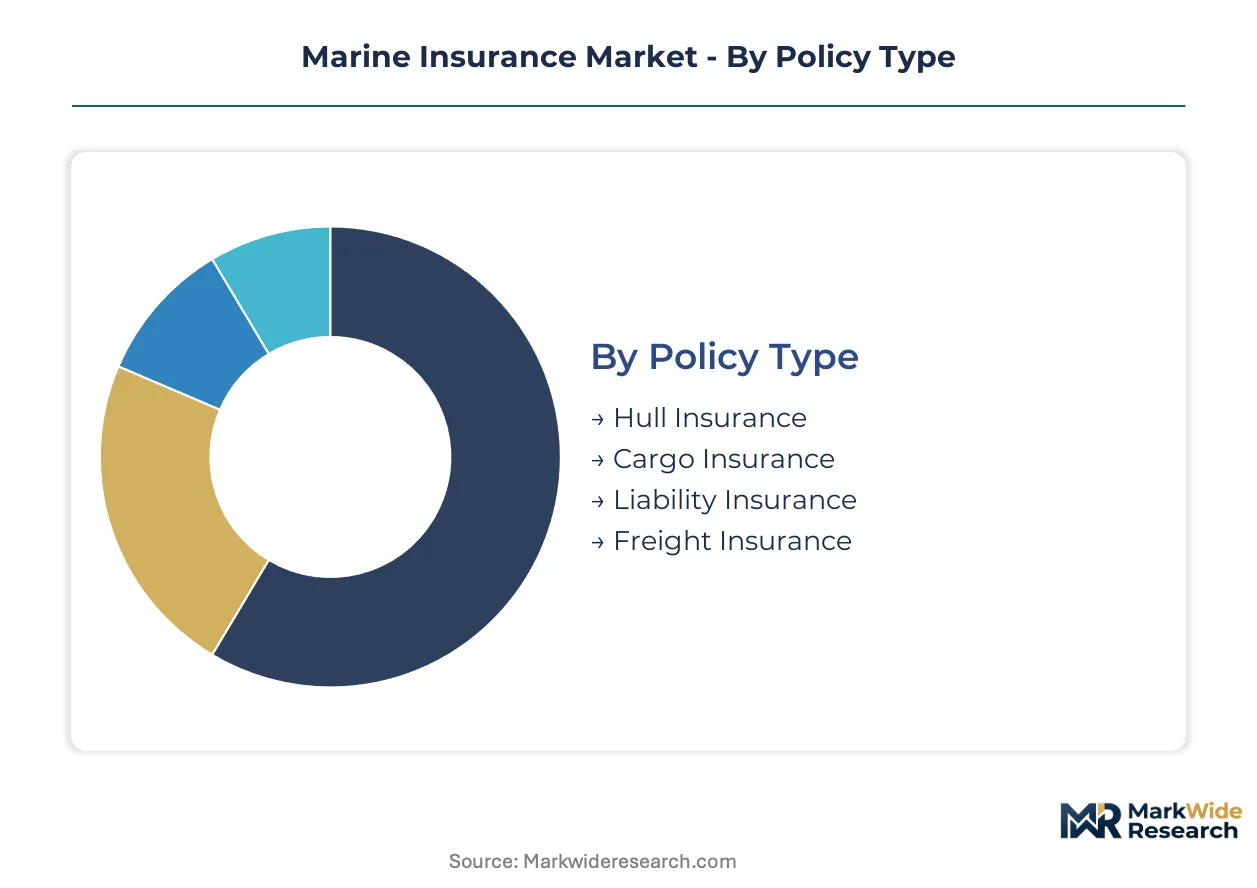
Marine insurance segmentation reflects divergent risk exposures across vessel operations, cargo flows, and liability jurisdictions. Underwriters calibrate premium structures, policy terms, and capital reserves differently for each segment based on loss frequency patterns and regulatory enforcement intensity.
Policy Type:
Buyers differentiate by asset concentration and voyage frequency rather than fleet size alone.
- Hull Insurance:Covers physical damage to vessels, machinery, and equipment against perils including collision, grounding, and fire. Demand concentrates among Singapore-based container operators managing high-frequency Asia-Europe rotations, driven by IMO-mandated machinery upgrade cycles and escalating repair costs at Korean and Chinese shipyards.
- Cargo Insurance:Protects goods during transit against theft, damage, and delay. Freight forwarders in Shanghai and Busan corridors are expanding coverage purchases as climate-related route disruptions intensify, narrowing inventory buffers in just-in-time supply chains.
- Liability Insurance:Third-party coverage for bodily injury, property damage, and collision liability.
- Freight Insurance:Protects against loss of freight revenue from cargo damage or vessel unavailability.
Hull insurance leads volumes today; cargo insurance is gaining share fastest.
End User:
Procurement sophistication varies by integration depth into maritime supply chains.
- Shipping Companies:Vessel-owning operators purchasing comprehensive fleet coverage including hull, machinery, and protection and indemnity. Large Greek and Danish operators dominate premium pools through centralized risk management functions and captive insurance structures.
- Freight Forwarders:Non-vessel-operating intermediaries arranging cargo coverage for shipper clients. Digital platforms in Singapore and Rotterdam are displacing traditional broker relationships through API-connected policy issuance.
- Importers:Manufacturing and retail buyers securing contingent cargo interest coverage.
- Exporters:Commodity producers and finished goods shippers managing letter-of-credit compliance requirements.
Shipping companies anchor premium volumes; freight forwarders are expanding coverage purchases most rapidly.
Coverage Type:
Regulatory enforcement intensity shapes demand concentration across liability categories.
- Physical Damage:Coverage for vessel structural integrity and machinery systems. European-flagged operators face tightening EU Green Deal compliance requirements that embed emissions profiles into risk selection algorithms and premium tiering structures.
- Loss of Cargo:Indemnification for goods damaged, destroyed, or delayed during transit. Automated parametric triggers tied to satellite-confirmed delivery confirmation are streamlining claims settlement for high-frequency cargo movements through Singapore and Shanghai.
- Marine Liability:Protection against third-party claims including collision and fixed-object damage.
- Pollution Liability:Coverage for environmental damage from bunker spills and cargo release. Coastal jurisdictions in Japan and South Korea are escalating claim frequency and severity through stricter enforcement of International Convention on Civil Liability for Oil Pollution Damage protocols.
Physical damage coverage dominates premium volumes; pollution liability is climbing the fastest.
Distribution Channel:
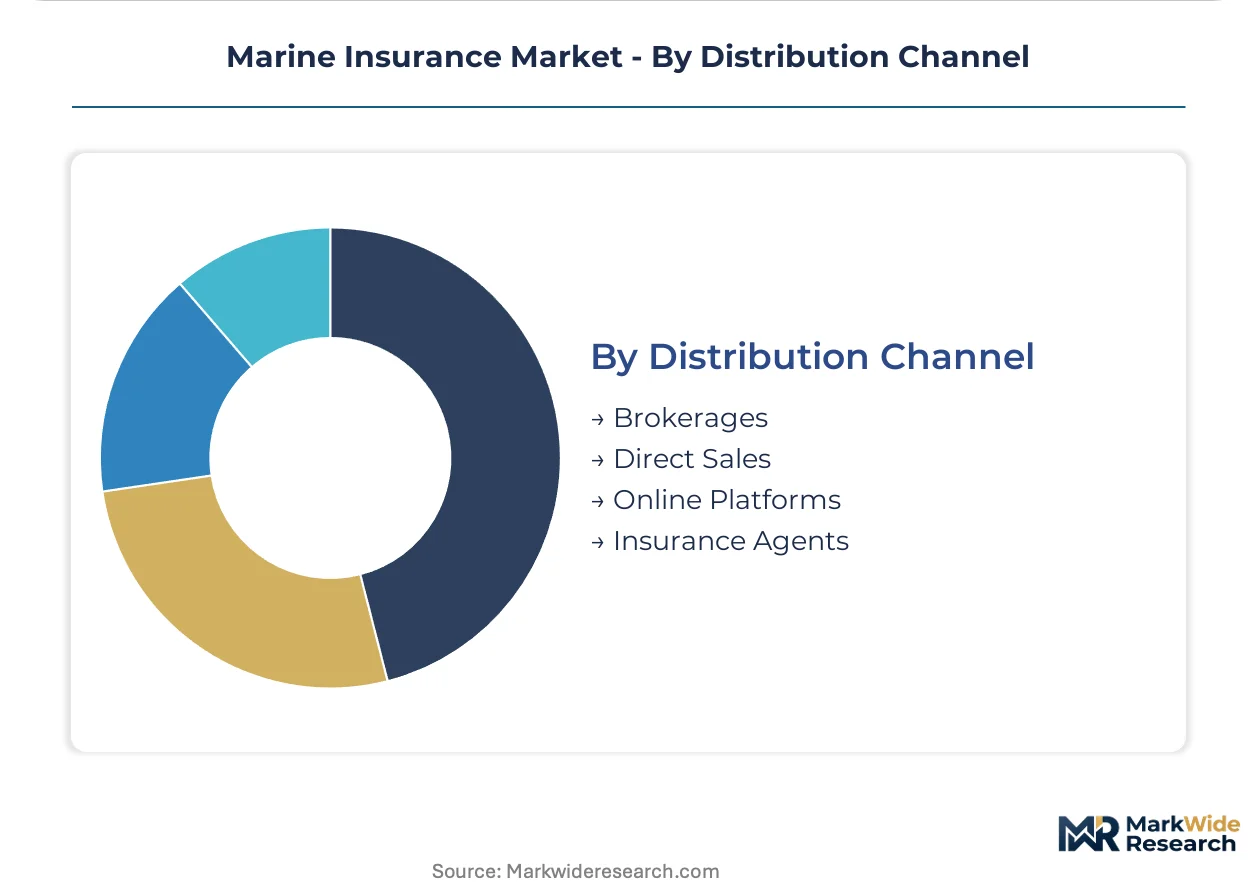
Channel selection reflects policy complexity and buyer digital maturity.
- Brokerages:Intermediaries placing complex risks across Lloyd's syndicated capacity. London and Singapore brokerages maintain dominance in war risk, terrorism extensions, and catastrophe excess layers where Bermuda market concentration creates pricing bottlenecks.
- Direct Sales:Carrier-owned distribution for large fleet accounts with centralized procurement functions. Maersk and MSC operate captive placement relationships bypassing traditional intermediaries for hull and machinery renewals.
- Online Platforms:Digital distribution enabling real-time quotation and policy issuance.
- Insurance Agents:Local representatives serving recreational marine and small commercial vessel segments.
Brokerages retain the largest placement volumes; online platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore generates denser marine premium volumes than Germany, while Japan's coastal enforcement regimes drive faster liability coverage expansion than either European or Southeast Asian markets.
Singapore
Container traffic through the Singapore Strait sustains concentrated demand for terminal operators' liability and port infrastructure policies. The Maritime and Port Authority of Singapore enforces strict bunker spill preparedness standards that elevate pollution liability premiums. Trading houses headquartered in Singapore's central business district are consolidating cargo coverage procurement through API-connected digital platforms.
United Kingdom
Lloyd's of London syndicates dominate complex hull and war risk placements for Greek and Danish fleet operators. The UK Prudential Regulation Authority maintains capital reserving frameworks that determine market access for international underwriters. London brokerages retain placement dominance for catastrophe excess layers where Bermuda market concentration creates pricing bottlenecks.
Japan
Coastal jurisdictions in Osaka Bay and Nagoya Harbor are escalating pollution claim frequency through stricter enforcement of International Convention on Civil Liability for Oil Pollution Damage protocols. METI coordinates vessel efficiency standards that reshape machinery breakdown coverage requirements. Tokio Marine anchors Asia-Pacific cargo flows through specialized underwriting expertise in regional port risks.
South Korea
Busan port zone concentration amplifies demand for high-frequency cargo movements and automated parametric triggers. The Ministry of Oceans and Fisheries mandates emissions disclosure for Korean-flagged operators that underwriters embed into risk selection algorithms. Korean shipyards in Ulsan and Geoje drive hull steel price volatility that destabilizes replacement value calculations.
United States
Recreational marine lines in Florida and the Pacific Northwest attract direct digital distribution through streamlined policy administration platforms. The US Coast Guard enforces pollution liability protocols in coastal jurisdictions where environmental damage claims escalate in severity. Progressive competes in recreational segments while nationwide broker networks handle commercial fleet placements.
Marine Insurance Market Key Industry Players
Top-tier vendors anchor syndicated capital structures, while mid-tier specialists compete through regional underwriting expertise and direct digital channels. The market exhibits tiered concentration with Lloyd's of London commanding complex risk placements and national carriers dominating standardized cargo lines. Three archetypes define competitive positioning: syndicated capital pools, regional specialist underwriters, and direct-to-consumer digital distributors. M&A activity concentrates on technology-enabled claims platforms, while capacity expansion targets parametric product development.
Within the syndicated capital tier, Lloyd's of London exemplifies complex hull and liability placement dominance through its distributed underwriting architecture. Tokio Marine Kiln occupies a position as the anchor for Asia-Pacific cargo risk expertise, particularly around Singapore, Shanghai, and Busan port zones. Progressive represents the digital distribution archetype, competing in recreational marine lines through streamlined policy administration and direct consumer channels.
| Leading Market Players |
|---|
| PURE Insurance |
| Global Marine Insurance Agency |
| Progressive |
| Tokio Marine Kiln |
| Tokio Marine Highland |
| Geico |
| Ahoy! Insurance |
| Lloyd's of London |
| Nationwide |
| Others |
Cost & Logistics Intelligence
Captive underwriting capacity in Bermuda and London syndicates anchors both risk placement availability and premium rate-setting power for catastrophe excess layers. Lloyd's distributed capital structure enables complex hull pricing that smaller national carriers cannot replicate, while Korean and Chinese shipyard input costs feed directly into replacement value calculations for newbuild coverage.
Pricing Analysis
Capacity additions in Singapore and Shanghai are reshaping price floors for cargo lines as digital platforms compress broker margins. Three-tier pricing structure across premium, standard, and economy levels separates Lloyd's syndicated placements from regional specialist quotes and direct digital recreational policies. Price differentiation hinges on satellite tracking integration and emissions certification tier under EU Green Deal CSRD alignment. Pricing pressure stems from hull steel volatility at Korean shipyards, with freight forwarders showing highest sensitivity and Greek fleet operators least responsive due to captive structures.
Supply Chain Analysis
Claims settlement velocity now depends on reverse data flows from automated parametric triggers back to underwriter capital reserves. Underwriting capacity concentrates in Bermuda, London, and Singapore as primary risk-acceptance nodes. Marine insurers draw from reinsurance treaties, retrocession arrangements, and alternative capital instruments as core funding inputs. Single-source vulnerability runs through Bermuda catastrophe excess layers where syndicate concentration creates placement bottlenecks. Distribution runs through Lloyd's broker networks for complex risks and API-connected platforms for standardized cargo lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine insurance functions as a regulatory compounder where IMO decarbonization mandates and EU Green Deal CSRD disclosure requirements continuously expand mandatory coverage categories and tighten risk selection criteria.
For Market Incumbents: Cement syndicated capital advantages by deepening parametric product development before alternative capital entrants scale weather-indexed offerings. Acquire satellite-AIS data analytics capabilities to defend placement relationships against API-connected digital platforms. Prioritize machinery breakdown coverage expansion as IMO carbon intensity indicators force fleet upgrade cycles. For New Entrants and Emerging Players: Digital freight forwarders in Singapore and Rotterdam corridors offer the most penetrable entry point for API-enabled cargo policy issuance. Target Indian coastal shipping operators underserved by Lloyd's-focused international carriers. Lead with automated parametric triggers for high-frequency Asia-Europe rotations where legacy carriers lack IoT integration. For Investors and Strategic Acquirers: Roll-up economics work for regional specialist underwriters with port-specific expertise because fragmented cargo risk knowledge across Shanghai, Busan, and Singapore resists centralized algorithmic pricing. Platform consolidation targets technology-enabled claims adjudication capabilities. Monitor IMO Marine Environment Protection Committee enforcement intensity as inflection indicator for pollution liability premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Weather-indexed contracts reduce loss-adjustment expenses through automated satellite-triggered settlement. |
| API Platform Integration | Direct digital placement displaces broker-mediated workflows for Singapore commodity trading houses. |
| Carbon Risk Auditing Services | EU Green Deal CSRD alignment creates advisory revenue alongside traditional hull coverage. |
| Satellite-AIS Data Partnership | Real-time vessel stress indicators enable dynamic premium adjustment for machinery breakdown lines. |
| Indian Coastal Expansion | Sagarmala port modernization unlocks domestic cabotage demand among regional fleet operators. |
Research Approach
Multiple input streams — underwriter placement executives, marine broker operations heads, port authority risk managers, and freight forwarder procurement leads — were reconciled against Lloyd's market filings, IMO regulatory submissions, EU CSRD disclosure databases, and satellite vessel tracking datasets. Primary interviews with syndicate capital providers and Asian cargo specialists were validated through secondary sources including Bermuda market catastrophe bond filings and Korean shipyard cost indices. Bottom-up premium volume estimates triangulated against top-down market sizing from regulatory capital adequacy reports.
Historical premium trends were cross-referenced against panel input from underwriting directors to establish baseline loss ratios across the projection horizon. Segmentation modeling incorporated policy type, end-user archetype, coverage category, and distribution channel dimensions. CAGRs were derived from trend extrapolation calibrated to IMO regulatory milestone timing and fleet renewal cycle patterns. Forecast inputs included climate-induced route volatility indices and parametric product penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IMO enforcement intensity and EU Green Deal expansion scope. Practitioners should monitor IMO Marine Environment Protection Committee rulings and EU CSRD disclosure threshold adjustments for early signals of coverage mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Motor Insurance
Vietnam Motor Insurance Market
Motor Insurance
Asia-Pacific Car Insurance Market
Motor Insurance
Indonesia Motor Insurance Market
Motor Insurance
Europe Mandatory Motor Third-Party Liability Insurance Market
Motor Insurance
South Korea Motor Insurance Market
Motor Insurance
Germany Motor Insurance Market
Motor Insurance
Two Wheeler Insurance Market
Motor Insurance
Motor Insurance Market
Motor Insurance
Singapore Motor Insurance Market
Motor Insurance
China Motor Insurance Market
Motor Insurance
India Motor Insurance Market
Motor Insurance
Taiwan Car Insurance Market
Motor Insurance
Automotive Insurance Market
Motor Insurance
Motorcycle Insurance Market
Motor Insurance
Taiwan Motor Insurance Market
Motor Insurance
Bangladesh Motor Insurance Market