
 North America Automotive Airfilters Market | 2026-2036
North America Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Airfilters Market Analytics
ISO 5011 test protocol certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Donaldson Company leverages its vertically integrated media manufacturing to sustain pricing power across heavy-duty applications. MANN+HUMMEL anchors its position through OEM supply contracts with Detroit-based automakers.
North America automotive airfilters are pleated fibrous media devices engineered to remove particulate contaminants from intake air streams, with efficiency ratings typically exceeding 99 percent for particles above five microns to protect internal combustion engines and cabin environments. Panel filters dominate volume shipments across passenger car and light truck parc, while HEPA filters command premium positioning within electric vehicle cabin air systems where occupant health sensitivity runs highest. Synthetic fiber media displaces traditional fiberglass in aftermarket channels due to superior moisture resistance and extended service intervals.
The EPA enforces tailpipe and evaporative emission standards that directly mandate intake air filtration integrity, while NHTSA safety regulations influence cabin air quality specifications for occupant protection. California Air Resources Board protocols function as de facto North American benchmarks, compelling manufacturers to validate products against the nation's most stringent test cycles. Stakeholders must monitor evolving federal particulate standards and state-level zero-emission vehicle mandates that will redefine filtration requirements across propulsion architectures.
Market Dynamics
The EPA's tightened particulate matter standards are forcing filter manufacturers to redesign media compositions and validate new test protocols, while fleet operators in the United States and Canada expand preventive maintenance schedules for commercial vehicles.
Growth Catalysts
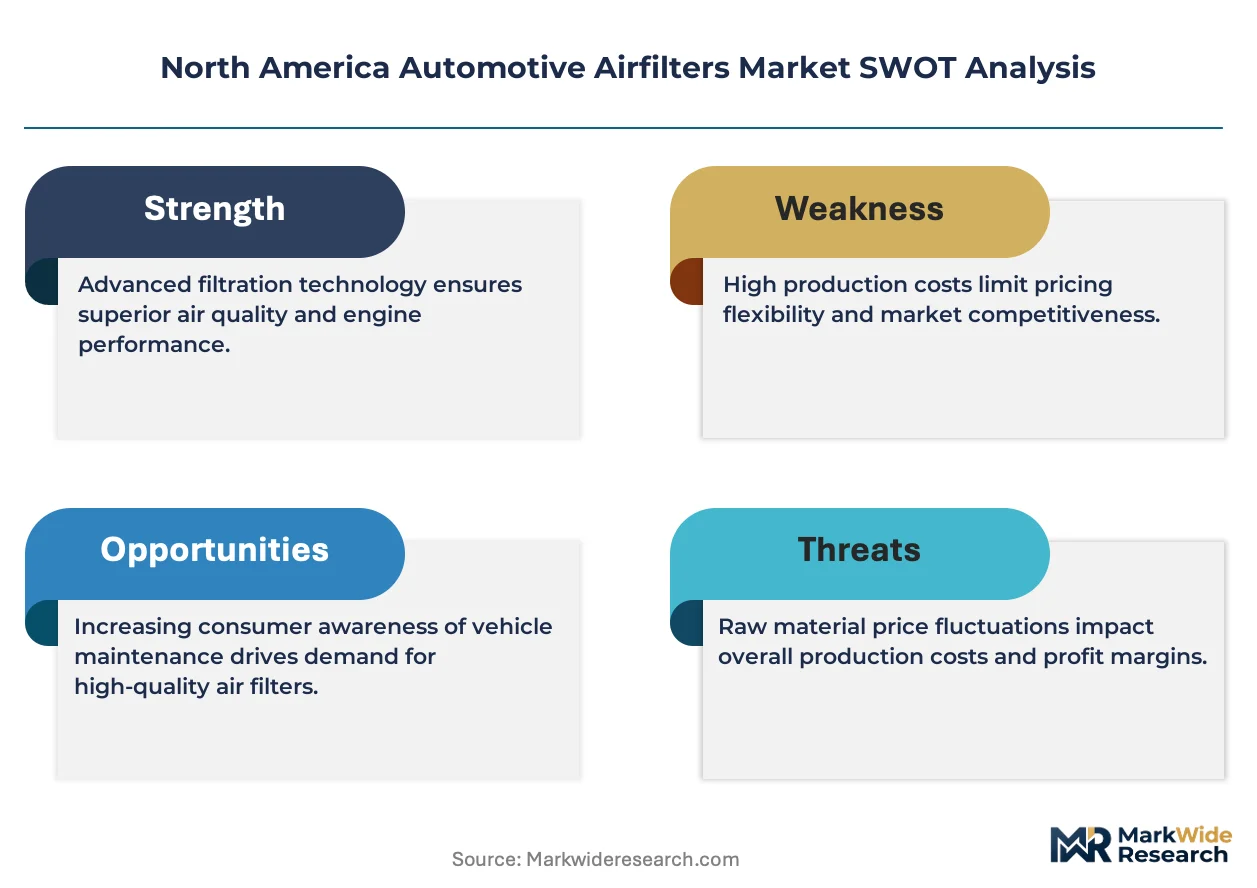
- EPA Particulate Standards:Tightened tailpipe and evaporative emission mandates are compelling OEMs and aftermarket suppliers to upgrade intake air filtration integrity across heavy-duty and light-duty vehicle platforms.
- Electric Vehicle Cabin Systems:HEPA-grade cabin air filtration is becoming standard equipment in battery electric vehicles as occupant health sensitivity drives specification upgrades.
- Synthetic Fiber Media:Superior moisture resistance and extended service intervals are displacing traditional fiberglass in aftermarket channels, particularly in the Great Lakes automotive manufacturing corridor.
Market Restraints
- ISO 5011 Certification Barriers:Test protocol certification requirements are bifurcating the competitive landscape and marginalizing suppliers lacking capital for validation infrastructure.
- Petrochemical Input Volatility:Synthetic polymer feedstock costs fluctuate with crude oil pricing, compressing margin stability for media manufacturers dependent on polypropylene and polyester fibers.
- Regional Supply Concentration:Filter media production clusters in Michigan, Ohio, and Ontario create geographic vulnerability to localized logistics disruptions and labor market tightness.
Strategic Opportunities
- California ZEV Mandates:State-level zero-emission vehicle requirements are redefining cabin filtration specifications and creating premium product tiers for electric vehicle platforms.
- Canadian Fleet Electrification:Federal and provincial commercial vehicle decarbonization incentives are expanding addressable market for specialized filtration in battery electric trucks and buses.
- Smart Filter Monitoring:Integration of pressure differential sensors with telematics systems is enabling predictive maintenance models and subscription-based filter replacement services.
Industry Challenges
- Media Engineering Talent Scarcity:Specialized expertise in nanofiber layering and electrostatic charging processes is concentrated among a limited pool of filtration scientists, constraining R&D velocity.
- Dual Certification Timelines:Simultaneous validation against EPA federal standards and California Air Resources Board protocols extends product launch cycles and increases compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Airfilters Market |
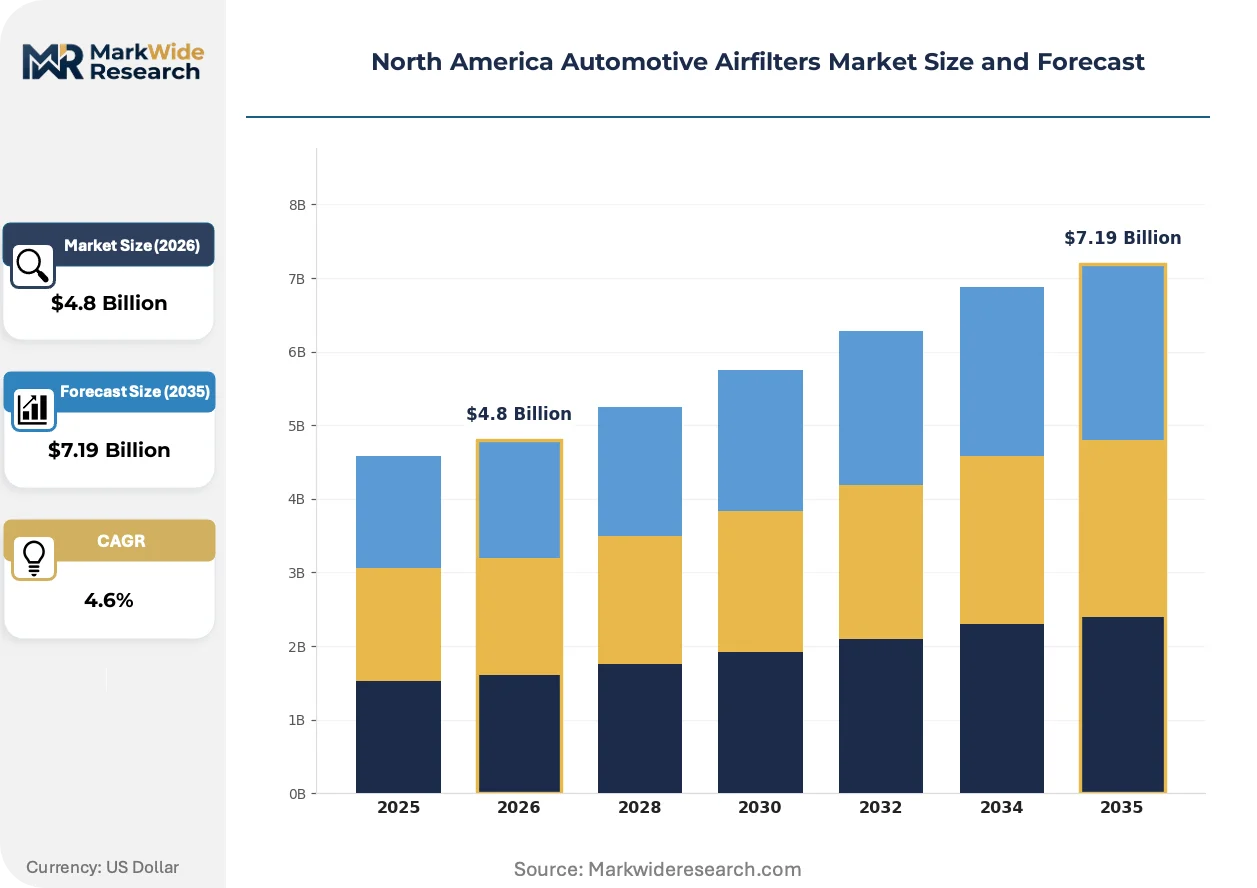
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Filters, Cabin Filters, HEPA Filters, Oil Filters Material: Fiberglass, Synthetic Fiber, Activated Carbon, Cotton Vehicle Type: Passenger Cars, Light Trucks, Motorcycles, Commercial Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Workshops |
| Companies Covered | Donaldson Company, MANN+HUMMEL, K&N Engineering, Parker-Hannifin Corporation, Cummins Inc., ACDelco, Purolator Filters, DENSO Corporation, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Airfilters Market Evolving Landscape
Active developments across materials science, regulatory compliance frameworks, and service delivery models are compressing product lifecycles and reconfiguring value capture in automotive air filtration.
Nanofiber surface-loading media is miniaturizing filter packaging while maintaining particulate capture efficiency above five microns. Electric vehicle manufacturers in California and Michigan are adopting these compact designs to free underhood space for battery thermal management systems. The structural consequence is a compression of traditional pleated panel filter dimensions by thirty to forty percent without performance degradation.
California Air Resources Board protocols are functioning as de facto North American benchmarks for cabin air quality specifications. Manufacturers must now validate products against the nation's most stringent test cycles before securing OEM supply contracts with Detroit-based automakers. The passenger car and light truck segments are responding by pre-certifying entire product families to CARB standards rather than maintaining separate regional SKUs.
Fleet maintenance departments are unbundling filter replacement from bundled service contracts and moving toward direct procurement through specialized distributors. Heavy-duty commercial operators in the United States and Canada are negotiating multi-year supply agreements with ISO 5011-qualified suppliers, bypassing traditional jobber networks. This pattern is most visible among Class 8 truck fleets operating along the I-75 corridor between Michigan and Florida.
North America Automotive Airfilters Market Segmentation
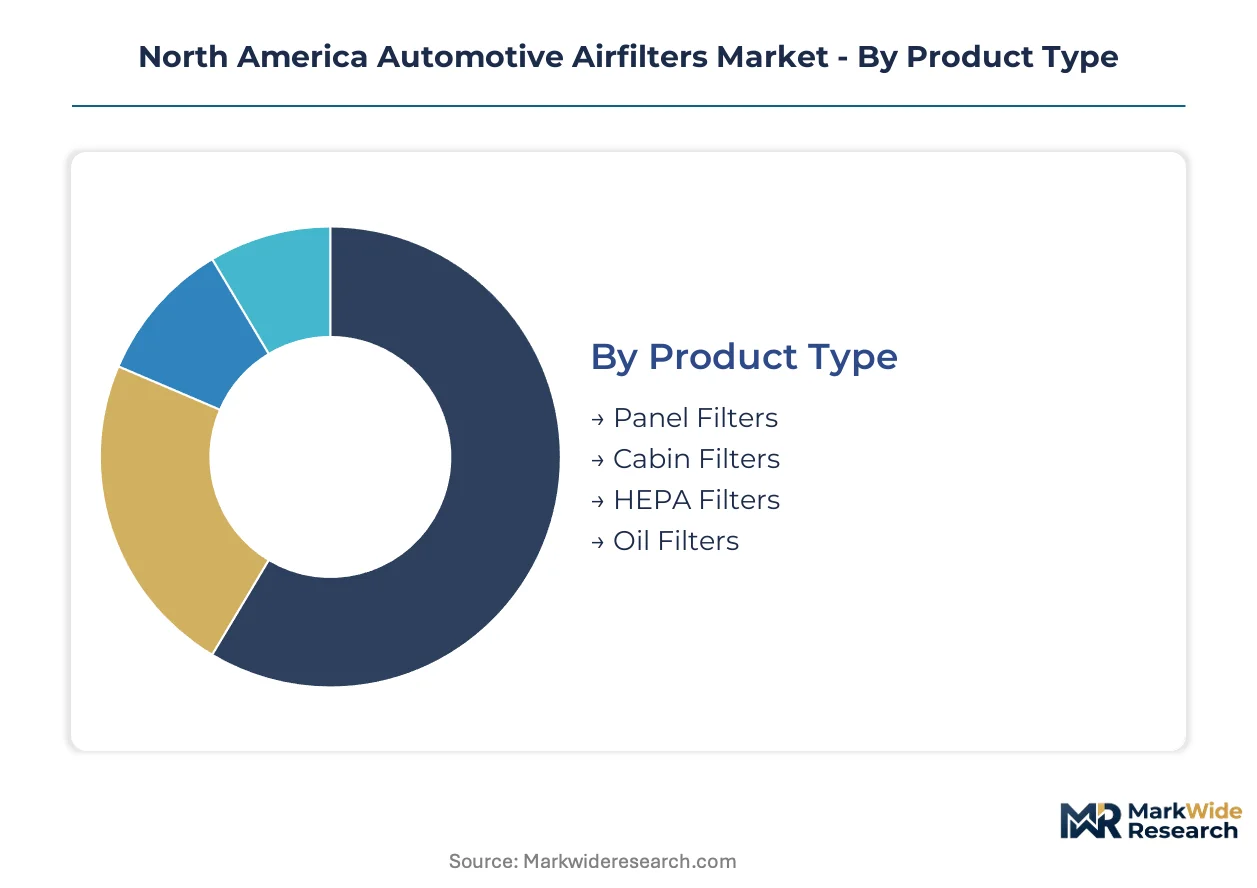
Segmentation in the North America automotive airfilters market reveals distinct procurement patterns across product categories, with OEM and aftermarket channels diverging sharply in specification requirements and pricing tolerance. Understanding these channel dynamics enables suppliers to align manufacturing capacity with demand concentration in Michigan, Ohio, and Ontario.
Product Type:
Channel distribution varies dramatically by product type, with panel and cabin filters flowing through high-velocity aftermarket distributors while HEPA filters concentrate in OEM supply agreements with Detroit-based manufacturers.
- Panel Filters:Pleated fibrous media devices engineered for intake air streams, typically achieving 99 percent efficiency for particles above five microns. Demand concentrates in light truck applications across the Great Lakes corridor, where extended service intervals drive preference for synthetic fiber variants over traditional fiberglass.
- Cabin Filters:Multi-layer media assemblies protecting vehicle occupants from particulate and gaseous contaminants. Electric vehicle platforms in California and Michigan are standardizing HEPA-grade specifications, creating a premium tier that commands pricing multiples over conventional designs.
- HEPA Filters:High-efficiency particulate air systems with sub-micron capture capability. Battery electric vehicle manufacturers specify these for cabin environments where occupant health sensitivity runs highest.
- Oil Filters:Full-flow and bypass configurations protecting engine lubrication systems from abrasive contaminants. Commercial vehicle fleets in the United States and Canada negotiate direct procurement agreements for high-capacity designs.
By volume, panel filters lead. By growth pace, HEPA filters are expanding most quickly.
Material:
Material selection tracks directly to application durability requirements and service environment moisture exposure, with synthetic formulations gaining share in regions experiencing seasonal humidity extremes.
- Synthetic Fiber:Polypropylene and polyester nonwoven media delivering superior moisture resistance and extended service intervals. Aftermarket channels in the Great Lakes automotive manufacturing corridor are displacing fiberglass with these formulations.
- Fiberglass:Traditional borosilicate glass fiber media with established cost positioning. Price-sensitive applications in commercial vehicle segments retain this material for standard-duty replacement cycles.
- Activated Carbon:Adsorptive layer integrations targeting cabin air quality against volatile organic compounds and odorants. California Air Resources Board protocols are driving specification upgrades in passenger car segments.
- Cotton:Washable and reusable media configurations popular in specialty and performance aftermarket applications. Limited OEM adoption due to maintenance complexity and variable efficiency retention.
Synthetic fiber commands the largest volume position. Activated carbon is climbing the fastest as cabin air quality regulations tighten.
Vehicle Type:
Vehicle classification determines filter sizing, duty cycle intensity, and replacement frequency, with commercial platforms generating the highest per-unit filter consumption through accelerated maintenance schedules.
- Commercial Vehicles:Class 6-8 trucks and buses operating under severe-duty cycles with shortened service intervals. Fleet operators along the I-75 corridor between Michigan and Florida are unbundling filter procurement from bundled service contracts.
- Passenger Cars:Light-duty platforms with standardized filter form factors and extended OEM-recommended replacement intervals. The segment shows highest sensitivity to pricing pressure in aftermarket channels.
- Light Trucks:Pickup and SUV configurations with elevated dust exposure in rural and construction applications. Michigan and Ohio manufacturing clusters supply this segment with regionally produced media.
- Motorcycles:Compact powertrains with exposed intake positioning requiring specialized compact filter designs. Aftermarket specialty distributors serve this fragmented demand base.
Passenger cars generate the highest absolute unit volumes. Commercial vehicles show the steepest expansion trajectory as fleet electrification accelerates filter replacement protocol development.
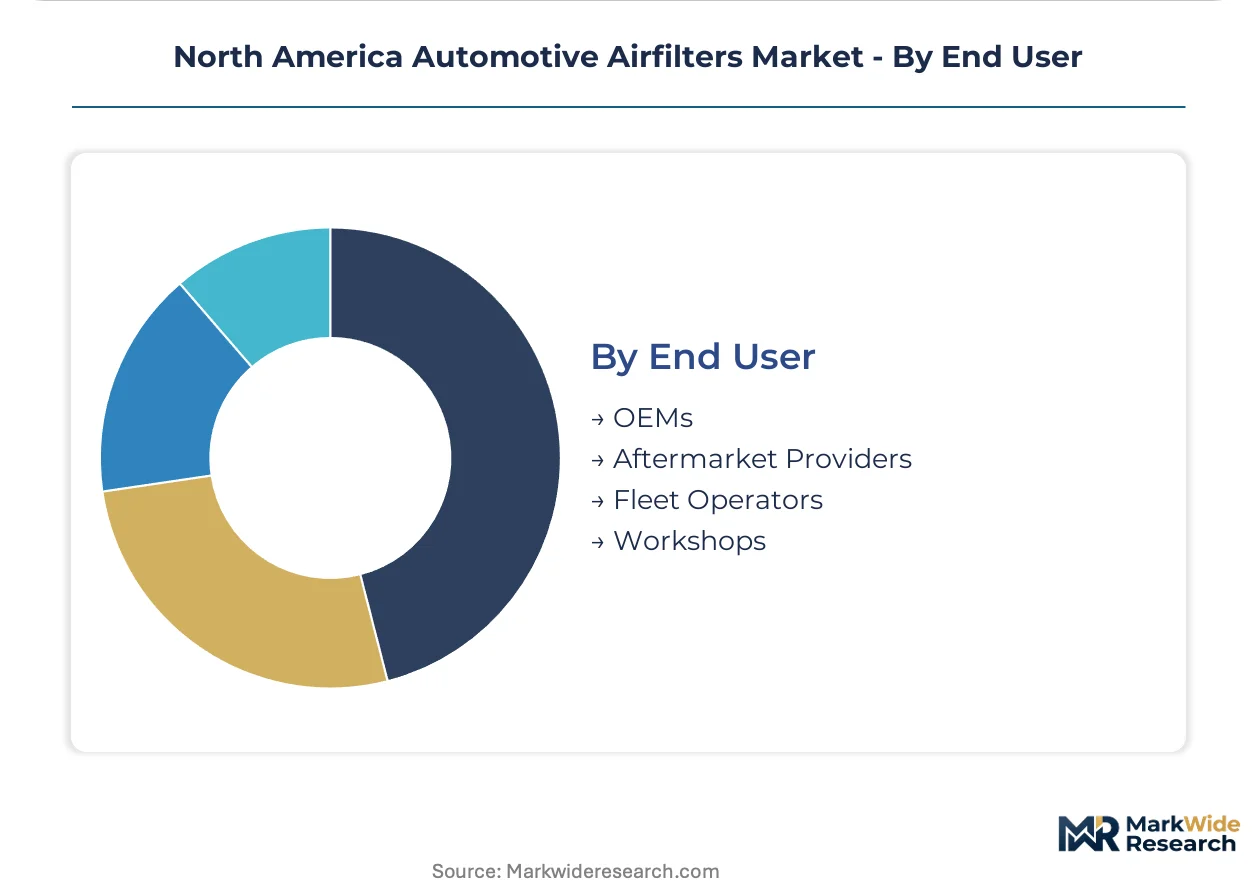
End User:
End-user category shapes contract structure, technical specification intensity, and inventory holding requirements, with fleet operators driving the most significant procurement pattern shifts.
- Fleet Operators:Heavy-duty commercial entities negotiating multi-year supply agreements with ISO 5011-qualified suppliers. United States and Canada federal decarbonization incentives are expanding addressable market for specialized filtration in battery electric trucks and buses.
- OEMs:Original equipment manufacturers integrating filters into vehicle assembly with zero-defect quality requirements. Detroit-based automakers require CARB pre-certification for entire product families rather than maintaining separate regional SKUs.
- Aftermarket Providers:Distributors and jobbers serving retail and installer channels with broad SKU coverage. This channel is losing share to direct fleet procurement models.
- Workshops:Independent service facilities and dealer service departments performing scheduled maintenance. Preventive maintenance schedule expansion is lifting filter attachment rates in commercial vehicle service bays.
OEMs anchor volume demand. Fleet operators are gaining share fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and OEM supply chains concentrate demand across three North American markets, with regulatory divergence between federal EPA standards and California Air Resources Board protocols creating distinct procurement zones.
United States
Commercial vehicle fleets along the I-75 corridor between Michigan and Florida are unbundling filter procurement from bundled service contracts. EPA tightened particulate matter standards are compelling manufacturers to redesign media compositions and validate against ISO 5011 protocols. Detroit-based automakers anchor OEM demand, requiring CARB pre-certification for entire product families.
Canada
Federal and provincial commercial vehicle decarbonization incentives are expanding addressable market for specialized filtration in battery electric trucks and buses. Health Canada and Environment and Climate Change Canada coordinate emission standards with EPA benchmarks while maintaining distinct verification requirements. Ontario's automotive manufacturing corridor spanning Windsor-Toronto supplies cross-border OEM assembly plants.
Mexico
Light truck production for export to US markets is driving panel filter demand across assembly operations in Nuevo León and Bajío Region. Mexican environmental regulator SEMARNAT aligns vehicle emission standards with EPA frameworks, creating regulatory continuity for suppliers. Manufacturing clusters in Guanajuato and Querétaro serve as low-cost production bases for fiberglass media destined for price-sensitive aftermarket channels.
North America Automotive Airfilters Market Competitive Landscape
Player mix skews toward vertically integrated media manufacturers and OEM-contracted specialists. The competitive structure bifurcates around ISO 5011 certification compliance, with qualified suppliers commanding pricing power in heavy-duty applications and marginal participants confined to undifferentiated aftermarket segments. Two strategic archetypes dominate: captive media producers controlling polymer feedstock-to-filter assembly chains, and OEM-anchored specialists securing multi-year supply agreements through zero-defect quality systems. Competitive moves concentrate on backward integration into synthetic fiber production and pre-certification of entire product families to CARB standards.
Within the vertically integrated tier, Donaldson Company exemplifies upstream control over media manufacturing, while MANN+HUMMEL anchors OEM-contracted positioning through Detroit automaker relationships. K&N Engineering occupies a distinct specialization niche in performance aftermarket applications. These three entities represent the dominant competitive archetypes: captive supply chain operators, OEM-anchored specialists, and performance-focused independents.
| Leading Market Players |
|---|
| Donaldson Company |
| MANN+HUMMEL |
| K&N Engineering |
| Parker-Hannifin Corporation |
| Cummins Inc. |
| ACDelco |
| Purolator Filters |
| DENSO Corporation |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
Capacity utilization above eighty percent across Michigan and Ontario synthetic fiber plants creates scale-driven pricing power for ISO 5011-certified suppliers while compressing margin recovery for marginal participants dependent on spot resin purchases. Fleet procurement centralization along the I-75 corridor reinforces this bifurcation, as volume-commitment contracts with index-linked petrochemical pricing displace transactional aftermarket purchasing.
Pricing Analysis
Cost-plus contracts with polypropylene and polyester indexation dominate heavy-duty fleet agreements, separating ISO 5011-certified suppliers from uncertified competitors through quality-grade premiums. Price differentiation hinges on CARB pre-certification status and synthetic fiber media composition, with fiberglass alternatives facing compression from moisture-resistance specifications. Pricing pressure intensifies in the passenger car aftermarket as direct-to-fleet procurement models bypass traditional jobber markups. Commercial vehicle operators show lowest price sensitivity due to total-cost-of-ownership calculations, while independent workshops face acute margin squeeze.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Detroit-based OEMs, while aftermarket distributors maintain strategic stockpiles of high-velocity panel filter SKUs to buffer against polymer feedstock volatility. Supply concentrates in Michigan, Ohio, and Ontario, with Mexican manufacturing clusters in Guanajuato and Querétaro serving price-sensitive fiberglass demand. Raw material dependencies center on polypropylene resin, polyester staple fiber, and activated carbon substrates. Single-source vulnerability runs through specialized nanofiber layering equipment. Distribution runs through ISO 5011-qualified direct procurement channels for fleets, with traditional jobber networks retreating to fragmented retail segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter replacement services and predictive maintenance subscriptions expand faster than hardware shipments, creating recurring-revenue layers that hardware-centric incumbents under-exploit. Smart monitoring integration with telematics platforms enables outcome-based service contracts that capture lifetime value beyond initial product margins.
For Market Incumbents: Consolidate backward into synthetic fiber production to secure margin control against petrochemical volatility, while locking multi-year CARB pre-certification cycles ahead of EPA particulate standard tightening. Threat substitution from nanofiber miniaturization demands R&D investment in compact media architectures. Channel control through direct fleet procurement relationships anchors pricing power against distributor disintermediation. For New Entrants and Emerging Players: Predictive maintenance software gaps in Class 8 truck fleets present white-space targeting for subscription-based filter monitoring services. Canadian battery electric bus procurement under federal decarbonization incentives offers the most penetrable geography for specialized HEPA cabin systems. Go-to-market execution should anchor on telematics platform partnerships rather than hardware-only distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated media manufacturers with captive polymer supply and ISO 5011 validation infrastructure. Long-term viability over a five-to-ten year horizon rests on CARB protocol alignment and electric vehicle cabin filtration specification capture. Signal to watch: California ZEV mandate acceleration triggering HEPA standardization across OEM supply agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Production | Captive polypropylene supply insulates margins from crude-linked resin volatility. |
| CARB Pre-Certification Investment | California protocols function as de facto North American benchmarks for OEM access. |
| Smart Filter Monitoring Platform Development | Pressure differential sensor integration enables predictive maintenance subscription models. |
| Direct Fleet Procurement Channel Establishment | Bypassing jobber networks captures volume commitment pricing along the I-75 corridor. |
| Nanofiber Media Architecture R&D | Compact designs free underhood space for battery thermal management in electric vehicles. |
Research Methodology
Desk research of EPA regulatory filings, vehicle production databases, and customs trade records preceded structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution executives, and fleet maintenance operations managers. Primary fieldwork combined telephone and in-person interviews across Michigan, Ohio, and Ontario manufacturing clusters. Secondary validation drew from NHTSA safety standards documentation, California Air Resources Board test protocols, and SEC filings from publicly traded filtration manufacturers. Bottom-up demand modeling triangulated against top-down market sizing from vehicle parc and replacement interval assumptions.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic automotive production forecasts. Industry-specific inputs incorporated EPA particulate standard implementation timelines and electric vehicle cabin filtration specification trajectories.
Underlying assumptions cover synthetic fiber adoption rates and fleet electrification penetration curves, with deviation risk concentrated in polymer feedstock price volatility and California ZEV mandate acceleration. Forecasts reflect these documented assumptions. Revision becomes warranted when EPA federal standards diverge from CARB benchmark stringency or when nanofiber media cost curves cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Cam Trigger Kits Market
Automotive Parts
Indonesia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fastener Market
Automotive Parts
Power Liftgate Market
Automotive Parts
Automotive Electric HVAC Compressor Market
Automotive Parts
Racing Motor Bike Seat Unit Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Small Engine Market
Automotive Parts
Global Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Air Suspension Systems Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Crankshaft Materials Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market