
 Global Beta Glucan Market | 2026-2036
Global Beta Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beta Glucan Market Analysis
Pharmaceutical-grade purity specifications is redrawing competitive boundaries across the beta glucan supply base. DSM Firmenich leverages its integrated fermentation infrastructure to secure consistent high-purity yeast-derived output. Kerry Group PLC anchors its position through backward integration into oat milling and extraction operations. Ceapro Inc. specializes in novel aqueous processing technology that preserves bioactive molecular weight profiles.
Beta glucans comprise a class of linear glucose polysaccharides linked by beta-glycosidic bonds, with molecular weight and branching patterns determining immunomodulatory potency and viscosity properties; manufacturers extract these compounds from yeast cell walls, fungal fruiting bodies, or cereal endosperm for use as functional ingredients in dietary supplements, clinical nutrition, and dermatological formulations. Yeast beta glucan commands the dominant revenue share owing to superior immune receptor activation data and established pharmaceutical validation, while oat beta glucan captures accelerating food and beverage penetration driven by cholesterol-reduction health claims approved in multiple jurisdictions. Mushroom beta glucan occupies a premium niche among adaptogenic supplement formulators seeking differentiation through polysaccharide diversity.
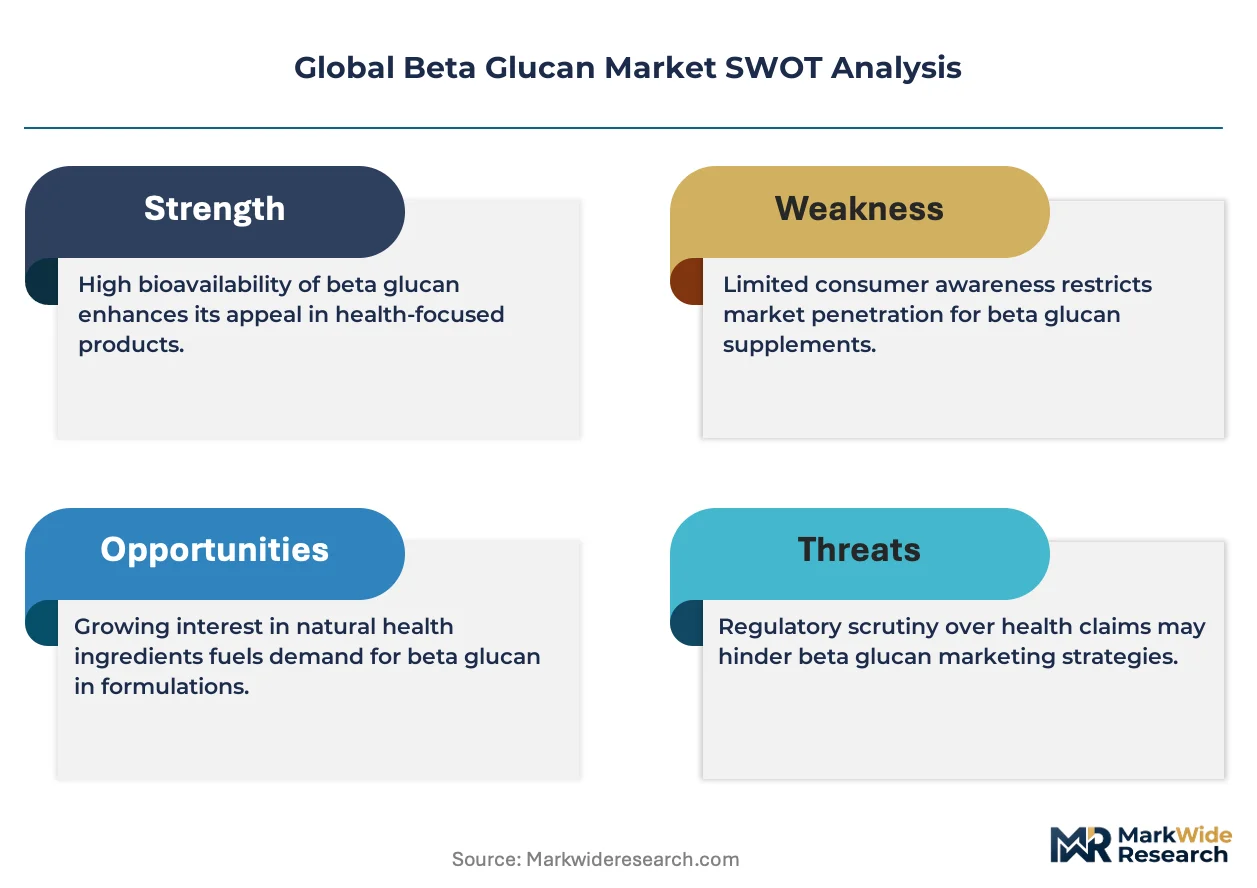
The FDA's GRAS program and the EFSA health claims framework jointly shape product positioning and substantiation requirements for beta glucan suppliers targeting regulated markets. ISO and FCC monographs provide analytical benchmarks for purity, molecular weight distribution, and endotoxin limits that determine qualification for pharmaceutical and injectable applications. Stakeholders must monitor evolving immunotherapy clinical trial pipelines and adaptogenic ingredient trend cycles to align capacity investments with demand trajectories.
Market Dynamics
Pharmaceutical-grade purity specifications are compressing margins for commodity-grade suppliers while rewarding integrated manufacturers with validated bioactive preservation technology. The FDA's GRAS notification pathway for novel dietary ingredients is accelerating qualification timelines for purified isolates, forcing legacy extraction operations to retool or exit.
Growth Catalysts
- Immunotherapy clinical validation:Yeast-derived beta glucan demonstrates superior Dectin-1 receptor activation in oncology adjuvant trials, pulling demand from research-grade into pharmaceutical procurement channels.
- EFSA Article 13.1 health claims:Approved cholesterol-reduction claims for oat beta glucan at 3g daily intake are driving reformulation in European functional food and beverage applications.
- Clean-label formulation mandates:United States CPG brands are substituting synthetic immunomodulators with plant-derived beta glucan to meet retailer clean-ingredient specifications.
Market Restraints
- Oat supply concentration:Nordic and Canadian milling operations control premium beta glucan feedstock, exposing formulators to crop yield volatility and protein co-product pricing swings.
- Endotoxin specification escalation:Injectable-grade applications now demand <0.5 EU/g endotoxin limits, requiring capital-intensive chromatographic purification that excludes smaller extraction houses.
- Polysaccharide substitution:Fucoidan and arabinogalactan suppliers are targeting immune-positioned supplement slots with comparable receptor-binding claims at lower input costs.
Strategic Opportunities
- Adaptogenic beverage white space:Mushroom beta glucan from reishi and maitake fruiting bodies commands premium positioning in functional RTD formats targeting stress-modulation claims.
- Indian nutraceutical manufacturing:FSSAI's streamlined novel food ingredient notifications and PLI scheme incentives are attracting toll extraction capacity for export-oriented yeast beta glucan production.
- Dermatological delivery systems:Nano-encapsulation convergence with transdermal penetration enhancers is opening cosmetic applications previously blocked by molecular weight bioavailability constraints.
Industry Challenges
- Biomarker standardization gaps:Lack of harmonized analytical methods for molecular weight distribution and triple-helix content creates batch-to-batch variability disputes between suppliers and pharmaceutical buyers.
- Fermentation scale-up bottlenecks:Pharmaceutical-grade yeast cell wall processing requires GMP-validated bioreactor infrastructure that demands 18-24 month qualification timelines and specialized clean-room engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beta Glucan Market |
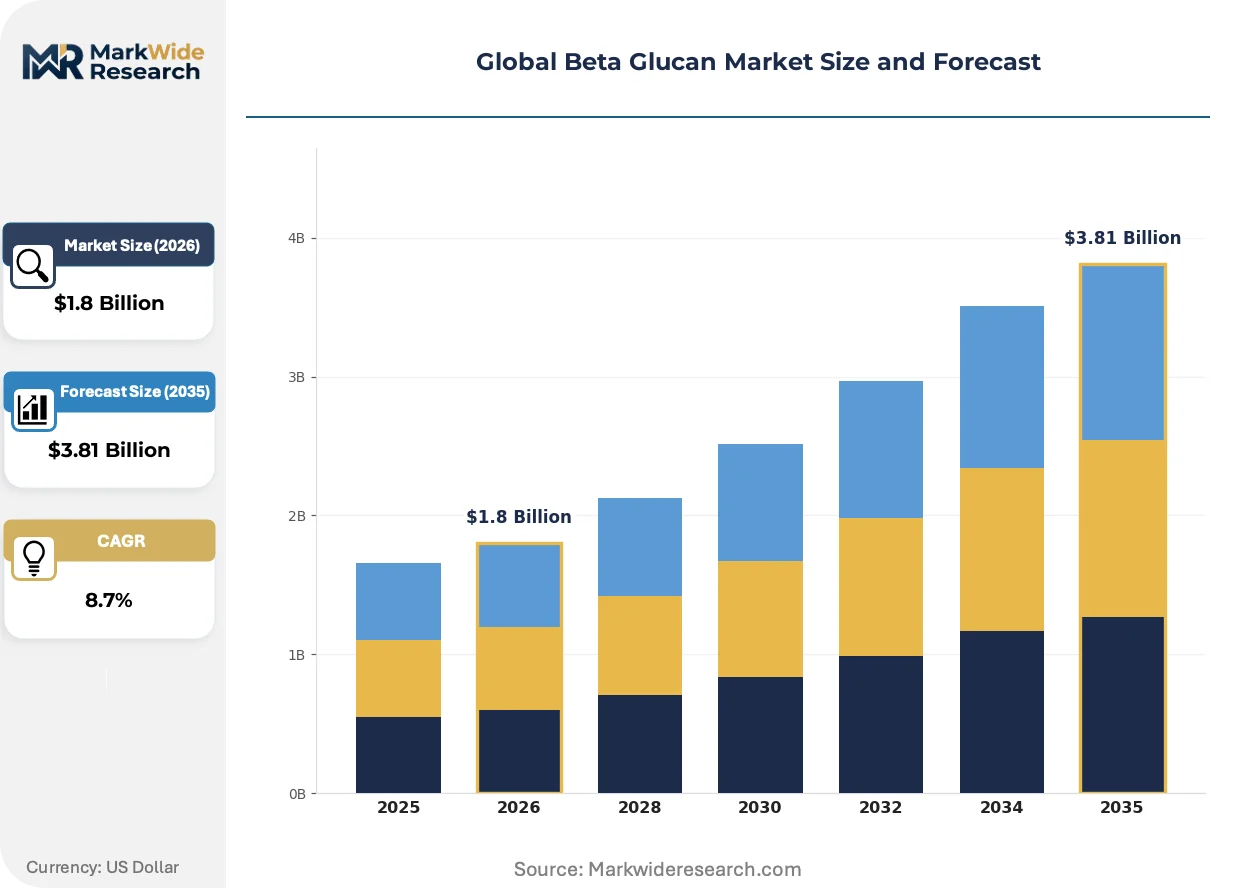
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Beta Glucan, Mushroom Beta Glucan, Oat Beta Glucan, Barley Beta Glucan Application: Nutraceuticals, Food & Beverages, Pharmaceuticals, Personal Care End User: Healthcare Providers, Food Manufacturers, Cosmetic Companies, Research Institutions Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Merck, Lesaffre, Kerry Group PLC, Garuda International, Ceapro Inc., Tate & Lyle PLC, Kemin Industries, Lallemand Inc., DSM Firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beta Glucan Market Emerging Trajectories
Extraction technology is fragmenting the competitive map as aqueous processing methods challenge solvent-based legacy systems. Bioactive preservation and sustainability credentials are becoming primary selection criteria ahead of unit cost.
Novel aqueous extraction technology is decomposing the historical dominance of alkaline and solvent-based methods that degraded molecular weight profiles. Nutraceutical contract manufacturers in Germany and California are adopting continuous-flow aqueous systems at pilot scale. This shift is compressing qualification timelines for pharmaceutical-grade supply while raising barriers for facilities lacking validated bioactive preservation protocols.
REACH registration requirements for novel polysaccharide derivatives are forcing European suppliers to consolidate substance identity dossiers ahead of 2026 deadlines. The industrial consequence is accelerated phase-out of undefined "beta glucan complex" formulations in favor of characterized isolates with documented monosaccharide ratios. Dietary supplement brands targeting EU distribution are reformulating with registered substances to avoid downstream liability exposure.
Direct-procurement relationships between finished goods manufacturers and extraction facilities are displacing traditional ingredient distributor intermediaries. Supplement brands with annual volumes exceeding 10 metric tons are negotiating captive offtake agreements with yeast fermentation houses in Iowa and Bavaria. This pattern is most visible in United States immune-health positioning segments where supply security and lot traceability outweigh spot-market price advantages.
Global Beta Glucan Market Segmentation
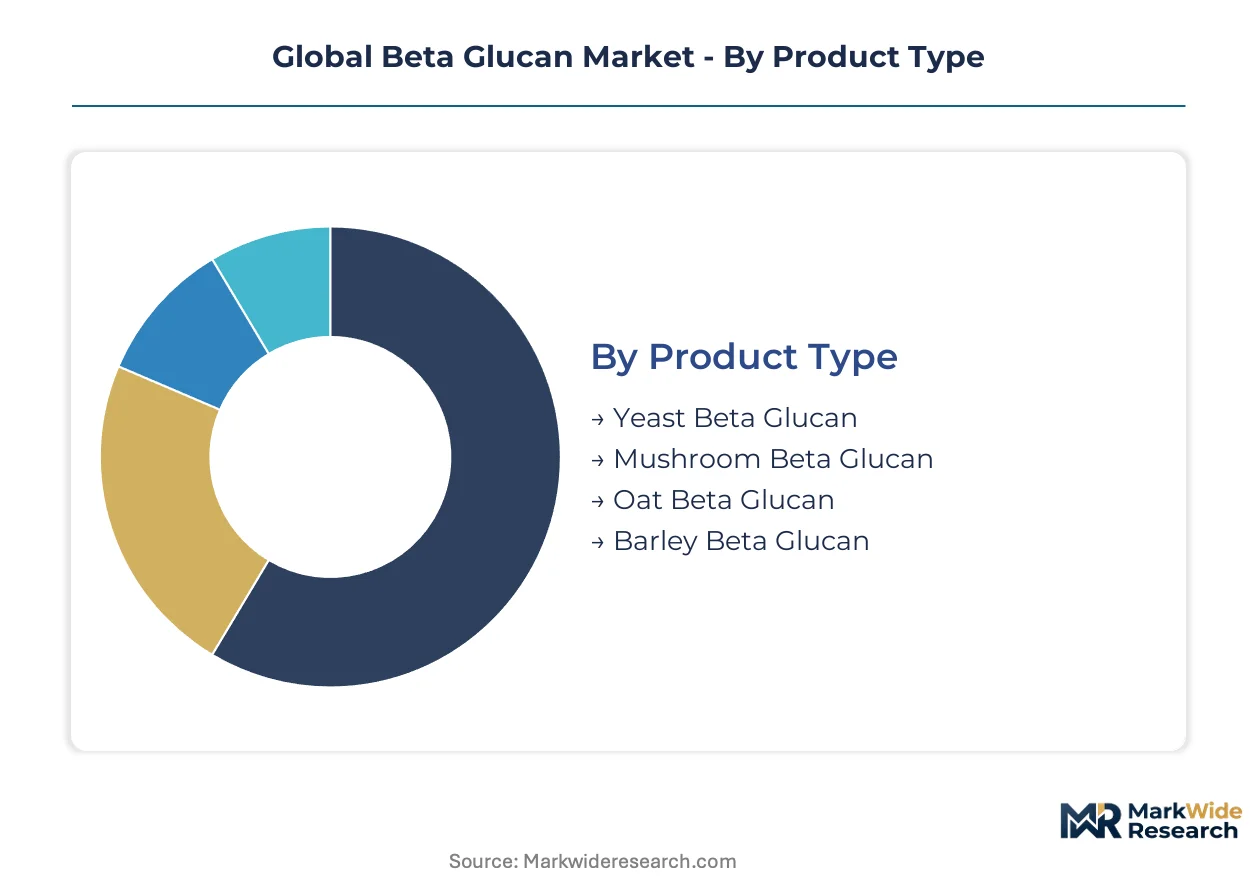
Beta glucan suppliers configure their extraction and purification investments around distinct margin architectures across product types, applications, and procurement channels. Understanding where value concentrates within each dimension determines portfolio prioritization for ingredient manufacturers and formulation partners.
Product Type:
Premium pricing pools sit with pharmaceutical-grade isolates where endotoxin specifications and molecular weight validation command 3-5x commodity premia.
- Yeast Beta Glucan:Derived from Saccharomyces cerevisiae cell walls through alkaline or aqueous extraction, this segment carries validated Dectin-1 receptor activation data that supports oncology adjuvant positioning. Demand concentrates in United States pharmaceutical procurement channels where FDA GRAS notifications and injectable-grade specifications drive supplier qualification.
- Oat Beta Glucan:Extracted from oat endosperm as mixed-linkage (1,3)(1,4)-β-D-glucan, this segment leverages EFSA-approved cholesterol reduction claims at 3g daily intake thresholds. European functional food reformulation and United States clean-label mandates are pulling volume into beverage and bakery applications.
- Mushroom Beta Glucan:Fruiting body polysaccharides from reishi, maitake, and shiitake sources occupy adaptogenic supplement niches with premium positioning.
- Barley Beta Glucan:Cereal-derived extracts share structural similarities with oat beta glucan but face narrower health claim substantiation and limited supplier scale.
The dominant share belongs to Yeast Beta Glucan, while Oat Beta Glucan is closing the gap fastest.
Application:
Volume flows correlate inversely with specification intensity, with food-grade applications scaling fastest and pharmaceutical contracts delivering sustained margin stability.
- Nutraceuticals:Dietary supplement formulations represent the primary demand channel for immune-positioned beta glucan, spanning capsules, powders, and functional gummies. United States brands are substituting synthetic immunomodulators with yeast-derived alternatives to meet retailer clean-ingredient specifications.
- Pharmaceuticals:Clinical nutrition and injectable applications demand GMP-validated production with documented endotoxin limits below 0.5 EU/g.
- Food & Beverages:Cholesterol-reduction positioning in European markets and fiber fortification in bakery applications drive oat beta glucan incorporation.
- Personal Care:Dermatological formulations exploit nano-encapsulation advances to overcome molecular weight bioavailability constraints in transdermal delivery.
Nutraceuticals commands the largest volume position, though Pharmaceuticals delivers the highest per-kilogram realization.
End User:
Procurement sophistication varies sharply across buyer categories, with healthcare providers demanding batch-level analytical documentation and food manufacturers prioritizing cost-stable supply contracts.
- Healthcare Providers:Hospitals and clinical nutrition services source pharmaceutical-grade isolates with full chain-of-custody documentation for parenteral and enteral applications.
- Food Manufacturers:CPG brands in Germany, California, and Iowa negotiate multi-year offtake agreements with integrated oat millers and yeast fermentation houses.
- Cosmetic Companies:Formulators in South Korea and France are piloting nano-encapsulated mushroom beta glucan for anti-inflammatory skin care positioning.
- Research Institutions:Academic and contract research organizations procure research-grade material for immunotherapy and mechanistic studies.
Food Manufacturers absorb the greatest tonnage, while Healthcare Providers are expanding specification requirements most aggressively.
Distribution Channel:
Direct procurement relationships are displacing traditional distributor intermediaries above 10 metric ton annual volumes, compressing channel margins for spot-market players.
- Online Retail:E-commerce platforms serve small-scale nutraceutical brands and direct-to-consumer supplement marketers with minimum order quantities below distributor thresholds.
- Supermarkets:Mass retail chains in the United States and Germany stock functional foods with front-of-pack beta glucan claims.
- Pharmacies:Drugstore channels in Japan and Switzerland carry clinical nutrition and dermatological formulations with pharmacist-assisted positioning.
- Specialty Stores:Health food retailers and adaptogenic-focused boutiques in California and British Columbia curate mushroom beta glucan SKUs.
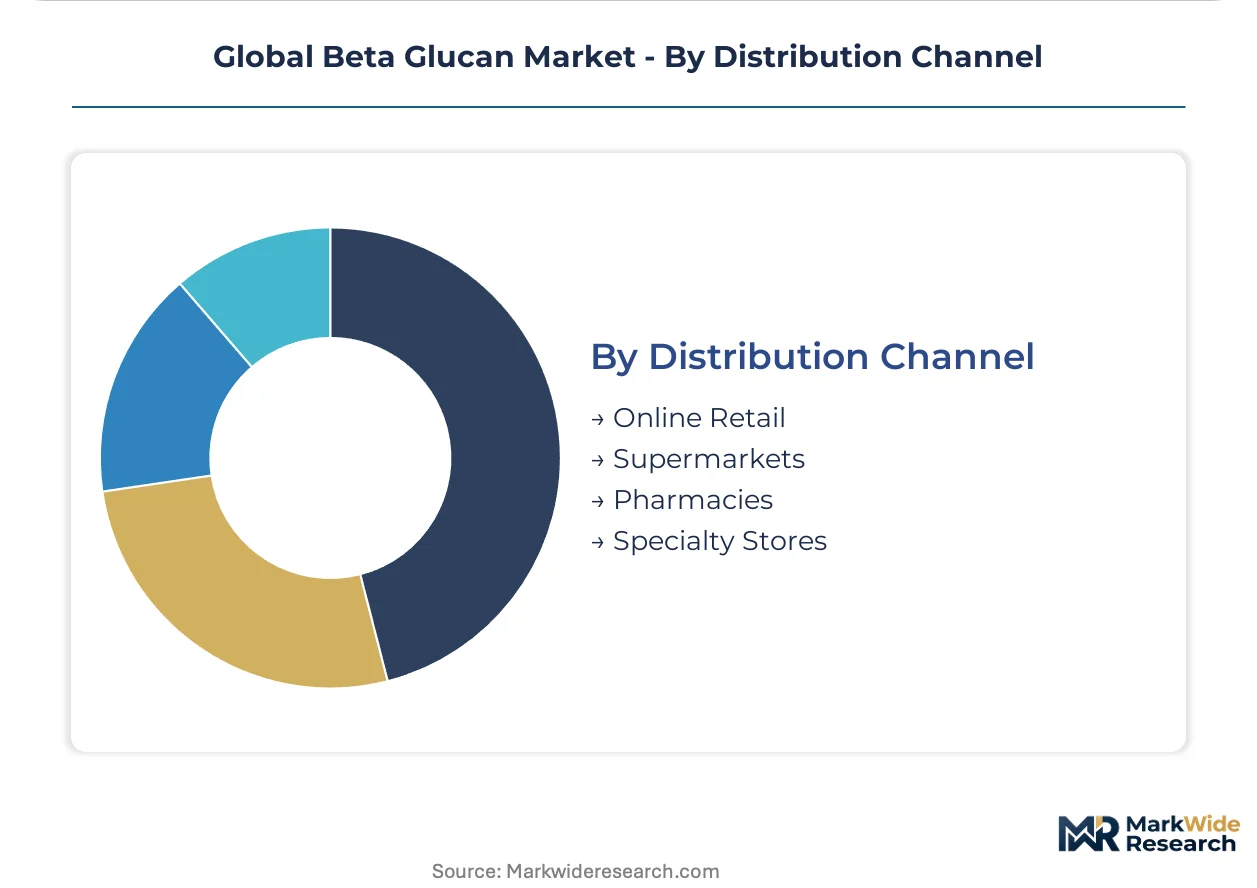
Supermarkets and Pharmacies together represent the largest revenue channel, though Online Retail is expanding most quickly among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yeast fermentation capacity clusters in the United States and Germany, while oat milling operations concentrate in Nordic regions and Canada. Regulatory divergence between FDA GRAS pathways and EFSA health claim frameworks creates distinct qualification requirements across jurisdictions.
United States
Clean-label formulation mandates from major retailers are pulling yeast beta glucan into immune-positioned supplements and functional beverages. The FDA's GRAS notification pathway accelerates novel ingredient qualification timelines. Iowa and California host integrated fermentation and extraction facilities serving pharmaceutical procurement channels.
Germany
EFSA-approved cholesterol reduction claims drive oat beta glucan incorporation into bakery and beverage applications. REACH registration requirements for polysaccharide derivatives are consolidating substance identity dossiers ahead of deadlines. Bavaria anchors aqueous extraction technology adoption among contract manufacturers.
India
FSSAI's streamlined novel food ingredient notifications are attracting toll extraction capacity for export-oriented production. The PLI scheme incentivizes pharmaceutical-grade fermentation infrastructure investment. Maharashtra and Gujarat house emerging GMP-validated facilities targeting United States and European export markets.
Canada
Premium oat beta glucan feedstock supply concentrates in Prairie Provinces milling operations. Health Canada and PMRA frameworks govern natural health product licensing for immune-positioned supplements. Saskatchewan and Manitoba face crop yield volatility exposure affecting protein co-product pricing dynamics.
Japan
Pharmacist-assisted positioning in drugstore channels supports clinical nutrition and dermatological beta glucan formulations. METI standards and PMDA oversight govern injectable-grade specifications for enteral applications. Kanto region formulation houses pilot nano-encapsulation advances for transdermal delivery systems.
Global Beta Glucan Market Vendor Landscape
Concentration sits with integrated fermentation specialists and backward-integrated cereal processors. The supply base stratifies across three tiers: pharmaceutical-grade isolates commanding premium realizations, food-grade commodity suppliers facing margin compression, and adaptogenic niche players targeting supplement differentiation. Dominant competitive moves include captive offtake agreements above ten metric ton annual volumes and aqueous extraction technology licensing to preserve bioactive molecular weight profiles.
Among diversified ingredient conglomerates, DSM Firmenich and Kerry Group PLC exemplify integrated archetypes spanning fermentation infrastructure and oat milling operations. Ceapro Inc. occupies a specialist position in novel aqueous processing technology. These three entities represent distinct strategic postures: multinational scale with validated GMP capacity, backward-integrated cereal extraction control, and proprietary bioactive preservation methods respectively.
| Leading Market Players |
|---|
| Merck |
| Lesaffre |
| Kerry Group PLC |
| Garuda International |
| Ceapro Inc. |
| Tate & Lyle PLC |
| Kemin Industries |
| Lallemand Inc. |
| DSM Firmenich |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between United States nutraceutical brands and Iowa fermentation houses lock in both supply access and price visibility for pharmaceutical-grade yeast beta glucan, insulating qualified suppliers from spot-market volatility while exposing non-integrated extractors to margin compression.
Pricing Analysis
FDA GRAS notification requirements dictate the pricing tier structure across the beta glucan market, separating validated isolates with documented endotoxin limits from undefined complexes. Three-tier pricing structure across pharmaceutical, food-grade, and commodity levels reflects certification burden and molecular weight validation intensity. Cost compression in commodity-grade segments is intensifying because REACH registration deadlines force reformulation costs onto smaller suppliers. Food manufacturers exhibit highest price sensitivity due to volume scale and substitution flexibility, while healthcare providers prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of premium oat feedstock dominates inventory strategy among Nordic and Canadian millers facing crop yield volatility, whereas just-in-time procurement prevails in yeast fermentation where GMP-validated bioreactor output is contract-committed before production. Supply concentrates in the United States, Germany, and Canada for yeast fermentation and oat milling respectively. Raw material flows draw from Saccharomyces cerevisiae cultivation, oat endosperm, and reishi fruiting bodies. Single-source vulnerability sits with Nordic beta glucan feedstock given protein co-product pricing swings. Distribution runs through direct procurement relationships above ten metric ton thresholds, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs the beta glucan market as direct-procurement relationships between finished goods manufacturers and extraction facilities displace distributor intermediaries, creating winner-take-most dynamics around validated bioactive preservation protocols and captive offtake scale.
For Market Incumbents: Consolidate fermentation capacity in Iowa and Bavaria through captive offtake agreements above ten metric ton annual volumes to defend against polysaccharide substitution threats from fucoidan and arabinogalactan suppliers. Deepen backward integration into oat milling operations to secure premium feedstock access amid Nordic crop volatility. Prioritize aqueous extraction technology licensing to preserve bioactive molecular weight profiles as a differentiation barrier. For New Entrants and Emerging Players: Lead with adaptogenic beverage white space in functional RTD formats targeting stress-modulation claims, where mushroom beta glucan from reishi and maitake commands premium positioning absent entrenched supplier relationships. Target Indian toll extraction capacity under FSSAI's streamlined novel food ingredient notifications as a low-capital entry vector. Deploy nano-encapsulation expertise as a go-to-market angle for dermatological applications previously blocked by molecular weight constraints. For Investors and Strategic Acquirers: GMP-validated aqueous processing specialists with proprietary bioactive preservation protocols represent the most defensible acquisition targets given eighteen-to-twenty-four month qualification timelines that exclude greenfield competition. Long-term viability hinges on alignment with immunotherapy clinical validation pipelines and adaptogenic ingredient trend cycles. Watch endotoxin specification escalation below 0.5 EU/g as the inflection signal separating pharmaceutical-grade realizations from commodity margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Milling | Kerry Group PLC's upstream control secures premium feedstock access amid Nordic supply volatility. |
| Aqueous Extraction Technology Licensing | Ceapro Inc.'s novel processing preserves bioactive molecular weight profiles for pharmaceutical qualification. |
| Captive Offtake Agreements | Direct procurement relationships above ten metric tons displace distributor intermediaries in United States immune-health segments. |
| GMP-Validated Fermentation Scale-Up | DSM Firmenich's integrated infrastructure meets FDA injectable-grade specifications with documented endotoxin limits. |
| REACH Registration Consolidation | European suppliers phase out undefined beta glucan complexes ahead of 2026 substance identity deadlines. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, spanning nutraceutical formulation scientists, pharmaceutical procurement managers, oat milling operations directors, fermentation facility engineers, and dietary supplement brand managers. Secondary validation incorporated FDA GRAS notification databases, EFSA health claim registers, ISO monograph specifications, customs trade flow records, and SEC filings from diversified ingredient conglomerates. Bottom-up volume modeling triangulated against top-down value projections to ensure segmentation coherence.
Across the analysis window, the forecast framework applied product type, application, and procurement channel dimensions to capture margin architecture variation between pharmaceutical-grade isolates and commodity-grade supplies. CAGRs derived from regression analysis of historical qualification timelines and demand trajectory alignment with immunotherapy clinical pipelines. Industry-specific inputs included EFSA Article 13.1 claim utilization rates and FDA novel dietary ingredient notification velocities.
The analysis sits within stated boundaries; outcomes outside sustained EFSA health claim enforcement and FDA GRAS pathway stability would require recalibration. Forecasts reflect assumptions regarding endotoxin specification trajectories and adaptogenic ingredient trend persistence. Practitioners should keep alternative scenarios live as REACH registration deadlines and polysaccharide substitution threats evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
EPA and DHA Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
South America Meal Replacement Products Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market