
 Asia-Pacific Collagen Peptide Products Market | 2026-2036
Asia-Pacific Collagen Peptide Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Collagen Peptide Products Market Outlook
Cosmetic applications are broadening within the end-use mix as skin-health positioning migrates from niche dermatology clinics to mass retail channels across the region. Gelita AG leverages its German technical heritage to dominate pharmaceutical-grade peptide supply chains in Japan and Australia. Nestlé sustains brand authority through integrated nutrition platforms that bundle collagen with vitamin complexes in China and Southeast Asia.
Collagen peptide products comprise short-chain amino acid sequences derived from enzymatic hydrolysis of bovine, porcine, or marine collagen, typically achieving molecular weights below 10 kDa for enhanced bioavailability in human absorption. These inputs serve primarily as functional ingredients in ingestible wellness formulations and topical cosmetic preparations where protein integrity dictates performance claims. Hydrolyzed collagen occupies the largest volume share across the product type spectrum, while collagen powder commands premium positioning in direct-to-consumer channels due to formulation flexibility and clean-label compatibility. Nutritional supplements generate the fastest value expansion among applications, driven by sports nutrition adoption in Australia and geriatric protein fortification in South Korea.
Japan's Ministry of Health, Labour and Welfare maintains strict FOSHU approval pathways for collagen-bearing functional foods, elevating compliance costs but rewarding certified entrants with pharmacy channel access. China's SAMR and India's FSSAI impose divergent labeling and origin requirements that fragment cross-border formulation strategies. Stakeholders must monitor regulatory harmonization talks between ASEAN member states, as mutual recognition agreements would reshape manufacturing location decisions and regional sourcing footprints.
Market Dynamics
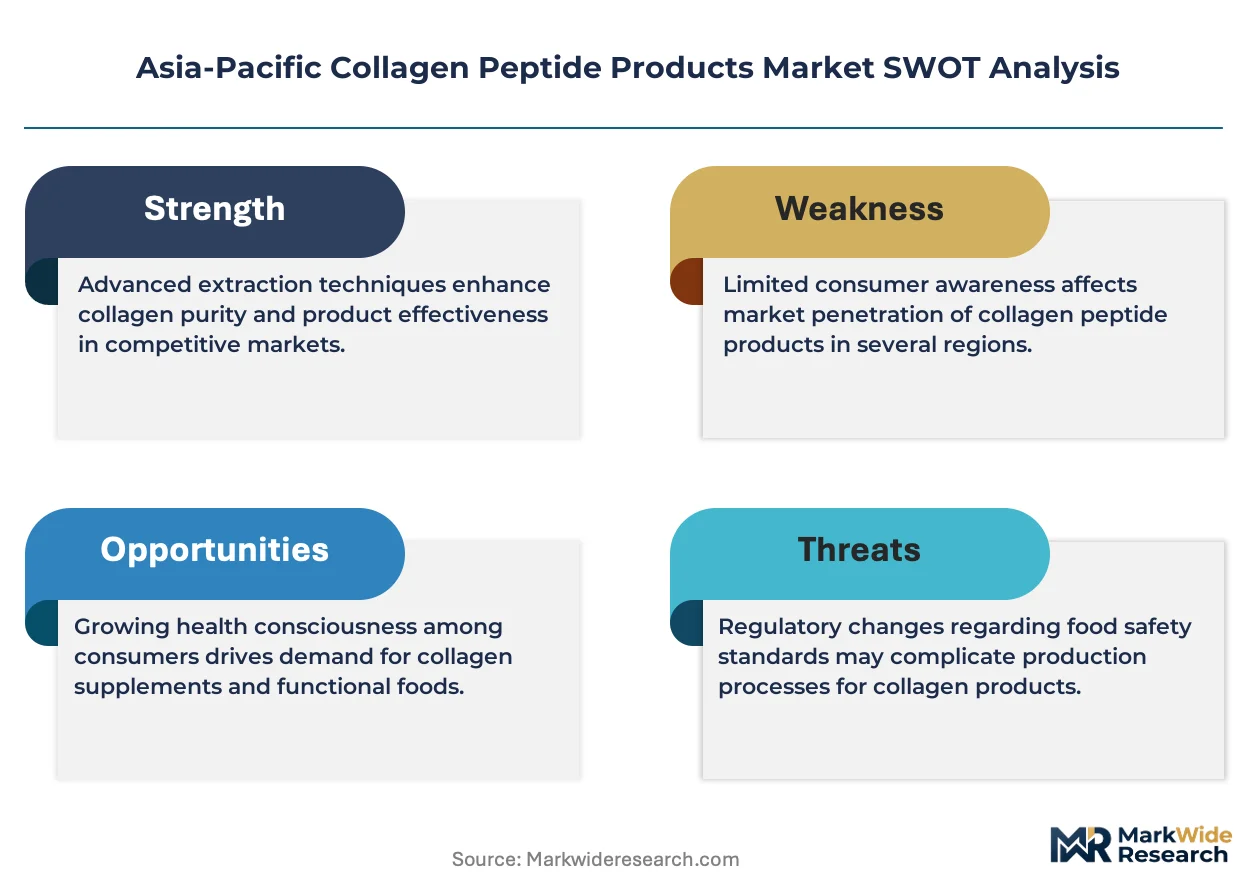
China's SAMR tightened functional food registration rules are forcing manufacturers toward clinical substantiation, compressing formulation cycles and elevating R&D spend across the Asia-Pacific region. This regulatory pivot is reshaping competitive positioning by rewarding certified entrants with pharmacy channel access while marginalizing legacy supplement brands.
Growth Catalysts
- Aging demographics in Japan and South Korea:Geriatric protein fortification demand accelerates nutritional supplement adoption among consumers over 65, expanding the addressable base for collagen peptide formulations.
- FOSHU approval pathways:Japan's Ministry of Health, Labour and Welfare certification rewards compliant manufacturers with privileged pharmacy distribution, creating structural incentives for quality investment.
- Marine collagen enzymatic hydrolysis:Advances in molecular weight reduction below 10 kDa enhance bioavailability claims, opening premium positioning in direct-to-consumer powder formats.
Market Restraints
- Bovine collagen origin restrictions:India's FSSAI labeling requirements and religious dietary laws fragment cross-border sourcing strategies, forcing parallel supply chain configurations.
- Marine raw material concentration:Wild-caught fish skin and scale supply concentrates in Southeast Asian coastal zones, exposing processors to climate-induced catch volatility.
- Clinical substantiation costs:China's National Health Commission mandates human trials for functional claims, elevating barrier-to-entry for mid-tier domestic brands.
Strategic Opportunities
- India's metropolitan corridors:Tier-one cities Mumbai, Delhi, and Bangalore exhibit faster premium wellness brand shelf space acquisition than secondary markets, signaling white-space expansion potential.
- ASEAN mutual recognition agreements:Ongoing regulatory harmonization talks between member states would enable centralized manufacturing with cross-border label equivalence, reducing compliance duplication.
- Topical cosmetic migration:Skin-health positioning is shifting from dermatology clinics to mass retail channels across Thailand and Vietnam, creating new distribution partnerships for peptide suppliers.
Industry Challenges
- Peptide characterization expertise:Shortage of analytical chemists proficient in amino acid sequencing and molecular weight verification slows product development timelines for regional manufacturers.
- Dual certification complexity:Brands targeting both Japan's FOSHU and China's Blue Hat registrations face divergent documentation standards, stretching regulatory affairs capacity.
- Legacy ERP integration:Batch traceability requirements for enzymatic hydrolysis processes strain older manufacturing execution systems, necessitating costly software upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Collagen Peptide Products Market |
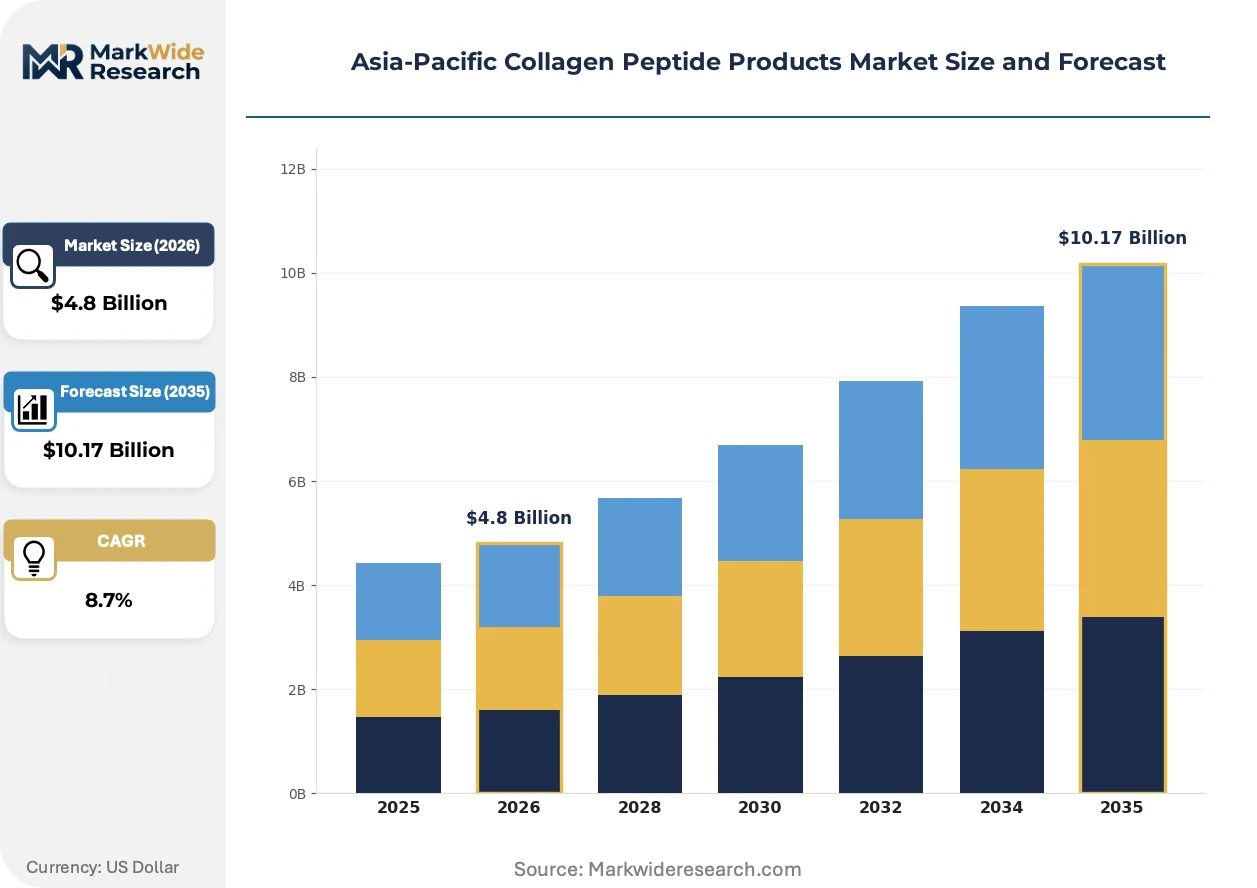
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptide, Collagen Powder Application: Nutritional Supplements, Food & Beverage, Cosmetics, Pharmaceuticals Form: Powder, Liquid, Capsule, Tablet End User: Health-Conscious Consumers, Athletes, Elderly, Cosmetic Manufacturers |
| Companies Covered | Nestlé, Gelita AG, Nitta Gelatin, Inc., Rousselot, Vital Proteins LLC, Tessenderlo Group NV, Vitalitown, Forest Leaf, Primal Harvest, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Collagen Peptide Products Market Strategic Shifts
Enzymatic precision and bioavailability science are compressing product development cycles while elevating performance claims. Formulation flexibility now determines channel access across the Asia-Pacific wellness landscape.
Precision enzymatic hydrolysis is electrifying collagen peptide manufacturing by enabling targeted molecular weight distributions. Sports nutrition brands in Australia and geriatric supplement marketers in South Korea are adopting these inputs at accelerated procurement cadences. This technology is compressing the gap between pharmaceutical-grade and food-grade specifications, forcing mid-tier suppliers to upgrade facilities or exit premium segments.
China's SAMR functional food registration reforms are elevating clinical substantiation requirements for collagen-bearing products. Manufacturers must now submit human trial data for absorption and efficacy claims, industrializing the R&D function within domestic firms. Nutritional supplement categories targeting tier-one urban consumers face the steepest compliance ramps, with several brands accelerating partnerships with contract research organizations.
Direct-to-consumer powder formats are displacing traditional capsule and tablet configurations among Asia-Pacific wellness purchasers. E-commerce platforms and subscription models in China's tier-one cities and India's metropolitan corridors are capturing share from pharmacy and mass retail channels. This channel rotation is most visible in premium positioning segments where clean-label compatibility and formulation flexibility drive repeat purchase behavior.
Asia-Pacific Collagen Peptide Products Market Segmentation
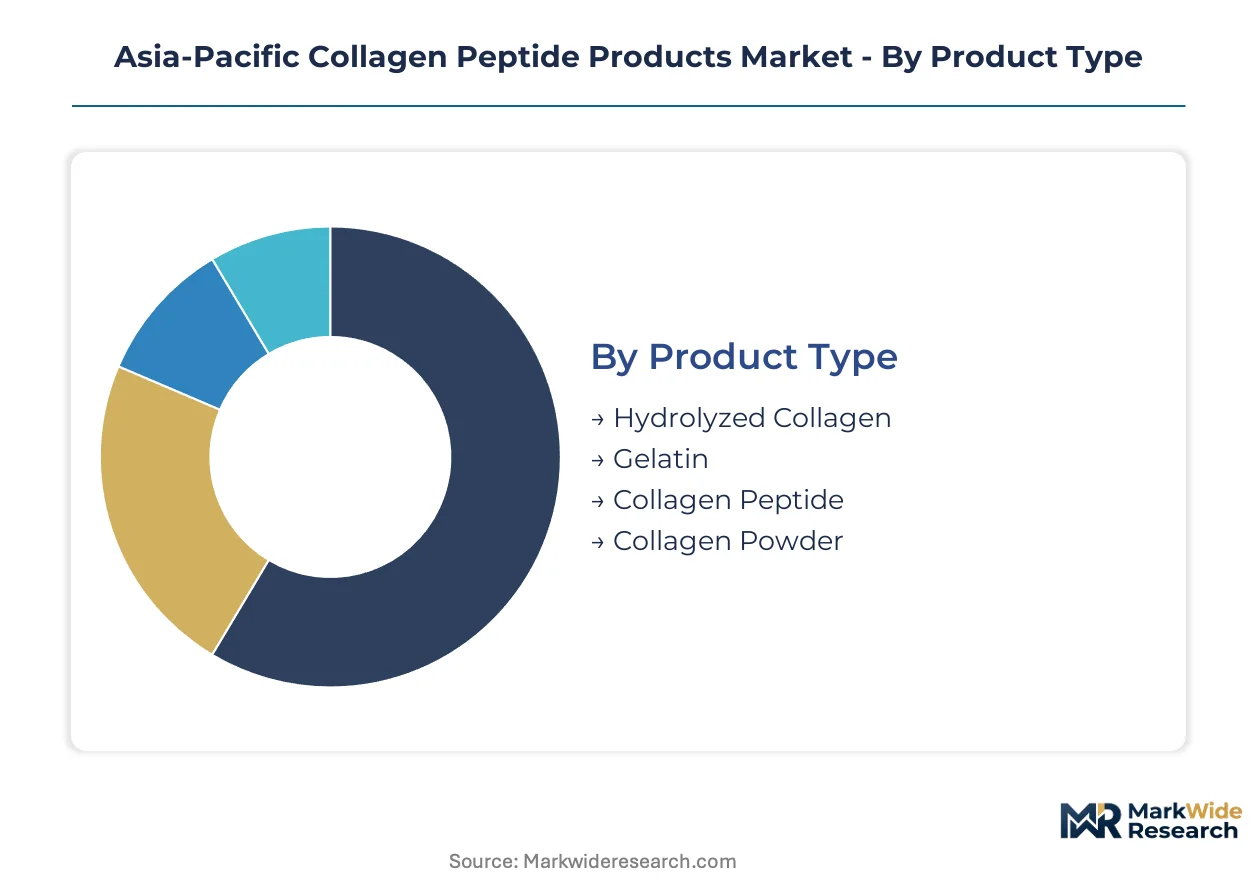
Segmentation in the Asia-Pacific collagen peptide market reveals how enzymatic precision, regulatory certification, and channel strategy fragment commercial opportunity. Manufacturers must align product architecture with Japan's FOSHU pathways, China's SAMR functional food tiers, and India's FSSAI origin requirements to capture shelf space.
Product Type:
Standardization dominates commodity-grade outputs while enzymatic customization commands premium positioning in pharmacy and direct-to-consumer channels across the region.
- Hydrolyzed Collagen:Achieves molecular weights below 10 kDa through controlled enzymatic hydrolysis of bovine, porcine, or marine substrates. Demand concentrates in China's tier-one cities where SAMR-compliant manufacturers secure pharmacy distribution through clinical substantiation investments.
- Collagen Powder:Offers formulation flexibility for sports nutrition brands in Australia and geriatric fortification marketers in South Korea. Clean-label compatibility drives repeat purchase behavior in subscription e-commerce channels across India's metropolitan corridors.
- Gelatin:Serves food-grade applications with higher molecular weight distributions and gelling functionality.
- Collagen Peptide:Targets pharmaceutical-grade specifications with batch-traceable enzymatic processes.
Gaining share fastest: Collagen Powder. Leading by volume: Hydrolyzed Collagen.
Application:
Channel migration from dermatology clinics to mass retail reshapes margin structures across end-use categories.
- Nutritional Supplements:Geriatric protein fortification in Japan and South Korea accelerates procurement from certified FOSHU manufacturers. Australia's sports nutrition brands adopt precision-hydrolyzed inputs at elevated procurement cadences.
- Cosmetics:Skin-health positioning shifts from niche dermatology to mass retail in Thailand and Vietnam. Topical peptide demand concentrates among cosmetic manufacturers seeking bioavailability claims for anti-aging formulations.
- Food & Beverage:Functional food integration requires SAMR registration in China and FSSAI compliance in India.
- Pharmaceuticals:Pharmaceutical-grade supply chains demand molecular weight verification and amino acid sequencing documentation.
Expanding most quickly: Nutritional Supplements. Dominant by revenue: Cosmetics.
Form:
Format selection determines channel access and compliance burden across divergent regulatory environments.
- Powder:Direct-to-consumer formats displace traditional configurations in China's tier-one cities and India's metropolitan corridors. Subscription models capture share from pharmacy channels where clean-label positioning drives loyalty.
- Liquid:Ready-to-drink formulations target convenience-seeking health-conscious consumers in Japan's convenience retail network.
- Capsule:Standardized dosing appeals to elderly consumers in South Korea's pharmacy channel.
- Tablet:Compression manufacturing suits high-volume nutritional supplement production for mass retail.
Climbing the fastest: Powder. Holding volume leadership: Capsule.
End User:
User archetypes dictate specification requirements from pharmaceutical-grade purity to mass-market accessibility.
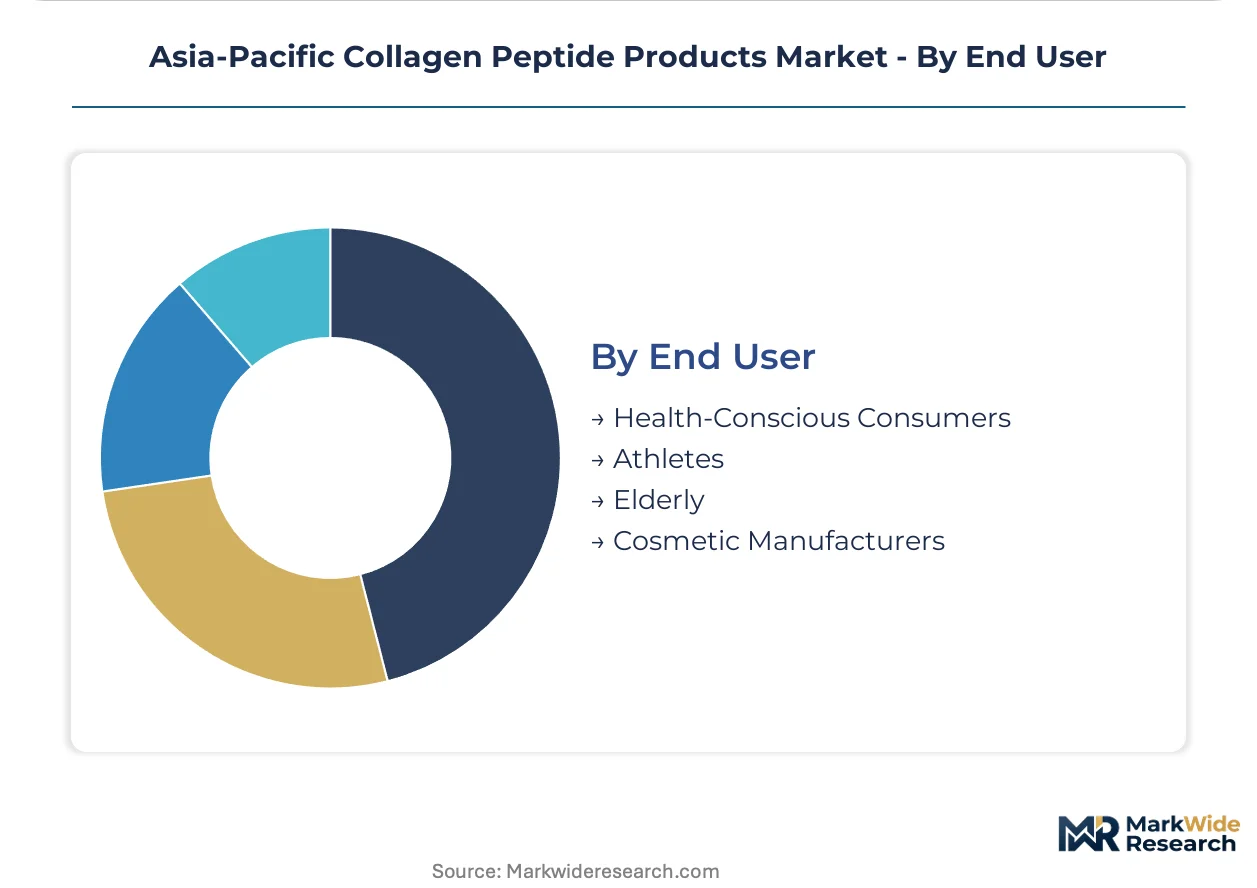
- Health-Conscious Consumers:Tier-one urban purchasers in China and India prioritize clean-label compatibility and formulation flexibility. E-commerce platforms enable subscription retention through personalized dosing protocols.
- Elderly:Geriatric protein fortification demand in Japan and South Korea requires FOSHU-certified manufacturers with pharmacy channel relationships. Absorption-optimized molecular weights below 10 kDa substantiate efficacy claims for aging digestive systems.
- Athletes:Sports nutrition adoption in Australia drives procurement of rapid-absorption peptide formats.
- Cosmetic Manufacturers:B2B purchasers require batch consistency and amino acid profiling for topical formulation stability.
Steepest expansion trajectory: Health-Conscious Consumers. Largest addressable base: Elderly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives are drawing collagen peptide manufacturers toward duty-free processing zones, concentrating enzymatic hydrolysis capacity in southern coastal clusters.
China
Functional food demand concentrates in Shanghai, Beijing, and Shenzhen where SAMR-compliant manufacturers secure pharmacy distribution through clinical substantiation investments. China's National Health Commission tightened registration rules for collagen-bearing supplements, mandating human trial data for absorption claims. Yangtze River Delta processors dominate pharmaceutical-grade peptide supply, serving both domestic geriatric fortification and export markets.
Japan
Geriatric protein fortification drives nutritional supplement procurement among consumers over 65, expanding the certified FOSHU manufacturer base. Japan's Ministry of Health, Labour and Welfare maintains strict approval pathways that reward compliant entrants with privileged pharmacy channel access. Kanto region laboratories specialize in molecular weight verification below 10 kDa, supplying precision-hydrolyzed inputs to domestic and Australian sports nutrition brands.
South Korea
Aging demographics accelerate collagen peptide adoption in Seoul and Busan metropolitan corridors where MFDS-regulated manufacturers target digestive-optimized formulations. South Korea's Ministry of Food and Drug Safety enforces batch traceability requirements for enzymatic hydrolysis processes. Seoul Capital Area facilities lead marine collagen extraction from wild-caught fish skin, though coastal catch volatility exposes processors to supply interruptions.
India
Mumbai, Delhi, and Bangalore exhibit faster premium wellness brand shelf space acquisition than secondary markets, signaling white-space expansion for clean-label powder formats. India's FSSAI imposes divergent labeling and origin requirements that fragment cross-border sourcing strategies, forcing parallel supply chain configurations. Gujarat and Maharashtra house the largest bovine collagen processing clusters, navigating religious dietary law restrictions through segregated production lines.
Australia
Sports nutrition brands in Sydney and Melbourne adopt precision-hydrolyzed peptide inputs at elevated procurement cadences, driving demand for rapid-absorption formats. Australia's Therapeutic Goods Administration oversees complementary medicine claims while maintaining alignment with international bioavailability standards. Victoria-based contract manufacturers serve as regional hubs for ASEAN export, leveraging TGA certification for cross-border pharmacy channel access.
Asia-Pacific Collagen Peptide Products Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade supply chains, while mid-tier domestic brands scramble for SAMR and FOSHU certifications to secure pharmacy distribution. The Asia-Pacific collagen peptide market exhibits tiered concentration with German technical heritage dominating premium specifications and integrated nutrition platforms capturing direct-to-consumer channels. Three strategic archetypes define competitive positioning: enzymatic precision specialists, integrated wellness bundlers, and marine-sourced origin purists. Dominant competitive moves include clinical substantiation partnerships with contract research organizations and backward integration into wild-caught marine raw material sourcing.
Among heritage European manufacturers, Gelita AG exemplifies the enzymatic precision archetype through its dominance of pharmaceutical-grade peptide specifications. Nestlé occupies a position within the integrated nutrition platform tier, bundling collagen with vitamin complexes across China and Southeast Asia. Nitta Gelatin, Inc. represents the marine-sourced origin specialist archetype, with Japanese technical heritage informing its regional supply relationships. These three anchors illustrate how certification depth, formulation integration, and raw material control separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Nestlé |
| Gelita AG |
| Nitta Gelatin, Inc. |
| Rousselot |
| Vital Proteins LLC |
| Tessenderlo Group NV |
| Vitalitown |
| Forest Leaf |
| Primal Harvest |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap enzymatic hydrolysis specialists in South Korea and Japan anchor supply discipline through conservative capacity expansion, translating raw material volatility into premium pricing power for FOSHU-certified outputs. Their reluctance to over-leverage shields pricing structures from the margin compression affecting contract-manufactured imports into China's tier-one cities.
Pricing Analysis
Short lead-time premiums of 15-20 percent separate emergency spot orders from contracted quarterly offtake across Australia's sports nutrition procurement channels. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications stratifies by molecular weight verification and batch traceability documentation. Cost compression in India's bovine collagen segment intensifies because Gujarat processors absorb FSSAI compliance overhead without pharmacy channel access. Direct-to-consumer subscription buyers in China's tier-one cities exhibit lowest price sensitivity, while mass retail distributors in Thailand's secondary markets negotiate hardest on per-kilogram contracts.
Supply Chain Analysis
Marine raw material supply rests on Indonesian and Vietnamese wild-caught fish skin processors, with South Korean coastal facilities providing precision-extraction finishing. Enzymatic hydrolysis equipment, amino acid sequencing instrumentation, and cold-chain logistics containers constitute critical input dependencies. Single-source vulnerability concentrates in Southeast Asian catch zones where climate-induced yield volatility exposes peptide manufacturers to supply interruptions. Distribution runs through pharmacy channel partnerships in Japan, direct-to-consumer e-commerce platforms in China, and sports nutrition specialty distributors in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's SAMR functional food registration reforms have erected a cost-of-compliance barrier that rewards certified incumbents with pharmacy channel moats while marginalizing mid-tier domestic brands lacking clinical substantiation budgets.
For Market Incumbents: Hedge against marine raw material volatility by securing multi-year offtake agreements with Indonesian coastal processors before climate pressures tighten supply. Deepen backward integration into enzymatic hydrolysis capacity within China's Yangtze River Delta to defend margin position against Australian contract manufacturers expanding into ASEAN markets.
For New Entrants and Emerging Players: E-commerce platform partnerships in India's metropolitan corridors offer the most penetrable white-space for clean-label collagen powder formats targeting health-conscious tier-one consumers. White-space also concentrates in Thailand's mass retail cosmetic channels where skin-health positioning migrates from dermatology clinics. Pursue private-label supply relationships with established wellness brands rather than direct-to-consumer launches.
For Investors and Strategic Acquirers: Distressed-cycle entries favor FOSHU-certified Japanese manufacturers with pharmacy channel relationships and molecular weight verification capabilities. Long-term viability over the next decade hinges on clinical substantiation infrastructure and regulatory affairs depth rather than raw material access alone. Watch ASEAN mutual recognition agreement progress as the signal indicating centralized manufacturing consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Partnership | Contract research organization alliances enable SAMR functional food registration in China's tier-one pharmacy channels. |
| Backward Integration into Marine Sourcing | Captive supply of Indonesian wild-caught fish skin insulates processors from climate-induced catch volatility. |
| Precision Enzymatic Hydrolysis Upgrade | Molecular weight reduction below 10 kDa opens premium positioning in Australia's sports nutrition procurement. |
| FOSHU Certification Investment | Japan's Ministry of Health, Labour and Welfare approval unlocks privileged distribution through pharmacy networks. |
| Direct-to-Consumer Platform Launch | Subscription e-commerce models in China's tier-one cities capture repeat purchase behavior through clean-label compatibility. |
Study Parameters
Independent corroboration across regulatory filing databases, customs trade records, and pharmaceutical-grade peptide procurement contracts underwrites the qualitative findings in this study. Primary interviews with enzymatic hydrolysis plant managers, FOSHU regulatory affairs leads, pharmacy channel procurement directors, and sports nutrition brand formulators combined with secondary validation from SAMR registration databases, MFDS approval records, and FSSAI labeling guidelines. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the Asia-Pacific region.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon, with segmentation modeling spanning product type, application, form, and end-user archetype plus regulatory certification tier as an industry-specific dimension. CAGRs derive from fitted growth curves applied to baseline consumption data, incorporating marine raw material supply constraints, enzymatic precision technology adoption curves, and channel migration patterns from pharmacy to e-commerce as forecast inputs.
Caveats apply where ASEAN mutual recognition agreement delays, China's SAMR registration rule tightening, or climate-induced Southeast Asian catch volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory stability, technology diffusion rates, and raw material supply continuity. A small set of named triggers—FOSHU approval pathway reforms, marine collagen substitution by recombinant alternatives, and India's FSSAI origin requirement harmonization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Food Market
Nutritional Supplements
Tea Tree Oil Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Dysphagia Supplements Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
GLP-1 Diet Food Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Chia-Based Protein Market