
 Italy Whey Protein Market | 2026-2036
Italy Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Whey Protein Market Foresight
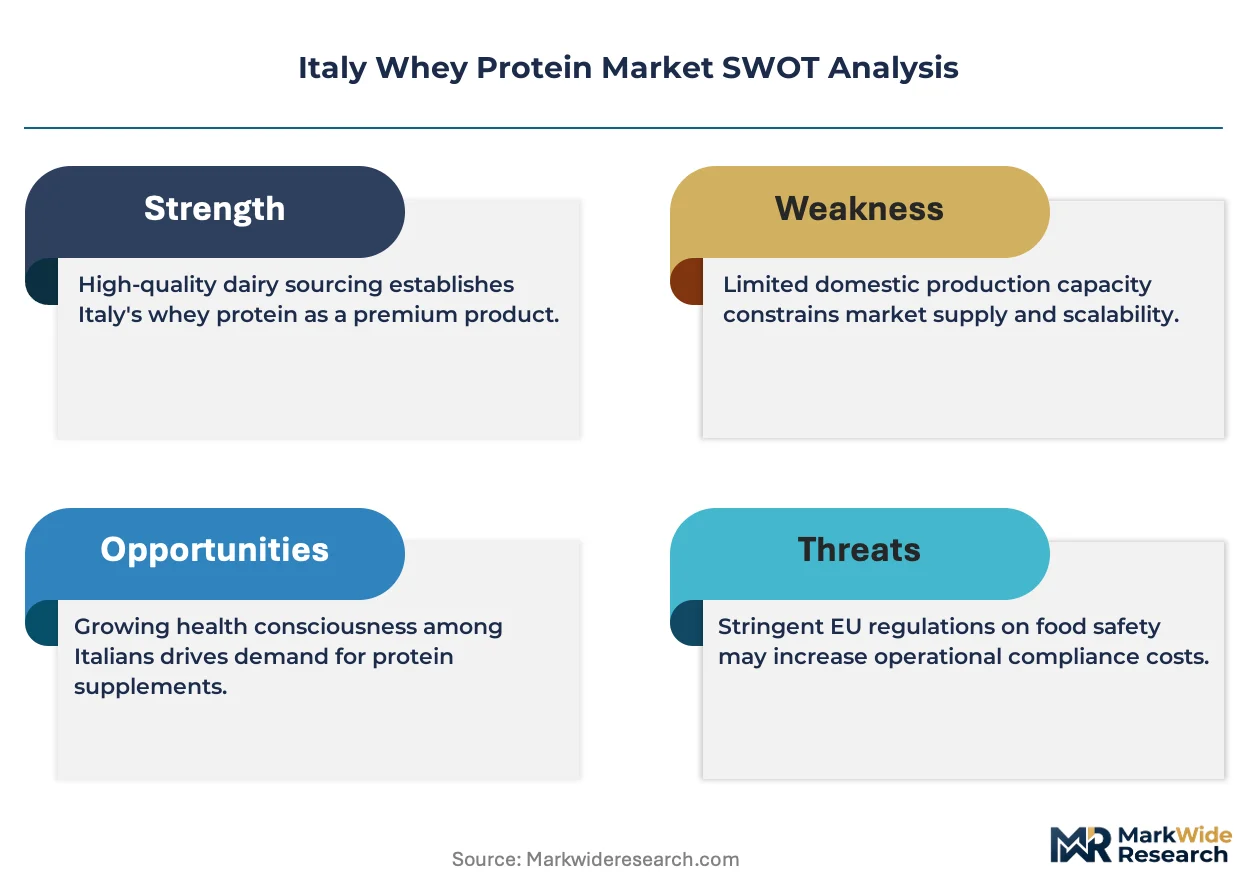
Microfiltration and ultrafiltration technology is narrowing the gap between commodity whey and premium isolate grades, compressing traditional tier boundaries. Lactalis Ingredients leverages its Lombardy dairy base to sustain captive whey streams. Arla Foods anchors its southern European supply through Danish-origin isolate positioning. Glanbia Plc competes via specialized hydrolysate production for clinical nutrition channels.
Italy whey protein denotes milk-derived protein fractions, typically containing beta-lactoglobulin and alpha-lactalbumin in ratios varying by processing method, recovered through membrane separation or ion exchange from cheese manufacturing byproduct streams. Its primary commercial purpose centers on delivering complete amino acid profiles with rapid gastric emptying for muscle protein synthesis support. Concentrate variants occupy the volume core due to cost-accessibility for mainstream fitness consumers, while isolate grades command premium positioning among physique competitors and clinical dietitians. Hydrolysate segments register the fastest structural ascent as pre-digested formats penetrate medical nutrition and infant formula adjacencies.
Italy's Ministry of Health oversees novel food registrations under EU Regulation 2015/2283, while EFSA evaluates health claims for protein-specific marketing. FSSAI-aligned importers face parallel scrutiny for non-EU origin material, tightening origin documentation requirements. CSRD disclosure mandates are pressing mid-sized processors toward supply chain traceability investments. Stakeholders must weigh whether backward integration into fluid whey sourcing or partnership with Po Valley cheese cooperatives offers more durable margin protection against input volatility.
Market Dynamics
Membrane filtration technology is compressing grade premiums between commodity whey concentrates and pharmaceutical-grade isolates, forcing processors to recalibrate margin architectures around functional differentiation rather than purity tiers alone.
Growth Catalysts
- Sports Nutrition Expansion:Fitness culture penetration across Lombardy and Emilia-Romagna drives steady demand for rapid-absorption protein formats among amateur and competitive athletes.
- EU Green Deal Protein Transition:Sustainability mandates under the Farm to Fork Strategy incentivize dairy byproduct valorization, positioning whey recovery as circular economy compliance.
- Microfiltration Advancement:Cross-flow membrane systems now achieve isolate-grade purity from standard cheese whey streams, collapsing traditional processing cost differentials.
Market Restraints
- Fluid Whey Input Volatility:Parmesan and Grana Padano production cycles in the Po Valley create seasonal supply discontinuities that destabilize processor procurement planning.
- EFSA Health Claim Scrutiny:Protein-specific marketing claims face prolonged substantiation timelines under EFSA evaluation protocols, delaying product launch cadences.
- Plant Protein Substitution:Pea and rice protein isolates from Nordic suppliers capture label-conscious consumers in organic retail channels.
Strategic Opportunities
- Medical Nutrition Adjacency:Pre-digested hydrolysate formats penetrate hospital and clinical dietitian channels previously dominated by enteral nutrition multinationals.
- CSRD Traceability Investment:Mid-sized processors can differentiate through supply chain disclosure compliance ahead of mandatory sustainability reporting deadlines.
- Southern Italy Underpenetration:Campania and Sicily retail infrastructure remains underserved relative to northern saturation, offering whitespace for regional distribution partnerships.
Industry Challenges
- Membrane Technician Scarcity:Cross-flow filtration operation and maintenance expertise concentrates in Emilia-Romagna technical institutes, constraining facility expansion elsewhere.
- Novel Food Registration Timelines:Italy's Ministry of Health processing queues for EU Regulation 2015/2283 compliance extend commercialization lead times for innovative formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Whey Protein Market |
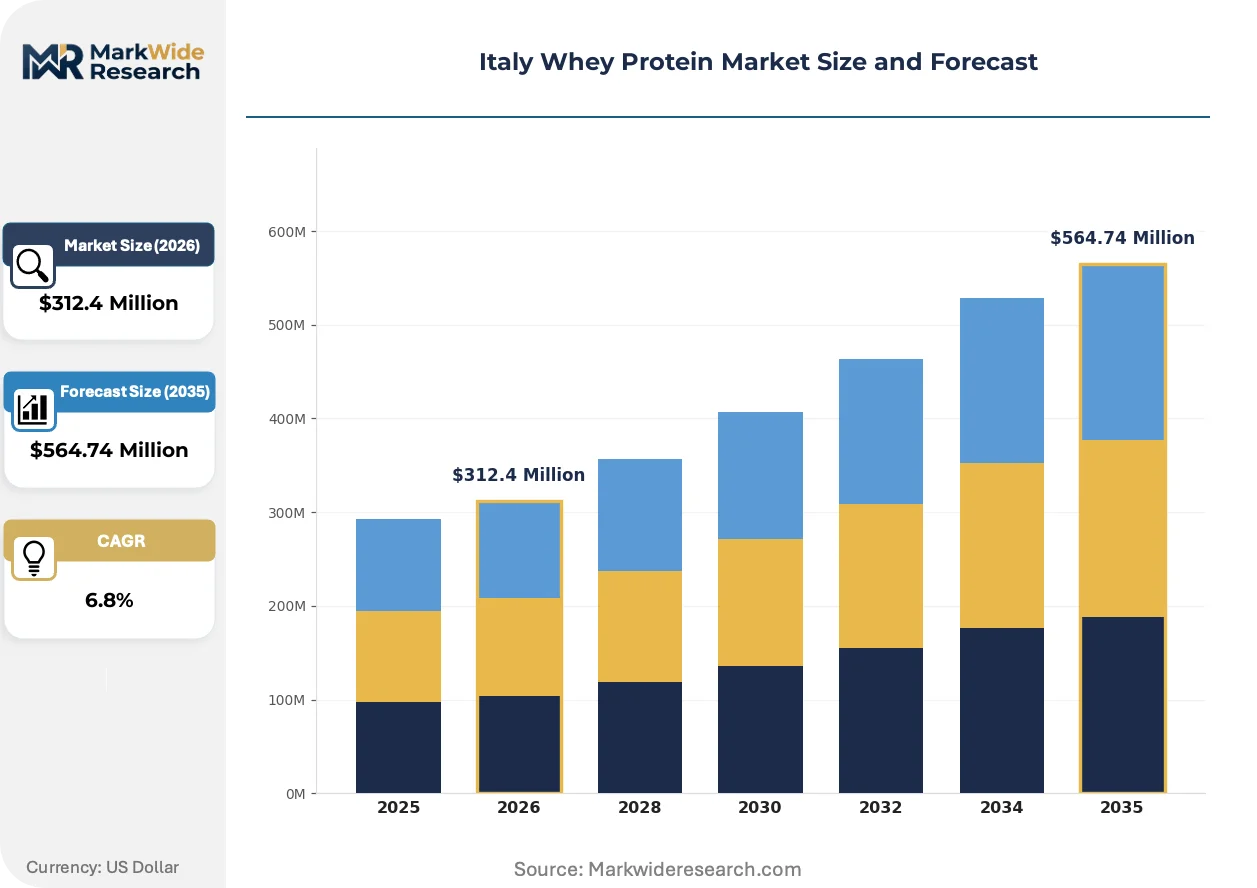
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends End User: Fitness Enthusiasts, Bodybuilders, Athletes, Health Conscious Consumers Form: Powder, Ready-to-Drink, Bars, Capsules Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Lactoprot Deutschland GmbH, Lactalis Ingredients, Arla Foods, Fonterra Co-operative Group, Carbery Group, Glanbia Plc, Agrial Enterprise, DMK Group, FrieslandCampina N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Whey Protein Market Shifts & Advancements
Processing technology convergence with sustainability verification systems is redefining competitive advantage around transparent provenance rather than commodity scale alone.
Cross-flow ceramic membrane systems is digitizing quality control through inline protein fraction monitoring and automated flux adjustment. Mid-sized processors in the Milan corridor adopt these platforms to reduce laboratory testing overhead. The technology is digitizing the traditional batch-release model into continuous verification, compressing time-to-market for isolate-grade products.
EFSA's evolving position on protein hydrolysate allergenicity claims is tightening substantiation requirements for infant formula applications. Manufacturers must now generate clinical endpoint data beyond compositional analysis. Pediatric nutrition specialists in Bologna research clusters face extended development cycles as they adapt dossiers to these protocols.
Direct-to-practitioner sampling programs are displacing traditional pharmacy distribution for clinical nutrition grades. Sports dietitians and rehabilitation specialists in Turin and Verona now source hydrolysate samples through specialized logistics platforms rather than wholesale intermediaries. This channel compression is most visible in northern industrial clusters where supplement manufacturing infrastructure overlaps with healthcare provider density.
Italy Whey Protein Market Segmentation
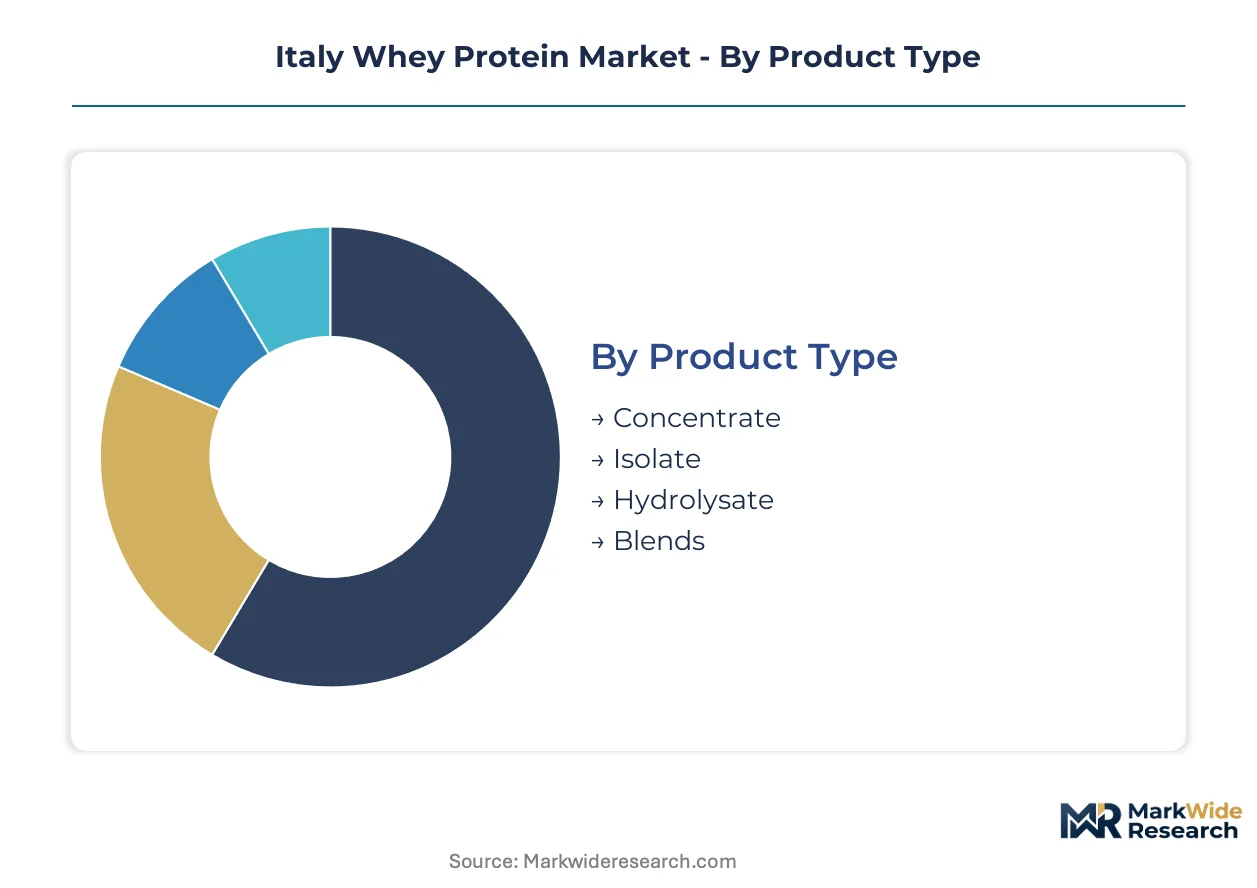
Whey protein segmentation in Italy reflects competing pressures between cost accessibility and functional specialization. Distinct product tiers, user profiles, and channel strategies create multiple entry points for processors navigating EFSA compliance and regional demand concentration.
Product Type:
Cost tier differentiation determines margin architecture across processing investments and purity specifications.
- Concentrate:Retains 70-80% protein content with residual lactose and fat, delivered through ultrafiltration of fluid whey streams. Demand concentrates among mainstream fitness consumers in Lombardy retail channels where price sensitivity dominates purchase decisions.
- Isolate:Achieves 90%+ protein purity via ion exchange or cross-flow microfiltration, eliminating most lactose. Competitive bodybuilders and clinical dietitians in Bologna research clusters drive specification requirements for rapid gastric emptying with minimal carbohydrate load.
- Hydrolysate:Pre-digested peptide fractions manufactured through enzymatic hydrolysis of isolate base stocks.
- Blends:Multi-source formulations combining whey fractions with casein or plant proteins for sustained release profiles.
Concentrate holds installed capacity. Hydrolysate is rotating up the share rankings.
End User:
Application specialization creates distinct formulation requirements across performance and wellness positioning.
- Fitness Enthusiasts:Amateur athletes pursuing body recomposition or endurance support represent the volume core. Milan metropolitan gyms and CrossFit boxes drive steady demand for flavored concentrate powders with convenience-focused packaging formats.
- Bodybuilders:Physique competitors require precise macronutrient tracking and rapid post-workout absorption. Emilia-Romagna supplement retailers stock isolate and hydrolysate grades in bulk configurations to serve this specification-driven segment.
- Athletes:Federated competitors in Olympic and professional leagues subject to anti-doping protocols.
- Health Conscious Consumers:Aging demographics and weight management seekers purchasing through pharmacy channels.
Fitness Enthusiasts anchor volume throughput. Health Conscious Consumers are climbing the fastest as clinical positioning expands.
Form:
Customer type preferences shape manufacturing infrastructure investments and shelf-life engineering requirements.
- Powder:Dry-mix formats dominate home consumption with extended stability and dose flexibility. Turin-area contract manufacturers operate dedicated blending and flavoring lines serving private-label sports nutrition brands.
- Ready-to-Drink:UHT-processed liquid beverages in aseptic packaging capture on-the-go consumption. Verona dairy processors leverage existing beverage infrastructure to enter this convenience-driven category.
- Bars:Extruded or cold-pressed formats combining protein with carbohydrate and fat matrices.
- Capsules:Encapsulated isolate or hydrolysate for clinical nutrition and precise dosing applications.
Powder commands legacy asset utilization. Ready-to-Drink is gaining share fastest through convenience retail expansion.
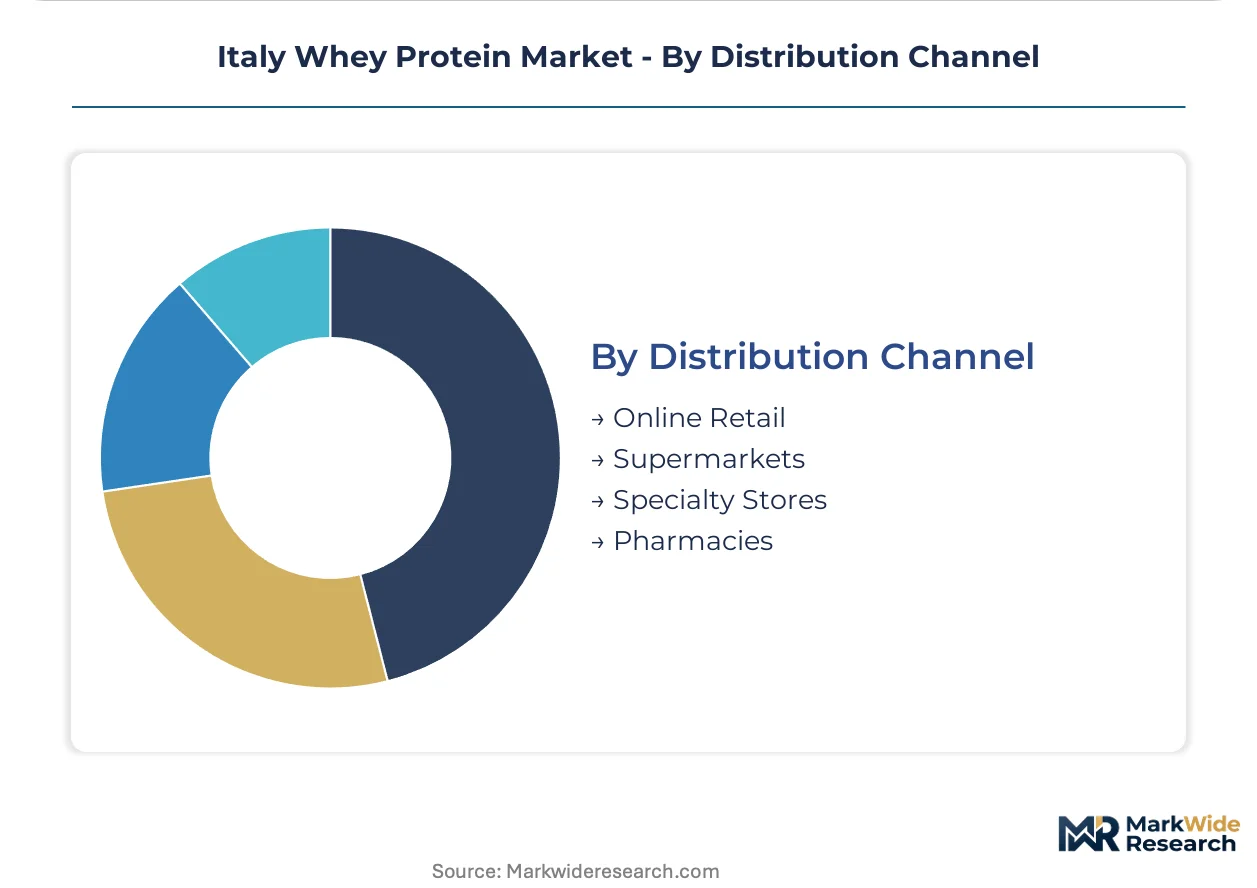
Distribution Channel:
Geography and margin capture determine channel prioritization across northern saturation and southern whitespace.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription models and flavor customization. Lombardy-based pure-play sports nutrition brands leverage Milan logistics hubs for next-day delivery coverage.
- Supermarkets:Mass-market retail placement requires scaled production and promotional investment. Coop and Conad central purchasing in Bologna sets listing standards for mainstream concentrate SKUs.
- Specialty Stores:Independent supplement retailers and gym pro-shops provide educated staff and sampling access.
- Pharmacies:Clinical-grade positioning through parafarmacia networks requires Ministry of Health registration compliance.
Supermarkets hold established shelf capacity. Online Retail is rotating up the share rankings through subscription retention models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts and clinical dietitians concentrate heavily in northern industrial corridors, with procurement patterns splitting between mass-market retail channels and specialized practitioner networks across distinct sub-regional economies.
Lombardy
Milan metropolitan gyms and CrossFit boxes drive concentrate demand through convenience-focused formats. EFSA health claim protocols govern product positioning for sports nutrition brands headquartered in the region. Contract manufacturers around Monza operate dedicated blending lines serving private-label sports nutrition brands.
Emilia-Romagna
Bologna research clusters shape isolate specifications for competitive bodybuilders and clinical applications. Italy's Ministry of Health maintains novel food registration processing facilities in the regional capital. Supplement retailers throughout the province stock bulk isolate and hydrolysate configurations for specification-driven segments.
Piedmont
Turin-area dairy processors leverage existing beverage infrastructure for ready-to-drink expansion. CSRD disclosure mandates press mid-sized processors toward supply chain traceability investments. Technical institutes in the region concentrate cross-flow filtration expertise that constrains facility replication elsewhere.
Veneto
Verona dairy processors repurpose UHT beverage lines for protein-fortified liquid formats. EU Green Deal circular economy incentives valorize whey recovery from Grana Padano production cycles. The province's manufacturing base captures convenience-driven consumption through aseptic packaging capabilities.
Campania
Pharmacy-channel penetration for clinical-grade positioning remains underdeveloped relative to northern saturation. FSSAI-aligned import scrutiny tightens origin documentation for non-EU material entering through Napoli logistics hubs. Regional distribution partnerships offer whitespace for hydrolysate formats targeting aging demographics.
Italy Whey Protein Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered purity grades and application adjacencies. The vendor base clusters around dairy-origin multinationals with captive whey streams and specialized processors with membrane filtration capabilities. Two strategic archetypes dominate: integrated dairy cooperatives leveraging Po Valley cheese production byproducts, and clinical-nutrition specialists with hydrolysate enzymatic processing expertise. Competitive moves center on backward integration into fluid whey sourcing and partnership formation with Po Valley cheese cooperatives.
Among dairy-integrated processors, Lactalis Ingredients and Arla Foods occupy positions exemplifying the cooperative archetype, anchoring supply security through Lombardy and Danish-origin whey streams respectively. Glanbia Plc sits within the specialized hydrolysate tier, representing clinical-nutrition positioning through pre-digested peptide production capabilities.
| Leading Market Players |
|---|
| Lactoprot Deutschland GmbH |
| Lactalis Ingredients |
| Arla Foods |
| Fonterra Co-operative Group |
| Carbery Group |
| Glanbia Plc |
| Agrial Enterprise |
| DMK Group |
| FrieslandCampina N.V. |
| Others |
Supply & Pricing Matrix
Po Valley cheese plant undercapacity during summer milk troughs forces processors to bid aggressively for fluid whey streams, compressing margins on concentrate grades while inflating spot premiums for isolate-bound material. This utilization volatility rewards operators with backward integration into cooperative supply agreements.
Pricing Analysis
Cost-plus contracts indexed to EU dairy commodity boards dominate procurement between Grana Padano cooperatives and membrane processors. Price differentiation hinges on protein purity certification and volume scale, with hydrolysate grades commanding substantial premia over concentrate due to enzymatic processing overhead. Pricing pressure intensifies as Nordic plant protein isolates capture label-conscious consumers in organic retail channels. Mainstream fitness enthusiasts exhibit highest price sensitivity, while clinical dietitians purchasing through pharmacy channels demonstrate minimal elasticity.
Supply Chain Analysis
Tariff exposure between EU and non-EU dairy jurisdictions dominates supply chain risk planning for Italian processors sourcing Danish-origin isolate base stocks. Geographic supply concentration centers on Italy, Denmark, and the Netherlands for whey fractionation capacity. Raw material dependencies include fluid whey from Parmigiano-Reggiano production cycles, ceramic membrane filtration modules from German suppliers, and food-grade enzymes from Dutch biotechnology specialists. Distribution runs through northern Italian logistics hubs serving Lombardy and Emilia-Romagna retail density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. EFSA health claim substantiation timelines and Ministry of Health novel food registration queues create structural barriers that protect incumbent positions.
For Market Incumbents: Harden membrane filtration capacity in Emilia-Romagna to capture hydrolysate demand from clinical nutrition channels. Deepen backward integration into Po Valley cheese cooperative supply agreements to neutralize fluid whey input volatility. Prioritize CSRD traceability investments ahead of mandatory sustainability disclosure deadlines to differentiate against mid-sized competitors lacking disclosure infrastructure. For New Entrants and Emerging Players: Pursue southern Italy whitespace through regional distribution partnerships targeting Campania and Sicily pharmacy channels. Medical nutrition adjacencies offer the most penetrable segment given entrenched enteral nutrition multinationals' slow adaptation to direct-to-practitioner sampling models. Position through specialized logistics platforms serving rehabilitation specialists rather than wholesale intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrolysate enzymatic processing as clinical-grade substantiation requirements demand expanded R&D facilities. Long-term viability favors operators with captive whey streams and membrane filtration expertise. Target acquisition candidates among mid-sized processors with CSRD-ready traceability systems. Monitor EFSA allergenicity claim protocol evolution as the critical inflection signal for pediatric nutrition positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluid Whey Sourcing | Captive supply from Po Valley cheese cooperatives neutralizes seasonal input volatility. |
| CSRD Traceability Infrastructure Investment | Mid-sized processors gain differentiation ahead of mandatory sustainability reporting deadlines. |
| Hydrolysate Production Scale-Up | Pre-digested peptide formats penetrate hospital channels previously dominated by enteral nutrition multinationals. |
| Direct-to-Practitioner Sampling Platforms | Channel compression displaces pharmacy wholesale intermediaries in Turin and Verona clinical networks. |
| Southern Italy Distribution Partnership Formation | Campania and Sicily retail infrastructure remains underserved relative to northern saturation. |
Research Methodology
Initial hypotheses were tested against primary input from membrane filtration plant managers, sports nutrition brand procurement leads, clinical dietitians in Bologna research clusters, and pharmacy category buyers, then refined through secondary validation against EFSA health claim registers, EU dairy commodity board price series, and Ministry of Health novel food approval databases. Bottom-up capacity assessments across Po Valley cheese cooperatives were triangulated with top-down demand modeling from gym chain supplement purchasing data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type tiers, end-user application specialization, form factor preferences, and distribution channel geography. CAGRs were derived from installed capacity utilization trajectories and price elasticity estimates calibrated to regional income differentials. Industry-specific forecast inputs included Grana Padano production cycle seasonality and cross-flow membrane technology adoption curves from Emilia-Romagna technical institutes.
Sensitivities concentrate around EFSA health claim evaluation timelines, fluid whey availability during summer milk production troughs, and plant protein isolate substitution rates in organic retail channels. Forecasts reflect documented assumptions on membrane filtration cost compression and regulatory disclosure mandate implementation schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Human Milk Oligosaccharides (HMO) Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Europe Diet Pills Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Plant Based Protein Supplements Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Dietary Supplement Cultures Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Fish Oil Supplements Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Global Soluble Dietary Fibers Market