
 Yeast Beta Glucan Market | 2026-2036
Yeast Beta Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Beta Glucan Market Analysis
The gap between pharmaceutical-grade and feed-grade yeast beta glucan is recalibrating procurement standards across the value chain. Lallemand Inc. leverages captive fermentation capacity to anchor supply security for high-purity grades. Lesaffre competes through geographic proximity to European nutraceutical compounders, while Angel Yeast Co., Ltd dominates cost structures via integrated yeast propagation in Asia.
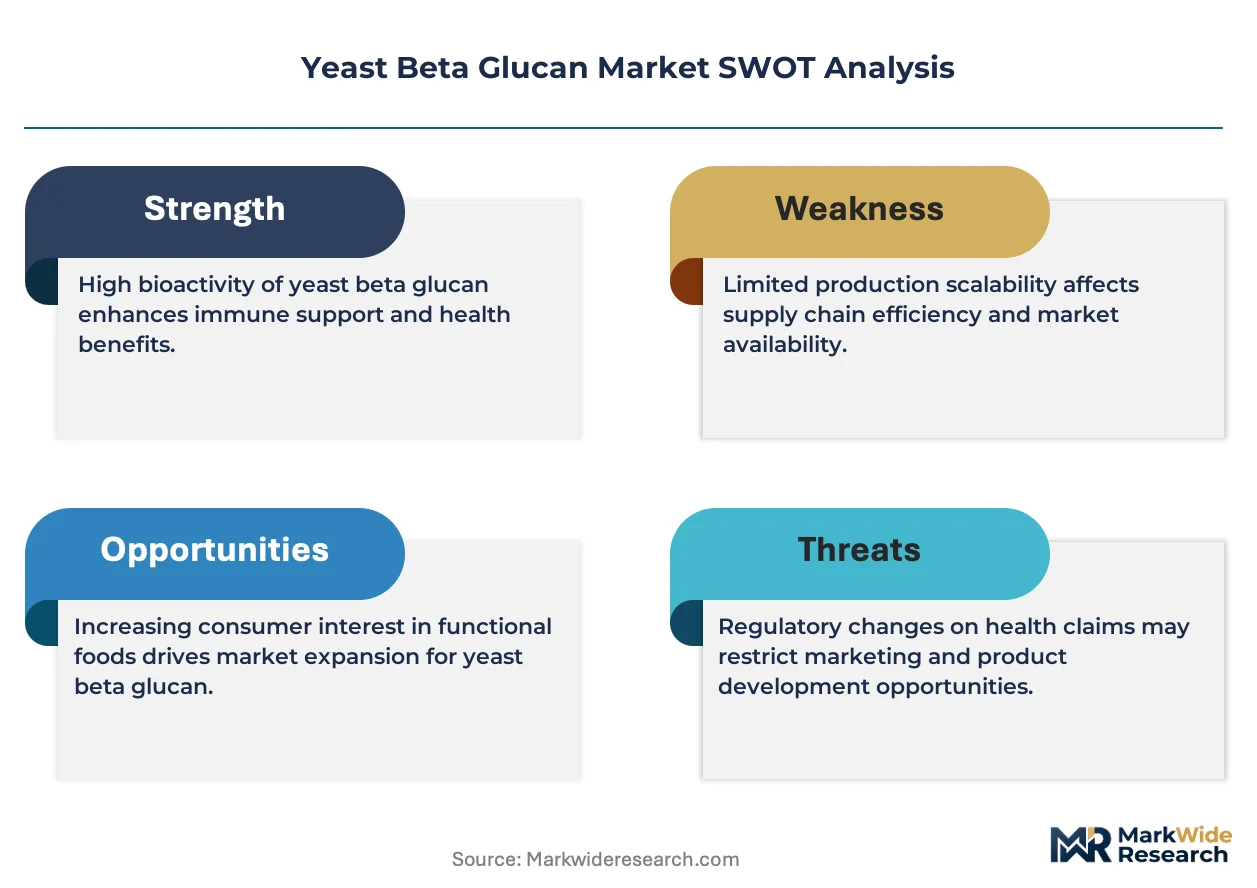
Yeast beta glucan comprises a class of glucose polymers, predominantly beta-1,3/1,6-glucans, extracted from Saccharomyces cerevisiae cell walls through alkaline or enzymatic processing; these polysaccharides activate macrophage and dendritic cell receptors, serving immunomodulatory functions in human and animal health. Powder formulations occupy the largest volume position due to stability in blending operations, though liquid concentrates are gaining traction in functional beverage applications where solubility parameters dictate formulation choice. Pharmaceutical-grade capsules command margin premiums over commodity animal feed granules, reflecting divergent purity certification requirements.
EU Novel Food regulations, EFSA health claim frameworks, and FDA GRAS notifications collectively govern market access and label permissibility for immune health positioning. REACH compliance and F-Gas Regulation constraints on solvent-based extraction are nudging producers toward enzymatic and aqueous processing platforms. Stakeholders must track evolving pharmacopeial monograph standards and regional clean-label enforcement intensity to align capacity investments with forthcoming compliance thresholds.
Market Dynamics
Clean-label extraction protocols are compressing the cost premium between pharmaceutical-grade and feed-grade yeast beta glucan, forcing suppliers to recalibrate purity certification investments across all output tiers.
Growth Catalysts
- EFSA health claim frameworks:EU Novel Food approvals for immune-modulating positioning unlock label permissibility in dietary supplements across Germany, France, and the Netherlands.
- Enzymatic processing platforms:Aqueous extraction methods reduce solvent dependency and align with REACH compliance mandates for fermentation-derived inputs.
- Functional beverage formulations:Liquid concentrate demand from North American nutraceutical compounders expands addressable volume beyond traditional powder applications.
Market Restraints
- Raw material concentration:Saccharomyces cerevisiae propagation capacity clusters in China and select EU fermentation hubs, creating geographic supply vulnerability.
- Extraction cost volatility:Alkaline processing input costs fluctuate with caustic soda and energy pricing, compressing margins on commodity feed-grade output.
- Regulatory fragmentation:Divergent FDA GRAS notification timelines versus EU Novel Food assessment periods delay synchronized market entry.
Strategic Opportunities
- Pet nutrition expansion:Immune-modulating positioning in premium companion animal formulations remains underdeveloped relative to human supplement saturation.
- Clean-label convergence:Fermentation technology advances paired with aqueous extraction create dual-certification pathways for organic and non-GMO positioning.
- Direct-to-practitioner channels:Functional medicine clinicians represent an emerging prescription-adjacent distribution vector for high-purity capsules.
Industry Challenges
- Pharmacopeial standardization delays:Absence of harmonized monographs across USP, EP, and JP compendia complicates multi-territory registration.
- Biomarker validation gaps:Clinical endpoint standardization for immune health claims requires investment in macrophage activation assay correlation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Beta Glucan Market |
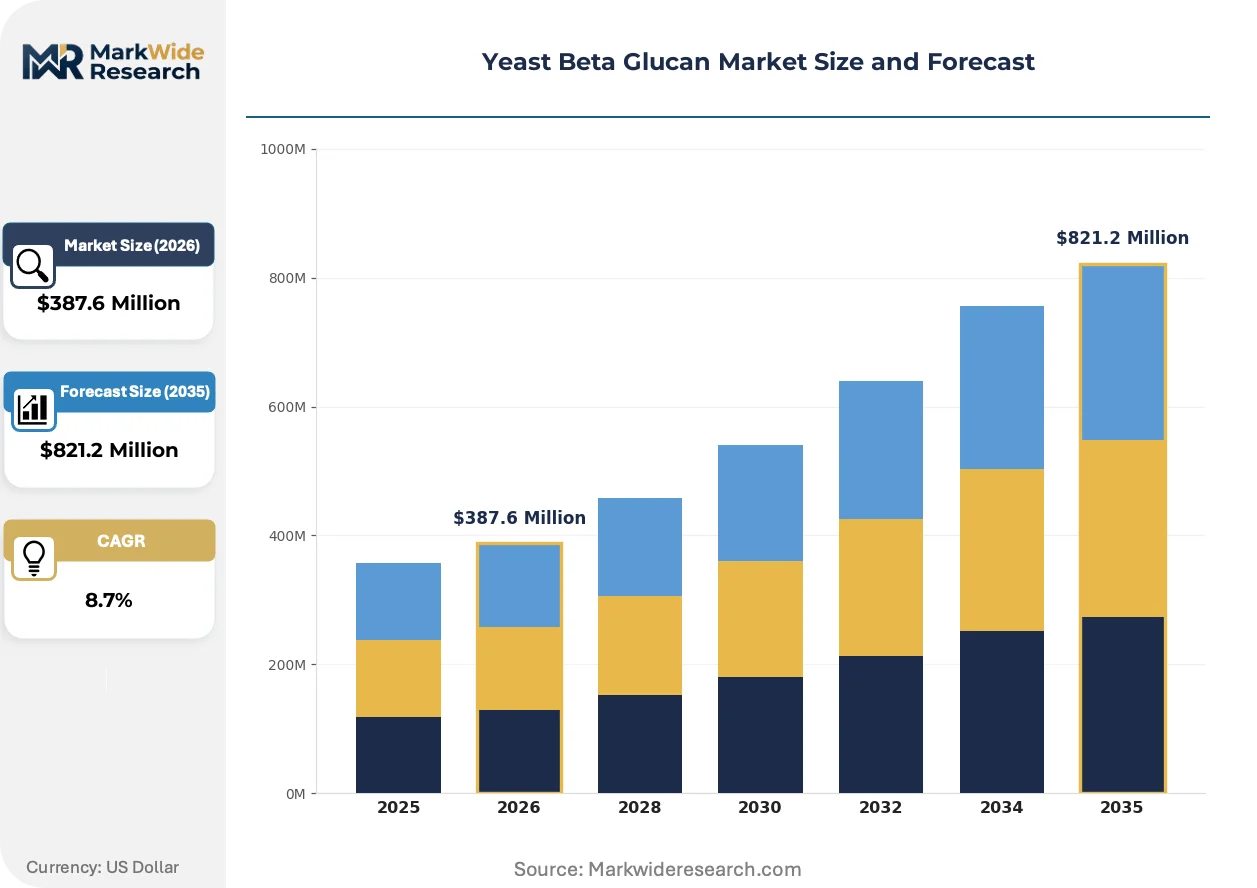
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Capsules Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Animal Feed End User: Healthcare, Food & Beverage, Nutraceuticals, Cosmetics Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Lallemand Inc., Leiber GmbH, Lesaffre, Alltech, Kemin Industries, Inc., Angel Yeast Co., Ltd, dsm-firmenich, Biorigin, Kerry Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Beta Glucan Market Emerging Trajectories
Bioprocessing efficiency gains and regulatory clarity around immune health positioning are compressing development timelines and expanding formulation latitude across human and animal applications.
Enzymatic cell-wall disruption is absorbing share from traditional alkaline extraction in high-purity applications. Nutraceutical compounders in Germany and Switzerland are adopting these platforms to satisfy clean-label procurement specifications. The technology is absorbing capital that previously flowed into solvent-based capacity, reshaping equipment vendor order books.
REACH F-Gas Regulation constraints on solvent-based extraction are accelerating aqueous platform investment across EU fermentation facilities. Industrial consequence includes shortened environmental permitting timelines for brownfield expansions. Pharmaceutical-grade producers in Belgium and the Netherlands are responding with closed-loop water recovery systems to maintain cost parity.
Ingredient buyers are consolidating supplier relationships around dual-certified fermentation partners capable of spanning human and animal health specifications. Long-term offtake agreements are displacing spot market purchasing in North American dietary supplement manufacturing. This concentration is most visible in contract manufacturing organizations serving branded finished goods companies.
Yeast Beta Glucan Market Segmentation
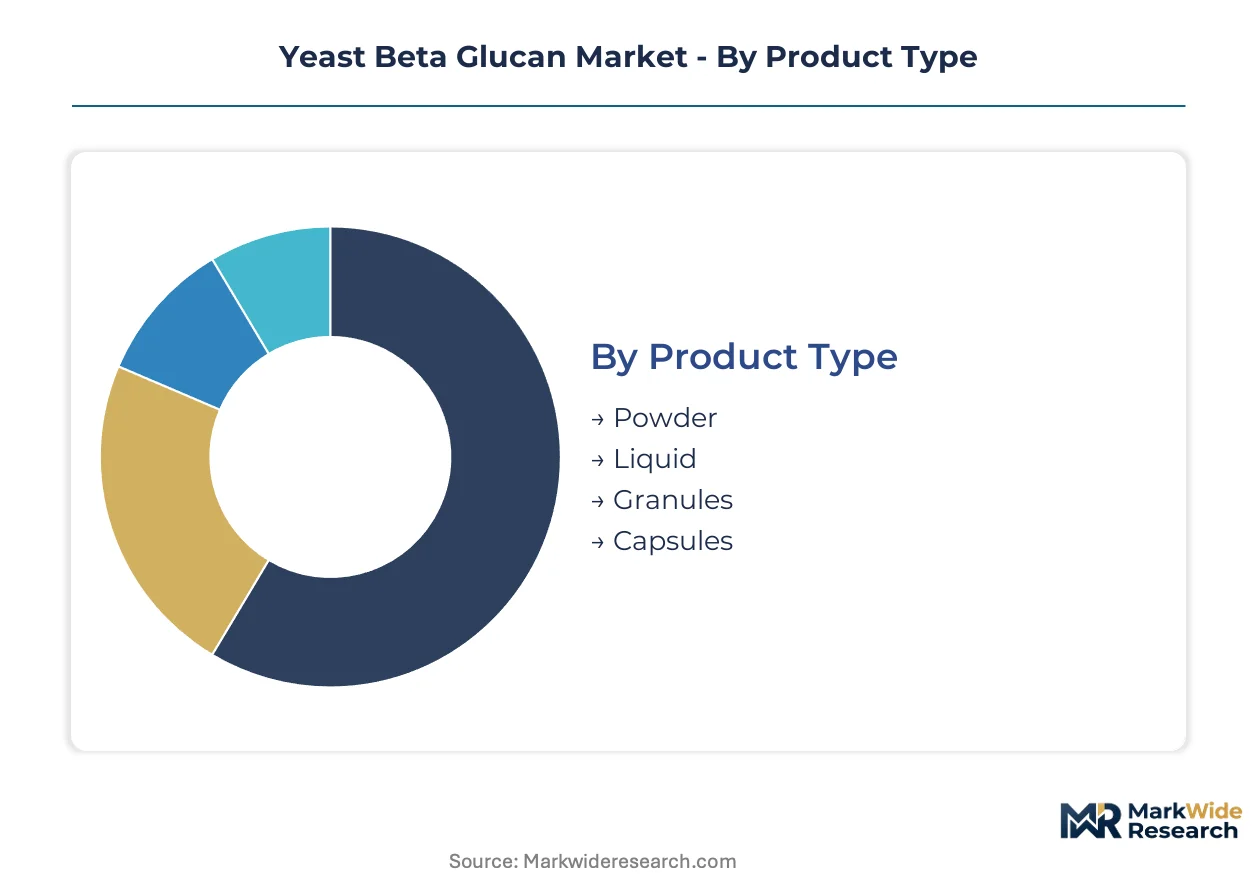
Yeast beta glucan procurement patterns diverge sharply across physical forms and end-use specifications, with pharmaceutical-grade purity commanding fundamentally different supply relationships than commodity feed applications. Formulation requirements dictate extraction method selection, while regulatory pathways determine which segments absorb capital investment versus spot-market purchasing.
Product Type:
Powder formulations anchor volume throughput, while liquid concentrates and encapsulated grades capture premium positioning through solubility and dosing precision advantages.
- Powder:Dominates blending operations across dietary supplement manufacturing due to thermal stability and bulk handling efficiency. Demand concentrates in North American contract manufacturers serving branded finished goods companies, where powder flow properties determine production line compatibility.
- Liquid:Gaining formulation share in functional beverage applications where solubility parameters override stability concerns. German and Swiss nutraceutical compounders are absorbing capacity from aqueous extraction platforms to satisfy clean-label procurement specifications.
- Granules:Standardized for animal feed compounding with lower purity thresholds and cost-sensitive procurement.
- Capsules:Pre-measured dosing for direct-to-consumer channels with pharmacopeial-grade certification requirements.
Mature deployment sits with Powder. Newer deployment is concentrated in Liquid.
Application:
Immune health positioning drives regulatory investment intensity, with human applications absorbing disproportionate compliance resources relative to animal feed commoditization.
- Dietary Supplements:Absorbs the majority of EFSA health claim framework investment and FDA GRAS notification activity. Long-term offtake agreements from North American manufacturers are displacing spot purchasing as branded companies consolidate supplier relationships.
- Pharmaceuticals:Requires harmonized USP, EP, and JP pharmacopeial compliance that remains incomplete across territories. Clinical endpoint standardization for macrophage activation assays is pending, delaying multi-territory registration.
- Functional Foods:Beverage and fortified food applications expanding through liquid concentrate adoption.
- Animal Feed:Cost-driven procurement with alkaline extraction cost volatility compressing margins.
Volume leadership belongs to Dietary Supplements. Steepest expansion trajectory is emerging in Pharmaceuticals pending biomarker validation completion.
End User:
Healthcare and nutraceutical procurement patterns are converging as functional medicine clinicians emerge as a prescription-adjacent distribution channel for high-purity grades.
- Nutraceuticals:Compounders in Germany, the United States, and the Netherlands drive specification development for immune-modulating formulations. EU Novel Food approvals unlock label permissibility that directly determines procurement authorization.
- Healthcare:Hospital and clinic procurement remains limited pending pharmacopeial standardization, though direct-to-practitioner channels are absorbing high-purity capsule volumes.
- Food & Beverage:Functional beverage manufacturers prioritize liquid concentrate solubility.
- Cosmetics:Topical applications represent a peripheral segment with limited current formulation penetration.
Procurement consolidation is most advanced in Nutraceuticals. Healthcare represents the underdeveloped expansion vector.
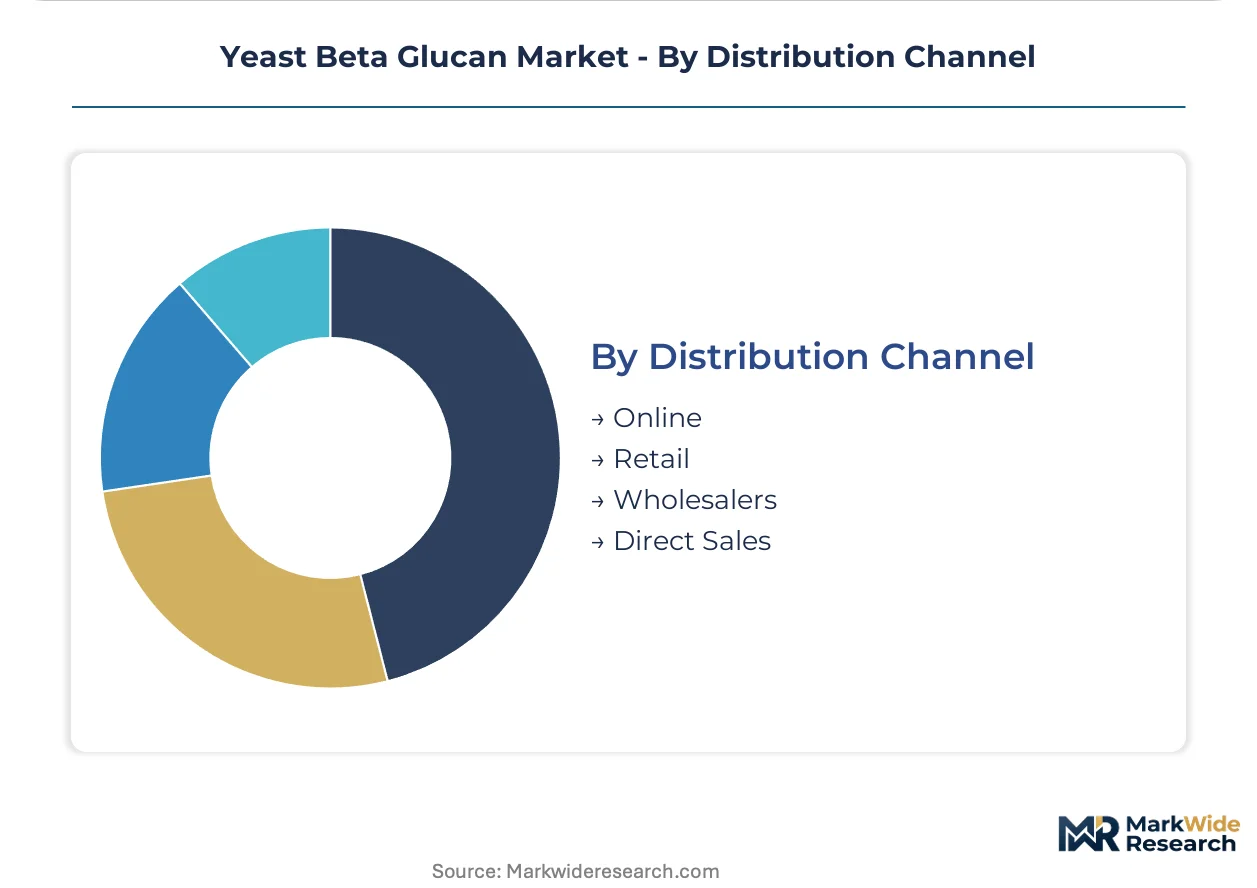
Distribution Channel:
Relationship-based purchasing dominates high-purity segments, while commodity grades tolerate transactional spot-market dynamics.
- Direct Sales:Long-term offtake agreements with dual-certified fermentation partners span human and animal health specifications. Belgian and Dutch pharmaceutical-grade producers leverage closed-loop water recovery systems to maintain cost parity under REACH F-Gas constraints.
- Wholesalers:Intermediate stocking for mid-tier nutraceutical compounders with less stringent certification requirements.
- Online:Direct-to-consumer and small-scale supplement brand procurement with limited technical specification negotiation.
- Retail:Minimal penetration for raw ingredient procurement; relevant only for finished goods.
Contractual lock-in is strongest in Direct Sales. Channel fragmentation persists in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strasbourg anchors regulatory precedent-setting for yeast beta glucan through EFSA's centralized health claim assessments, while industrial fermentation clusters in Belgium and the Netherlands execute novel food compliance protocols.
United States
Dietary supplement contract manufacturers in Utah and California drive powder formulation demand for immune health positioning. FDA GRAS notification pathways determine market entry sequencing for new suppliers. Chicago-area nutraceutical compounders consolidate supplier relationships through long-term offtake agreements with dual-certified fermentation partners.
Germany
Functional beverage startups in Berlin and Hamburg absorb liquid concentrate volumes from aqueous extraction platforms. BfR (Federal Institute for Risk Assessment) coordinates with EFSA on novel food safety evaluations. Bavarian fermentation facilities invest in closed-loop water recovery systems under REACH F-Gas constraints.
China
Angel Yeast Co., Ltd's integrated propagation complexes in Hubei and Guangxi provinces dominate cost structures through captive Saccharomyces cerevisiae supply. NMPA (National Medical Products Administration) oversees pharmaceutical-grade registration requirements. Yangtze River Delta nutraceutical exporters serve European and North American contract manufacturers.
Belgium
Pharmaceutical-grade producers in the Flanders biotech corridor pursue harmonized USP-EP-JP pharmacopeial compliance for capsule formulations. EMA's proximity accelerates clinical endpoint consultation timelines for immune health claims. Ghent fermentation facilities specialize in high-purity enzymatic extraction for premium nutraceutical applications.
Netherlands
Rotterdam port logistics facilitate raw yeast biomass import flows from Asian fermentation hubs. RIVM (National Institute for Public Health and the Environment) contributes to EFSA scientific opinions on beta-glucan immunomodulatory mechanisms. Wageningen university-industry partnerships advance clean-label extraction technology transfer to commercial producers.
Yeast Beta Glucan Market Vendor Landscape
Premium-margin players sit above commodity-margin players across purity certification tiers, with pharmaceutical-grade suppliers commanding fundamentally different procurement relationships than feed-grade processors. The vendor base stratifies between integrated fermentation operators, specialized extraction technology providers, and diversified ingredient conglomerates. Three archetypes dominate: captive yeast propagators controlling upstream biomass, toll manufacturers leveraging geographic proximity to compounders, and multi-ingredient portfolios using beta-glucan as an immune health anchor. Competitive moves concentrate on enzymatic processing platform licensing and dual-certification capacity expansion spanning human and animal health specifications.
Within the integrated fermentation tier, Lallemand Inc., Lesaffre, and Angel Yeast Co., Ltd exemplify contrasting geographic and structural positioning. Lallemand Inc. represents North American captive capacity deployment, Lesaffre occupies a position anchored in European proximity to nutraceutical compounders, and Angel Yeast Co., Ltd sits within Asia-Pacific cost-structure leadership through backward integration into yeast propagation. These three entities collectively illustrate how biomass control, regional regulatory familiarity, and extraction technology access determine competitive position without requiring equivalent strategic moves.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Leiber GmbH |
| Lesaffre |
| Alltech |
| Kemin Industries, Inc. |
| Angel Yeast Co., Ltd |
| dsm-firmenich |
| Biorigin |
| Kerry Group PLC |
| Others |
Supply Flow & Price Mechanics
Captive yeast propagation in Hubei and Guangxi provinces anchors Angel Yeast Co., Ltd's cost position and pricing power across pharmaceutical-grade and feed-grade tiers. This backward integration into Saccharomyces cerevisiae biomass control compresses raw material volatility for integrated operators while forcing toll manufacturers to absorb alkaline extraction cost swings.
Pricing Analysis
Immune-modulating efficacy claims anchor value-based pricing premiums for pharmaceutical-grade capsules over commodity feed granules. Three-tier pricing structure across pharmaceutical, nutraceutical, and feed grades reflects divergent purity certification requirements under USP, EP, and EFSA frameworks. Cost compression in feed-grade output intensifies as caustic soda and energy pricing volatility squeezes alkaline processing margins. Contract manufacturing organizations serving branded finished goods companies exhibit lowest price sensitivity, while animal feed compounders prioritize volume-scale procurement.
Supply Chain Analysis
Skilled fermentation technologist availability in Belgium, the Netherlands, and Germany anchors pharmaceutical-grade enzymatic extraction capacity. Saccharomyces cerevisiae biomass feeds from Chinese propagation hubs, European fermentation facilities, and North American captive operations. Single-source vulnerability concentrates in Hubei province yeast propagation complexes. Distribution runs through long-term offtake agreements with dual-certified partners spanning human and animal health specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Yeast beta glucan competitive dynamics constitute a vertical-integration race where biomass control and extraction technology access determine margin capture. Players are pursuing backward integration into Saccharomyces cerevisiae propagation to secure supply position.
For Market Incumbents: Hedge against enzymatic processing platform disruption by licensing aqueous extraction technology from Wageningen university-industry partnerships. Defend margin position through closed-loop water recovery systems under REACH F-Gas constraints. Consolidate supplier relationships around dual-certified fermentation partners capable of spanning pharmaceutical-grade and feed-grade specifications. For New Entrants and Emerging Players: The premium-to-economy price-point gap in pet nutrition immune-modulating formulations offers white-space entry. Target underdeveloped premium companion animal applications in North American and Western European markets. Pursue clean-label aqueous extraction positioning to satisfy German and Swiss nutraceutical compounder procurement specifications. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified ingredient conglomerates seeking immune health portfolio anchors. Long-term viability favors integrated fermentation operators with captive yeast propagation and pharmacopeial-grade certification capabilities. Watch EFSA health claim framework expansion timelines as inflection indicator for European market entry authorization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Platform Licensing | Wageningen technology transfer enables REACH F-Gas compliance for Belgian and Dutch producers. |
| Dual-Certification Capacity Expansion | Human and animal health specification spanning captures consolidation-driven contract manufacturing demand. |
| Closed-Loop Water Recovery Systems | Bavarian and Flanders facilities maintain cost parity under aqueous extraction investment requirements. |
| Pet Nutrition Formulation Development | Premium companion animal immune health positioning remains underdeveloped relative to human supplement saturation. |
| Direct-to-Practitioner Channel Buildout | Functional medicine clinicians represent emerging prescription-adjacent distribution for high-purity capsules. |
Methodological Framework
Document review covered EFSA scientific opinions, FDA GRAS notification filings, and EU Novel Food approval records, complemented by interviews with fermentation facility operations directors, nutraceutical compounder procurement leads, regulatory affairs specialists at ingredient suppliers, and contract manufacturing organization supply chain managers. Secondary validation drew from customs trade data, pharmacopeial monograph updates, and REACH compliance disclosure filings. Bottom-up volume modeling triangulated against top-down market sizing across purity grades and application segments.
Cross-referencing historical capacity expansion patterns against expert panel input on enzymatic processing adoption timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled included physical form, purity certification tier, end-use application, and geographic regulatory cluster. CAGRs derived from slope analysis of documented capacity investments correlated with EFSA and FDA approval velocity assumptions. Forecast inputs incorporated biomass propagation yield improvements and clean-label extraction technology transfer rates.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than commodity feed-grade estimates due to pharmacopeial reporting requirements. Forecasts reflect assumptions around EFSA health claim framework expansion, REACH F-Gas enforcement intensity, and enzymatic processing cost convergence timelines. Regulatory approval delays, raw material concentration disruptions, and biomarker validation gaps constitute primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Therapeutic Food Delivery for Clinical Nutrition Market
Functional Food and Beverage
Oat Beta-Glucan Market
Functional Food and Beverage
Botanical Infusions Market
Functional Food and Beverage
Europe Prebiotics Market
Functional Food and Beverage
Functional Foods and Natural Health Products Market
Functional Food and Beverage
North America Probiotic Drinks Market
Functional Food and Beverage
Asia-Pacific Beauty Drinks Market
Functional Food and Beverage
Zero-Fat Protein Market
Functional Food and Beverage
Xanthohumol Market
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
Functional Food and Beverage Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Beauty Drinks Market
Functional Food and Beverage
Global Oral Proteins and Peptides Market
Functional Food and Beverage
Europe Health Drinks Market
Functional Food and Beverage
Functional Soda Market