
 Nutrition Powder Market | 2026-2036
Nutrition Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Nutrition Powder Market Analysis
China is rewriting competitive dynamics in nutrition powder manufacturing through expanded whey processing and plant protein extraction facilities. Amway leverages its direct-selling infrastructure to sustain recurring revenue across Asian markets. Optimum Nutrition anchors North American shelf presence through flavor R&D and gym-channel exclusivity. Herbalife competes in weight-management positioning with personalized nutrition coaching bundled to powder subscriptions.
Nutrition powder denotes dry-formulated blends of proteins, vitamins, minerals, and functional additives designed for reconstitution in liquid or integration into food matrices, typically manufactured via spray-drying, dry blending, or agglomeration to achieve solubility targets between 60-90 seconds. These formulations serve commercial purposes spanning muscle protein synthesis support, micronutrient fortification, and caloric control in managed diets. Protein powder occupies the largest margin pool due to premium pricing on isolate and hydrolysate grades, while plant-based ingredient source categories are expanding fastest as oat, pea, and fava bean proteins displace soy in clean-label portfolios. Meal replacement applications lead volume among consumer type segments as busy professionals substitute breakfast and lunch occasions with macro-balanced shakes.
FDA oversees nutrition powder labeling through DSHEA and facility registration mandates, while EFSA in Europe enforces novel food approvals for emerging protein sources such as insect and algae derivatives, shaping reformulation pipelines and market access timelines. China's SAMR implements GB standards for protein content claims and contaminant limits, forcing import brands to localize testing protocols. Stakeholders must monitor divergence between FDA's pending modernized good manufacturing practice enforcement and the EU's tightening threshold for environmental claim substantiation on packaging.
Market Dynamics
The nutrition powder sector faces a structural compression between FDA's pending modernized good manufacturing practice enforcement and the EU's tightening threshold for environmental claim substantiation, forcing simultaneous reformulation and packaging redesign cycles.
Growth Catalysts
- Amateur athlete adoption:Sports nutrition powders are penetrating weekend warrior segments as gym-channel education normalizes peri-workout protein timing protocols.
- DSHEA facility registration mandates:The FDA's tightened facility oversight is culling marginal operators and consolidating shelf access for compliant manufacturers.
- Plant protein extraction advances:Enzymatic hydrolysis of fava and mung bean proteins is achieving solubility parity with whey isolates in clean-label portfolios.
Market Restraints
- Whey concentrate cost volatility:Dairy commodity swings and New Zealand drought cycles transmit directly into margin pressure for mid-tier protein SKUs.
- Novel food approval timelines:EFSA's safety dossier requirements for insect and algae proteins extend European market access by 18-24 months versus conventional sources.
- Substitution by whole-food alternatives:Greek yogurt and refrigerated protein beverages are capturing convenience-oriented breakfast occasions from powder formats.
Strategic Opportunities
- Senior nutrition underpenetration:Sarcopenia-targeted leucine-enriched formulations for adults over 65 remain underserved relative to sports positioning.
- Telehealth bundle integration:Registered dietitian consultations paired with automated powder subscriptions create recurring revenue lock-in.
- China's dual carbon goals:Domestic plant-protein capacity expansion aligns with MEE emissions targets and reduces import dependency for oat and pea isolates.
Industry Challenges
- Flavor chemist scarcity:Masking off-notes in high-fiber plant proteins demands specialized sensory science talent concentrated in Switzerland and Netherlands clusters.
- Cross-border label harmonization:Divergent protein content claim thresholds between FDA, EFSA, and China's SAMR force SKU fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutrition Powder Market |
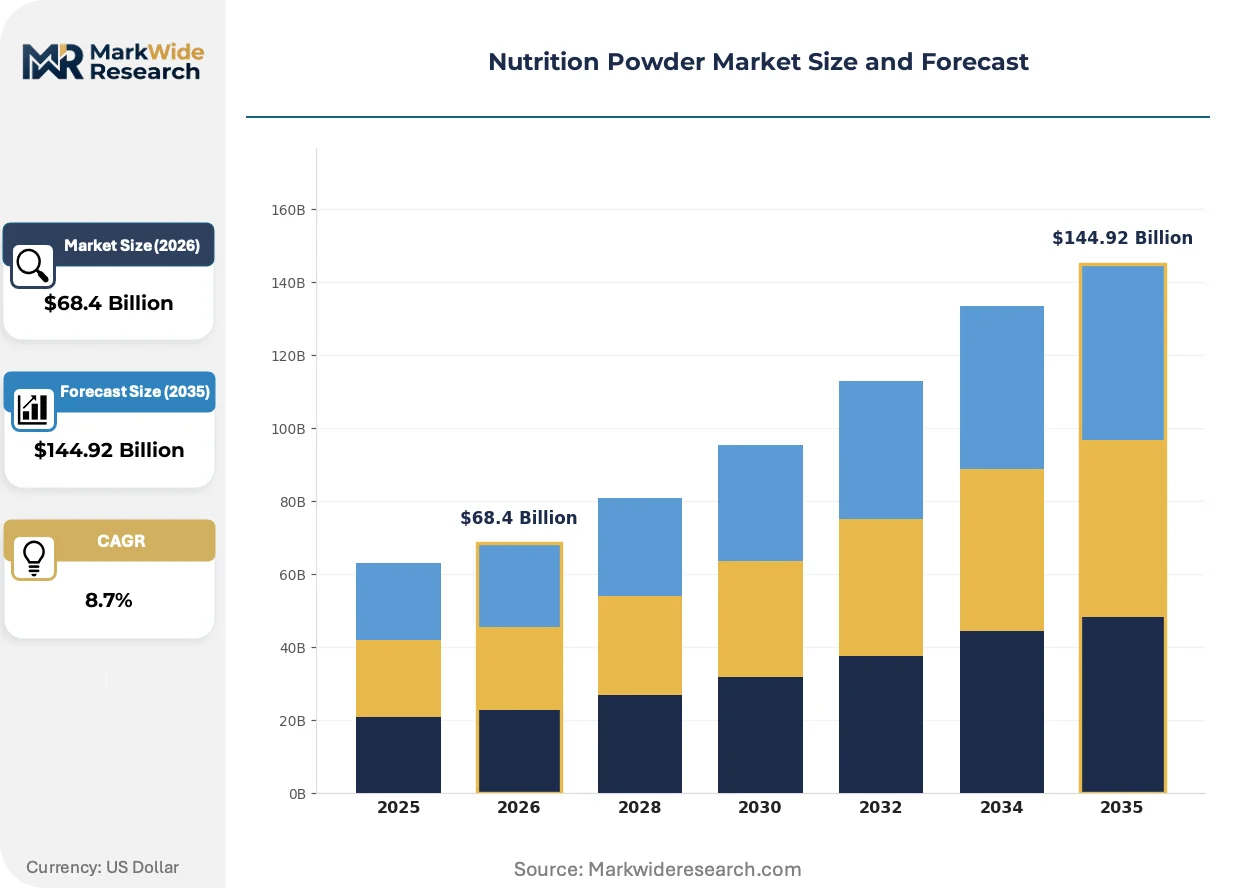
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacement, Sports Nutrition, Dietary Supplements, Protein Powder Ingredient Source: Plant-Based, Dairy-Based, Animal Protein, Synthetic Consumer Type: Athletes, Fitness Enthusiasts, Weight Management, General Health Formulation Type: Ready-to-Drink, Powder, Bar, Capsule |
| Companies Covered | Melaleuca, Transparent Labs, Amway, Orgain, MuscleTech, Herbalife, Optimum Nutrition, Isagenix, PM-International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutrition Powder Market Emerging Trajectories
Spray-drying and dry-blending equipment is converging with precision fermentation infrastructure, enabling hybrid manufacturing platforms that switch between dairy and microbial protein outputs based on input cost signals.
Precision fermentation-derived whey proteins from Perfect Day and competitors are hybridizing with conventional dairy streams in hybrid formulations that reduce lactose content while maintaining functional properties. Mid-market brands are adopting these ingredients fastest as they seek premium positioning without isolate-grade pricing. This technology is compressing the traditional whey value chain by bypassing animal agriculture entirely for specific amino acid profiles.
EFSA's novel food approval framework is extending safety dossier requirements to cover post-market surveillance for emerging protein sources. Manufacturers must now budget for multi-year toxicology studies before European commercialization. Insect protein powders face the steepest compliance burden, with several applicants withdrawing dossiers after preliminary feedback.
Direct-to-consumer subscription models are displacing mass retail velocity as the primary growth channel for specialized formulations. Specialty e-commerce platforms curating third-party tested products are capturing enthusiast segments that previously purchased through GNC and Vitamin Shoppe doorways. This shift is most visible in North American urban markets where same-day delivery logistics have matured.
Nutrition Powder Market Segmentation
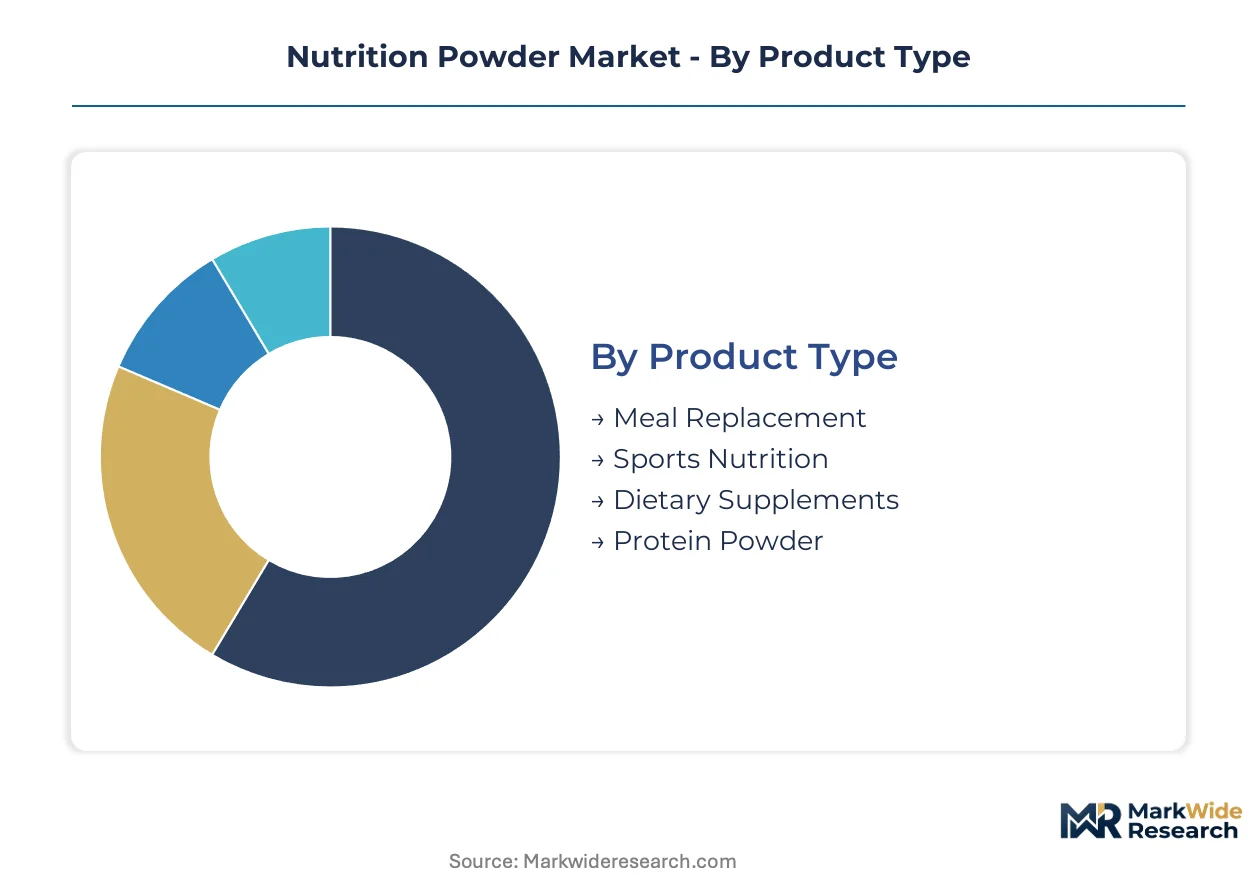
Nutrition powder segmentation reflects divergent formulation priorities across muscle synthesis support, caloric control, and micronutrient fortification. Each category channels distinct raw material sourcing, regulatory compliance burdens, and distribution economics that reshape competitive positioning.
Product Type:
Use-case spectrum spans from clinical weight management protocols to amateur athletic performance optimization, with formulation complexity and pricing power varying substantially across these endpoints.
- Meal Replacement:Macro-balanced formulations delivering 400-600 calories per serving with complete amino acid profiles and 25-30 micronutrients. Demand concentrates among busy professionals in urban China and the United States substituting breakfast and lunch occasions, constrained by refrigerated protein beverage competition and Greek yogurt substitution.
- Sports Nutrition:Peri-workout timing formulations emphasizing rapid absorption whey hydrolysates and leucine-enriched blends for muscle protein synthesis. Amateur athlete adoption across weekend warrior segments in Germany and Australia accelerates volume, though flavor R&D costs and gym-channel exclusivity fees compress mid-tier margins.
- Dietary Supplements:Targeted micronutrient fortification powders addressing specific deficiencies such as vitamin D, B-complex, or mineral gaps. Elderly consumers in Japan and South Korea drive steady demand.
- Protein Powder:Isolate and concentrate grades serving both athletic and general wellness positioning, with premium isolate pricing sustaining the largest margin pool in the category.
Established volume favors Meal Replacement; emerging adoption favors Sports Nutrition.
Ingredient Source:
Cost tier stratification separates commodity dairy derivatives from precision fermentation and enzymatically processed plant proteins, with clean-label premiums widening price bands.
- Plant-Based:Pea, oat, and fava bean proteins processed via enzymatic hydrolysis achieving 60-90 second solubility targets. China's domestic capacity expansion and MEE emissions alignment accelerate adoption, though flavor chemist scarcity in Switzerland and Netherlands clusters limits formulation quality.
- Dairy-Based:Whey concentrates and isolates from cheese manufacturing byproducts, with New Zealand drought cycles and dairy commodity swings transmitting direct margin pressure.
- Animal Protein:Egg white and collagen derivatives serving niche paleo and beauty-from-within positioning in South Korea and Brazil.
- Synthetic:Amino acid isolates and vitamin premixes manufactured via fermentation or chemical synthesis for precise dosing control in clinical applications.
Volume concentration remains with Dairy-Based; steepest expansion trajectory belongs to Plant-Based.
Consumer Type:
Customer maturity varies from performance-obsessed enthusiasts demanding third-party testing to casual wellness seekers prioritizing convenience and taste accessibility.
- Athletes:Competitive and recreational competitors requiring NSF Certified for Sport or Informed Sport verification for anti-doping compliance. Olympic and professional league procurement standards in the United States and United Kingdom drive premium pricing.
- Fitness Enthusiasts:Gym-regular consumers without competitive aspirations, representing the largest addressable population and highest churn risk as subscription models displace retail velocity.
- Weight Management:Caloric deficit seekers using portion-controlled shakes, with Herbalife and similar direct-selling networks dominating through personalized coaching bundles.
- General Health:Preventive wellness consumers seeking protein adequacy or micronutrient insurance, most price-sensitive and susceptible to whole-food substitution.
Recurring revenue lock-in succeeds with Athletes; volume scaling depends on Fitness Enthusiasts.
Formulation Type:
Supply concentration in spray-drying and agglomeration equipment shapes powder economics, while ready-to-drink alternatives capture convenience premiums.
- Ready-to-Drink:Pre-mixed beverages in aseptic packaging, commanding 40-60% price premiums over powder equivalents. Cold chain logistics in North American urban markets with mature same-day delivery infrastructure accelerate adoption.
- Powder:Dry-formulated blends manufactured via spray-drying, dry blending, or agglomeration, dominating total category volume through shelf stability and shipping efficiency.
- Bar:Compressed protein and carbohydrate matrices competing for on-the-go consumption occasions against powder convenience.
- Capsule:Encapsulated amino acids or micronutrients for precise dosing without flavor masking requirements, niche but growing in clinical and senior segments.
Margin capture favors Ready-to-Drink; manufacturing scale concentrates in Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA facility registration mandates under DSHEA anchor United States market structure, while EFSA novel food protocols and China's SAMR GB standards collectively reshape international competitive positioning across manufacturing and import channels.
United States
Amateur athlete adoption drives sports nutrition volume through gym-channel education and peri-workout timing normalization. FDA's pending modernized good manufacturing practice enforcement tightens quality disclosures and consolidates shelf access. Utah and Arizona clusters concentrate direct-selling network headquarters for personalized nutrition coaching bundles.
China
Domestic brands expand plant-based protein portfolios as busy professionals substitute breakfast occasions with macro-balanced shakes. SAMR implements GB standards for protein content claims and contaminant limits, forcing import brands to localize testing protocols. Yangtze River Delta processing facilities scale enzymatic hydrolysis capacity for oat and pea isolates aligned with MEE emissions targets.
Germany
Weekend warrior segments accelerate sports nutrition adoption through normalized protein timing education. EFSA enforces novel food approvals for emerging protein sources, extending safety dossier timelines. Cologne and Munich industrial zones concentrate flavor R&D infrastructure serving clean-label plant protein masking requirements.
Japan
Elderly consumers drive steady demand for targeted micronutrient fortification powders addressing sarcopenia and deficiency gaps. METI standards shape manufacturing quality benchmarks for export-oriented production. Osaka-Kobe industrial corridor hosts precision fermentation infrastructure development for hybrid dairy-microbial protein platforms.
Australia
Recreational competitors require NSF Certified for Sport verification for anti-doping compliance across amateur and professional segments. TGA oversight aligns with international supplement quality frameworks while permitting novel ingredient market access. Sydney and Melbourne logistics hubs enable same-day delivery infrastructure for direct-to-consumer subscription models.
Nutrition Powder Market Vendor Landscape
Direct-selling networks and retail-brand conglomerates split the market into divergent channel architectures. Consolidation pressure concentrates around compliant manufacturers with FDA-registered facilities and EFSA dossier capabilities. Three archetypes dominate: personalized coaching bundlers, gym-channel exclusivity holders, and precision fermentation ingredient adopters. Capacity expansion in Chinese plant-protein processing and strategic partnerships for telehealth integration represent the dominant competitive vectors reshaping market access.
Within the direct-selling archetype, Amway leverages Asian infrastructure for recurring revenue lock-in, while Herbalife occupies weight-management positioning through coaching-subscription bundling. Optimum Nutrition anchors North American retail presence through flavor development and gym-channel relationships. These three exemplify divergent strategic bets on channel control versus manufacturing scale versus ingredient innovation as primary competitive moats.
| Leading Market Players |
|---|
| Melaleuca |
| Transparent Labs |
| Amway |
| Orgain |
| MuscleTech |
| Herbalife |
| Optimum Nutrition |
| Isagenix |
| PM-International |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Swiss and Dutch flavor chemistry clusters tightens formulation premiums for plant-protein masking while compressing margins for mid-tier brands unable to secure specialized talent. This utilization squeeze transmits directly into pricing posture, with clean-label portfolios commanding premiums and commodity whey concentrates facing cost volatility from dairy commodity swings.
Pricing Analysis
Geographic price spreads between North American gym-channel exclusivity fees and Chinese domestic plant-protein output widen margin capture opportunities. Three-tier pricing structure across premium isolate grades, standard concentrates, and economy blends separates NSF-certified sports formulations from mass-market meal replacements. Pricing pressure stems from refrigerated protein beverage substitution in breakfast occasions. General health consumers exhibit highest price sensitivity while competitive athletes accept premiums for anti-doping verification.
Supply Chain Analysis
Tariff exposure between United States and China on whey concentrate imports dominates supply chain risk planning for North American manufacturers. Raw material sourcing draws from New Zealand dairy streams, Chinese oat and pea isolate capacity, and Swiss precision fermentation infrastructure. Single-source vulnerability concentrates in flavor chemist talent pools centered around Cologne and Zurich. Distribution runs through direct-to-consumer subscription platforms displacing traditional retail velocity in urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized sensory science talent for plant-protein masking represents the critical capability gap constraining formulation quality and clean-label expansion. Brands unable to secure this expertise face permanent margin compression against competitors with secured R&D partnerships.
For Market Incumbents: Build regulatory dossier capabilities as a defensive moat against EFSA novel food approval timelines extending European market access. Invest in FDA-registered facility consolidation to capture shelf access from culled marginal operators. Deepen backward integration into Chinese Yangtze River Delta processing capacity to secure plant-protein supply aligned with MEE emissions targets. For New Entrants and Emerging Players: Build out telehealth bundle integration targeting sarcopenia-formulation white space in adults over 65, the most underpenetrated consumer segment relative to sports positioning. Senior nutrition applications in Japan and South Korea offer lowest competitive density. Partner with registered dietitian networks for recurring revenue lock-in rather than competing on retail shelf presence. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation ingredient adopters with hybrid manufacturing platforms capable of switching between dairy and microbial protein outputs. Long-term viability favors manufacturers with enzymatic hydrolysis capabilities achieving solubility parity with whey isolates. Watch EFSA dossier withdrawal rates for insect protein applicants as signal of regulatory burden intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Flavor R&D Partnership | Swiss and Dutch sensory science clusters enable clean-label plant-protein masking quality. |
| Telehealth Bundle Launch | Registered dietitian consultations paired with powder subscriptions create recurring revenue lock-in. |
| Precision Fermentation Adoption | Perfect Day-derived whey proteins bypass animal agriculture for specific amino acid profiles. |
| China Domestic Capacity Expansion | Yangtze River Delta enzymatic hydrolysis facilities align with MEE dual carbon emissions targets. |
| Anti-Doping Certification Investment | NSF Certified for Sport verification captures Olympic and professional league procurement standards. |
Methodological Framework
The analysis maps sports nutrition, meal replacement, and senior fortification sub-sectors, each validated through formulation scientists, gym-channel procurement managers, and direct-selling network operators. Primary interviews with flavor chemists, regulatory affairs leads at supplement manufacturers, and telehealth platform executives combined with secondary validation from FDA facility registration databases, EFSA novel food submission records, and Chinese SAMR GB standard filings. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates from customs trade data and retail audit channels.
Assumptions held FDA modernized GMP enforcement timelines and EFSA environmental claim substantiation thresholds fixed across the projection horizon, while varying dairy commodity price scenarios and plant-protein adoption curves. Segmentation dimensions modeled include product type, ingredient source, consumer archetype, and formulation format. CAGRs derived from fitted growth curves applied to base-year sizing, with precision fermentation cost-reduction trajectories and amateur athlete penetration rates as key industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic brands or rapid precision fermentation scale-up would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Omega-3 Fish Oils Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Prenatal Vitamin Supplements Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Nutritional Oil Powder Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Vitamins and Minerals Market