
 South America Meal Replacement Products Market | 2026-2036
South America Meal Replacement Products Market Size, Share, and Industry Trends Forecast 2026-2036
South America Meal Replacement Products Market Analytics
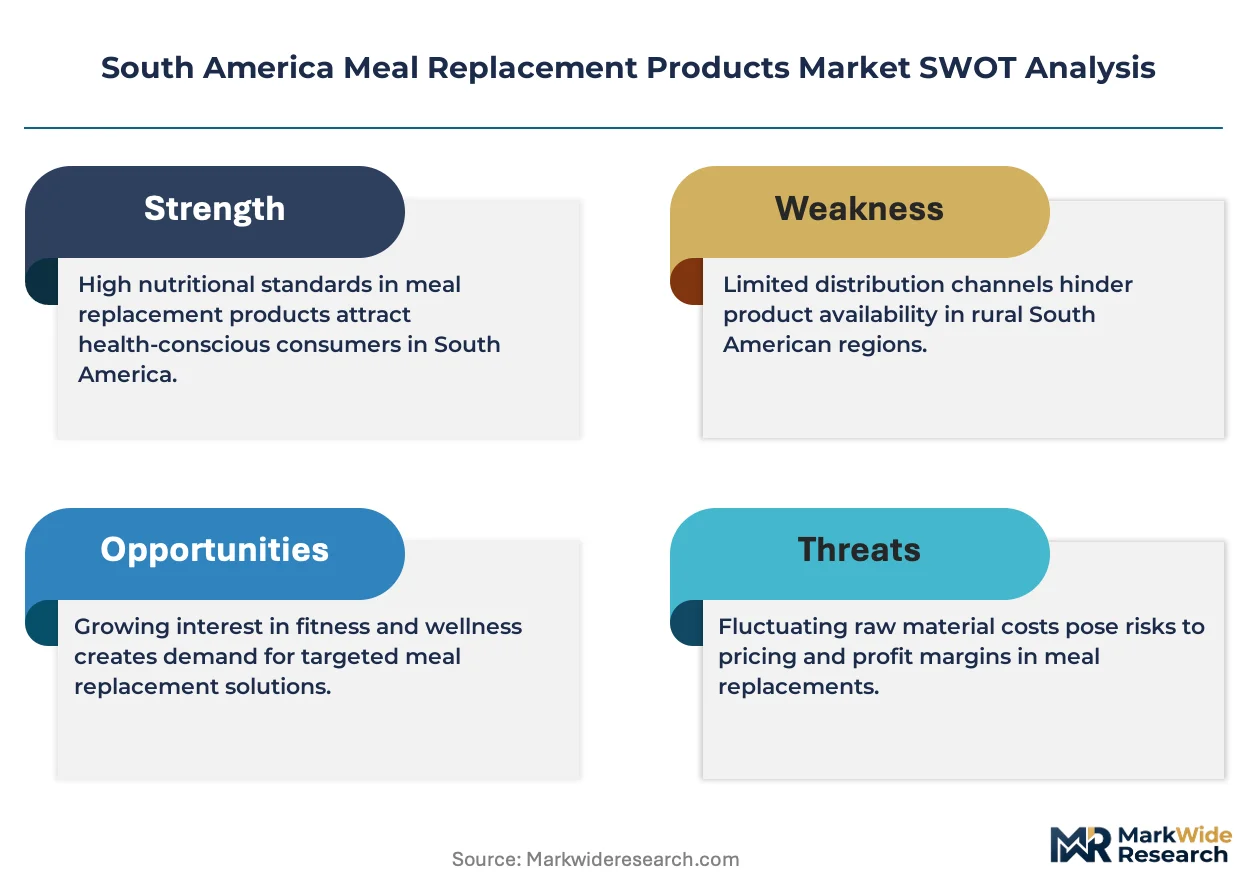
ANVISA's updated nutrition labeling requirements is pivoting formulation costs upward for new entrants. Herbalife Nutrition leverages its direct-sales infrastructure to sustain margins across Brazilian metro corridors. Glanbia PLC anchors its regional supply through specialized protein sourcing partnerships. Nestlé S.A. competes via shelf-space dominance in mainstream retail channels.
South America meal replacement products are shelf-stable or refrigerated consumables engineered to deliver complete macronutrient profiles in single-serve formats, typically containing 15-30 grams of protein, controlled carbohydrate loads, and micronutrient fortification for metabolic completeness. These products serve industrial purposes spanning clinical nutrition support, athletic performance optimization, and convenience-driven dietary substitution for time-constrained consumers. Powder formats dominate volume throughput due to lower logistics costs and extended shelf stability, while ready-to-drink lines capture premium margin pools through convenience positioning in Brazilian and Argentinean convenience retail. The vegan formulation segment is expanding fastest as ingredient biotechnology reduces plant-protein cost premiums.
ANVISA governs product registration and health claims enforcement across Brazil, while Argentina's national food safety authority mandates parallel compositional disclosures for imported meal replacements. Chile's front-of-package warning label law shapes reformulation priorities for brands seeking Andean market access. Stakeholders must monitor evolving protein-content verification protocols and adapt label architectures before enforcement windows tighten.
Market Dynamics
ANVISA's nutrition labeling overhaul is compressing formulation timelines and forcing mid-tier manufacturers to accelerate compliance investments or exit Brazil's southeastern corridor entirely.
Growth Catalysts
- ANVISA Labeling Modernization:Updated protein-content verification protocols are creating tiered compliance benchmarks that reward pre-certified suppliers with expedited shelf access.
- São Paulo Fitness Cluster:Gym culture density in Brazil's southeastern corridor sustains demand for 20-30 gram protein formats among time-scarce professionals seeking meal substitution.
- Precision Fermentation:Ingredient biotechnology is collapsing plant-protein cost premiums, enabling vegan formulation parity with whey-based alternatives.
Market Restraints
- Whey Protein Concentrate Volatility:Argentina's dairy export restrictions periodically constrain raw material flows to Brazilian processors.
- Import Tariff Cascades:Mercosur's non-automatic licensing requirements for vitamin premixes extend lead times for reformulated SKUs.
- Refrigerated RTD Logistics:Cold-chain gaps in secondary Brazilian cities limit ready-to-drink penetration outside metro corridors.
Strategic Opportunities
- Colombian Andean Corridor:Bogotá's emerging corporate wellness programs show underpenetrated demand for shelf-stable workplace formats.
- Chilean Front-of-Package Compliance:Brands achieving warning-label exemption status gain preferential retail positioning in Santiago's supermarket channels.
- Direct-to-Consumer Subscription:Specialized protein sourcing partnerships enable personalized macronutrient profiling bypassing traditional retail markup.
Industry Challenges
- Reformulation Talent Scarcity:Brazil's food science programs produce insufficient technologists versed in micronutrient stability under ANVISA's tightened disclosure windows.
- Cross-Border Label Harmonization:Divergent Argentine and Chilean compositional disclosure requirements force SKU proliferation for Andean market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Meal Replacement Products Market |
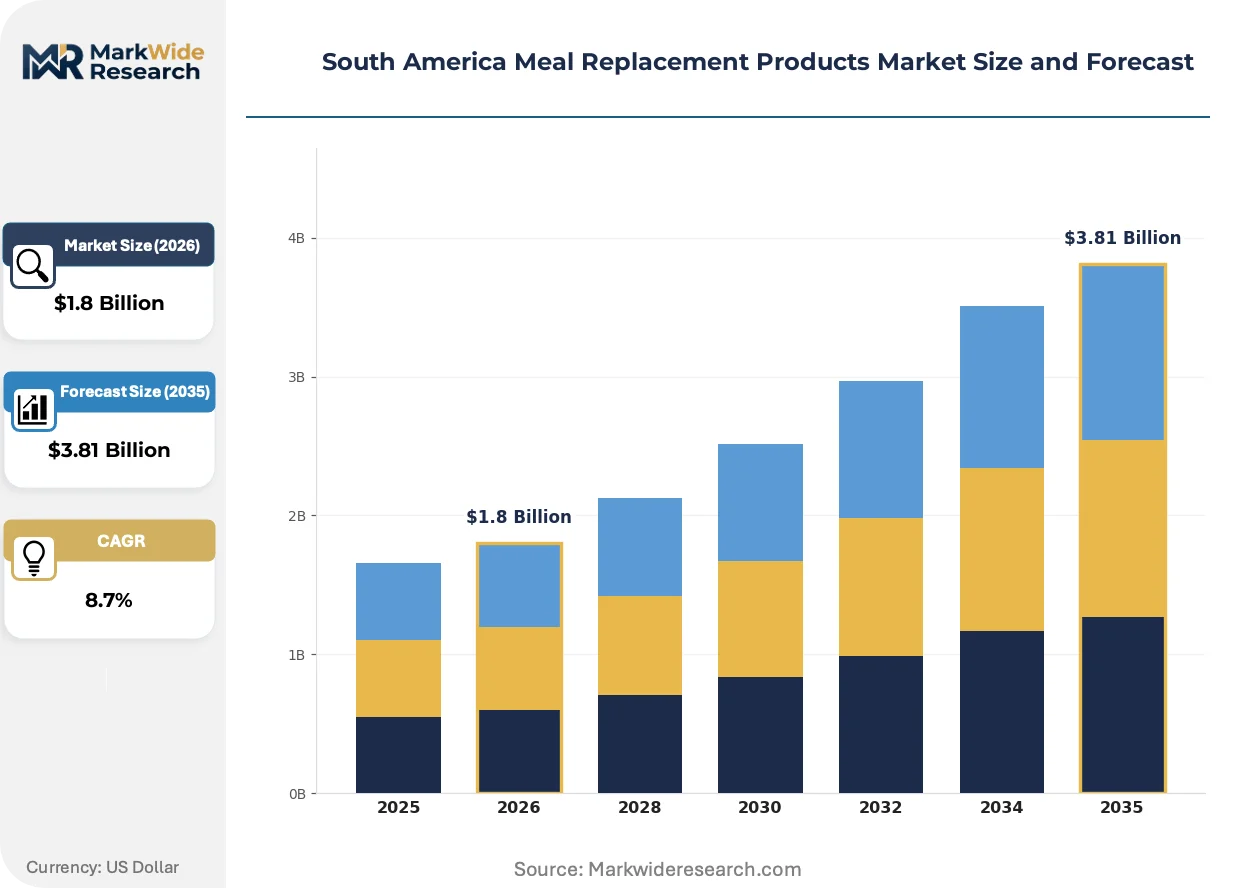
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shakes, Bars, Powders, Ready-to-Drink End User: Fitness Enthusiasts, Weight Watchers, Busy Professionals, Seniors Distribution Channel: Supermarkets, Online Retail, Health Stores, Gyms Formulation: Protein-Rich, Low-Calorie, Gluten-Free, Vegan |
| Companies Covered | Bob's Red Mill Natural Foods, Probiotica Supplements, Herbalife Nutrition, Amway GmbH, Quest Nutrition LLC, Glanbia PLC, biO2 Organic Comercio de Alimentos Ltd, Nestlé S.A., Alpina SA, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Meal Replacement Products Market Evolving Landscape
Biotechnology-enabled ingredient sourcing and regulatory disclosure architectures are compressing product development cycles while fragmenting competitive advantage sources across formulation, compliance, and channel control.
Precision fermentation of pea and fava protein isolates is converging with enzymatic hydrolysis to deliver amino acid completeness matching dairy-based benchmarks. Argentine ingredient startups are licensing these platforms to Brazilian contract manufacturers at 40% cost reduction versus 2019 import parity. This technology convergence is converging with legacy powder manufacturing infrastructure, enabling mid-tier brands to launch vegan lines without captive biotech investment.
Chile's front-of-package warning label law is mandating sugar and sodium threshold compliance for retail placement eligibility. Brands exceeding thresholds face automatic relegation to specialty channels with 60% lower foot traffic. The Andean premium segment is responding with stevia-monkfruit blends and savory flavor profiles that circumvent sweetener disclosure triggers.
Corporate procurement departments in São Paulo and Buenos Aires are consolidating vendor relationships through annual macronutrient specification contracts replacing transactional spot purchasing. This buyer concentration is compressing switching flexibility and rewarding suppliers with ISO 22000 certification and dedicated account engineering support. The shift is most visible in Brazil's pharmaceutical and financial services verticals, where wellness stipends now cover 70% of employee meal replacement expenditure.
South America Meal Replacement Products Market Segmentation
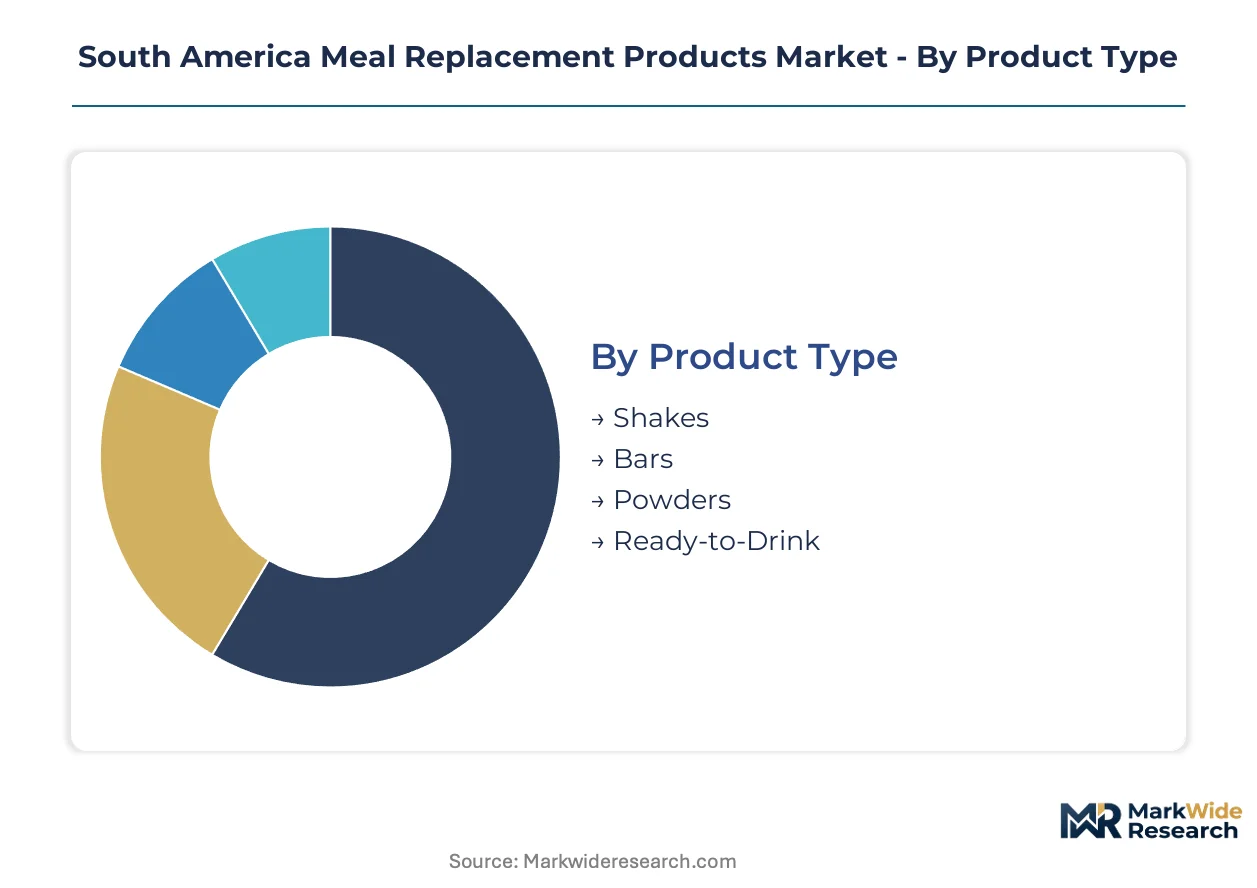
Meal replacement manufacturers in South America configure production lines around four intersecting dimensions. Product format dictates logistics infrastructure, end-user profile governs protein load specifications, channel selection determines margin architecture, and formulation type shapes raw material sourcing.
Product Type:
Buyers differentiate by convenience threshold versus unit economics tolerance.
- Powders:Bulk dry blends containing 15-30 gram protein servings dominate Brazilian manufacturing throughput. São Paulo's pharmaceutical and financial services sectors purchase these formats through corporate wellness stipends covering 70% of employee expenditure.
- Ready-to-Drink:Shelf-stable liquid formulations in single-serve bottles command premium positioning in Argentine convenience retail. Cold-chain gaps in secondary Brazilian cities constrain penetration outside metro corridors.
- Shakes:Pre-mixed liquid products requiring refrigeration occupy niche positioning in gym-adjacent channels.
- Bars:Solid compressed formats with binding agents and coating layers target travel and workplace consumption occasions.
Volume sits with powders; growth tilts toward ready-to-drink.
End User:
Protein load requirements and price sensitivity separate these buyer pools.
- Fitness Enthusiasts:Gym culture density in Brazil's southeastern corridor sustains demand for 20-30 gram protein formats. These consumers prioritize amino acid completeness and bioavailability metrics.
- Busy Professionals:Time-scarce workers in São Paulo and Buenos Aires substitute powder formats for breakfast and lunch occasions. Corporate procurement departments now consolidate vendor relationships through annual macronutrient specification contracts.
- Weight Watchers:Calorie-controlled formulations with controlled carbohydrate loads address metabolic management goals.
- Seniors:Texture-modified and micronutrient-fortified products serve clinical nutrition support applications.
Revenue concentrates with fitness enthusiasts; expansion tilts toward busy professionals.
Distribution Channel:
Margin capture and brand control trade off across these pathways.
- Supermarkets:Shelf-space dominance in mainstream Brazilian retail channels requires compliance with ANVISA's updated nutrition labeling protocols. Brands achieving pre-certification gain expedited shelf access.
- Online Retail:Direct-to-consumer subscription models enable personalized macronutrient profiling that bypasses traditional retail markup. Specialized protein sourcing partnerships support this channel's customization requirements.
- Health Stores:Specialty retail in Santiago and Bogotá carries premium-positioned SKUs with warning-label exemption status under Chilean front-of-package law.
- Gyms:Point-of-sale placement in São Paulo fitness clusters captures impulse substitution purchases.
Volume flows through supermarkets; margin expansion tilts toward online retail.
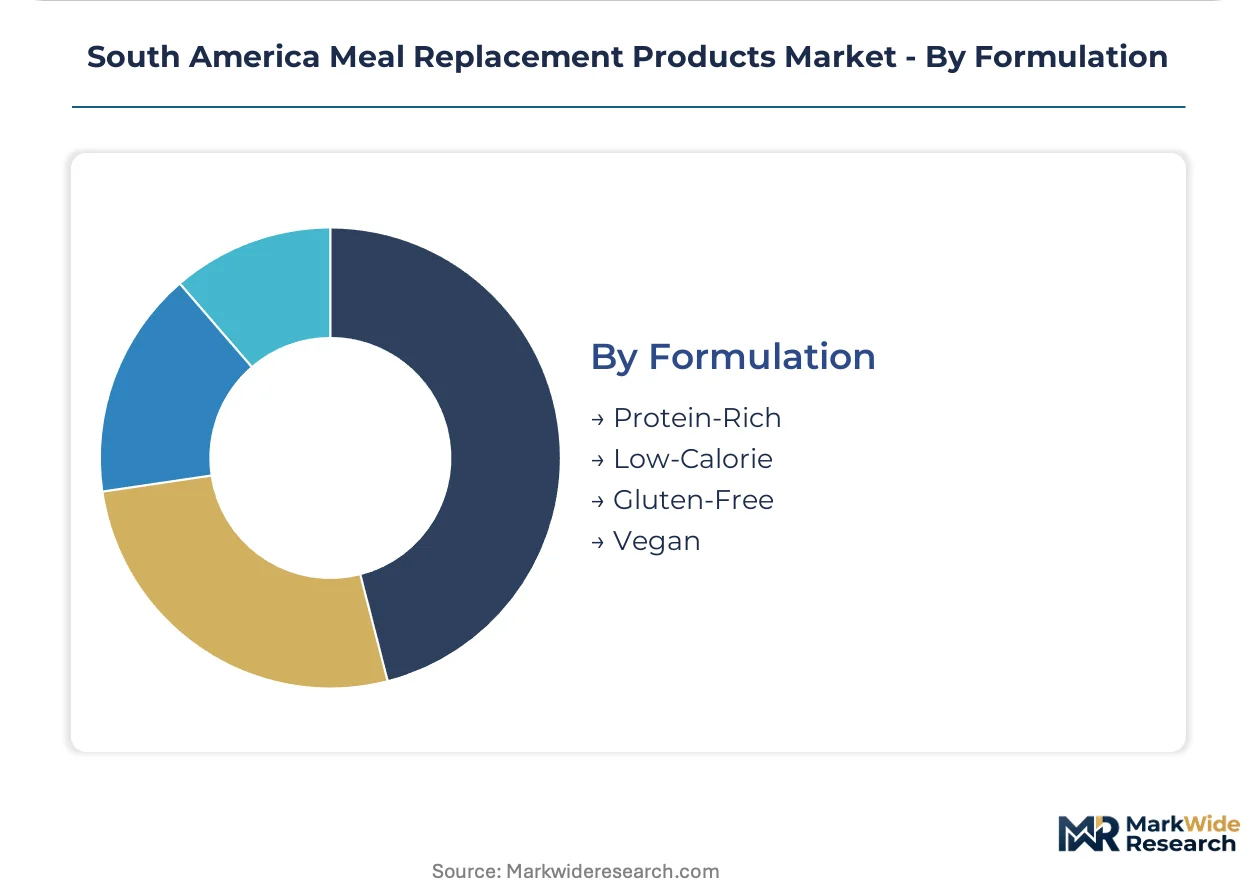
Formulation:
Ingredient biotechnology and regulatory disclosure requirements reshape competitive positioning.
- Protein-Rich:Formulations delivering 20-30 grams per serving anchor demand in Brazil's southeastern corridor. ANVISA's tightened protein-content verification protocols reward suppliers with pre-certified laboratory documentation.
- Vegan:Precision fermentation of pea and fava protein isolates collapses cost premiums versus whey-based alternatives. Argentine ingredient startups license these platforms to Brazilian contract manufacturers at 40% cost reduction versus 2019 import parity.
- Low-Calorie:Calorie-restricted profiles with stevia-monkfruit blends circumvent Chilean sugar disclosure triggers.
- Gluten-Free:Allergen-controlled formulations address celiac and sensitivity segments with dedicated production line requirements.
Volume rests with protein-rich; steepest expansion trajectory belongs to vegan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives concentrate import-processing capacity for vitamin premixes and protein isolates, anchoring northern Brazil's role in regional supply chains. This fiscal architecture shapes cross-border manufacturing decisions across the continent.
Brazil
São Paulo's pharmaceutical and financial services sectors drive corporate wellness procurement at scale, with gym culture density in the southeastern corridor sustaining 20-30 gram protein format demand. ANVISA's updated nutrition labeling protocols compress formulation timelines for new entrants. Belo Horizonte's contract manufacturing cluster absorbs precision fermentation technology from Argentine ingredient licensors.
Argentina
Buenos Aires professionals substitute powder formats for breakfast and lunch occasions, generating concentrated demand among time-scarce white-collar workers. The national food safety authority mandates parallel compositional disclosures for imported meal replacements. Rosario's dairy processing belt faces periodic export restrictions that constrain whey protein concentrate flows to Brazilian processors.
Chile
Santiago's supermarket channels reward brands achieving front-of-package warning label exemption status with preferential retail positioning. The national food safety regulator enforces sugar and sodium thresholds that trigger automatic channel relegation for non-compliant SKUs. Valparaíso's logistics hub supports Andean distribution for shelf-stable formats.
Colombia
Bogotá's emerging corporate wellness programs show underpenetrated demand for workplace-compatible shelf-stable formats. The national food and drug surveillance institute oversees product registration and health claims verification. Medellín's manufacturing base processes imported protein isolates for regional redistribution.
Peru
Lima's urban fitness culture adopts protein-rich formulations through gym-adjacent retail channels and direct-to-consumer subscription models. The national health authority maintains import licensing requirements for vitamin-fortified products. Callao's port infrastructure handles Pacific-facing ingredient shipments for Andean contract manufacturers.
South America Meal Replacement Products Market Competitive Landscape
Brazilian producers anchor one tier of supply; Argentine and Chilean specialists hold complementary positions in ingredient technology and compliance architecture. The vendor base arranges around three strategic archetypes: direct-sales infrastructure operators, retail shelf-space dominators, and biotechnology-enabled contract manufacturers. Consolidation pressures favor pre-certified suppliers with expedited ANVISA shelf access. Capacity expansion and specialized protein sourcing partnerships represent the dominant competitive moves.
Within the direct-sales tier, Herbalife Nutrition exemplifies infrastructure-heavy positioning across Brazilian metro corridors. Nestlé S.A. anchors retail shelf-space dominance in mainstream supermarket channels. Glanbia PLC occupies a position tied to specialized protein sourcing partnerships that support regional supply security. These three entities represent distinct archetypes: relationship-driven distribution, mass-market retail penetration, and upstream ingredient control.
| Leading Market Players |
|---|
| Bob's Red Mill Natural Foods |
| Probiotica Supplements |
| Herbalife Nutrition |
| Amway GmbH |
| Quest Nutrition LLC |
| Glanbia PLC |
| biO2 Organic Comercio de Alimentos Ltd |
| Nestlé S.A. |
| Alpina SA |
| Others |
Value Network & Pricing Analysis
Precision fermentation technology adoption simultaneously collapses plant-protein input costs and concentrates formulation expertise among Brazilian contract manufacturers with Argentine licensing partnerships. This production-method transition rewards pre-certified suppliers with expedited ANVISA shelf access while squeezing mid-tier competitors unable to absorb compliance investments.
Pricing Analysis
Lead-time-driven pricing separates expedited formulation certification from spot-market powder availability, with ANVISA pre-certified suppliers commanding shelf-access premiums. Price differentiation rests on ISO 22000 certification tier and dedicated account engineering support. Cost compression in standard powder tiers intensifies as corporate procurement departments consolidate annual contracts. Busy professionals through corporate wellness programs show lowest price sensitivity; weight watchers in secondary cities exhibit highest.
Supply Chain Analysis
Reverse-logistics infrastructure for expired vitamin premixes and reformulated SKUs remains underdeveloped across Brazilian secondary cities, forcing write-offs. Geographic supply concentrates in Argentina for whey protein concentrate, Brazil for contract manufacturing capacity, and Chile for stevia-monkfruit sweetener inputs. Raw material dependencies include pea and fava protein isolates, vitamin premixes, and enzymatic hydrolysis agents. Single-source vulnerability runs through Rosario's dairy processing belt during export restriction windows. Distribution runs through São Paulo's pharmaceutical and financial services procurement departments for bulk corporate contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where ANVISA's tightened protein-content verification protocols force undercapitalized mid-tier manufacturers toward exit. Pre-certified suppliers capture disproportionate shelf access while compliance laggards face channel relegation.
For Market Incumbents: Cement shelf-space dominance through accelerated ANVISA pre-certification investments before enforcement windows tighten. Anchor supply security via specialized protein sourcing partnerships with Argentine precision fermentation licensors. Defend against biotechnology-enabled contract manufacturers by locking multi-year corporate wellness procurement contracts with dedicated account engineering support. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models in Bogotá's underpenetrated corporate wellness segment, bypassing supermarket shelf-space barriers. Target Chilean warning-label exemption status through stevia-monkfruit reformulation to secure preferential retail positioning in Santiago's health stores. Exploit reformulation talent scarcity by recruiting Brazilian food science programs' limited micronutrient stability specialists. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by direct-sales infrastructure operators seeking Brazilian metro corridor density. Long-term viability favors pre-certified suppliers with captive laboratory documentation and ISO 22000 certification. The signal to watch is ANVISA enforcement action against non-compliant SKUs, which would accelerate consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Pre-Certification Investment | Expedited shelf access in São Paulo's supermarket channels rewards early compliance expenditure. |
| Precision Fermentation Licensing | Argentine technology transfer to Brazilian contract manufacturers collapses vegan formulation cost premiums. |
| Corporate Wellness Contract Consolidation | Annual macronutrient specification agreements with pharmaceutical and financial services sectors lock revenue. |
| Direct-to-Consumer Subscription Launch | Bypasses traditional retail markup while enabling personalized macronutrient profiling for Bogotá professionals. |
| Chilean Warning-Label Exemption Achievement | Stevia-monkfruit reformulation secures preferential positioning in Santiago's supermarket channels. |
Research Methodology
Document review covered ANVISA regulatory filings, Chilean front-of-package compliance databases, and Brazilian customs trade records, complemented by interviews with contract manufacturing executives, corporate wellness procurement managers, and food science program directors. Secondary validation drew from pharmaceutical sector wellness stipend disclosures, gym chain point-of-sale data, and ingredient biotechnology patent filings. Bottom-up demand modeling triangulated against top-down market sizing across powder, ready-to-drink, and bar format segments.
Output metrics span volume tonnage and value realization across product type, end-user profile, distribution channel, and formulation category dimensions throughout the forecast period. CAGRs derive from regression analysis of protein-content verification protocol adoption curves and corporate wellness program penetration rates. Forecast inputs include precision fermentation cost-reduction trajectories and ANVISA enforcement intensity scenarios.
The model assumes a particular technology adoption path; alternative pathways for enzymatic hydrolysis platform maturation would alter the outlook for vegan-whey price parity timing. Forecasts reflect documented assumptions regarding ANVISA compliance window extensions and Mercosur vitamin premix licensing efficiency. Practitioners should monitor Argentine dairy export restriction announcements and Chilean sugar threshold enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Global Nutraceutical Ingredients Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Fat Powders Market
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Global Docosahexaenoic Acid (DHA) Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Vegan Protein Market