
 Prenatal Vitamin Supplements Market | 2026-2036
Prenatal Vitamin Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Prenatal Vitamin Supplements Market Analysis
Microencapsulation technology is reshaping nutrient bioavailability in prenatal formulations, enabling timed-release delivery of iron and folate that reduces gastrointestinal side effects. Bayer AG leverages its pharmaceutical heritage to sustain clinical credibility among obstetrician-gynecologist networks. Garden of Life differentiates through whole-food sourcing and third-party certifications that command premium shelf positioning in health stores.
Prenatal vitamin supplements are multi-nutrient dietary preparations containing folic acid, iron, calcium, DHA, and vitamin D, engineered to meet elevated nutritional requirements during gestation and lactation. Softgels dominate volume due to superior lipid-soluble nutrient delivery, while chewables capture growing preference among consumers with pill aversion. Natural and organic formulations extract margin premiums as clean-label procurement shifts purchasing patterns across online retail and pharmacy channels.
FDA Current Good Manufacturing Practices and EFSA health claim evaluations shape formulation standards and market access across North America and Europe. The EU's MDR and F-Gas Regulation indirectly influence excipient sourcing and packaging sustainability requirements. Stakeholders must monitor evolving pharmacovigilance frameworks and adapt label transparency to preempt regulatory friction in priority markets.
Market Dynamics
Microencapsulation technology is collapsing traditional formulation trade-offs between nutrient stability and gastrointestinal tolerability, forcing manufacturers to retool production lines or surrender shelf space to bioavailability innovators.
Growth Catalysts
- FDA Current Good Manufacturing Practices:Stringent quality mandates elevate barrier-to-entry for low-cost competitors, concentrating volume among certified manufacturers with validated analytical capabilities.
- Direct-to-consumer subscription models:Recurring revenue structures lock in millennial cohorts through personalized dosing algorithms and automated replenishment cycles.
- Clean-label procurement:Third-party certifications from NSF International and USP Verified programs command premium positioning in pharmacy and specialty retail channels.
Market Restraints
- Fish oil supply concentration:Peruvian and Chilean anchovy fisheries dominate DHA raw material sourcing, exposing formulations to El Niño-driven catch volatility and marine stewardship certification delays.
- Iron excipient costs:Ferrous bisglycinate and carbonyl iron variants trade at 3-4x ferrous sulfate prices, compressing margins on value-tier private label offerings.
- EU F-Gas Regulation:Refrigeration-dependent probiotic and omega-3 formulations face escalating cold-chain compliance costs across distribution networks.
Strategic Opportunities
- Postnatal extension formulations:Lactation-supporting nutrient complexes targeting the twelve-month postpartum window capture recurring demand beyond gestation.
- India FSSAI functional food pathways:Emerging regulatory clarity on prenatal gummies and fortified beverages opens access to 25 million annual births.
- Telehealth-integrated sampling:Obstetrician-dispensed starter packs bundled with virtual consultation platforms convert clinical endorsement into subscription enrollment.
Industry Challenges
- Phytochemical standardization:Whole-food sourced folate from lemon peel and spinach extracts exhibits 15-40% potency variance between harvest lots, complicating label claim verification.
- Cross-border e-commerce harmonization:Divergent maximum permitted levels for vitamin A and iodine across national pharmacopeias trigger customs detention and relabeling expenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prenatal Vitamin Supplements Market |
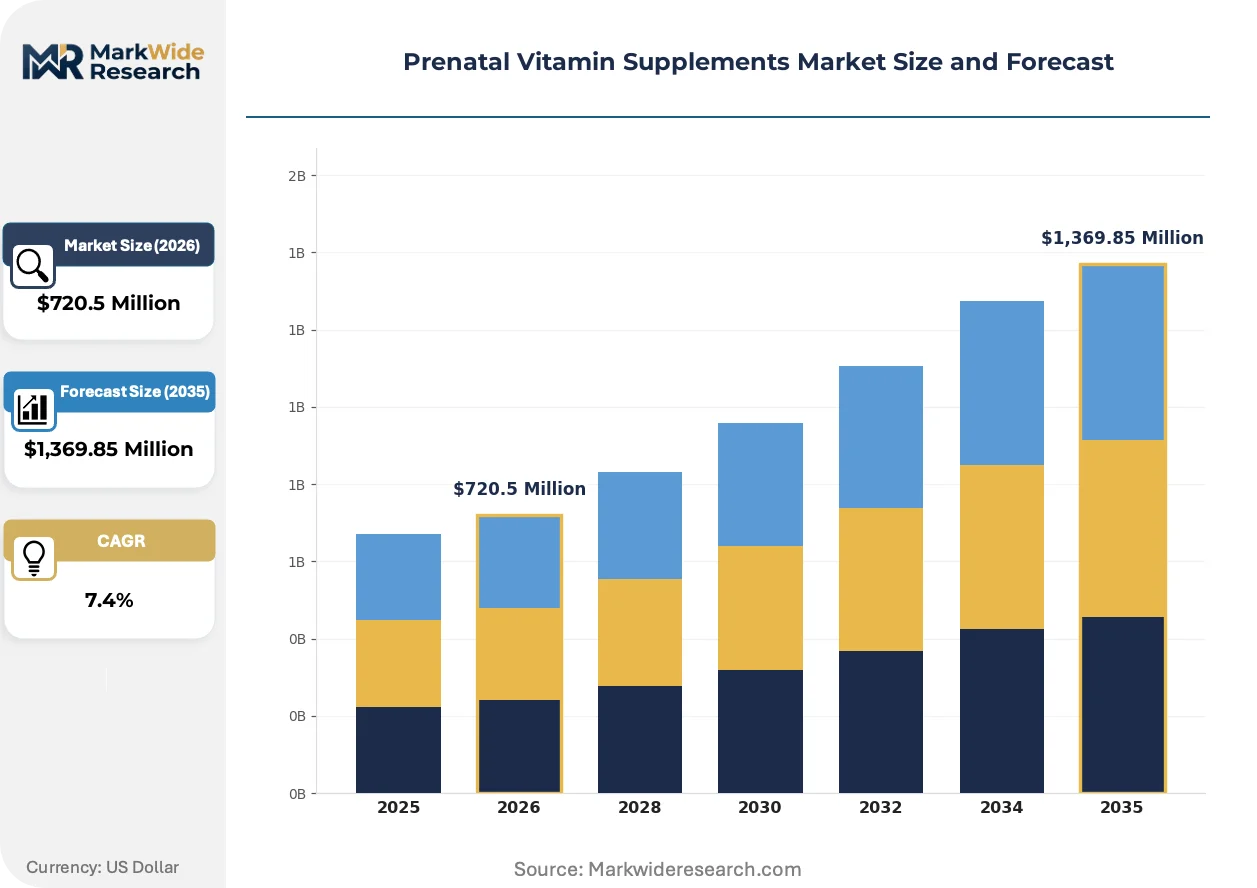
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,369.85 Million |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Chewables, Tablets, Powders Formulation: Natural, Synthetic, Organic, Non-GMO Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores Target Audience: Expectant Mothers, Healthcare Professionals, Prenatal Clinics, Gynecologists |
| Companies Covered | Church & Dwight Co., Inc., Bayer AG, Abbott, Garden of Life, Country Life, Nature Made, Pharmavite, Nordic Naturals, MegaFood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prenatal Vitamin Supplements Market Emerging Trajectories
Formulation science and distribution architecture are undergoing parallel transformation as bioavailability engineering converges with personalized delivery mechanisms.
Liposomal encapsulation is collapsing absorption rate differentials between synthetic and food-derived nutrients, enabling manufacturers to substitute lower-cost raw materials without sacrificing serum concentration targets. Millennial expectant mothers in urban United States clusters are adopting these premium formats at 2-3x the rate of conventional tablets. The technology is compressing R&D amortization periods by validating equivalence claims through pharmacokinetic studies rather than multi-year clinical trials.
EFSA health claim evaluations are tightening permissible pregnancy-related marketing language across European Union member states, forcing brands to retire unqualified neurological development assertions. Manufacturers must now anchor promotional materials to approved Article 13.1 and 13.5 claims or risk enforcement action from national competent authorities. Softgel and gummy formats targeting German and French pharmacy channels are most affected, with label revision cycles extending 8-14 months.
Millennial cohorts are bypassing traditional retail pharmacy counseling in favor of algorithm-driven online subscription platforms that adjust micronutrient ratios across trimesters. Direct-to-consumer brands are capturing prescription-adjacent trust through telehealth partnerships with board-certified obstetrician-gynecologists. This channel rotation is most pronounced in United States coastal metropolitan markets where same-day delivery infrastructure supports just-in-time replenishment patterns.
Prenatal Vitamin Supplements Market Segmentation
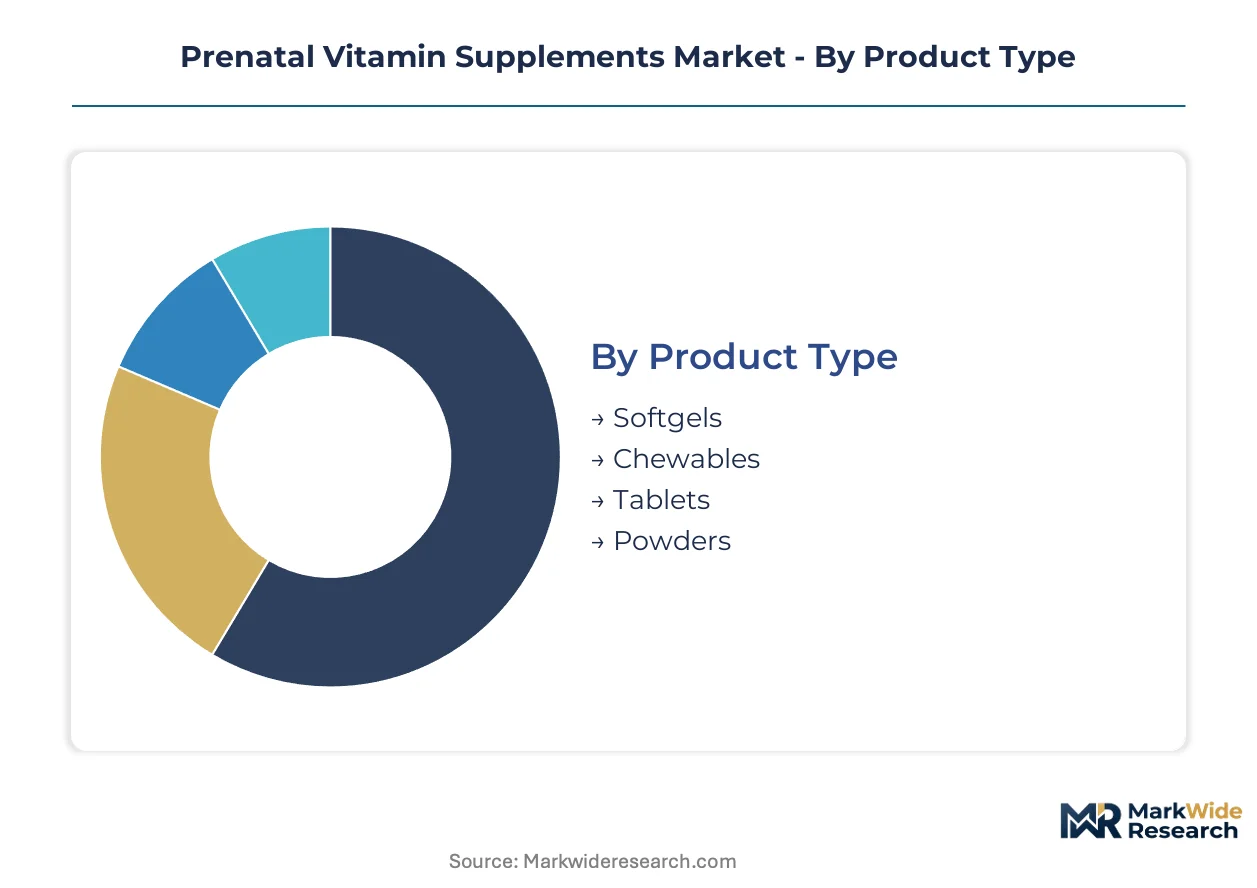
Prenatal vitamin segmentation reflects divergent consumer priorities across bioavailability, sourcing ethics, and purchase convenience. Manufacturers must align formulation architecture and channel strategy to capture value from distinct pregnancy-stage needs and professional endorsement pathways.
Product Type:
Mature formats dominate pharmacy shelves while emerging delivery systems capture digitally-native cohorts seeking tolerability improvements.
- Softgels:Lipid-based encapsulation enables superior absorption of DHA and fat-soluble vitamins A, D, E, and K. Demand concentrates among second and third trimester mothers in United States coastal metropolitan markets where gastrointestinal sensitivity peaks and compliance with large tablet regimens drops. The format commands shelf space through obstetrician dispensing partnerships.
- Chewables:Palatable gummy matrices address pill aversion affecting 30-40% of first-trimester women experiencing nausea. Growth accelerates in direct-to-consumer subscription channels targeting millennial expectant mothers who prioritize convenience over unit cost.
- Tablets:Compressed multi-nutrient platforms remain the default for Medicaid reimbursement programs and hospital formulary procurement due to manufacturing scale and stability.
- Powders:Flexible dosing formats blend into smoothies for women with severe morning sickness who cannot tolerate solid oral delivery.
Softgels retain volume leadership; chewables hold the steepest expansion curve.
Formulation:
Cost tier stratification separates premium-positioned certifications from commodity synthetic sourcing.
- Natural:Whole-food extracted nutrients from spinach, citrus, and algae biomass carry 25-35% price premiums over synthetic equivalents. United States health store channels and Whole Foods Market procurement standards drive specification requirements.
- Synthetic:Laboratory-synthesized folic acid, iron salts, and vitamin D3 dominate pharmacy chains and private label programs where cost-per-day metrics determine formulary inclusion.
- Organic:USDA Organic and EU Organic certification compliance restricts excipient sourcing to non-GMO, pesticide-free supply chains. German pharmacy channels and French maternity clinic dispensing favor this tier.
- Non-GMO:Identity-preserved supply chain documentation meets Project Verified standards without full organic compliance, capturing mid-market positioning in United States mass retail.
Synthetic formulations retain volume leadership; organic holds the steepest expansion curve.
Distribution Channel:
Customer type bifurcation separates self-directed online purchasers from professionally-guided pharmacy buyers.
- Online Retail:Algorithm-driven subscription platforms with trimester-adjusted dosing capture recurring revenue from millennial cohorts in United States urban markets. Same-day delivery infrastructure supports just-in-time replenishment patterns.
- Pharmacies:CVS Health and Walgreens counseling programs leverage pharmacist credentialing to convert walk-in pregnancy test purchasers into supplement regimens. Third-party certification displays at point-of-sale influence selection.
- Supermarkets:Mass retail placement in Target and Walmart prenatal aisles captures unplanned purchases during routine grocery trips, typically value-tier private label selection.
- Health Stores:GNC and Vitamin Shoppe specialty retail emphasizes NSF International and USP Verified positioning for consumers prioritizing quality verification over convenience.
Pharmacies retain volume leadership; online retail holds the steepest expansion curve.
Target Audience:
Application focus varies between end-user consumption and professional endorsement intermediation.
- Expectant Mothers:Direct consumption decisions increasingly follow Instagram and TikTok influencer recommendations, with clean-label scanning via Yuka and Think Dirty apps filtering permissible ingredients.
- Healthcare Professionals:Obstetrician-gynecologist networks in United States academic medical centers influence brand selection through American College of Obstetricians and Gynecologists continuing education programming.
- Prenatal Clinics:Hospital-affiliated maternity programs in United Kingdom NHS Trusts and Kaiser Permanente integrated systems dispense starter packs at first prenatal visits.
- Gynecologists:Private practice dispensing arrangements in Germany and Switzerland bundle supplements with consultation fees, capturing margin from insurance reimbursement pathways.
Expectant mothers retain volume leadership; healthcare professionals hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial expectant mothers in the United States drive the highest per-capita spending on clean-label prenatal formulations, while pharmacy-based counseling programs in Germany and subscription platforms in the United Kingdom reshape how pregnancy-stage nutrients reach consumers.
United States
Direct-to-consumer subscription models with trimester-adjusted algorithms lock in recurring revenue from urban coastal mothers. FDA Current Good Manufacturing Practices elevate quality barriers, concentrating volume among certified manufacturers. Boston and San Francisco metro clusters host telehealth-integrated dispensing partnerships that convert clinical endorsement into automated replenishment cycles.
Germany
Pharmacy counseling programs leverage EU Organic certification to command premium positioning among expectant mothers. EFSA health claim evaluations tighten permissible pregnancy-related marketing language, forcing label revision cycles extending 8-14 months. Bavaria and Baden-Württemberg industrial zones concentrate softgel manufacturing capacity serving French and Swiss export demand.
United Kingdom
NHS Trust maternity programs dispense starter packs at first prenatal visits, embedding supplements within institutional care pathways. The EU MDR indirectly influences excipient sourcing standards for hospital-affiliated procurement. London and Southeast England health store clusters emphasize NSF International and USP Verified third-party certifications for quality-conscious consumers.
India
FSSAI functional food regulatory clarity opens access pathways for prenatal gummies and fortified beverages targeting 25 million annual births. Clean-label procurement shifts purchasing patterns among urban millennial cohorts in Mumbai and Delhi-NCR. Maharashtra and Gujarat manufacturing hubs scale tablet production for Medicaid-equivalent government nutrition programs.
China
NMPA dietary supplement registration requirements shape formulation standards for imported and domestic prenatal products alike. Algae-derived DHA sourcing displaces fish oil in premium-tier offerings among tier-one city consumers. Yangtze River Delta pharmaceutical clusters develop liposomal encapsulation capacity for bioavailability-enhanced maternal nutrition exports.
Prenatal Vitamin Supplements Market Vendor Landscape
Channel-controlling players compete with product-specialist players across pharmacy, online retail, and health store vectors. The vendor base organizes around three archetypes: pharmaceutical heritage manufacturers leveraging clinical credibility, whole-food sourced specialists commanding certification premiums, and direct-to-consumer platforms capturing subscription revenue. Consolidation pressures favor certified manufacturers with validated analytical capabilities over low-cost competitors. Strategic moves concentrate on telehealth partnerships for clinical endorsement conversion and microencapsulation technology licensing for gastrointestinal tolerability improvements.
Within the pharmaceutical heritage tier, Bayer AG anchors clinical credibility through obstetrician-gynecologist network relationships. Among whole-food sourced specialists, Garden of Life exemplifies third-party certification positioning that commands premium shelf space in health store channels. At the direct-to-consumer vector, Church & Dwight Co., Inc. occupies a position representing mass-market accessibility through pharmacy and mass retail distribution scale.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Bayer AG |
| Abbott |
| Garden of Life |
| Country Life |
| Nature Made |
| Pharmavite |
| Nordic Naturals |
| MegaFood |
| Others |
Supply Flow & Price Mechanics
Fish oil supply concentration in Peruvian and Chilean anchovy fisheries determines both the 3-4x cost spread between premium ferrous bisglycinate formulations and value-tier ferrous sulfate products and the cold-chain infrastructure investments required across distribution networks. This single-source dependency for DHA raw materials compresses margins on private label offerings while elevating pricing power for certified manufacturers with validated marine stewardship documentation.
Pricing Analysis
Cost-plus contracts with fish meal indexation anchor DHA ingredient pricing, creating volatility pass-through to finished goods. Three-tier pricing structure across premium organic-certified, standard natural-sourced, and economy synthetic formulations separates USDA Organic positioning from mass-market pharmacy tiers. Pricing pressure stems from iron excipient cost inflation as manufacturers substitute carbonyl iron for ferrous sulfate. Medicaid reimbursement programs exhibit highest price sensitivity; direct-to-consumer subscription cohorts in United States coastal markets show lowest.
Supply Chain Analysis
Export-control restrictions on algae-derived DHA biotechnology limit technology transfer to Chinese manufacturing clusters, constraining alternative sourcing development. Raw material flows center on Peruvian anchovy fisheries for marine omega-3s, Indian pharmaceutical hubs for synthetic vitamin precursors, and German excipient manufacturers for softgel gelatin. Single-source vulnerability concentrates in South American fish oil catch volumes exposed to El Niño disruption. Distribution runs through pharmacy counseling programs, direct-to-consumer subscription platforms, and health store specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical upswing driven by millennial birth rate recovery in United States urban clusters, creating favorable conditions for capacity expansion and certification investments.
For Market Incumbents: Harden supply chain resilience through backward integration into algae-derived DHA cultivation or long-term offtake agreements with Peruvian fisheries. Secure NSF International and USP Verified certifications to defend shelf position against emerging whole-food specialists. Lock in telehealth partnership exclusives with Kaiser Permanente and NHS Trust systems to convert clinical endorsement into recurring subscription revenue. For New Entrants and Emerging Players: Build out postnatal extension formulations targeting the twelve-month lactation window where incumbent coverage remains thin. India FSSAI regulatory clarity on prenatal gummies presents the most penetrable geography-application intersection. Launch through obstetrician-dispensed starter packs bundled with virtual consultation platforms to bypass saturated pharmacy channel gatekeeping. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors certified manufacturers with validated analytical capabilities over undifferentiated private label operators. Five-to-ten year viability rests on microencapsulation technology licensing portfolios and clean-label procurement compliance. Watch for FDA enforcement actions on unqualified neurological development claims as the inflection signal for regulatory compliance premium repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Bioavailability engineering reduces gastrointestinal side effects, converting obstetrician-gynecologist skepticism into dispensing partnerships. |
| Telehealth Platform Integration | Virtual consultation bundling with board-certified obstetrician-gynecologists transforms clinical endorsement into automated subscription enrollment. |
| Algae-Derived DHA Sourcing Transition | Marine stewardship certification bypasses El Niño-driven Peruvian anchovy catch volatility and appeals to clean-label millennial cohorts. |
| Postnatal Formulation Extension | Lactation-supporting nutrient complexes capture twelve-month recurring demand beyond gestation windows where incumbent portfolios end. |
| Third-Party Certification Investment | NSF International and USP Verified positioning commands premium shelf space in CVS Health and Walgreens counseling programs. |
Methodological Framework
Operator-level perspectives from obstetrician-gynecologists, pharmacy procurement managers, direct-to-consumer brand executives, and dietary supplement formulators anchored the qualitative base. Primary interviews combined with secondary validation from FDA Current Good Manufacturing Practice filings, EFSA health claim evaluation databases, FSSAI functional food registration records, and customs trade data on fish oil imports. Bottom-up volume modeling across product type, formulation, distribution channel, and target audience segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing around regulatory enforcement intensity and raw material supply disruption framed the projection horizon. Segmentation dimensions modeled include delivery format, certification tier, channel structure, and pregnancy stage application. CAGRs derived from historical volume trajectories adjusted for millennial demographic shifts and telehealth adoption curves. Forecast inputs incorporated trimester-adjusted dosing algorithm penetration and clean-label procurement elasticity estimates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algae-DHA biotechnology specialists or telehealth-integrated subscription platforms would shift outcomes. Material shifts in FDA labeling enforcement, EFSA health claim evaluations, or El Niño frequency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Cordyceps Product Market
Nutritional Supplements
Europe Dietary Supplements Market
Nutritional Supplements
L-Leucine Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
US Nutraceuticals Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Vitamins Gummies Market