
 Beta Glucan and Fucoidan Market | 2026-2036
Beta Glucan and Fucoidan Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Glucan and Fucoidan Market Analysis
Subscription-based ingredient certification programs is broadening what suppliers sell beyond raw material volumes. Kerry Group PLC leverages its global application centers to sustain formulation partnerships with nutraceutical brands. Koninklijke DSM NV anchors its position through backward integration into yeast-derived beta glucan fermentation. Marinova specializes in certified organic fucoidan extraction, occupying a premium tier in cosmetic and pharmaceutical supply chains.
Beta glucan and fucoidan comprise bioactive polysaccharides extracted from yeast cell walls and brown seaweed biomass respectively, with beta glucan chains typically containing beta-1,3 and beta-1,6 glycosidic linkages that modulate immune cell receptors and fucoidan characterized by sulfated L-fucose polymers with molecular weights ranging from tens to thousands of kilodaltons depending on extraction severity. The nutraceuticals application segment leads current value generation as functional food and dietary supplement brands incorporate these compounds for immune and gut health positioning, while pharmaceutical applications represent the fastest-growing margin pool as clinical trials advance for oncology adjuvant and wound healing indications. Powder form dominates manufacturing throughput due to stability in bulk handling and compatibility with encapsulation lines, though liquid extracts gain traction in beverage fortification.
EFSA novel food panels and FDA GRAS notification pathways shape European and North American market access timelines for new extraction processes and source organisms, while Japan's Ministry of Health, Labour and Welfare maintains distinct FOSHU approval requirements that filter which fucoidan suppliers reach functional food positioning. FSSAI and BIS standards in India are tightening contaminant limits for imported seaweed extracts, redirecting sourcing toward certified supply chains. Stakeholders must monitor how regulatory divergence between pharmacopeial-grade and food-grade specifications fragments procurement strategies and capital allocation across extraction capacity.
Market Dynamics
Regulatory divergence between pharmacopeial-grade and food-grade specifications fragments procurement strategies across extraction capacity investments. Suppliers must now dual-track compliance for nutraceutical and pharmaceutical channels simultaneously.
Growth Catalysts
- EFSA novel food authorizations:Streamlined approval pathways in Europe accelerate purified extract market entry for fucoidan suppliers targeting functional food positioning.
- Immune-support formulation demand:Nutraceutical manufacturers expand beta glucan inclusion rates as post-pandemic consumer preference for gut-health positioning hardens.
- Okinawan mozuku extraction infrastructure:Japan's established domestic fucoidan supply chains provide clinical credibility templates replicable for brown seaweed sourcing globally.
Market Restraints
- Seaweed biomass supply concentration:Brown algae harvesting concentrates in coastal prefectures vulnerable to climate-induced harvest volatility and seasonal sulfated polysaccharide yield variation.
- FSSAI contaminant limit tightening:India's import standards for heavy metals and iodine content redirect sourcing toward certified organic supply chains with elevated qualification costs.
- Yeast fermentation input cost exposure:Beta glucan producers face glucose and nitrogen source price sensitivity that compresses margin at pharmaceutical-grade purity thresholds.
Strategic Opportunities
- Beverage fortification channel expansion:Liquid extract formats penetrate functional drink formulations previously inaccessible to powder-handling limitations.
- Oncology adjuvant clinical positioning:Pharmaceutical applications advance through trial design that differentiates high-molecular-weight fucoidan fractions for immunomodulatory protocols.
- Subscription certification programs:Ingredient authentication services create recurring revenue streams beyond raw material volume transactions for extraction specialists.
Industry Challenges
- Dual-grade extraction facility capex:Simultaneous pharmacopeial and food-grade production lines demand segregated cleanroom infrastructure with divergent validation protocols.
- Analytical method standardization gaps:Molecular weight distribution reporting lacks harmonized ISO reference standards, complicating batch-to-batch consistency claims across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Glucan and Fucoidan Market |
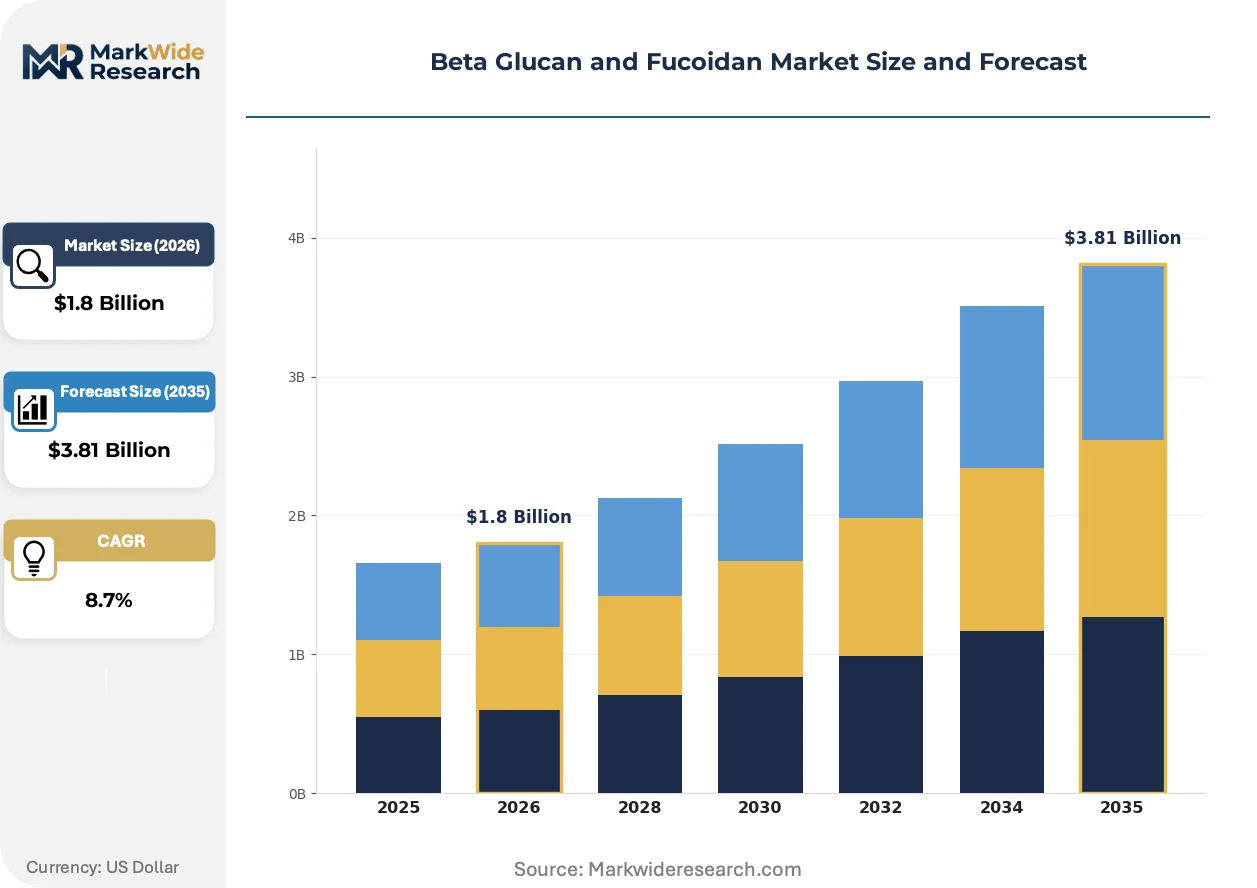
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta Glucan, Fucoidan, Supplements, Functional Foods Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Animal Feed Form: Powder, Liquid, Capsule, Tablet Source: Yeast, Seaweed, Mushroom, Others |
| Companies Covered | Lantmannen, Kerry Group PLC, Koninklijke DSM NV, Kemin Industries, Merck KGaA, Super Beta Glucan Inc, Arcticzymes Technologies ASA, Marinova, Yaizu Suisankagaku Industry Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Glucan and Fucoidan Market Emerging Trajectories
Extraction technology convergence with analytical characterization tools reshapes how suppliers demonstrate bioactivity consistency. Process innovation now centers on preserving structural integrity through gentler recovery methods.
Continuous flow processing technology for seaweed cell wall disruption is modularizing extraction operations previously constrained by batch-scale limitations. Mid-size nutraceutical contract manufacturers adopt plug-and-play skid systems that reduce qualification timelines for new fucoidan source verification. This technology compression enables geographic dispersal of processing capacity closer to raw material harvesting zones.
REACH registration requirements for novel sulfated polysaccharide derivatives tighten substance characterization obligations for European cosmetic and pharmaceutical ingredient suppliers. Industrial consequence includes mandatory toxicological dossier preparation that filters smaller extraction operations from premium supply tiers. German and French formulators now demand pre-registered fucoidan intermediates, shifting procurement toward vertically integrated seaweed processors with in-house regulatory affairs capabilities.
Certification-driven supplier preference now displaces spot-market purchasing for immune-health ingredient procurement. Major dietary supplement brands consolidate vendor lists around third-party verified beta glucan sources with published receptor-binding assay data. This consolidation pattern concentrates most visibly in North American contract manufacturing organizations serving direct-to-consumer subscription brands.
Beta Glucan and Fucoidan Market Segmentation
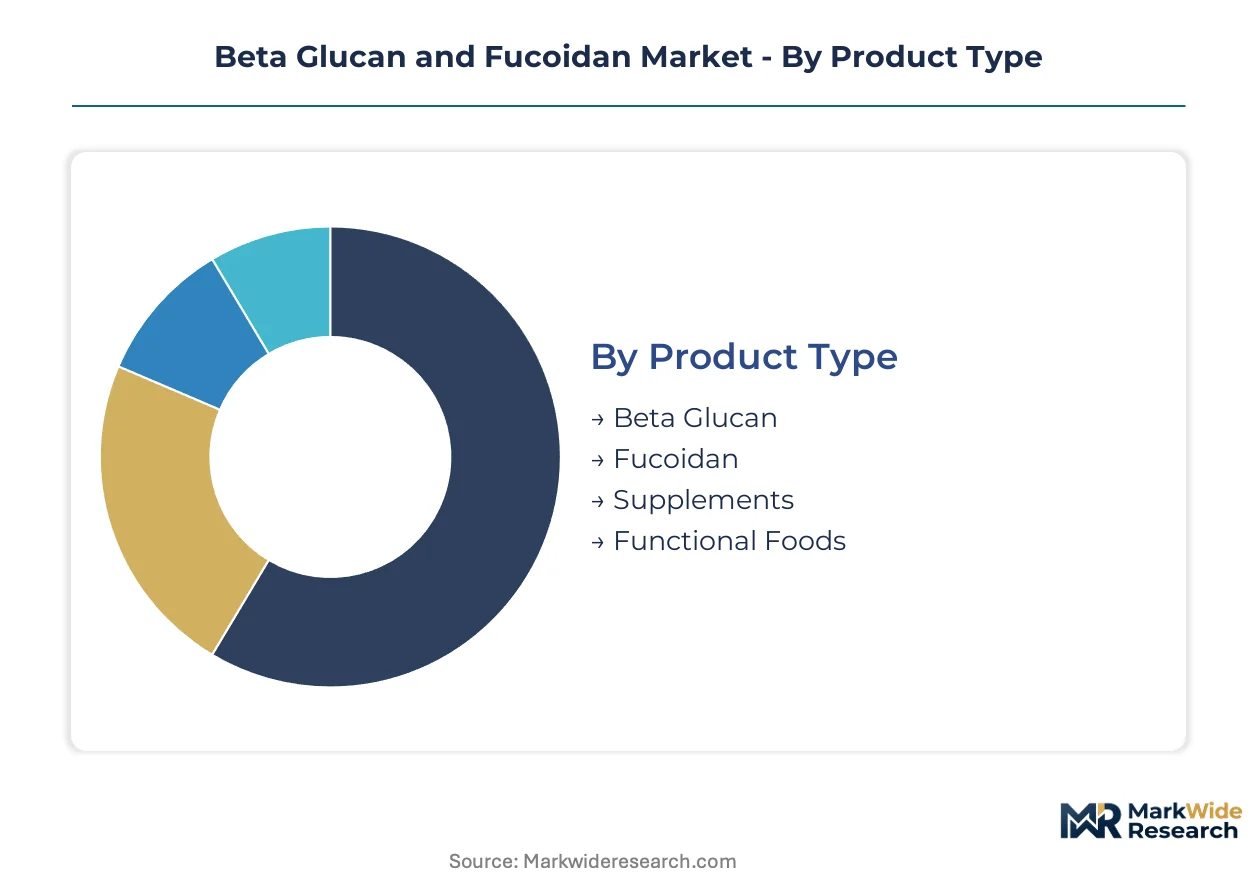
Structural differentiation across beta glucan and fucoidan supply chains determines extraction economics, regulatory pathways, and end-use qualification requirements. Each segmentation axis carries distinct margin profiles and technical barriers that shape supplier positioning.
Product Type:
Specification grade and purity thresholds separate pharmaceutical-grade isolates from commodity bulk ingredients.
- Beta Glucan:Yeast-derived beta-1,3/1,6-glucan chains with receptor-binding assays verifying immune-modulatory potency command premium positioning in clinical nutrition formulations. Pharmaceutical-grade material requires endotoxin-controlled fermentation and multi-step purification that limits qualified supplier pools.
- Fucoidan:Sulfated L-fucose polymers from brown seaweed biomass concentrate demand in Japan's Okinawan mozuku supply chains, where established clinical credibility supports functional food positioning. Molecular weight fractionation capabilities differentiate premium cosmetic and pharmaceutical grades from bulk nutraceutical material.
- Supplements:Encapsulated and tableted finished goods integrate standardized extracts with formulation stability testing for shelf-life claims.
- Functional Foods:Beverage and fortified food applications require taste-masked, heat-stable extract formats with solubility engineering.
Beta Glucan leads on scale; Fucoidan leads on momentum.
Application:
End-use channel selection dictates regulatory compliance burden and pricing realization.
- Nutraceuticals:Dietary supplement and functional food brands drive current volume absorption, with immune-support positioning hardening post-pandemic consumer preference for gut-health formulations.
- Pharmaceuticals:Oncology adjuvant and wound healing indications represent the steepest expansion trajectory as clinical trials advance for high-molecular-weight fucoidan fractions and purified beta glucan isolates.
- Cosmetics:Topical anti-inflammatory and hydrating claims leverage fucoidan's sulfated polysaccharide film-forming properties in premium skincare.
- Animal Feed:Gut health and immunomodulatory applications in aquaculture and livestock production absorb commodity-grade material with lower purity thresholds.
Nutraceuticals dominates current procurement; Pharmaceuticals is climbing the fastest.
Form:
Physical presentation determines handling infrastructure compatibility and formulation flexibility.
- Powder:Spray-dried and milled extracts dominate manufacturing throughput due to stability in bulk handling, compatibility with encapsulation lines, and extended shelf-life under controlled humidity. Contract manufacturers prefer powder for blending uniformity.
- Liquid:Aqueous extracts and concentrated solutions penetrate beverage fortification channels previously inaccessible to powder-handling limitations, requiring preservative systems and cold-chain logistics.
- Capsule:Hard-shell and soft-gel delivery formats integrate standardized doses with consumer convenience positioning.
- Tablet:Compressed formulations with excipient engineering for disintegration profiles serve mass-market supplement retail.
Powder leads on scale; Liquid leads on momentum.
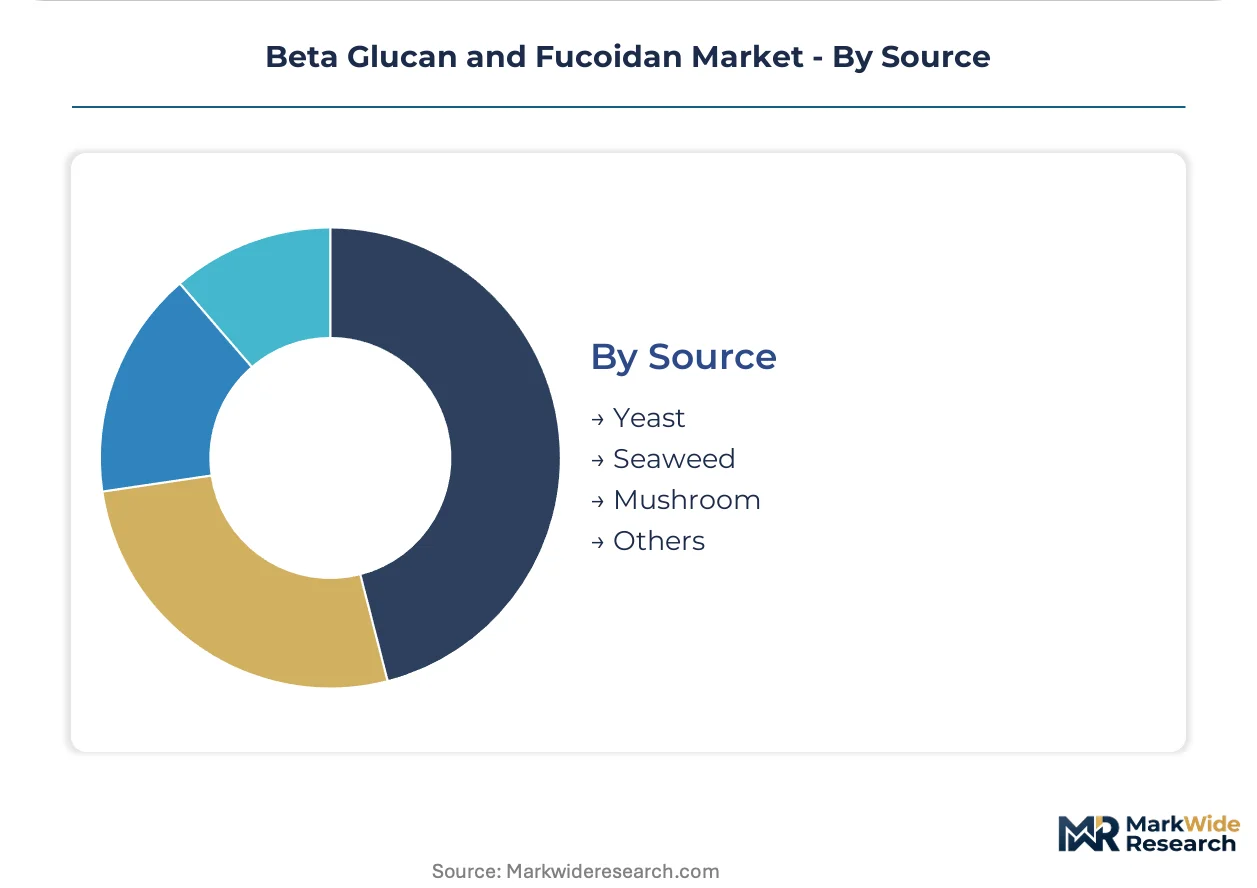
Source:
Biomass origin shapes molecular structure, regulatory pathway, and supply security profile.
- Yeast:Saccharomyces cerevisiae fermentation delivers consistent beta-1,3/1,6-glucan structures with batch-to-batch reproducibility that supports pharmacopeial-grade qualification. DSM and Kerry Group anchor supply through captive fermentation infrastructure.
- Seaweed:Brown algae harvesting concentrates in Japanese, Korean, and Tasmanian coastal zones, with climate-induced harvest volatility and seasonal sulfated polysaccharide yield variation creating supply concentration risk.
- Mushroom:Lentinus edodes and Grifola frondosa fruiting body extracts provide beta-glucan with distinct glycosidic linkage patterns favored in traditional medicine-positioned formulations.
- Others:Cereal grain sources (oat, barley) and bacterial fermentation represent emerging alternative supply routes with cost advantages but limited clinical validation.
Yeast leads on scale; Seaweed leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan commands fucoidan clinical credibility while the United States drives beta glucan volume through yeast fermentation infrastructure. Germany anchors European pharmaceutical-grade extraction capacity. These three markets generate divergent regulatory pathways and sourcing strategies.
United States
FDA GRAS notifications streamline purified beta glucan entry into functional foods and dietary supplements. Kerry Group PLC operates application centers that bridge formulation partnerships with nutraceutical brands. The Midwest fermentation corridor concentrates yeast-derived supply chains with captive glucose sourcing.
Japan
Okinawan mozuku seaweed carries established clinical credibility for immune-support positioning in domestic functional foods. The Ministry of Health, Labour and Welfare maintains distinct FOSHU approval requirements that filter supplier access. Yaizu City in Shizuoka Prefecture anchors extraction infrastructure with coastal harvesting integration.
Germany
REACH registration requirements tighten substance characterization for cosmetic and pharmaceutical ingredient suppliers. EFSA novel food panels shape European approval timelines for purified fucoidan extracts. Hamburg and Frankfurt clusters concentrate vertically integrated processors with in-house regulatory affairs capabilities.
India
FSSAI contaminant limit tightening for heavy metals and iodine redirects seaweed extract sourcing toward certified organic supply chains. BIS standards for imported biomass elevate qualification costs for international suppliers. Gujarat and Maharashtra coastal zones host emerging domestic brown algae cultivation pilots.
Australia
TGA regulatory alignment with pharmacopeial-grade specifications supports clinical trial material supply for oncology adjuvant applications. Tasmanian coastal waters provide brown seaweed biomass with seasonal sulfated polysaccharide yield variation. Marinova operates certified organic extraction capacity serving premium cosmetic and pharmaceutical supply chains.
Beta Glucan and Fucoidan Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived beta glucan consolidating around captive yeast processors and fucoidan fragmenting across coastal extraction zones. Three archetypes dominate: multinational nutrition ingredient platforms with backward integration into fermentation, regional seaweed processors with geographic harvesting advantages, and application-focused formulators bridging technical specification with brand positioning. Competitive moves concentrate on dual-grade facility qualification and subscription-based certification programs that displace spot-market purchasing.
Among the multinational nutrition platforms, Koninklijke DSM NV and Kerry Group PLC exemplify divergent integration strategies. DSM anchors position through in-house yeast-derived beta glucan fermentation capacity, while Kerry leverages global application centers to sustain formulation partnerships. Marinova occupies a premium tier position as a certified organic fucoidan specialist with Tasmanian coastal sourcing. These three represent distinct competitive vectors: captive supply control, technical application services, and premium certification differentiation.
| Leading Market Players |
|---|
| Lantmannen |
| Kerry Group PLC |
| Koninklijke DSM NV |
| Kemin Industries |
| Merck KGaA |
| Super Beta Glucan Inc |
| Arcticzymes Technologies ASA |
| Marinova |
| Yaizu Suisankagaku Industry Co Ltd |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade and food-grade certification divergence splits procurement economics across extraction tiers, with endotoxin-controlled fermentation commanding triple-digit premiums over bulk nutraceutical material while dual-grade facility capex concentrates supplier power in Japan, Germany, and the United States.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for yeast-derived beta glucan as Kerry Group and DSM expand captive fermentation infrastructure. Three-tier pricing structure across pharmaceutical, nutraceutical, and feed-grade levels reflects endotoxin thresholds and receptor-binding assay verification. Cost compression in commodity-grade material intensifies because glucose and nitrogen source price volatility feeds through fermentation economics. Contract manufacturing organizations serving direct-to-consumer brands exhibit highest price sensitivity, while pharmaceutical sponsors absorb premium pricing for clinical trial material supply security.
Supply Chain Analysis
Direct-to-nutraceutical-brand channels handle standardized powder demand, while pharmaceutical sponsors source through qualified supplier audits with batch-specific CoA requirements. Raw material harvesting concentrates in Japan's Okinawan coastal prefectures, Tasmania's certified organic zones, and the United States Midwest fermentation corridor. Brown algae biomass draws from seasonal mozuku harvests with sulfated polysaccharide yield variation, while yeast fermentation feeds from corn-derived glucose and soy nitrogen sources. Single-source vulnerability runs through Japanese fucoidan extraction infrastructure given climate-induced harvest volatility and FOSHU regulatory filtering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA novel food authorization costs in Europe diverge from Japan's established FOSHU clinical credibility templates, rewarding suppliers with pre-qualified multi-jurisdictional dossiers.
For Market Incumbents: To counter analytical method standardization gaps that fragment batch-to-batch consistency claims, invest in ISO reference standard adoption and receptor-binding assay publication. Prioritize dual-grade extraction facility qualification to capture pharmaceutical margin pools while maintaining nutraceutical volume throughput. For New Entrants and Emerging Players: Launch via beverage fortification channel partnerships with functional drink brands seeking liquid extract formats previously inaccessible to powder-handling limitations. Target India's certified organic supply chain qualification gap as FSSAI contaminant limit tightening redirects sourcing toward pre-qualified international suppliers with heavy metals and iodine documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH registration requirements for novel sulfated polysaccharide derivatives filter smaller extraction operations from premium cosmetic and pharmaceutical supply tiers. Long-term viability centers on vertically integrated seaweed processors with in-house regulatory affairs capabilities spanning EFSA, FDA GRAS, and FOSHU pathways. Monitor oncology adjuvant clinical trial readouts as inflection indicators for high-molecular-weight fucoidan fraction demand.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Grade Facility Qualification | Captures pharmaceutical margin pools while maintaining nutraceutical volume throughput for yeast and seaweed processors. |
| Subscription Certification Programs | Creates recurring revenue streams beyond raw material volume transactions through third-party verified receptor-binding assay data. |
| Continuous Flow Processing Adoption | Enables geographic dispersal of extraction capacity closer to Japanese, Tasmanian, and Korean raw material harvesting zones. |
| REACH Pre-Registration Investment | Secures premium supply tier access for European cosmetic and pharmaceutical formulators demanding toxicological dossier preparation. |
| Beverage Fortification Channel Expansion | Penetrates functional drink formulations with taste-masked, heat-stable liquid extract formats engineered for solubility. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction facility operations managers, nutraceutical brand formulation scientists, regulatory affairs specialists at EFSA and FDA consultation firms, and pharmaceutical clinical supply procurement directors with secondary validation through EFSA novel food panel decisions, FDA GRAS notification filings, FOSHU approval registries, and customs trade data for brown seaweed biomass imports. Bottom-up capacity modeling and top-down demand triangulation anchored market sizing across the projection horizon.
Historical reference periods established baseline extraction economics and regulatory approval timelines that shaped growth trajectory assumptions over the analysis window. Segmentation dimensions modeled include product type specification grade, application channel regulatory burden, physical form handling infrastructure, and biomass source geographic concentration. CAGRs derived from supply-side capacity buildout schedules and demand-side formulation inclusion rate trends across immune-support and oncology adjuvant positioning. Forecast inputs incorporated seasonal sulfated polysaccharide yield variation and dual-carbon policy impacts on fermentation energy costs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-induced harvest disruption and regulatory divergence between pharmacopeial-grade and food-grade specifications. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Mediterranean Pre-Diabetes Ingredient Concepts Market
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
North America Omega-3 PUFA Market
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Brominated Vegetable Oil Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Multifunctional Food Ingredients Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Essential Fatty Acids Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Protein Cookie Market