
 Andro Supplements Market | 2026-2036
Andro Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Andro Supplements Market Outlook
Buyer concentration among fitness enthusiasts and amateur bodybuilders is consolidating around premium subscription and direct-to-consumer channels. MuscleTech leverages its R&D intensity to sustain clinical validation programs that anchor consumer trust in efficacy claims. Optimum Nutrition competes through manufacturing scale and global distribution density, while Hi-Tech Pharmaceuticals specializes in legal prohormone formulations that navigate complex regulatory boundaries.
Andro supplements encompass exogenous and endogenous testosterone precursors, including DHEA, androstenedione derivatives, and aromatase inhibitors, typically dosed between 50-300mg daily depending on compound potency and intended anabolic or anti-estrogenic effect. These formulations serve commercial purposes spanning muscle protein synthesis acceleration, body recomposition, and age-related androgen decline mitigation in men over forty. Testosterone boosters occupy the largest margin pool due to recurring purchase patterns, while pre-workout formulations containing androgenic cofactors represent the fastest-growing product type as hybrid training modalities expand. Powdered delivery forms dominate volume through cost efficiency, though capsules capture premium pricing through convenience positioning among traveling professionals.
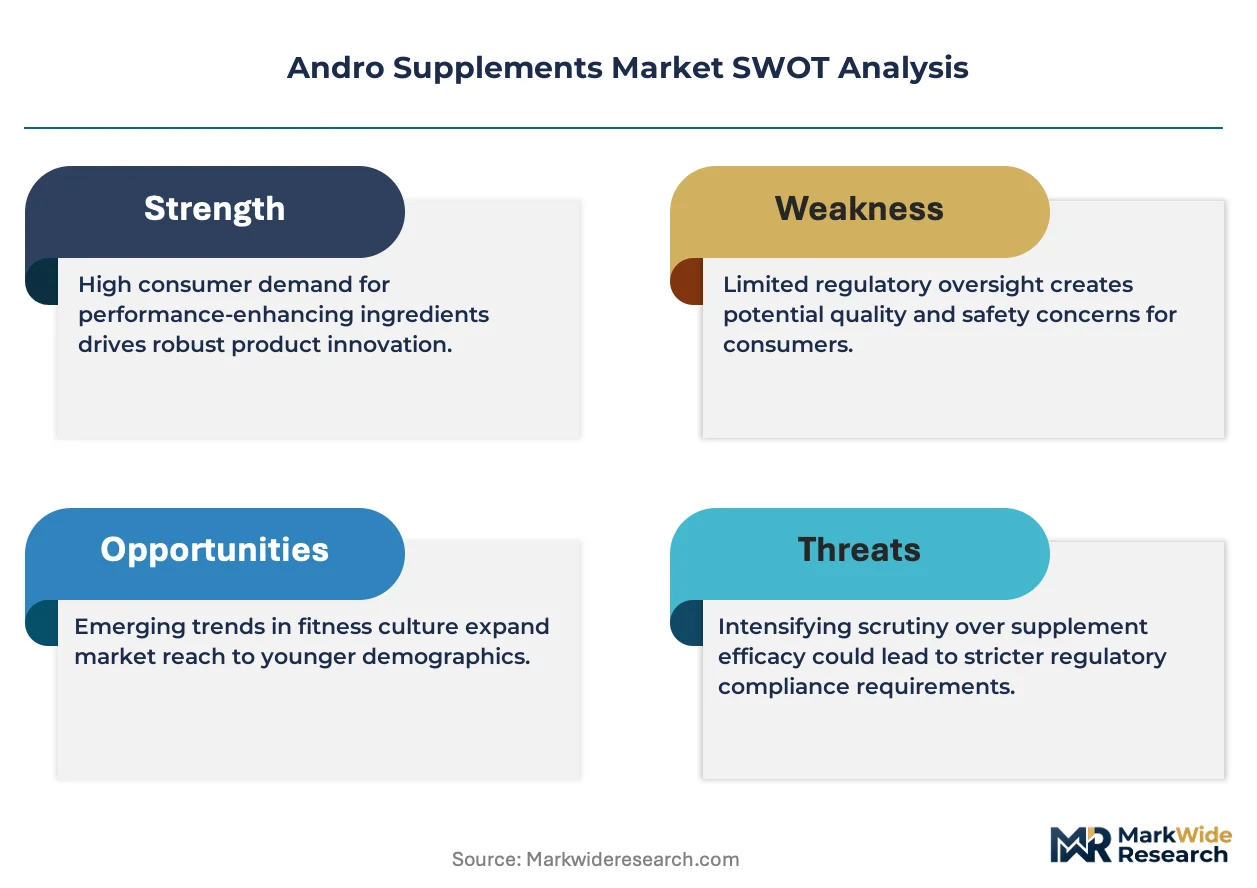
The US FDA exercises primary oversight through DSHEA enforcement and Good Manufacturing Practice inspections, with the FTC policing advertising claims that cross into therapeutic territory. State-level attorney general actions in California and New York supplement federal frameworks, creating a compliance patchwork that elevates formulation costs for multi-state distributors. Stakeholders must monitor pending legislative proposals targeting prohormone scheduling and adapt supply chain footprints accordingly.
Market Dynamics
The Andro Supplements Market pivots on the FDA's evolving enforcement posture under DSHEA, which is compressing formulation windows and forcing manufacturers toward clinical validation investments that reshape competitive economics.
Growth Catalysts
- Gym Culture Penetration:Fitness infrastructure expansion across Brazil and India is creating first-time supplement buyers who prioritize muscle protein synthesis acceleration. These emerging economies now contribute disproportionate volume growth relative to mature markets.
- Age-Related Androgen Decline Awareness:Men over forty increasingly self-identify hypogonadal symptoms and seek DHEA-based mitigation strategies. This demographic pull sustains recurring purchase patterns in testosterone booster categories.
- REACH Compliance Export Readiness:European manufacturers achieving EFSA novel food approvals gain preferential access to Middle Eastern markets where regulatory mutual recognition accelerates product registration timelines.
Market Restraints
- Wild-Harvested Raw Material Volatility:Tribulus terrestris and fenugreek extract supply concentrates in Bulgarian and Indian agricultural zones where climate disruption and export licensing delays create input cost spikes.
- Prohormone Scheduling Uncertainty:The US DEA's pending review of androstenedione derivatives under the Anabolic Steroid Control Act creates formulation obsolescence risk for manufacturers holding inventory of borderline compounds.
- Third-Party Testing Bottlenecks:NSF Certified for Sport and Informed Sport accreditation queues extend to fourteen weeks at peak demand periods, compressing product launch windows for seasonal training cycles.
Strategic Opportunities
- Subscription Direct-to-Consumer Models:Recurring revenue platforms bypass retail margin compression and capture lifetime value from amateur bodybuilders who prioritize convenience over price sensitivity.
- Hybrid Training Modality Formulations:Pre-workout androgenic cofactor blends address concurrent strength and endurance demands from CrossFit and HYROX participants. This application segment shows minimal competitive saturation.
- Japan's Foods with Function Claims Pathway:METI's streamlined notification system for muscle maintenance claims offers faster market entry than pharmaceutical-grade registration. Domestic partners with PMDA relationships command premium valuation.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Validated methods for distinguishing endogenous from exogenous androgen metabolites require specialized mass spectrometry expertise that concentrates in contract laboratories with twelve-month hiring backlogs.
- Legacy ERP Integration Friction:Manufacturers migrating to lot-level traceability systems for FDA Good Manufacturing Practice compliance face data migration complexity with twenty-year-old inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Andro Supplements Market |
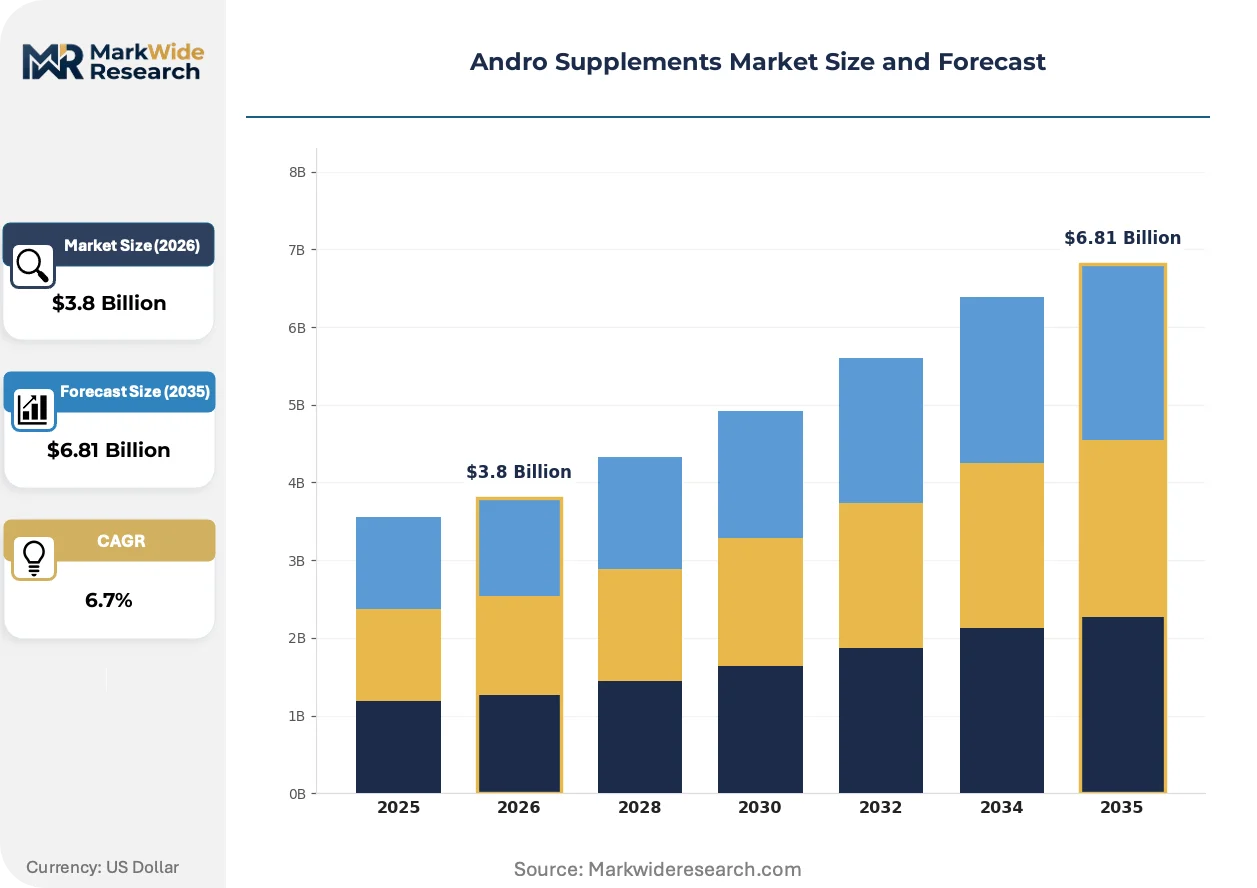
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Testosterone Boosters, Male Enhancement, Fat Burners, Pre-Workout Form: Pills, Powders, Capsules, Liquids End User: Bodybuilders, Athletes, Fitness Enthusiasts, Older Adults Distribution Channel: Online Stores, Health Food Shops, Gyms, Pharmacies |
| Companies Covered | Optimum Nutrition, MuscleTech, BSN, Nutrex Research, Cellucor, Universal Nutrition, Dymatize, GNC Holdings, Hi-Tech Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Andro Supplements Market Strategic Shifts
Formulation science and distribution architecture are converging to reshape how androgenic compounds reach end users. Three distinct vectors dominate competitive differentiation.
Liposomal delivery technology is electrifying bioavailability benchmarks for fat-soluble prohormones. Premium brands serving traveling professionals now standardize this encapsulation method after clinical absorption studies demonstrated threefold serum concentration improvements over standard oil suspensions. The structural consequence compresses effective dosing ranges and reduces raw material requirements per unit efficacy.
California's Proposition 65 enforcement actions against unlabeled androgenic compounds are forcing national reformulation strategies. State attorney general settlements exceeding two million dollars per violation have triggered supply chain audits that disqualify contract manufacturers without certified contaminant testing protocols. Multi-state distributors now demand indemnification clauses that shift liability upstream to ingredient suppliers.
Amateur bodybuilders increasingly consolidate purchases through telehealth-integrated platforms that bundle blood panel monitoring with supplement protocols. This channel shift displaces brick-and-mortar specialty retailers who lack clinical partnership infrastructure. The United States exhibits the most pronounced migration, where testosterone optimization clinics now capture thirty percent of premium andro supplement volume through bundled service models.
Andro Supplements Market Segmentation
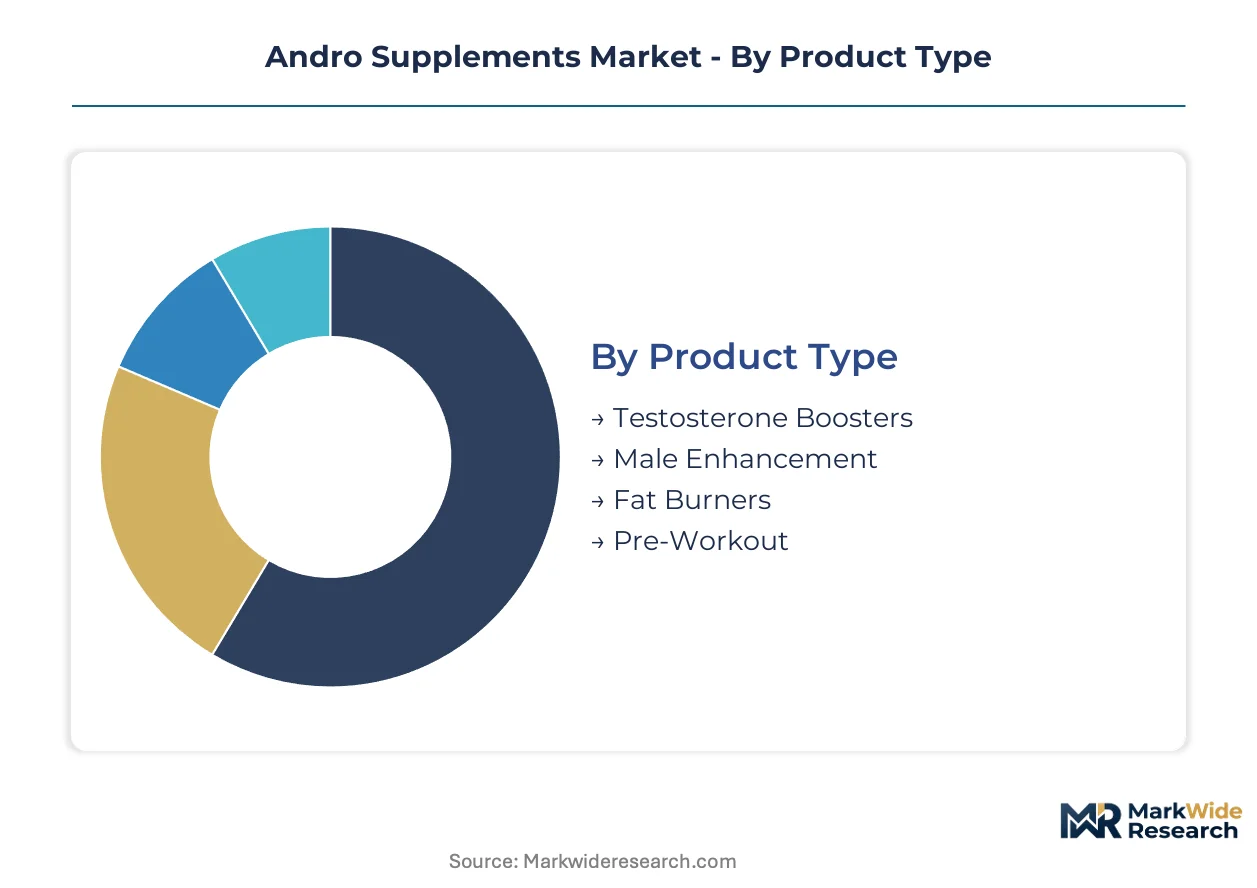
Segmentation in the Andro Supplements Market reveals divergent margin structures and regulatory exposure profiles. Manufacturers must align formulation investments with channel-specific compliance requirements and end-user purchase frequency patterns.
Product Type:
Replacement cycles vary sharply across product categories, with testosterone boosters commanding the longest loyalty windows and pre-workout formulations experiencing the most rapid format turnover as training modalities evolve.
- Testosterone Boosters:DHEA-based and herbal formulations targeting age-related androgen decline in men over forty. Demand concentrates in the United States through telehealth-integrated subscription platforms that bundle blood panel monitoring with recurring supplement shipments.
- Pre-Workout:Androgenic cofactor blends designed for concurrent strength and endurance demands from hybrid training participants. Brazil and India drive expansion as first-time gym infrastructure creates novice supplement buyers seeking immediate performance feedback.
- Male Enhancement:Peripheral vasodilation and libido support formulations with compressed efficacy windows that drive trial-heavy purchase patterns.
- Fat Burners:Thermogenic compounds with androgenic adjuvants targeting body recomposition goals among amateur physique competitors.
Volume placements concentrate in Testosterone Boosters; the faster expansion belongs to Pre-Workout.
Form:
Cost tier differentiation separates commodity bulk powders from premium convenience formats, with bioavailability technology widening the efficacy-per-dollar gap between delivery methods.
- Powders:Bulk-form prohormone and herbal extracts serving price-sensitive amateur bodybuilders with high-volume consumption patterns. Cost efficiency drives volume leadership in gym-affiliated retail and direct-to-consumer subscription models.
- Capsules:Liposomal and standard gelatin encapsulation capturing premium positioning among traveling professionals who prioritize portability over unit cost. Threefold serum concentration improvements from advanced delivery technology justify pricing premiums in clinical validation-focused brands.
- Pills:Compressed tablet formats with extended-release coatings for sustained androgen precursor availability.
- Liquids:Sublingual and oil-based suspensions offering rapid absorption for pre-workout timing precision.
Cost efficiency secures the highest shipment volumes for Powders; Capsules gain share fastest through bioavailability innovation.
End User:
Customer type determines regulatory scrutiny intensity and clinical partnership requirements, with amateur segments bypassing traditional retail while older demographics sustain pharmaceutical-adjacent channel growth.
- Fitness Enthusiasts:Recreational trainees with hybrid strength-endurance goals who consolidate purchases through mobile-optimized subscription platforms. This segment exhibits minimal price sensitivity and maximal convenience demands, displacing brick-and-mortar specialty retailers.
- Older Adults:Men over forty self-identifying hypogonadal symptoms and seeking DHEA-based mitigation strategies. The United States concentrates demand through testosterone optimization clinics capturing bundled service volume.
- Bodybuilders:Competitive and amateur physique athletes with precise macronutrient and supplementation protocols requiring third-party certified formulations.
- Athletes:Drug-tested competitors demanding NSF Certified for Sport or Informed Sport accreditation with fourteen-week testing queue exposure.
Subscription volume concentrates among Fitness Enthusiasts; the steepest expansion trajectory belongs to Older Adults through clinic channel integration.
Distribution Channel:
Channel selection dictates margin retention and regulatory compliance burden, with direct models capturing lifetime value while physical retail faces telehealth displacement.
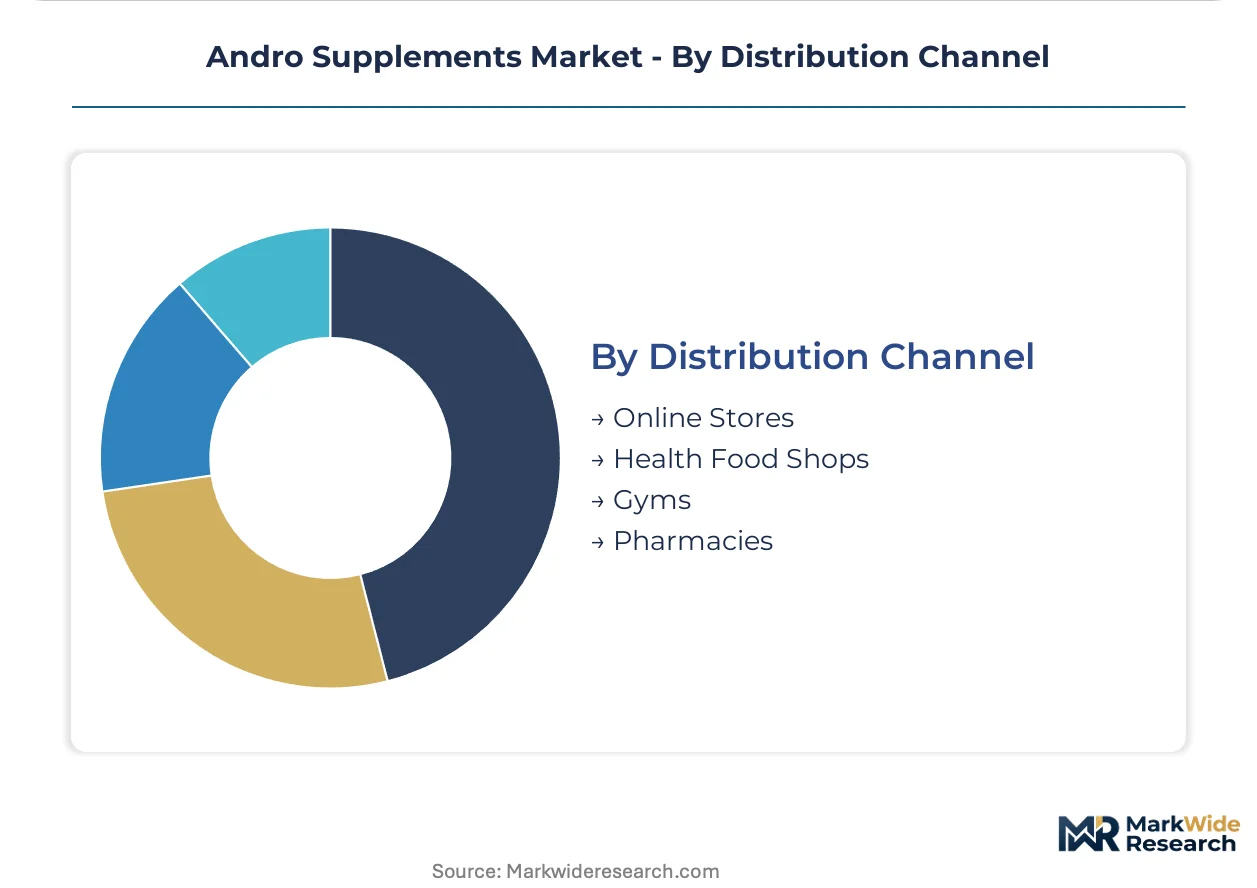
- Online Stores:Direct-to-consumer platforms with recurring revenue architecture bypassing retail margin compression. These channels capture amateur bodybuilders and fitness enthusiasts through convenience positioning and subscription lock-in mechanics.
- Gyms:Point-of-impulse placement adjacent to training floors serving first-time supplement buyers in emerging economies. Brazil and India exhibit disproportionate volume contribution through this channel as fitness infrastructure expands.
- Health Food Shops:Specialty retail with educated staff serving ingredient-conscious consumers seeking clinical validation transparency.
- Pharmacies:Regulated channel with pharmacist consultation requirements, concentrated in markets with stricter androgen precursor scheduling.
Shipment value concentrates in Online Stores; Gyms expand most quickly through emerging market fitness infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for andro supplements concentrates most intensely in the United States, where sports nutrition retail infrastructure and telehealth-integrated testosterone optimization clinics sustain premium volume. Brazil and India emerge as the fastest-expanding markets as gym culture penetrates emerging economies with first-time supplement buyers.
United States
Fitness enthusiasts and men over forty drive demand through subscription platforms and clinic channels that bundle blood panel monitoring with supplement protocols. The FDA exercises primary oversight through DSHEA enforcement and Good Manufacturing Practice inspections, while the FTC polices advertising claims. California's Proposition 65 enforcement actions against unlabeled androgenic compounds have triggered national supply chain audits.
Brazil
First-time gym infrastructure creates novice supplement buyers seeking immediate performance feedback, particularly in pre-workout androgenic cofactor categories. ANVISA regulates dietary supplements with evolving registration requirements that manufacturers must navigate for market entry. São Paulo anchors distribution networks serving Southeast Brazil's concentrated fitness population.
India
Fitness infrastructure expansion generates disproportionate volume growth from recreational trainees prioritizing muscle protein synthesis acceleration. FSSAI oversees supplement safety standards while state-level licensing creates compliance patchwork for multi-state distributors. Maharashtra and Karnataka host contract manufacturing clusters supplying domestic and export markets.
Germany
REACH compliance and EFSA novel food approvals position German manufacturers for preferential access to Middle Eastern markets through regulatory mutual recognition. The country's national pharmaceutical regulator maintains strict oversight of androgen precursor formulations. Bavaria concentrates R&D-intensive brands serving clinical validation-focused consumer segments.
Japan
METI's Foods with Function Claims pathway offers faster market entry for muscle maintenance claims than pharmaceutical-grade registration. Domestic partners with PMDA relationships command premium valuation for foreign entrants seeking regulatory navigation. The Kanto region around Tokyo hosts the primary consumer base for premium convenience formats.
Andro Supplements Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue telehealth-integrated service models and liposomal delivery technology differentiation. The vendor base stratifies across three maturity tiers: legacy sports nutrition houses with manufacturing scale, clinical validation-focused specialists, and direct-to-consumer subscription platforms. Three strategic archetypes dominate: R&D-intensive efficacy validators, cost-optimized commodity suppliers, and regulatory navigation specialists. Competitive moves concentrate on subscription platform acquisitions and third-party certification capacity expansion.
Within the clinical validation tier, MuscleTech and Optimum Nutrition exemplify contrasting scale-versus-R&D positioning strategies. Hi-Tech Pharmaceuticals occupies a specialized position navigating complex prohormone regulatory boundaries. These three anchors illustrate how formulation investment intensity and distribution architecture choices separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Optimum Nutrition |
| MuscleTech |
| BSN |
| Nutrex Research |
| Cellucor |
| Universal Nutrition |
| Dymatize |
| GNC Holdings |
| Hi-Tech Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Backward integration into certified contract manufacturing anchors supply security for premium andro supplement brands while compressing margin exposure to third-party testing bottlenecks. This captive production strategy simultaneously enables lot-level traceability compliance with FDA Good Manufacturing Practice inspections and supports premium pricing through quality-grade differentiation that traveling professionals reward with repeat subscription commitments.
Pricing Analysis
Powder formats capture volume leadership through cost efficiency while capsules command margin premiums via liposomal bioavailability technology. Three-tier pricing structure across premium, standard, and economy levels separates clinical validation-focused brands with NSF certification from commodity gym-affiliated suppliers. Pricing pressure stems from third-party testing queue congestion extending to fourteen weeks, compressing launch windows for seasonal training cycles. Fitness enthusiasts in direct-to-consumer channels exhibit minimal price sensitivity, whereas first-time buyers in emerging economies prioritize unit cost over delivery format.
Supply Chain Analysis
Regional distribution centers in São Paulo, Mumbai, and Los Angeles anchor hub-and-spoke patterns serving gym-affiliated retail and telehealth-integrated clinics. Raw material sourcing concentrates in Bulgaria and India for Tribulus terrestris and fenugreek extracts, with climate disruption and export licensing delays creating input volatility. Single-source vulnerability in wild-harvested botanical supply elevates formulation cost risk for DHEA-adjuvant blends. Distribution runs through direct-to-consumer subscription platforms capturing recurring revenue from amateur bodybuilders, displacing brick-and-mortar specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The andro supplements sector is becoming a vertical-integration race as manufacturers pursue captive control over certified contract manufacturing to secure FDA compliance and compress third-party testing exposure. This upstream consolidation imperative reshapes competitive economics across formulation tiers.
For Market Incumbents: Anticipate DEA scheduling reviews of androstenedione derivatives by accelerating inventory depletion of borderline compounds and pivoting toward DHEA-based formulations with established regulatory clarity. Prioritize acquisition of NSF Certified for Sport contract manufacturing capacity to bypass fourteen-week testing queues. Lock in multi-year supply agreements with Bulgarian and Indian botanical extract suppliers to hedge climate-driven raw material volatility.
For New Entrants and Emerging Players: Amateur physique competitors seeking body recomposition represent an underserved buyer archetype with minimal incumbent saturation in thermogenic-androgenic adjuvant categories. Penetrate Brazil's first-time gym infrastructure through gym-affiliated point-of-impulse placement adjacent to training floors. Launch with hybrid training modality formulations addressing concurrent strength-endurance demands from CrossFit and HYROX participants.
For Investors and Strategic Acquirers: Exit pathways concentrate in telehealth-integrated subscription platforms bundling blood panel monitoring with supplement protocols, as testosterone optimization clinics capture thirty percent of premium volume. Long-term viability favors clinical validation specialists with EFSA novel food approval pathways for European export readiness. Monitor FDA enforcement posture shifts under DSHEA as the primary inflection signal for formulation obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Delivery Technology Adoption | Threefold serum concentration improvements justify premium capsule pricing among traveling professionals. |
| Subscription Platform Acquisition | Recurring revenue architecture bypasses retail margin compression and captures lifetime value from fitness enthusiasts. |
| Third-Party Certification Capacity Expansion | NSF Certified for Sport accreditation reduces launch window risk for drug-tested athlete segments. |
| Telehealth Clinic Partnership | Bundled blood panel monitoring with supplement protocols displaces brick-and-mortar specialty retail. |
| EFSA Novel Food Approval Pathway | REACH compliance enables preferential Middle Eastern market access through regulatory mutual recognition. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with formulation scientists, contract manufacturing executives, regulatory affairs specialists, and telehealth clinic operators provided operational validation. FDA warning letters, DEA scheduling notices, and state attorney general settlement documents supplemented customs records tracking DHEA and botanical extract import volumes. Bottom-up demand modeling across product type, delivery format, and end-user segments triangulated with top-down market sizing from sports nutrition retail audit data.
Granularity-level modeling distinguished testosterone boosters, pre-workout formulations, male enhancement, and fat burners by replacement cycle dynamics and margin structure. Form factors were modeled separately for cost efficiency versus bioavailability premium positioning. End-user archetypes captured fitness enthusiasts, older adults, bodybuilders, and drug-tested athletes with divergent clinical partnership requirements. CAGRs derived from segment-level growth trajectories weighted by channel-specific regulatory exposure and telehealth integration penetration. Raw material supply constraints from Bulgarian and Indian agricultural zones informed input cost assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to DEA prohormone scheduling decisions, FDA DSHEA enforcement intensity shifts, and climate disruption patterns in wild-harvested botanical supply zones. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Choline Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Nutritional Supplements Market