
 Global Digestive Enzyme Supplements Market | 2026-2036
Global Digestive Enzyme Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digestive Enzyme Supplements Market Foresight
The gap between wellness-center procurement and sports-nutritionist recommendations is collapsing as athletic consumers prioritize gut health for performance recovery. Enzymedica leverages its specialized protease formulations to dominate the high-performance athlete segment. NOW Foods sustains broad retail distribution across North American pharmacies and natural-product channels. Amano Enzyme Inc. anchors industrial-scale fermentation capabilities that supply private-label enzyme blends to multiple finished-goods brands.
Digestive enzyme supplements comprise exogenous proteins—typically protease, lipase, amylase, and cellulase—manufactured through microbial fermentation or extracted from plant and animal tissues, then stabilized in capsule, tablet, or powder matrices to catalyze macronutrient breakdown in the gastrointestinal tract. The protease category leads current revenue contribution due to its central role in protein digestion and sports-nutrition applications, while lipase and lactase formulations are accelerating fastest as fat-adapted diets and dairy-intolerance awareness expand the addressable population. Capsule and tablet forms occupy the dominant share of pharmacy and wellness-center distribution, though powder formats are gaining traction among sports nutritionists seeking dose flexibility for personalized protocols.
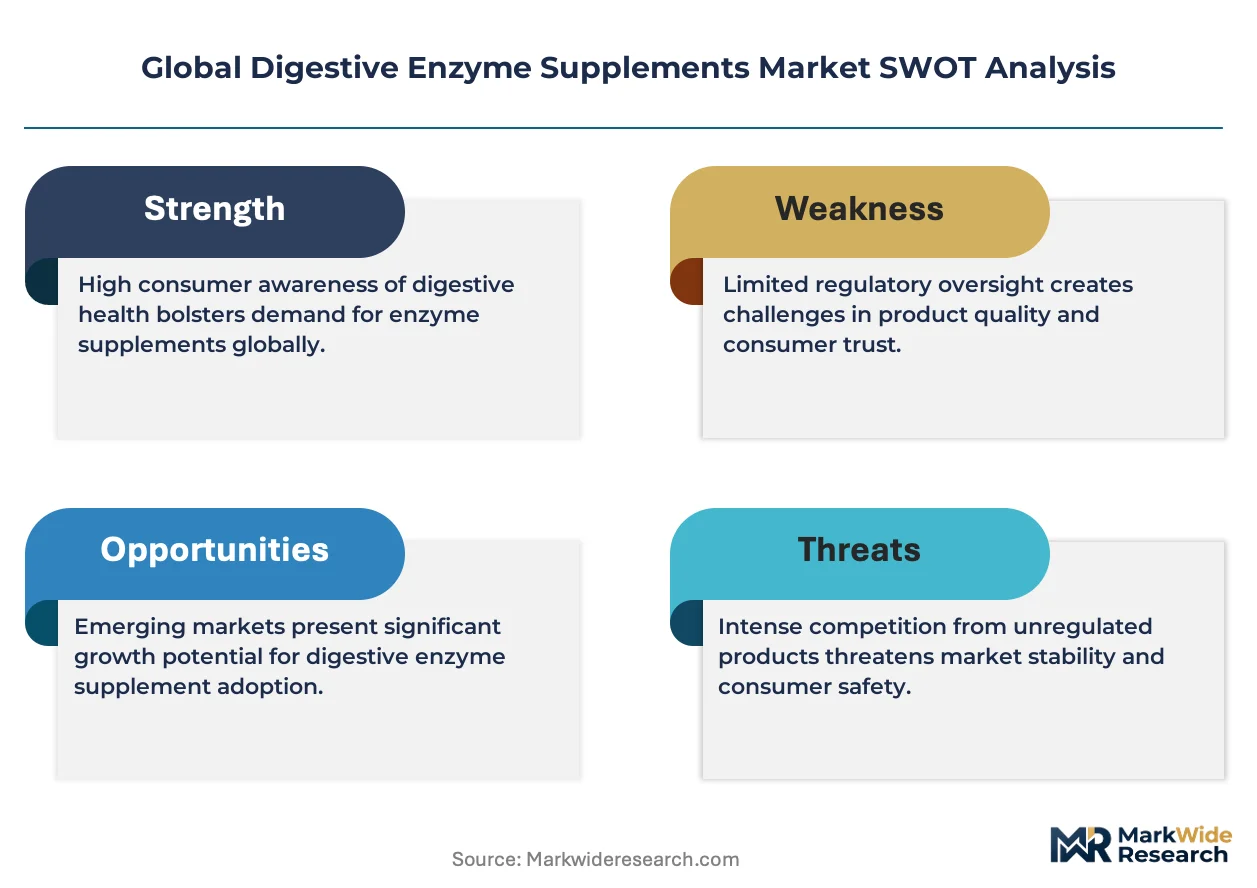
The FDA enforces cGMP standards for dietary supplement manufacturing, while the EMA and national European regulators monitor enzyme-based products crossing into pharmaceutical classifications under the MDR framework. Health Canada and Australia's TGA impose additional stability-testing and label-claim verification requirements that shape export strategies for North American manufacturers. Stakeholders must monitor whether FDA enforcement actions on enzyme-specific health claims redirect marketing investment toward structure-function language or clinical-trial substantiation.
Market Dynamics
The FDA's dietary supplement cGMP enforcement is compressing manufacturing economics while simultaneously elevating quality thresholds that filter marginal producers from pharmacy and wellness-center supply chains.
Growth Catalysts
- Sports nutritionist channel expansion:Athletic consumers now prioritize gut health for performance recovery, collapsing the historical gap between wellness-center procurement and sports-nutritionist recommendations.
- Fat-adapted diet proliferation:Ketogenic and low-carbohydrate eating patterns across North America and Western Europe accelerate lipase formulation demand for macronutrient assimilation support.
- Lactase intolerance awareness campaigns:Dairy-intolerance education initiatives in East Asian markets broaden the addressable population for enzyme-based digestive aids.
Market Restraints
- Fermentation input cost volatility:Microbial culture media and carbohydrate feedstock prices fluctuate with agricultural commodity cycles, squeezing contract manufacturing margins.
- API supply concentration:Industrial-scale enzyme production concentrates in Japanese and Danish fermentation facilities, creating geographic vulnerability for North American finished-goods brands.
- Stability-testing burden:Health Canada and Australia's TGA impose extended shelf-life verification protocols that delay product launch timelines and inflate regulatory compliance spend.
Strategic Opportunities
- Direct-to-consumer channel maturation:Subscription-based enzyme delivery models in the United States bypass traditional pharmacy intermediaries, capturing margin and consumer data simultaneously.
- Functional medicine clinic integration:Personalized protocols from integrative health practitioners in Germany and Switzerland create premium positioning for dose-flexible powder formats.
- EU MDR framework navigation:Enzyme products approaching pharmaceutical classification thresholds in Europe reward early clinical-trial investment with defensible market positioning.
Industry Challenges
- Formulation science talent scarcity:Protein stabilization and enteric-coating expertise concentrates among legacy fermentation scientists approaching retirement, constraining R&D pipeline velocity.
- Label-claim substantiation complexity:Structure-function language permissible under FDA guidelines requires careful legal review to avoid enforcement actions that redirect marketing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digestive Enzyme Supplements Market |
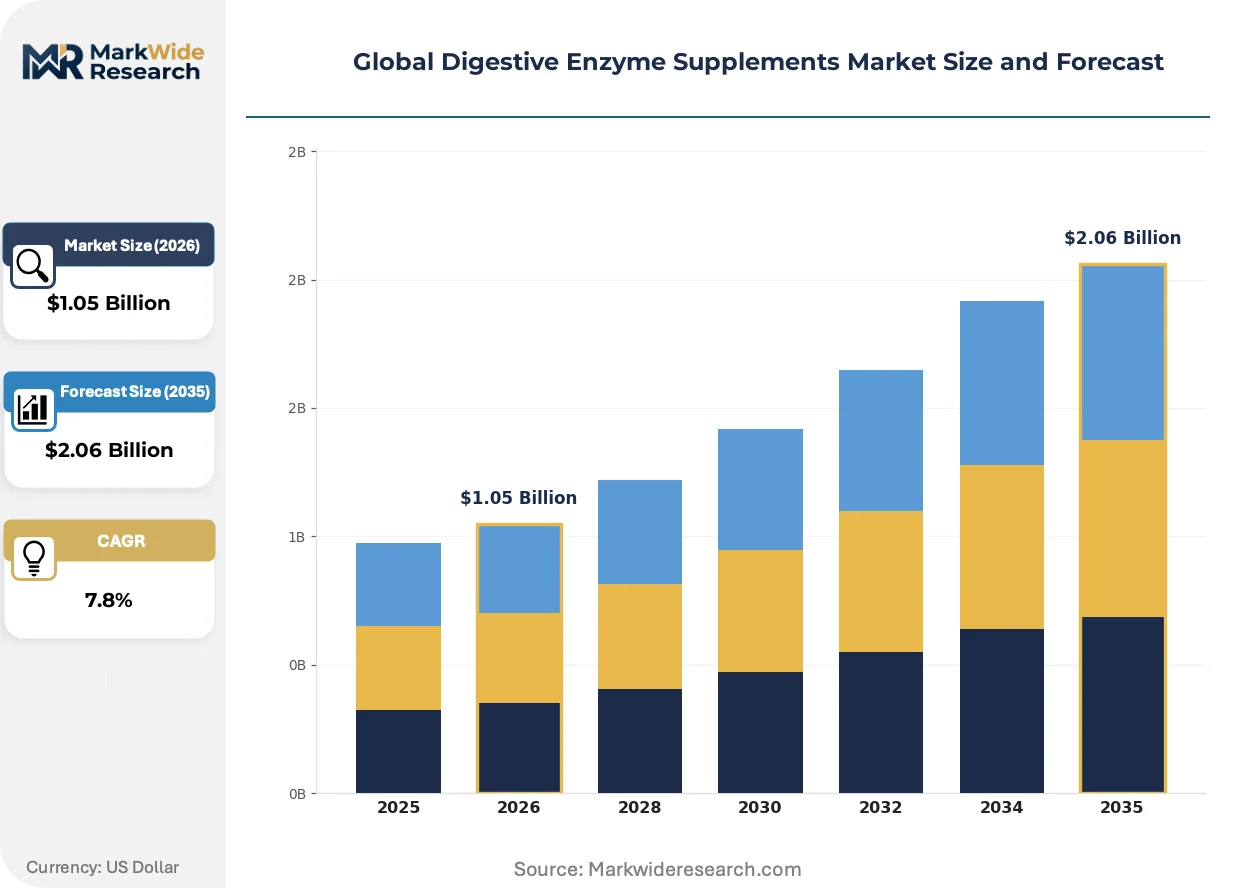
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protease, Lipase, Amylase, Cellulase, Lactase, Bromelain Application: Gastrointestinal Disorders, Pancreatic Insufficiency, Inflammatory Bowel Disease, Celiac Disease, Food Intolerance, Nutritional Support End User: Pharmacies, Wellness Centers, Sports Nutritionists, Geriatric Care, Pediatric Clinics, Alternative Medicine Providers Form: Capsules, Tablets, Powders, Liquid Extracts, Enzyme Blends, Chewables |
| Companies Covered | Enzymedica, Amano Enzyme Inc., Advanced Enzyme Technologies, Metagenics, Klaire Laboratories, National Enzyme Company, Enzymes, Inc., Nestlé Health Science, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digestive Enzyme Supplements Market Shifts & Advancements
Microencapsulation technologies and bioavailability enhancement methods are restructuring competitive positioning, while regulatory convergence between dietary supplement and pharmaceutical frameworks forces capital reallocation toward clinical substantiation.
Targeted-release microencapsulation using pH-sensitive polymers is supplanting standard gelatin capsules in high-performance athlete segments. Sports nutritionists prescribe these formulations for precise proximal-intestine enzyme delivery. The technology compresses generic capsule margins while enabling 40-60% price premiums for substantiated bioavailability claims.
EMA's MDR framework is tightening classification boundaries for enzyme products with therapeutic indications. Manufacturers now face binary decisions between dietary supplement registration and full pharmaceutical authorization. German and Swiss brands invest most heavily in clinical trial infrastructure to navigate this regulatory bifurcation.
Athletic consumers now self-direct enzyme procurement through specialized e-commerce platforms rather than relying on retail pharmacy staff. This channel disintermediation concentrates in the United States and Australia where direct-to-consumer marketing regulations permit broader health communication. Traditional wellness centers respond by developing proprietary branded formulations to retain patient loyalty.
Global Digestive Enzyme Supplements Market Segmentation
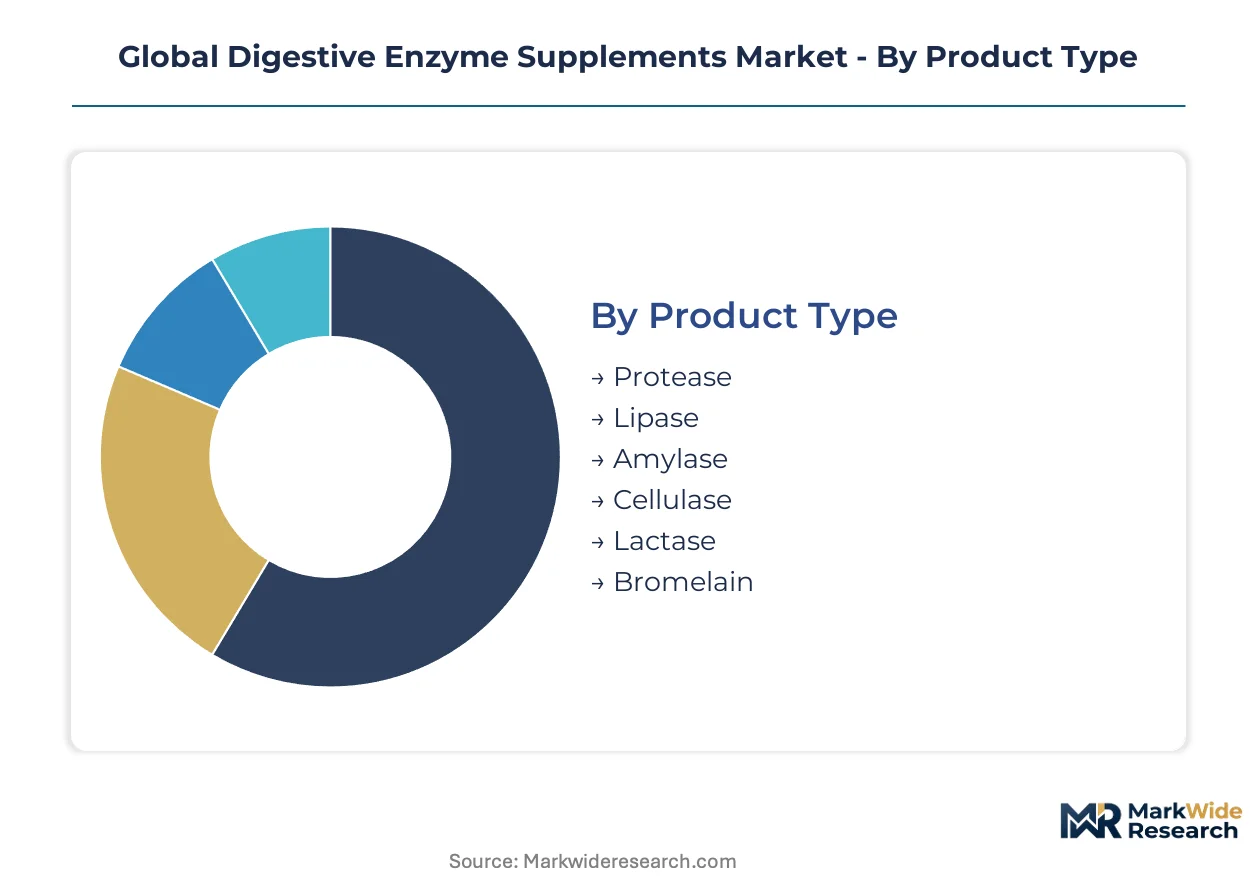
Enzyme formulation heterogeneity creates distinct competitive arenas where substitution risk varies sharply by therapeutic positioning and delivery mechanism. Manufacturers must map segment-specific vulnerability to synthetic alternatives and prescription pancreatic enzymes when allocating R&D investment.
Product Type:
Protease formulations face intensifying substitution pressure from prescription pancreatic enzyme replacement therapies in diagnosed exocrine pancreatic insufficiency, while plant-derived alternatives compete on cost in wellness applications.
- Protease:These protein-cleaving enzymes—primarily trypsin, chymotrypsin, and papain variants—dominate sports nutrition protocols for post-workout recovery. Demand concentrates among United States athletic consumers seeking performance optimization, though FDA scrutiny of structure-function claims constrains marketing latitude.
- Lipase:Fat-digesting enzymes accelerate assimilation in ketogenic and low-carbohydrate dietary patterns. Adoption is climbing fastest in North American direct-to-consumer channels as fat-adapted eating proliferates.
- Amylase:Starch-breaking enzymes support carbohydrate digestion in standard dietary supplement portfolios.
- Cellulase:Fiber-digesting enzymes target plant-based diet consumers experiencing bloating from high-roughage intake.
- Lactase:Dairy-specific enzymes expand in East Asian markets where lactose intolerance prevalence drives category education investments.
- Bromelain:Pineapple-derived proteolytic complex serves anti-inflammatory positioning in alternative medicine channels.
Protease anchors the volume base while lipase gains share at the steepest rate.
Application:
Cost tier stratification separates pharmaceutical-grade enzyme therapies from commodity digestive aids, with reimbursement status determining margin architecture across clinical versus wellness positioning.
- Gastrointestinal Disorders:Broad-spectrum enzyme protocols address functional dyspepsia and irritable bowel syndrome presentations. Demand concentrates in German and Swiss functional medicine clinics where personalized dosing commands premium positioning.
- Pancreatic Insufficiency:Prescription pancreatic enzyme replacement therapy dominates this segment, creating competitive moats for pharmaceutical manufacturers with clinical trial substantiation.
- Inflammatory Bowel Disease:Adjunctive enzyme therapy supports nutrient absorption in Crohn's disease and ulcerative colitis management.
- Celiac Disease:Gluten-specific enzyme formulations target accidental exposure mitigation in strict gluten-free protocols.
- Food Intolerance:Condition-specific enzymes address FODMAP sensitivity and histamine intolerance in self-directed consumer segments.
- Nutritional Support:General wellness positioning captures aging populations seeking digestive efficiency maintenance.
Gastrointestinal disorder applications generate the highest absolute revenue while food intolerance positioning expands most quickly.
End User:
Customer type fragmentation reflects channel bifurcation between clinical recommendation authority and self-directed procurement behavior.
- Pharmacies:Traditional retail pharmacy channels stock standard-strength capsule and tablet formats for walk-in digestive complaints. United States pharmacy chains now allocate shelf space based on direct-to-consumer brand recognition rather than clinical endorsement alone.
- Sports Nutritionists:Performance-focused practitioners prescribe targeted-release microencapsulated formulations for athlete gut health optimization. This channel is expanding most rapidly as athletic consumers prioritize recovery protocols.
- Wellness Centers:Integrative health facilities bundle enzyme protocols with broader functional medicine assessments.
- Geriatric Care:Aging-related digestive enzyme decline drives institutional and home-care procurement.
- Pediatric Clinics:Specialized formulations address developmental enzyme insufficiency and feeding intolerance.
- Alternative Medicine Providers:Naturopathic and Ayurvedic practitioners prescribe plant-derived enzyme complexes.
Pharmacies retain the largest transaction volume base while sports nutritionist recommendations are climbing the fastest.
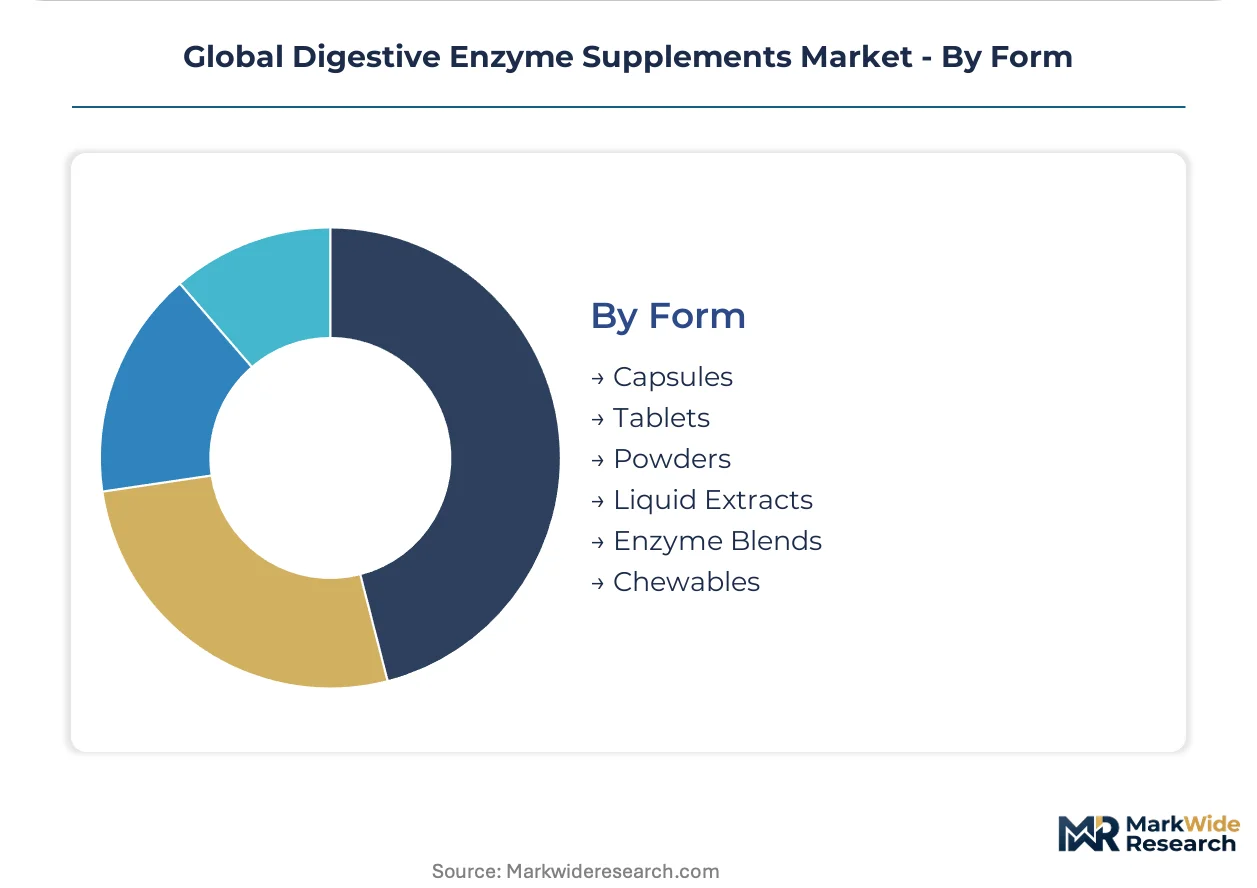
Form:
Supply concentration in capsule manufacturing equipment creates margin pressure for format innovators seeking powder and liquid differentiation.
- Capsules:Gelatin and vegetarian capsule formats dominate pharmacy and wellness center distribution due to dosing precision and stability. Australian TGA stability-testing requirements favor this format's established shelf-life documentation.
- Powders:Dose-flexible formats enable personalized protocols from sports nutritionists and functional medicine practitioners. Adoption is accelerating fastest in United States subscription direct-to-consumer models.
- Tablets:Compressed formats compete on manufacturing economy for mass-market positioning.
- Liquid Extracts:Rapid absorption claims support pediatric and geriatric compliance applications.
- Enzyme Blends:Multi-enzyme complexes simplify protocol complexity for general wellness consumers.
- Chewables:Palatability-focused formats target pediatric and travel-use segments.
Capsules anchor the volume base while powders gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles handles containerized enzyme raw materials from Asian fermentation facilities, underwriting North American finished-goods manufacturing capacity. European distribution relies on Rotterdam's cold-chain infrastructure for temperature-sensitive enzyme stability during transshipment.
United States
Sports nutritionist channel expansion and direct-to-consumer subscription models concentrate demand in California and Texas metropolitan corridors. FDA cGMP enforcement actions in 2024 elevated quality compliance costs for contract manufacturers. The San Diego biotech cluster houses multiple enzyme formulation specialists serving athletic performance segments.
Germany
Functional medicine clinic adoption and personalized dosing protocols drive premium powder format procurement in Bavaria and Baden-Württemberg. EMA's MDR framework tightens classification boundaries for therapeutic enzyme indications. The Munich-Planegg corridor hosts fermentation technology providers supplying private-label enzyme blends.
Japan
Industrial-scale fermentation capacity and proprietary culture strain development anchor Amano Enzyme's supply position for global finished-goods brands. METI's biotechnology promotion programs subsidize next-generation enzyme manufacturing infrastructure. The Nagoya industrial belt concentrates contract fermentation facilities serving North American and European brand owners.
Australia
TGA stability-testing requirements and extended shelf-life verification protocols shape export strategies for enzyme supplement manufacturers targeting Asia-Pacific markets. Direct-to-consumer channel maturation accelerates in Sydney and Melbourne metropolitan areas. The Melbourne biomedical precinct houses formulation science consultancies specializing in enteric-coating technologies.
India
Contract manufacturing cost advantages and expanding domestic wellness consumption attract multinational brand sourcing decisions to Maharashtra and Gujarat pharmaceutical zones. FSSAI label-claim verification requirements align gradually with Codex Alimentarius enzyme standards. The Hyderabad fermentation corridor develops specialized protease production capacity for sports nutrition export markets.
Global Digestive Enzyme Supplements Market Competitive Landscape
Listed leaders compete with private specialists across fermentation scale and clinical substantiation capabilities. The vendor base stratifies between industrial-scale enzyme producers supplying private-label markets and finished-goods brands commanding retail pharmacy shelf space. Three archetypes dominate: fermentation technology licensors, direct-to-consumer wellness platforms, and clinical-channel specialists with practitioner endorsement networks. Competitive moves concentrate on backward integration into culture strain development and geographic expansion through regulatory pathway optimization.
Within the industrial supply tier, Amano Enzyme Inc. and Advanced Enzyme Technologies exemplify fermentation-scale positioning that underwrites finished-goods brand formulation flexibility. Among clinical-channel specialists, Metagenics and Klaire Laboratories occupy positions defined by practitioner protocol integration and personalized medicine alignment. NOW Foods represents the mass-market archetype leveraging broad retail distribution across North American pharmacy and natural-product channels. These three groupings—industrial suppliers, clinical specialists, and mass-market distributors—capture distinct margin architectures within the value chain.
| Leading Market Players |
|---|
| Enzymedica |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies |
| Metagenics |
| Klaire Laboratories |
| National Enzyme Company |
| Enzymes, Inc. |
| Nestlé Health Science |
| NOW Foods |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Japanese fermentation facilities and North American finished-goods brands lock in protease supply access while anchoring price visibility against agricultural commodity volatility. These arrangements concentrate procurement power among legacy manufacturers with cGMP-certified capacity, compressing margin flexibility for spot-market buyers.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade enzyme specifications from commodity wellness formulations, with FDA cGMP certification and TGA stability documentation commanding 40-60% premiums over uncertified alternatives. Price differentiation hinges on fermentation scale and enteric-coating technology ownership. Cost compression in standard capsule formats intensifies as private-label competition proliferates. Sports nutritionist-directed buyers exhibit lowest price sensitivity, prioritizing bioavailability substantiation over per-unit cost.
Supply Chain Analysis
Japan and Denmark anchor industrial-scale microbial fermentation for protease and lipase concentrates, while India and China supply plant-derived papain and bromelain extracts. Raw material dependencies center on carbohydrate feedstocks, specialized culture media, and pH-sensitive polymer coatings for microencapsulation. Single-source vulnerability concentrates in Nagoya-area fermentation corridors. Distribution runs through Rotterdam's cold-chain infrastructure for European transshipment and direct container routes to the Port of Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where subscription-based direct-to-consumer models are displacing pharmacy-centric distribution, rewarding brands that capture consumer data and dosing-protocol loyalty.
For Market Incumbents: Shield market position by securing captive fermentation capacity through backward integration into Japanese or Danish culture-strain development. Prioritize clinical-trial investment for EMA MDR navigation before therapeutic classification thresholds harden. Defend against private-label erosion by embedding practitioner protocol integration in German and Swiss functional medicine clinics. For New Entrants and Emerging Players: FDA cGMP fast-track certification for contract manufacturers unlocks pharmacy shelf access without legacy brand recognition. Target powder-format sports nutritionist channels in United States metropolitan corridors where dose-flexibility protocols command premium positioning. Pursue white-label supply relationships with direct-to-consumer wellness platforms seeking proprietary branded formulations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based enzyme delivery models with personalized protocol engines. Five-to-ten year viability favors acquisition targets with clinical-trial infrastructure and EU regulatory pathway expertise. Watch for FDA enforcement actions on structure-function claims as inflection signals redirecting marketing investment toward pharmaceutical-grade substantiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive protease supply from Amano-class facilities insulates against API concentration risk. |
| Clinical Trial Infrastructure Investment | EMA MDR readiness in German and Swiss markets creates defensible therapeutic positioning. |
| Direct-to-Consumer Subscription Launch | Bypasses pharmacy intermediaries in United States corridors while capturing dosing-protocol data. |
| Microencapsulation Technology Licensing | pH-sensitive polymer delivery commands 40-60% premiums in athlete gut-health segments. |
| Practitioner Protocol Integration | Functional medicine clinic embedding in Bavaria and Baden-Württemberg secures premium powder demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation technology directors, sports nutritionist practitioners, FDA regulatory consultants, and pharmacy category buyers; and secondary validation through FDA cGMP inspection records, EMA MDR classification databases, TGA stability-testing protocols, and customs trade data for enzyme raw material flows. Bottom-up triangulation against top-down market sizing anchored volume and value estimates.
The forecasting boundary spans the full projection horizon with explicit segmentation across enzyme type, application indication, end-user channel, and delivery format. CAGRs derive from regression analysis of historical fermentation capacity expansion, regulatory approval velocity, and channel-shift elasticities. Modeled inputs include sports nutritionist adoption curves, direct-to-consumer subscription conversion rates, and EMA MDR reclassification probabilities.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA cGMP enforcement and stable Japanese-Danish fermentation supply; material deviation in agricultural commodity cycles or regulatory classification thresholds would warrant model refresh. Recalibration cycles align with material shifts in enforcement patterns and API supply geography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
Sports Food Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Nutritional Oil Powder Market